
 Metal Heat Treatment Market | 2026-2036
Metal Heat Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Heat Treatment Market Outlook
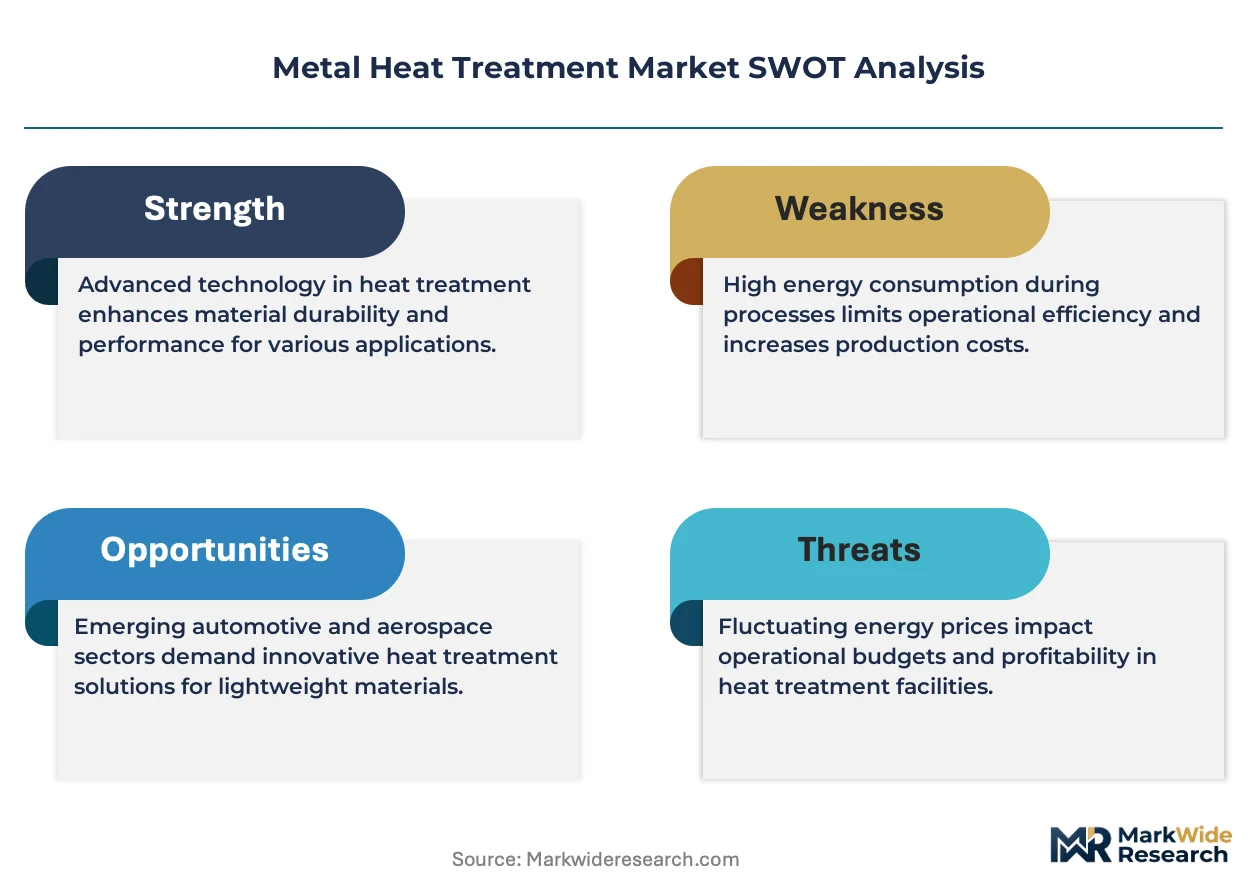
Digital twin integration with furnace control systems is rewriting how heat treatment workflows optimize energy use and metallurgical consistency. Bodycote plc leverages its distributed service center network to sustain proximity advantages across North American automotive supply chains. ALD Vacuum Technologies anchors premium positioning through specialized vacuum carburizing systems for aerospace turbine manufacturers. Specialty Steel Treating differentiates via precision batch processing for medical instrument alloys where tolerances tighten continuously.
Metal heat treatment encompasses controlled thermal cycles applied to ferrous and non-ferrous alloys to alter microstructure, hardness, ductility, or residual stress profiles, typically operating between 300°C and 1,200°C depending on material and desired phase transformation. The process serves critical functions across durability-critical industries where mechanical failure carries catastrophic cost or safety consequences. Hardening and tempering sequences command substantial value share in steel processing due to their ubiquity in drivetrain and tooling applications, while vacuum-based technologies grow fastest as OEMs specify cleaner surface finishes and tighter carbon control. Aluminum solution treatment lines are expanding capacity near automotive lightweighting clusters where body-in-white specifications now specify heat-treated 6xxx series alloys.
EPA regulations on industrial furnace emissions and OSHA thermal process safety standards shape capital allocation toward closed-loop atmosphere control and automated material handling systems in US-based operations. China's GB standards for heat treatment energy intensity and the EU's F-Gas Regulation on fluorinated greenhouse gases used in controlled atmosphere processes are redirecting technology procurement across their respective jurisdictions. Stakeholders must weigh retrofit timelines against regulatory compliance deadlines while monitoring induction technology cost curves that could accelerate displacement of conventional fuel-fired furnace infrastructure.
Market Dynamics
EPA emissions standards on industrial furnace operations are redirecting capital toward electric induction systems, compressing payback periods for conventional gas-fired infrastructure and reshaping supplier procurement criteria across durability-critical manufacturing sectors.
Growth Catalysts
- Lightweighting mandates in automotive stamping:Heat-treated 6xxx series aluminum alloys now dominate body-in-white specifications, pulling capacity expansion near Shanghai and Shenyang industrial clusters.
- F-Gas Regulation in the European Union:Controlled atmosphere processes face fluorinated greenhouse gas phase-downs, accelerating vacuum technology substitution for conventional carburizing lines.
- Digital twin integration:Furnace control systems now deploy real-time metallurgical simulation, cutting energy intensity and scrap rates in precision batch operations.
Market Restraints
- Natural gas price volatility:Fuel-fired furnace operators face margin compression where energy constitutes 25-35% of processing costs, advantaging electric alternatives.
- Specialized equipment supply concentration:High-vacuum heat treatment systems rely on concentrated German and Japanese component suppliers, extending lead times for North American buyers.
- Technical limitation in thick-section titanium:Vacuum furnaces struggle with thermal uniformity beyond 300mm cross-sections, constraining adoption for large aerospace structural forgings.
Strategic Opportunities
- Medical instrument alloy processing:Precision tolerances for surgical stainless and cobalt-chrome devices create premium service tiers with limited qualified competition.
- India's PLI scheme for specialty steel:Domestic heat treatment capacity lags behind rolled product investments, opening contract processing gaps for automotive and defense suppliers.
- Induction-convection hybrid systems:Convergence of electromagnetic heating with controlled atmosphere control enables through-hardening of complex geometries previously requiring batch furnaces.
Industry Challenges
- Metallurgical engineer scarcity:Retirement-driven attrition in phase transformation expertise constrains quality system implementation and customer technical support.
- Nadcap certification timelines:Aerospace heat treatment approvals require 18-24 month audit cycles, delaying market entry for new service centers.
- Legacy SCADA integration:Digital twin deployment confronts incompatible data architectures in installed furnace fleets, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Heat Treatment Market |
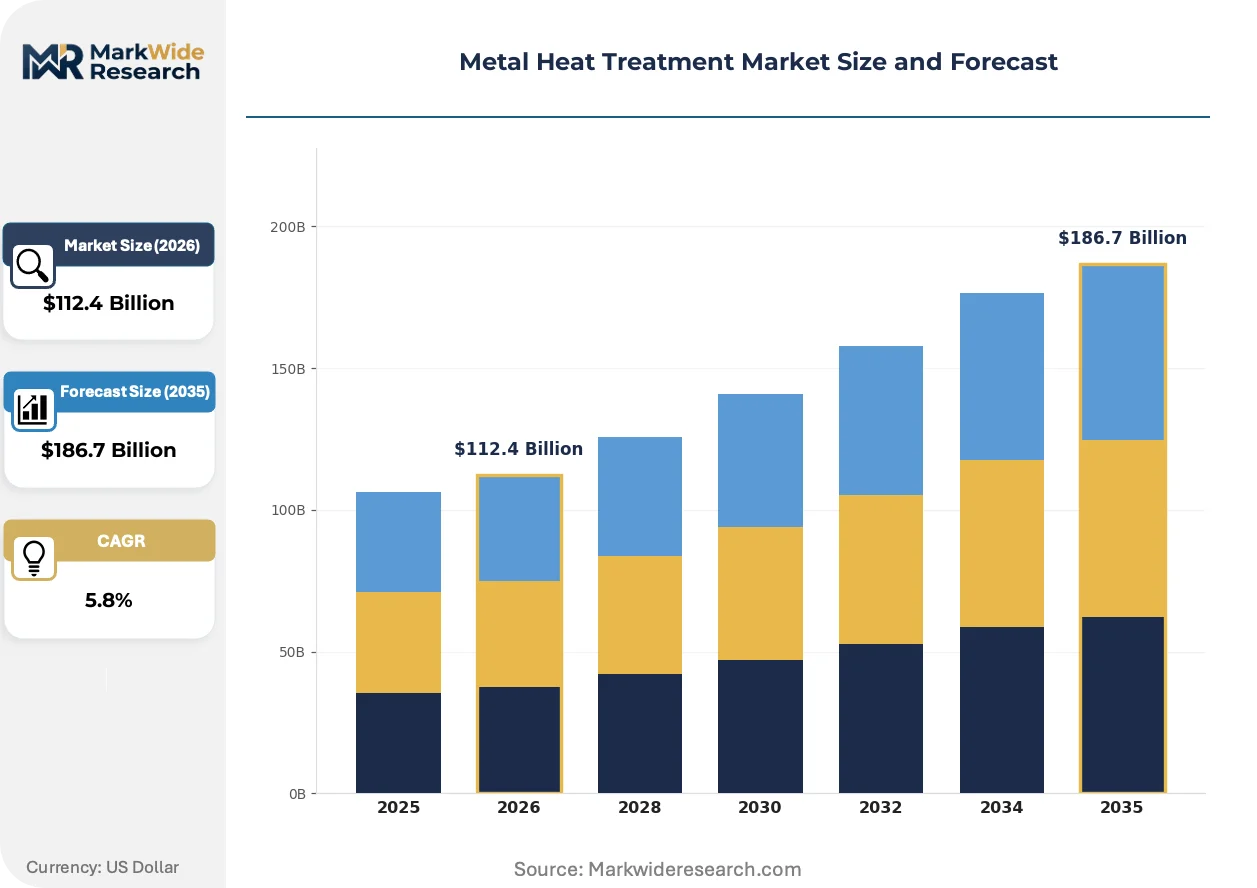
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Annealing, Quenching, Tempering, Hardening Material Type: Steel, Aluminum, Titanium, copper End User: Aerospace, Automotive, Machinery, Construction Technology: Induction Heating, Flame Hardening, Salt Bath, Furnace |
| Companies Covered | Advanced Heat Treat Corp, MetalTek International, Bodycote plc, Stack Metallurgical, Aichelin Group, ALD Vacuum Technologies, Braddock Metallurgical, Specialty Steel Treating, Bluewater Thermal Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Heat Treatment Market Strategic Shifts
Process virtualization and closed-loop atmosphere control are compressing the gap between empirical heat treatment practice and predictive metallurgy, enabling quality guarantees that were previously impossible outside captive operations.
Digital twin software for furnace thermal mapping is virtualizing quality assurance workflows across distributed heat treatment networks. Aerospace tier suppliers now mandate simulation-validated process recipes before production authorization. This virtualization is compressing the competitive advantage of vertically integrated manufacturers over independent service providers.
China's GB standards for heat treatment energy intensity are forcing facility retrofits or closures in provinces with the strictest carbon intensity targets. The regulations impose measurable efficiency benchmarks per ton processed, with non-compliant operations facing production limits. Domestic automotive stampers are responding by consolidating volumes with certified regional champions capable of documented compliance.
Specification-driven vendor consolidation is concentrating procurement authority among OEM quality engineering teams, displacing traditional purchasing-led supplier selection. Tier-one drivetrain manufacturers now pre-approve heat treatment partners at the design phase rather than delegating to component fabricators. This pattern is most pronounced in German and US automotive supply chains where liability for field failures has sharpened traceability requirements.
Metal Heat Treatment Market Segmentation
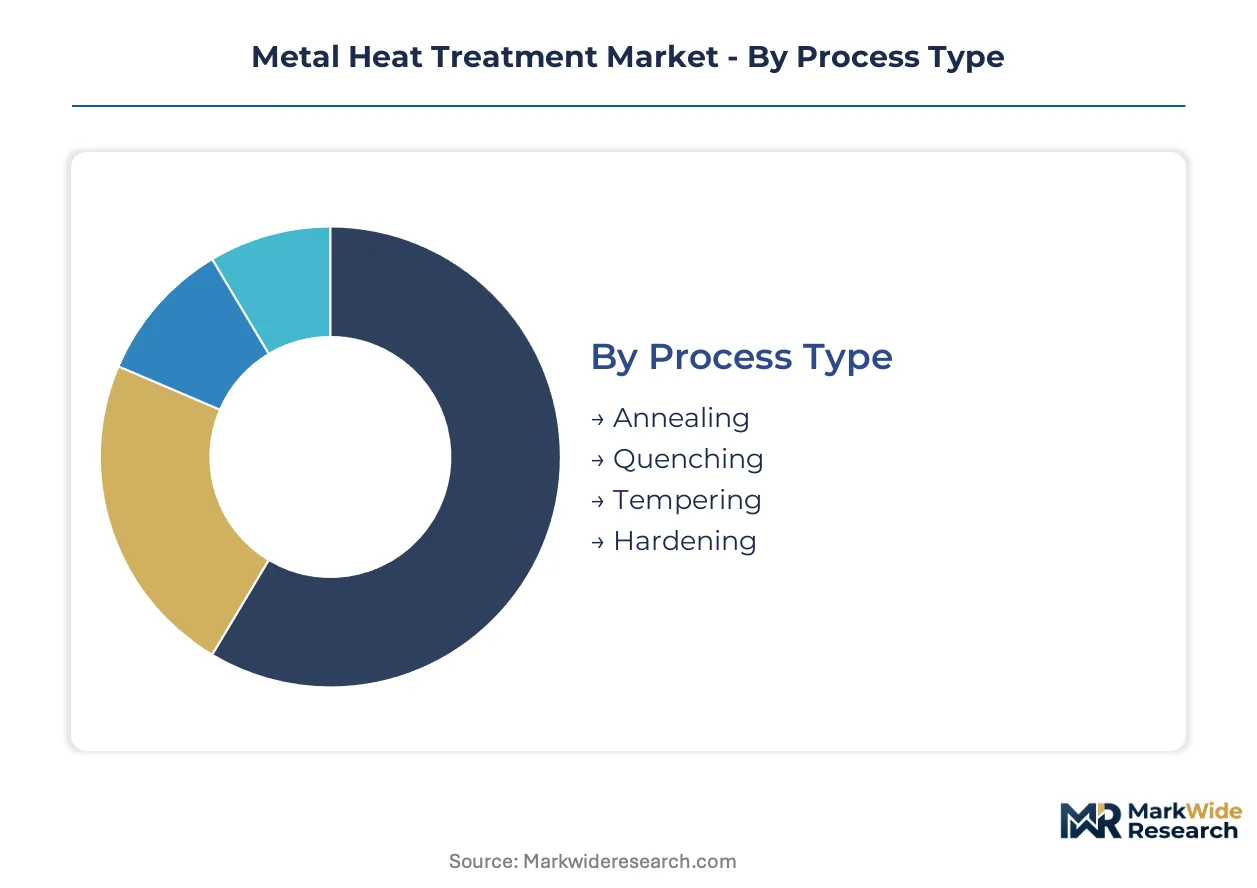
Metal heat treatment segmentation reveals distinct technology maturity curves and cost-performance tradeoffs that govern supplier selection across durability-critical applications. Process economics and metallurgical precision requirements diverge sharply between high-volume automotive stamping and low-volume aerospace forging.
Process Type:
Mature thermal sequences dominate volume processing while emerging precision methods capture specification-driven premiums.
- Hardening:Martensitic phase transformation through rapid cooling from austenitizing temperatures produces maximum hardness in ferrous alloys. Automotive drivetrain manufacturers in Germany and the US specify through-hardened gears and shafts under NHTSA durability testing protocols.
- Tempering:Sub-critical reheating of hardened components reduces brittleness while retaining sufficient strength for tooling and structural applications. China's automotive stamping clusters around Shanghai demand precisely tempered 6xxx series aluminum for body-in-white assemblies.
- Quenching:Controlled rapid cooling media selection (oil, polymer, gas) determines final hardness distribution and residual stress profiles.
- Annealing:Full, partial, and stress-relief variants soften work-hardened alloys for subsequent forming operations.
Hardening retains volume leadership; tempering holds the steepest expansion curve.
Material Type:
Cost tiers separate commodity ferrous processing from premium non-ferrous capabilities requiring specialized atmosphere control.
- Steel:Carbon, alloy, and tool steel grades constitute the processing backbone across hardening, tempering, and annealing workflows. EPA emissions standards on fuel-fired furnaces are redirecting US steel heat treatment capital toward electric induction systems.
- Aluminum:Solution treatment and artificial aging of 2xxx, 6xxx, and 7xxx series alloys enable automotive lightweighting mandates. Shenyang industrial cluster capacity expansions target heat-treated aluminum body panels for domestic OEM platforms.
- Titanium:Vacuum heat treatment prevents alpha-case formation and maintains fatigue-critical properties for aerospace rotating components.
- Copper:Annealing and stress relief processing serve electrical conductivity and forming applications with lower thermal precision requirements.
Steel retains volume leadership; aluminum holds the steepest expansion curve.
End User:
Application-specific certification requirements create divergent margin structures across customer segments.
- Automotive:Powertrain, chassis, and body-in-white specifications drive the largest absolute processing volumes with tightening traceability mandates. Tier-one suppliers now pre-approve heat treatment partners at the design phase rather than delegating to component fabricators.
- Aerospace:Nadcap certification and OEM-specific process specifications impose 18-24 month qualification timelines for rotating and structural component suppliers. Vacuum heat-treated titanium components for next-generation engine platforms anchor procurement expansion among US and German manufacturers.
- Machinery:Tooling, bearings, and industrial equipment demand hardening and tempering with moderate precision requirements.
- Construction:Structural steel heat treatment focuses on weldability and toughness for seismic and heavy-load applications.
Automotive retains volume leadership; aerospace holds the steepest expansion curve.
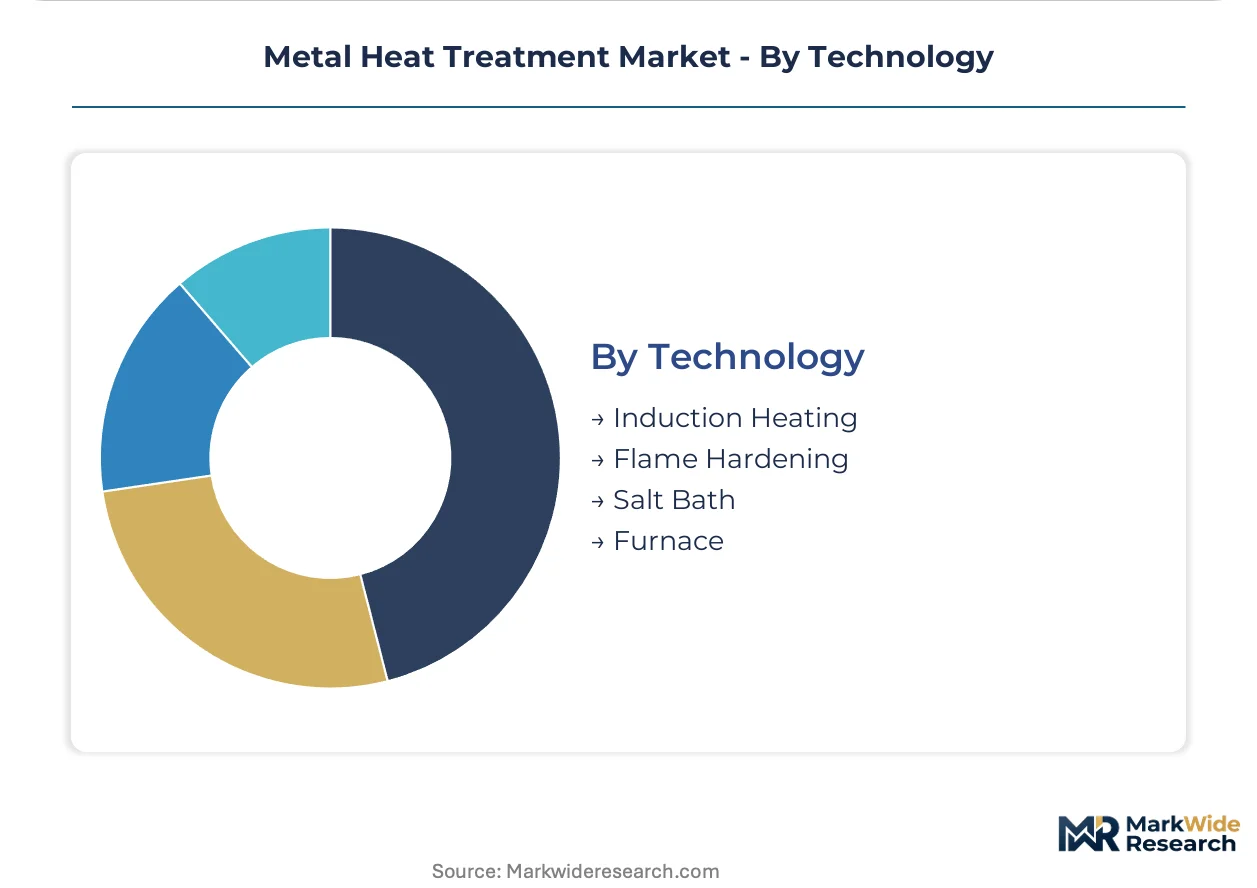
Technology:
Supply concentration in high-vacuum component sourcing shapes procurement lead times and geographic technology diffusion.
- Induction Heating:Electromagnetic energy transfer enables rapid, localized heating with precise depth control and minimal thermal distortion. Natural gas price volatility is compressing payback periods for electric induction systems against conventional fuel-fired furnaces.
- Furnace:Batch and continuous atmosphere-controlled systems remain ubiquitous for large-volume steel processing despite emissions compliance costs. China's GB standards for heat treatment energy intensity are forcing retrofits or closures in provinces with strict carbon intensity targets.
- Flame Hardening:Oxy-fuel surface heating suits large components where through-hardening is impractical or uneconomical.
- Salt Bath:Liquid medium heat transfer delivers uniform, rapid heating for complex geometries though environmental disposal constraints limit new installations.
Furnace retains volume leadership; induction heating holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports vacuum heat-treated titanium components to US aerospace manufacturers, establishing a transatlantic trade corridor in precision metallurgy. This bilateral flow anchors European positioning in high-value thermal processing segments. Demand patterns diverge sharply across major economies based on automotive, aerospace, and energy sector requirements.
United States
EPA emissions standards on industrial furnace operations are redirecting capital toward electric induction systems across Michigan and Ohio automotive corridors. NHTSA durability testing protocols mandate through-hardened drivetrain components, tightening procurement specifications for domestic stampers. Houston-Gulf Coast energy clusters drive demand for corrosion-resistant alloy processing in oilfield equipment.
China
GB standards for heat treatment energy intensity are forcing facility retrofits or closures in provinces with strict carbon intensity targets. Shanghai and Shenyang industrial clusters concentrate domestic automotive stamping capacity expansion for heat-treated 6xxx series aluminum body panels. MIIT industrial policy prioritizes vacuum technology substitution in controlled atmosphere processes.
Germany
EU F-Gas Regulation phase-downs on fluorinated greenhouse gases accelerate vacuum technology substitution for conventional carburizing lines. Baden-Württemberg and Bavaria host concentrated aerospace tier supplier networks demanding Nadcap-certified vacuum heat treatment. KBA automotive safety standards reinforce traceability mandates across powertrain component supply chains.
India
PLI scheme incentives for specialty steel production outpace domestic heat treatment capacity investments, opening contract processing gaps for automotive and defense suppliers. Maharashtra and Gujarat industrial corridors attract heat treatment service center expansions to support rolled product downstream processing. BIS quality certification requirements are tightening for heat-treated structural components in infrastructure projects.
Japan
METI energy efficiency targets compress payback periods for electric induction systems against conventional fuel-fired furnace infrastructure. Chubu and Kansai manufacturing belts concentrate precision tooling and bearing heat treatment demand. JIS standards for automotive component metallurgy reinforce specification-driven vendor consolidation among tier-one drivetrain manufacturers.
Metal Heat Treatment Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between volume-driven service networks and precision-batch operators. The vendor base stratifies into three tiers: integrated multi-process providers, vacuum technology specialists, and regional batch processors serving automotive supply chains. Two strategic archetypes dominate competitive positioning—distributed service center networks capturing proximity advantages, and captive-equipment specialists anchoring premium aerospace and medical segments. M&A activity concentrates on geographic fill-in acquisitions, while technology licensing partnerships accelerate digital twin deployment across installed furnace fleets.
Within the distributed service network tier, Bodycote plc and Bluewater Thermal Solutions exemplify channel-controlling scale, while ALD Vacuum Technologies GmbH anchors the premium equipment-specialist position. These three entities represent divergent competitive vectors: proximity-driven contract processing, integrated thermal solutions, and high-vacuum system manufacturing respectively.
| Leading Market Players |
|---|
| Advanced Heat Treat Corp |
| MetalTek International |
| Bodycote plc |
| Stack Metallurgical |
| Aichelin Group |
| ALD Vacuum Technologies |
| Braddock Metallurgical |
| Specialty Steel Treating |
| Bluewater Thermal Solutions |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on German and Japanese high-vacuum component suppliers determines both the three-tier pricing spread across furnace technologies and the elongated supply chain shape that concentrates procurement authority among OEM engineering teams.
Pricing Analysis
Current-generation electric induction systems command premium positioning over prior-generation fuel-fired furnaces and emerging hybrid configurations. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-certified aerospace processors from automotive batch operators and commodity steel treaters. Cost compression in standard-tier furnace operations is intensifying because natural gas price volatility erodes margins where energy constitutes 25-35% of processing costs. Automotive stampers exhibit highest price sensitivity due to volume procurement leverage, while medical instrument alloy processors show least sensitivity given precision tolerance requirements.
Supply Chain Analysis
Export-control restrictions on high-vacuum pump technology and advanced thermal sensors limit component flows from Germany and Japan to North American furnace builders. Geographic supply concentration centers on Germany, Japan, and China for vacuum chamber fabrication, induction coil winding, and atmosphere control systems. Raw material dependencies draw from specialty refractory alloys, high-purity graphite fixtures, and fluorinated process gases. Single-source vulnerability runs through concentrated German vacuum component suppliers extending lead times for North American buyers. Distribution runs through direct equipment sales for large furnace systems and regional service center networks for contract processing capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among tier-one automotive drivetrain manufacturers concentrates procurement authority at the design phase, shifting buyer power upstream from component fabricators to OEM quality engineering teams.
For Market Incumbents: Pre-empt displacement by electric induction systems through accelerated retrofit of fuel-fired furnace fleets before EPA compliance deadlines tighten. Anchor regional service center density in Michigan and Ohio automotive corridors to defend proximity advantages against emerging contract processors. Prioritize Nadcap certification investments to maintain aerospace tier supplier positioning as qualification timelines lengthen. For New Entrants and Emerging Players: Mid-market medical instrument alloy processing in the US Midwest represents the most penetrable entry point given limited qualified competition and continuous tolerance tightening. India's PLI scheme contract processing gaps for specialty steel downstream treatment offer secondary white-space targeting. Pursue technology licensing partnerships with established furnace control software providers to accelerate digital twin deployment without captive R&D burden. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors equipment-specialist archetypes over distributed service networks. Long-term viability across the five-to-ten year window hinges on vacuum technology positioning as F-Gas Regulation phase-downs accelerate conventional carburizing line displacement. Watch for induction-convection hybrid system commercialization as inflection indicator for next-generation technology leadership.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Virtualized quality assurance compresses competitive advantage of vertically integrated manufacturers over independent service providers. |
| Electric Induction Capacity Expansion | EPA emissions compliance redirects capital away from fuel-fired furnace infrastructure toward electric alternatives with compressed payback periods. |
| Nadcap Certification Investment | Aerospace tier supplier pre-approval at design phase requires 18-24 month qualification timelines that barrier new market entrants. |
| Vacuum Technology Substitution | EU F-Gas Regulation phase-downs on fluorinated greenhouse gases accelerate displacement of conventional carburizing lines. |
| Regional Service Center Density | Proximity advantages in automotive supply chains concentrate procurement volumes with certified regional champions capable of documented compliance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, and industry association reports covering furnace equipment shipments and contract processing volumes. Primary interviews engaged heat treatment plant managers, OEM procurement leads at tier-one drivetrain manufacturers, vacuum technology R&D directors, and aerospace quality engineering heads. Secondary validation drew from EPA emissions compliance filings, EU F-Gas Regulation implementation guidance, and China GB standards documentation. Bottom-up capacity modeling across installed furnace fleets triangulates against top-down demand estimates from automotive stamping and aerospace forging output.
Forecast inputs include technology substitution rates, regulatory compliance timelines, and energy price trajectory assumptions across the projection horizon. Segmentation dimensions modeled encompass process type, material category, end-use industry, and technology generation with geographic production cluster overlay. CAGRs derive from installed base expansion curves and replacement demand cycles rather than extrapolated point estimates. Industry-specific inputs incorporate EPA emissions standard implementation phases and China MIIT industrial policy directives on vacuum technology prioritization.
Stress conditions across natural gas price volatility bands, vacuum component supply disruption scenarios, and automotive production cycle downturns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology cost curves and regulatory enforcement intensity. Material shifts in EPA emissions standard stringency or EU F-Gas Regulation phase-down acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Melamine Market
Industrial Materials
Metal Molds Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Grouting Materials Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Tooling Board Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
Couplings Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Industrial Kiln Market