
 Brazing Strips Market | 2026-2036
Brazing Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Brazing Strips Market Outlook
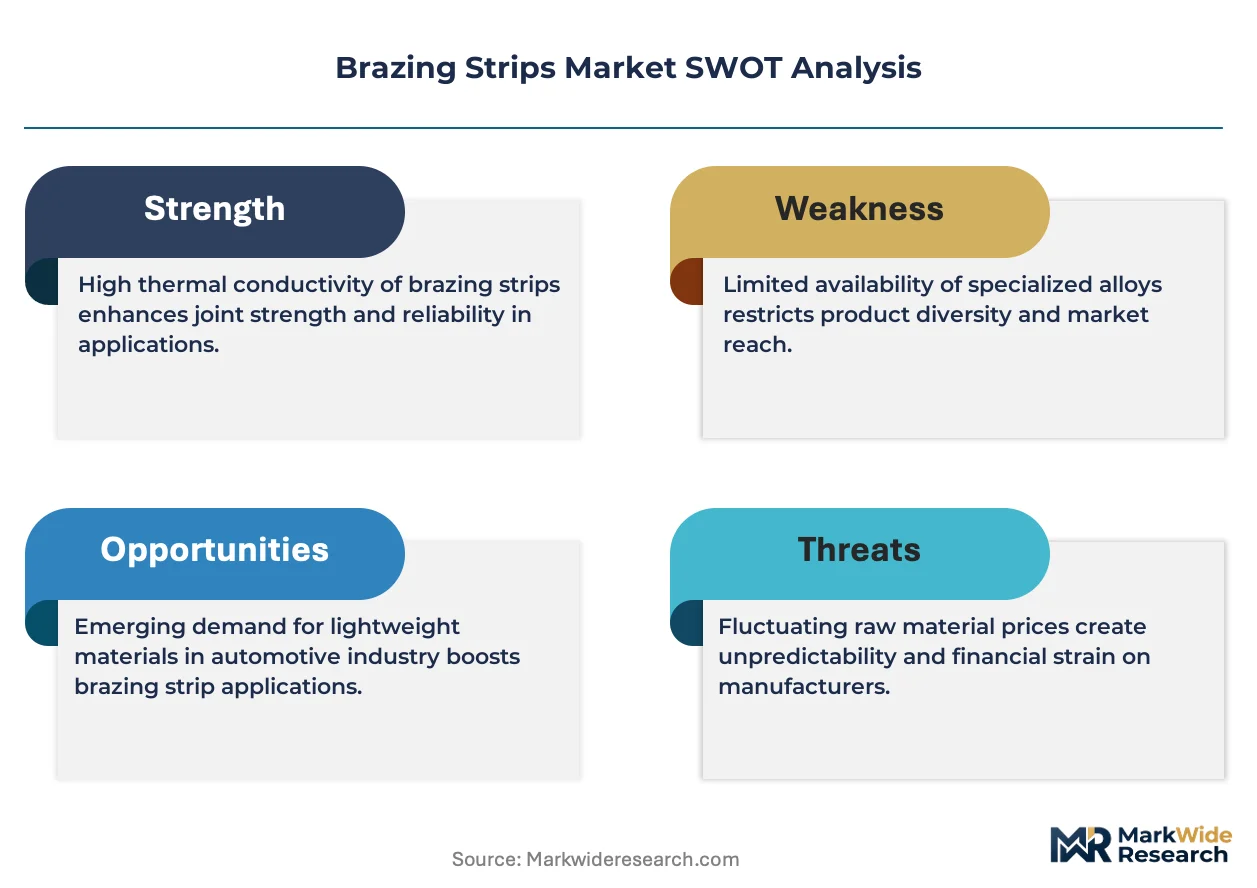
The brazing strips market is decoupling into two distinct supply tiers. Premium vacuum-grade silver-copper alloys command qualification cycles measured in years. Lucas-Milhaupt leverages captive wire-drawing capacity to lock in aerospace OEM approvals. Harris Products Group anchors its position through North American distribution density for HVAC service alloys.
Brazing strips are thin metal sections, typically 0.05 mm to 3.2 mm thick, composed of copper-silver-phosphorus or nickel-chromium-boron systems, manufactured via continuous casting and precision rolling for metallurgical bonding in dissimilar metal joints. Copper strips dominate volume in HVAC and plumbing applications where thermal conductivity governs performance. Silver-bearing formulations capture disproportionate margin pools in aerospace turbine repair and semiconductor cooling assemblies. Nickel-based strips sustain growth in automotive exhaust gas recirculation coolers where corrosion resistance exceeds 800°C operating thresholds.
REACH restrictions on cadmium-bearing filler metals and China's GB/T 6418 standards for brazing material classification reshape alloy development roadmaps across supplier laboratories. The US EPA and OSHA jointly enforce workplace exposure limits for brazing fumes containing manganese and hexavalent chromium compounds, pushing induction technology adoption. Stakeholders must monitor alloy substitution timelines as regulatory pressure on heavy metal content intersects with OEM lightweighting targets for thermal management systems.
Market Dynamics
The brazing strips market is bifurcating around vacuum-grade qualification cycles that now exceed 36 months for aerospace OEM approvals, while commodity HVAC alloys compete on North American distribution density alone.
Growth Catalysts
- Automotive heat exchanger assembly:EV thermal management systems require nickel-chromium-boron strips rated above 800°C for exhaust gas recirculation coolers in South Korean battery supply chains.
- REACH cadmium restrictions:ECHA enforcement is accelerating silver-copper-phosphorus substitution in European precision engineering clusters, forcing alloy reformulation across German supplier laboratories.
- Induction brazing technology:US EPA and OSHA joint fume exposure limits are displacing torch-based methods in HVAC fabrication, compressing cycle times for copper strip joints.
Market Restraints
- Silver price volatility:Precious metal input costs swing 15-40% annually, compressing margins on aerospace-grade silver-copper alloys where pass-through contracts lag spot markets by quarters.
- Supplier concentration risk:Vacuum-grade wire-drawing capacity concentrates in three German and Japanese producers, creating 18-month lead time exposure for qualified aerospace material.
- Technical limitation in dissimilar metal bonding:Aluminum-to-steel joints remain unreliable with standard copper-silver fillers, restricting penetration in automotive lightweighting applications.
Strategic Opportunities
- Underpenetrated Indian HVAC infrastructure:Bureau of Indian Standards certification gaps in brazing alloy classification create first-mover advantage for REACH-compliant European suppliers establishing local rolling capacity.
- Semiconductor cooling assemblies:Thermal interface bonding for AI chip packaging demands ultra-thin 0.05 mm silver strips with oxygen content below 10 ppm, a specification tier with limited qualified suppliers.
- China's dual carbon goals:MIIT energy efficiency mandates for industrial heat exchangers are accelerating nickel-based strip adoption in domestic EGR cooler production, displacing lower-grade alternatives.
Industry Challenges
- Metallurgical certification timelines:Aerospace OEM qualification cycles for new vacuum-grade alloys now span 3-4 years, freezing supplier R&D roadmaps and delaying revenue recognition.
- Workforce fume exposure compliance:OSHA manganese and hexavalent chromium monitoring requirements demand capital-intensive ventilation retrofits in legacy fabrication shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazing Strips Market |
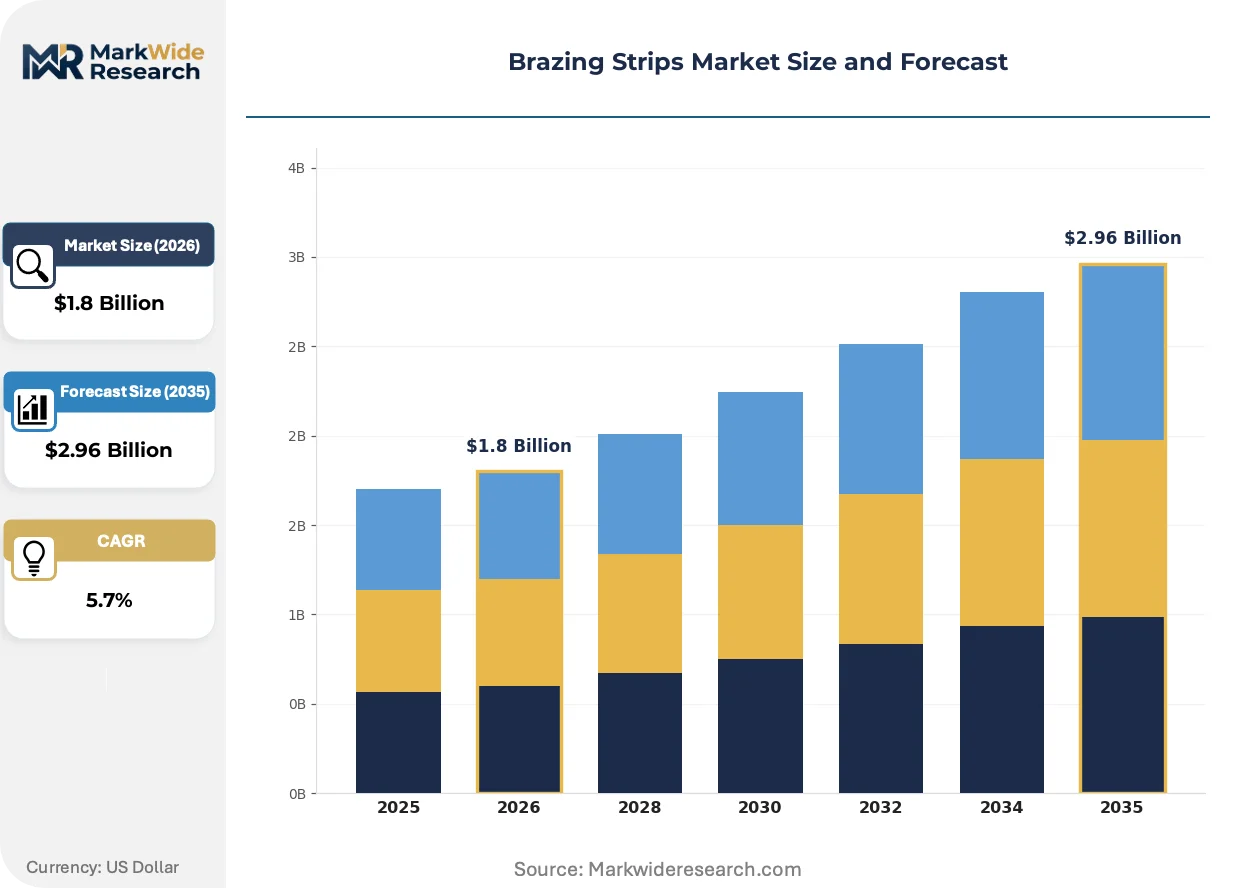
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Aluminum, Nickel, Silver End User: Aerospace, Automotive, Electrical, HVAC Form: Solid, Foil, Powder, Rod Technology: Manual, Semi-Automatic, Automatic, Induction |
| Companies Covered | Lucas-Milhaupt, Harris Products Group, Umicore, Morgan Advanced Materials, Johnson Matthey, Prince & Izant Company, Oerlikon Metco, Wall Colmonoy, Aimtek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazing Strips Market Strategic Shifts
Active diffusion bonding techniques and real-time thermal monitoring are compressing joint quality variance in precision applications, while regulatory chemistry constraints force fundamental alloy system redesigns.
Laser-assisted brazing is converging with continuous strip feeding systems to enable single-pass joining of dissimilar thicknesses in automotive battery cooling plates. Tier-1 suppliers in Stuttgart and Detroit are piloting this hybrid approach for 800V EV architectures. The technology is converging with existing resistance welding lines, allowing capital-efficient retrofit rather than greenfield investment.
REACH Annex XVII cadmium restrictions now prohibit filler metals above 0.01% content in European heat exchanger manufacturing, with ECHA enforcement actions accelerating in 2024. German precision engineering clusters have shifted procurement specifications to silver-copper-phosphorus alternatives within 18 months. The regulation is compressing qualification timelines for compliant alloys across aerospace and semiconductor cooling segments.
Buyer consolidation among HVAC original equipment manufacturers is compressing supplier bases from regional distributors to direct mill relationships. Lennox, Carrier, and Daikin have centralized brazing alloy procurement through single-source agreements with qualified North American wire producers. This concentration is most visible in the southeastern United States, where new heat pump manufacturing capacity is concentrating demand among three approved suppliers.
Brazing Strips Market Segmentation
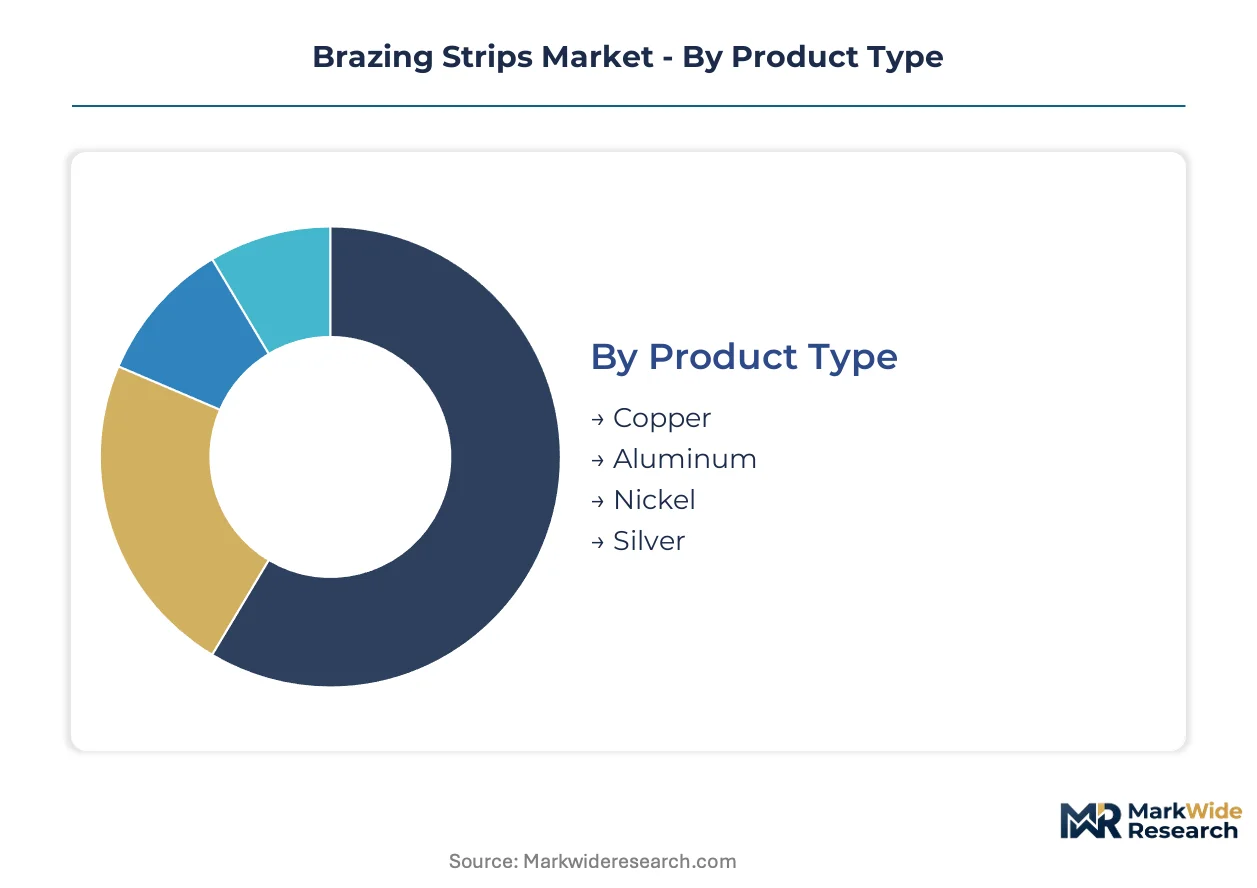
Brazing strips segment by metallurgical performance tiers that separate commodity thermal conductivity from vacuum-grade aerospace qualification. Alloy composition dictates margin structure more sharply than form factor or joining method.
Product Type:
Copper alloys dominate unit volume while silver-bearing formulations capture disproportionate margin pools in precision applications.
- Copper:Continuous-cast copper-silver-phosphorus strips between 0.05 mm and 3.2 mm thickness serve HVAC heat exchanger fabrication and plumbing infrastructure. Demand concentrates in German precision engineering clusters where REACH cadmium restrictions have forced rapid alloy reformulation. Copper strips face margin compression from silver price pass-through limitations in long-term service contracts.
- Silver:Vacuum-grade silver-copper alloys with oxygen content below 10 ppm command 36-month OEM qualification cycles in aerospace turbine repair and semiconductor cooling assemblies. South Korean EV battery supply chains are expanding procurement of ultra-thin 0.05 mm specifications for thermal interface bonding in AI chip packaging applications.
- Nickel:Nickel-chromium-boron systems sustain corrosion resistance above 800°C operating thresholds in automotive exhaust gas recirculation coolers.
- Aluminum:Lightweight aluminum strips target automotive lightweighting applications where aluminum-to-steel joint reliability remains technically constrained with standard copper-silver fillers.
Mature deployment sits with copper formulations in established HVAC infrastructure. Newer deployment is concentrated in silver-bearing vacuum-grade alloys for semiconductor and aerospace thermal management.
End User:
Application requirements split between corrosion-critical automotive systems and precision-bonded aerospace components.
- Automotive:EV thermal management systems and exhaust gas recirculation coolers drive nickel-based strip specifications above 800°C ratings. China's MIIT energy efficiency mandates are accelerating domestic EGR cooler production with qualified nickel-chromium-boron alloys.
- Aerospace:Turbine repair applications demand vacuum-grade silver-copper alloys with multi-year OEM qualification cycles that freeze supplier R&D roadmaps and delay revenue recognition.
- HVAC:Heat pump manufacturing capacity in the southeastern United States concentrates demand among three approved North American wire producers under single-source procurement agreements.
- Electrical:Power distribution and transformer applications utilize copper strip formulations where thermal conductivity governs joint performance.
Procurement consolidation is most advanced in HVAC with centralized mill-direct relationships. Aerospace maintains the most fragmented supplier base due to qualification barriers.
Form:
Physical configuration aligns with automation level and joint accessibility requirements in fabrication workflows.
- Foil:Ultra-thin 0.05 mm foils serve semiconductor cooling assemblies and AI chip packaging where thermal interface bonding demands precise thickness control.
- Solid:Standard solid strips dominate HVAC and plumbing applications with thickness ranges from 0.5 mm to 3.2 mm for conventional torch and induction joining.
- Powder:Powder forms enable custom alloy blending for specialized dissimilar metal joints in repair applications.
- Rod:Rod configurations support manual brazing operations in field service and maintenance environments.
Volume concentration favors solid strip formats in commodity HVAC. Foil specifications are expanding most quickly in semiconductor thermal management.
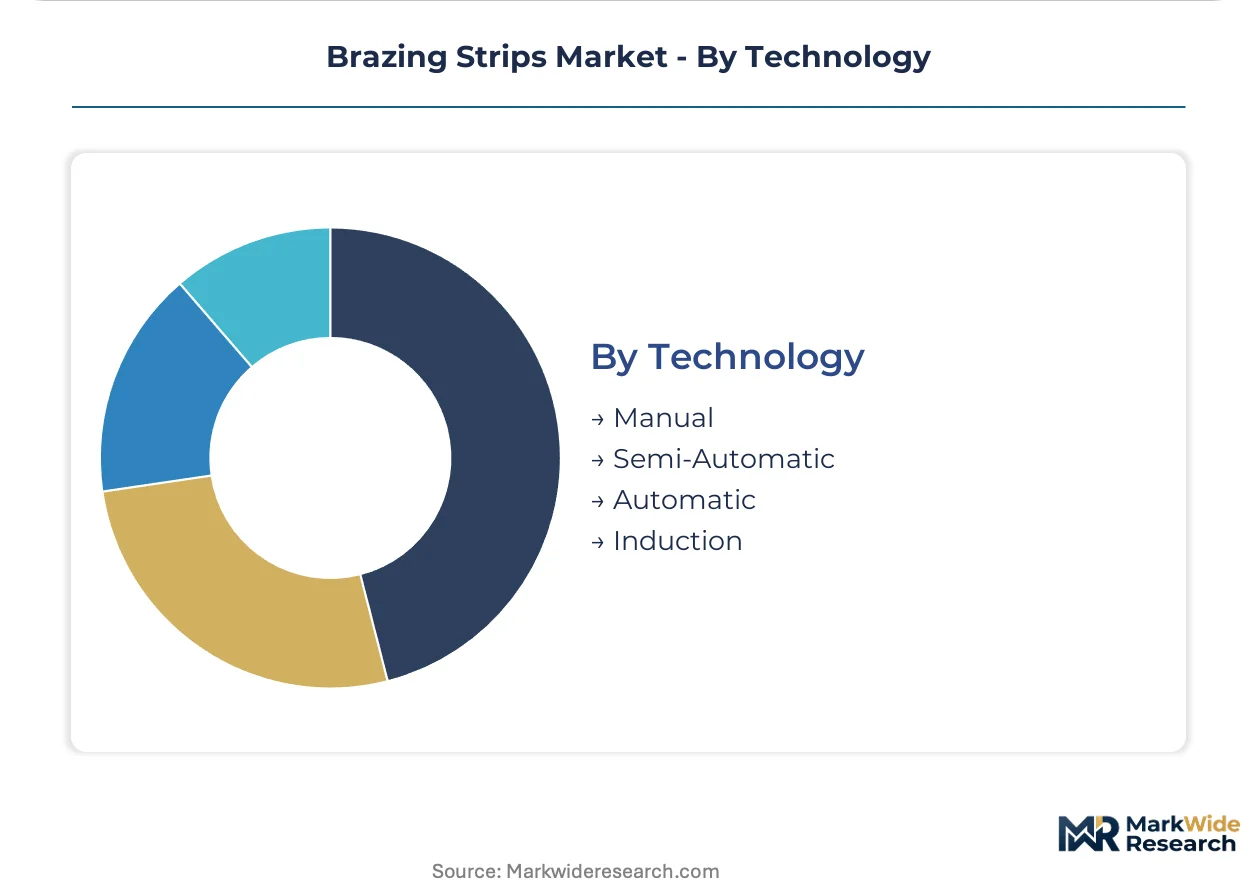
Technology:
Joining method selection is displacing torch-based approaches where US EPA and OSHA fume exposure limits apply.
- Induction:Induction brazing compresses cycle times for copper strip joints while eliminating manganese and hexavalent chromium fume exposure in fabrication shops. US regulatory enforcement is accelerating capital investment in induction retrofit over greenfield installation.
- Automatic:Automated strip feeding systems converge with laser-assisted brazing for single-pass joining of dissimilar thicknesses in automotive battery cooling plates.
- Semi-Automatic:Hybrid systems bridge manual precision with production throughput in precision engineering clusters.
- Manual:Torch-based manual methods persist in field service and legacy fabrication where capital retrofit economics are unfavorable.
Regulatory pressure is concentrating new investment in induction and automatic systems. Manual torch methods are contracting in covered industrial fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand precision engineering clusters drive alloy specification upgrades for automotive thermal management systems. German suppliers navigate REACH cadmium restrictions while scaling vacuum-grade capacity for aerospace OEMs. South Korean battery supply chains concentrate nickel-based strip procurement for EV exhaust gas recirculation coolers.
United States
Heat pump manufacturing concentrates in southeastern states where Lennox, Carrier, and Daikin operate centralized procurement through mill-direct agreements. EPA and OSHA joint enforcement of manganese and hexavalent chromium fume limits accelerates induction brazing retrofits in legacy fabrication shops. Detroit automotive clusters pilot laser-assisted strip feeding systems for 800V battery cooling plate assembly.
Germany
Precision engineering clusters in Stuttgart and Munich drive silver-copper-phosphorus substitution following ECHA REACH Annex XVII enforcement. German laboratories compress 36-month aerospace qualification cycles for vacuum-grade alloys with oxygen content below 10 ppm. Bavarian wire-drawing capacity locks in multi-year OEM approvals through captive metallurgical certification.
China
MIIT energy efficiency mandates accelerate domestic EGR cooler production with nickel-chromium-boron alloys rated above 800°C. GB/T 6418 standards for brazing material classification tighten heavy metal content thresholds parallel to European REACH restrictions. Yangtze River Delta rolling mills scale capacity for industrial heat exchanger fabrication under dual carbon goals.
South Korea
EV battery supply chains expand procurement of ultra-thin 0.05 mm silver strips for thermal interface bonding in semiconductor cooling. Busan-Ulsan manufacturing corridors concentrate nickel-based alloy demand for exhaust gas recirculation systems. MFDS alignment with international metallurgical standards streamlines import qualification for vacuum-grade materials.
India
Bureau of Indian Standards certification gaps in brazing alloy classification create first-mover openings for REACH-compliant European suppliers. HVAC infrastructure expansion in Maharashtra and Gujarat drives copper strip demand for heat exchanger fabrication. Local rolling capacity investments target import substitution for precision-engineered thermal management components.
Brazing Strips Market Competitive Environment
Premium-margin players sit above commodity-margin players across qualification-cycle duration and metallurgical purity tiers. Vacuum-grade suppliers with captive wire-drawing capacity command 36-month OEM lock-in periods, while HVAC-focused competitors compete on North American distribution density alone. Three archetypes dominate: aerospace-qualified vacuum-grade specialists, automotive thermal systems integrators, and commodity copper alloy distributors. Competitive moves concentrate on backward integration into precision rolling capacity and geographic expansion into underpenetrated Asian HVAC markets.
Within the vacuum-grade specialist tier, Lucas-Milhaupt and Harris Products Group exemplify divergent geographic anchoring strategies. Lucas-Milhaupt occupies a position tied to captive wire-drawing infrastructure for aerospace OEM approvals. Harris Products Group represents the distribution-density archetype for North American HVAC service alloys. Umicore sits within the materials science conglomerate structure, spanning multiple metallurgical product categories beyond brazing strips alone.
| Leading Market Players |
|---|
| Lucas-Milhaupt |
| Harris Products Group |
| Umicore |
| Morgan Advanced Materials |
| Johnson Matthey |
| Prince & Izant Company |
| Oerlikon Metco |
| Wall Colmonoy |
| Aimtek |
| Others |
Value Chain & Pricing Dynamics
Precision metallurgist concentrations in Bavarian wire-drawing clusters amplify labor-cost differentials between vacuum-grade aerospace alloys and commodity HVAC formulations. REACH cadmium restrictions and silver price pass-through limitations widen pricing-tier spreads as European suppliers absorb reformulation costs while North American distributors compete on volume scale alone.
Pricing Analysis
Yield-guarantee contracts for semiconductor cooling assemblies anchor value-based pricing for ultra-thin 0.05 mm silver strips with oxygen content below 10 ppm. Three-tier pricing structure across premium vacuum-grade, standard automotive thermal, and economy HVAC service levels differentiates by certification cycle duration and metallurgical purity. Cost compression in commodity copper-silver-phosphorus alloys intensifies because long-term service contracts lag spot silver markets by quarters. HVAC original equipment manufacturers exhibit highest price sensitivity through centralized mill-direct procurement, while aerospace OEMs prioritize qualification security over unit cost.
Supply Chain Analysis
China's GB/T 6418 standards and India's Bureau of Indian Standards certification gaps are reshaping sourcing patterns for REACH-compliant European suppliers establishing local rolling capacity. Geographic supply concentration centers on German precision engineering clusters, Japanese vacuum-grade wire-drawing facilities, and Yangtze River Delta rolling mills. Raw material dependencies rest on silver bullion markets, high-purity copper cathodes, and nickel-chromium master alloys. Single-source vulnerability concentrates in qualified aerospace material where 36-month OEM approval cycles freeze alternative supplier qualification. Distribution runs through direct mill relationships for HVAC consolidation and specialized metallurgical distributors for precision engineering segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brazing strips market is becoming a backward-integration race where captive wire-drawing capacity and in-house vacuum-grade qualification laboratories determine tier access. Players are pursuing upstream control over metallurgical certification infrastructure to lock in multi-year OEM approvals.
For Market Incumbents: Hedge silver price volatility through indexed procurement contracts with precious metal suppliers while expanding captive rolling capacity in South Korean EV supply corridors. Defend against REACH-compliant European entrants in Indian HVAC infrastructure by accelerating Bureau of Indian Standards certification timelines. Prioritize induction brazing technology partnerships to capture EPA and OSHA compliance-driven retrofit demand in southeastern United States fabrication shops. For New Entrants and Emerging Players: Regional HVAC distributors in Maharashtra and Gujarat offer channel access for REACH-compliant copper alloy formulations targeting heat exchanger fabrication expansion. White-space concentration sits with ultra-thin 0.05 mm silver strip specifications for semiconductor cooling assemblies where qualified supplier scarcity exceeds demand growth. Pursue technical licensing agreements with German precision engineering clusters to compress vacuum-grade alloy development cycles. For Investors and Strategic Acquirers: The window for entry favors mid-cap vacuum-grade specialists with captive wire-drawing infrastructure and active aerospace OEM qualification pipelines. Long-term viability hinges on regulatory chemistry adaptation capacity as REACH restrictions and China's dual carbon goals converge on heavy metal content thresholds. Monitor ECHA enforcement action intensity as inflection indicator for silver-copper-phosphorus substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire-Drawing Capacity | Captive metallurgical certification locks in 36-month aerospace OEM approval cycles. |
| REACH-Compliant Alloy Reformulation | Silver-copper-phosphorus substitution accelerates across German precision engineering clusters. |
| Induction Brazing Technology Deployment | EPA and OSHA fume exposure compliance drives capital retrofit in legacy fabrication shops. |
| Ultra-Thin Foil Specification Development | 0.05 mm silver strips with sub-10 ppm oxygen content serve AI chip packaging thermal interfaces. |
| Geographic Expansion into Indian HVAC Infrastructure | Bureau of Indian Standards certification gaps create first-mover advantage for European suppliers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this brazing strips market assessment. Primary interviews with vacuum-grade alloy plant managers, automotive thermal system procurement leads, HVAC original equipment manufacturer technical directors, and precision rolling distribution channel partners combined with secondary validation from ECHA REACH enforcement databases, MIIT energy efficiency mandate publications, and SEC 10-K filings from listed metallurgical suppliers. Bottom-up alloy consumption modeling and top-down thermal management system demand estimation provided triangulation across the analysis window.
Granularity-level modeling segmented the market by metallurgical composition tier, end-use application thermal requirement, form factor thickness specification, and joining technology automation level across the projection horizon. CAGRs derived from regression analysis against automotive heat exchanger production forecasts and semiconductor packaging capacity expansion plans. Industry-specific inputs included aerospace OEM qualification cycle duration distributions and silver price volatility impact coefficients on margin structure.
Caveats apply where ECHA enforcement intensity, MIIT mandate implementation pace, or silver market dislocation could materially shift the outlook. Forecasts reflect assumptions about regulatory chemistry constraint timelines and OEM lightweighting target trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Ultra-Low Alpha Metal Market
Metals
Medium Carbon Steel Market
Metals
Transition Metals Market
Metals
Nickel Foam Market
Metals
Electrolytic Manganese Metal Market
Metals
Global Oxygen-Free Copper Market
Metals
Crude Steel Market
Metals
Copper Powder Market
Metals
Iron Casting Market
Metals
Iron and Steel Market
Metals
Aluminum Hot Rolling Mill Market
Metals
Qatar Metalworking Market
Metals
Powder Metallurgy Market
Metals
Steel Salvage Drums Market
Metals
Metallurgical Silicon Market
Metals
Vietnam Aluminum Market