
 Solid Surface Materials Market | 2026-2036
Solid Surface Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Surface Materials Market Outlook
Modular countertop-and-sink bundling is restructuring buyer procurement patterns across the solid surface materials industry. DuPont leverages its Corian brand heritage to sustain premium positioning in healthcare-specified installations. Wilsonart anchors North American distribution through fabricator-direct channel control. Cosentino Group competes on sintered stone adjacencies while extending solid surface portfolio breadth.
Solid surface materials denote engineered mineral-filled acrylic or polyester resin sheets, typically comprising roughly two-thirds aluminum trihydrate and one-third polymer binder, thermoformed or fabricated into seamless, non-porous surfaces for hygiene-critical environments. Acrylic formulations dominate premium specification due to superior thermoformability and repairability, while polyester segments occupy cost-driven residential retrofit demand where fabrication simplicity outweighs performance margins. The hospitality end user category generates concentrated project volume, though healthcare procurement commands higher per-unit specification value.
US EPA emissions standards and OSHA workplace exposure limits constrain resin formulation chemistry, while EU REACH chemical registration requirements shape import access for Asian manufacturers. FDA compliance for food-contact surfaces and NSF/ANSI 51 certification further filter product eligibility in commercial kitchen applications. Stakeholders must monitor evolving state-level low-VOC building material mandates alongside emerging circularity disclosure obligations under CSRD-aligned procurement rules.
Market Dynamics
Modular countertop-and-sink bundling is restructuring procurement patterns across the solid surface materials industry, compressing traditional fabricator-distributor relationships and forcing upstream consolidation.
Growth Catalysts
- EU Green Deal building renovation targets:Mandates for low-emission materials in commercial retrofits across France, Germany, and Italy are accelerating substitution away from high-carbon alternatives in hospitality and healthcare fit-outs.
- Healthcare infection control specifications:US hospitals are expanding seamless solid surface installations in surgical suites and patient rooms due to superior cleanability versus tile and laminate.
- China urban commercial construction corridors:Dense development in Shanghai, Shenzhen, and Chengdu is concentrating demand for premium acrylic formulations in mixed-use towers and luxury retail.
Market Restraints
- Aluminum trihydrate price volatility:Raw mineral filler costs fluctuate with bauxite mining output and energy-intensive refining economics, squeezing polyester segment margins.
- Asian manufacturer REACH compliance gaps:EU chemical registration requirements create import friction for uncertified resin sheet producers seeking European market access.
- Sintered stone substitution threat:Ultra-compact surfaces from adjacent material categories capture premium kitchen specification with superior heat resistance.
Strategic Opportunities
- India commercial real estate build-out:Underpenetrated solid surface specification in Mumbai and Bangalore hospitality projects offers first-mover positioning as BIS standards mature.
- Circular material recovery programs:CSRD-aligned procurement rules in the Netherlands and Denmark are creating disclosed recycled-content premiums for compliant fabricators.
- Digital templating-to-fabrication integration:CNC routing and laser measurement convergence enables made-to-measure sink-countertop bundles with compressed lead times.
Industry Challenges
- Skilled thermoforming technician scarcity:Complex acrylic bending and seaming expertise concentrates among aging fabricator workforces in mature markets.
- NSF/ANSI 51 certification timeline compression:Food-contact surface approval delays bottleneck commercial kitchen project deliveries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Surface Materials Market |
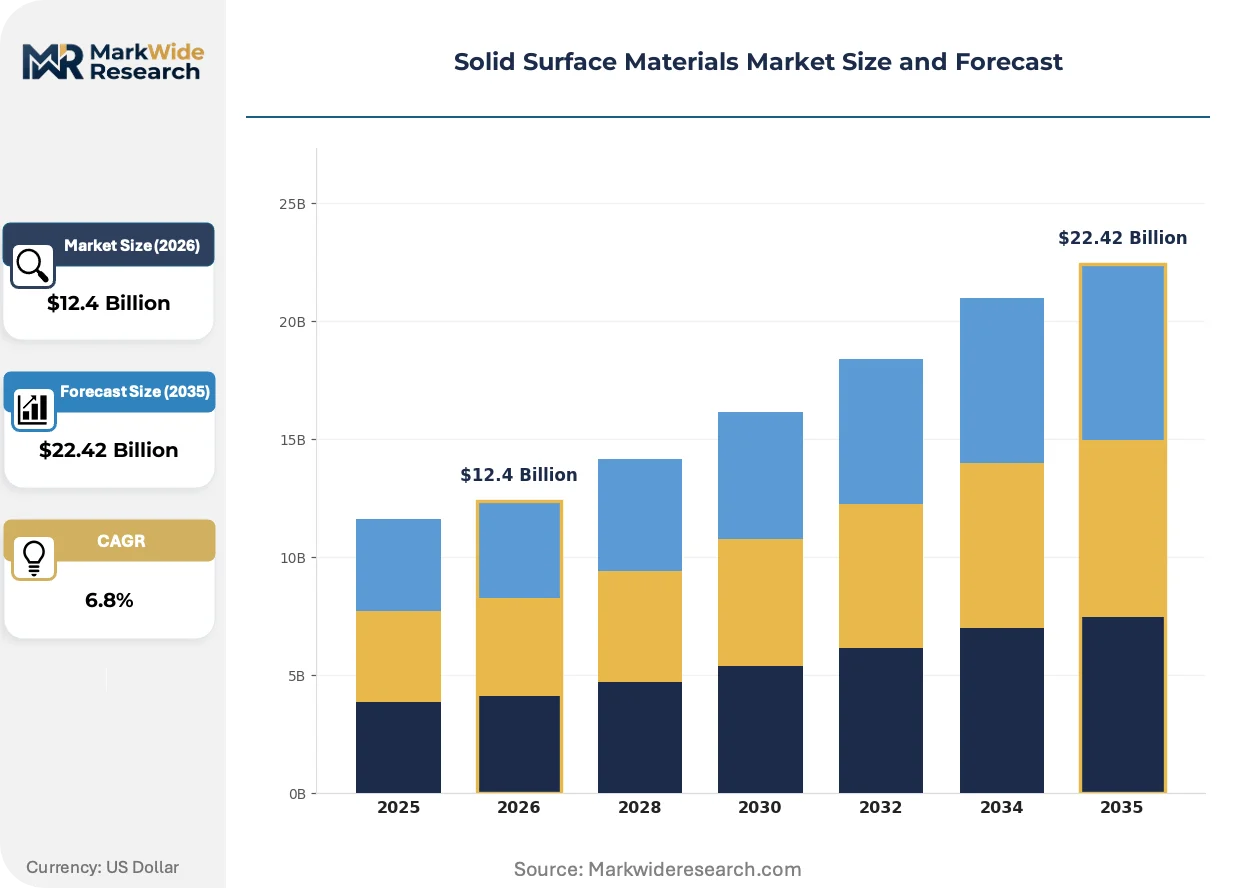
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin-Based, Acrylic, Polyester, Composite Application: Countertops, Sinks, Wall Cladding, Furniture End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Showrooms |
| Companies Covered | DuPont, LG Hausys, Wilsonart, Aristech Surfaces, Formica Corporation, Hanwha L&C, Cosentino Group, Caesarstone, Staron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Surface Materials Market Strategic Shifts
Material science advances and regulatory disclosure mandates are converging to reshape competitive positioning in solid surface specification. Three developments warrant particular attention.
Thermoformable acrylic-nanocomposite sheet technology is advancing surface durability and repairability in high-traffic installations. Hospitality operators in Dubai and Singapore are specifying these formulations for luxury hotel lobbies and guest bathrooms. The technology is modularizing countertop production into standardized sub-assemblies that ship flat and configure on-site.
REACH SVHC candidate list expansion is forcing reformulation of legacy polyester resin chemistries. Manufacturers serving EU markets must eliminate specific plasticizers and stabilizers or face market exclusion. Healthcare-specified acrylic lines are responding fastest due to existing purity requirements for FDA compliance.
Buyer concentration among national hospitality chains is compressing vendor negotiation cycles and unbundling after-sales service from material supply. Marriott and Hilton procurement teams now contract directly with fabricator networks, bypassing traditional distributor markup layers. This pattern is most visible in US Sun Belt expansion corridors where new construction volume concentrates purchasing power.
Solid Surface Materials Market Segmentation
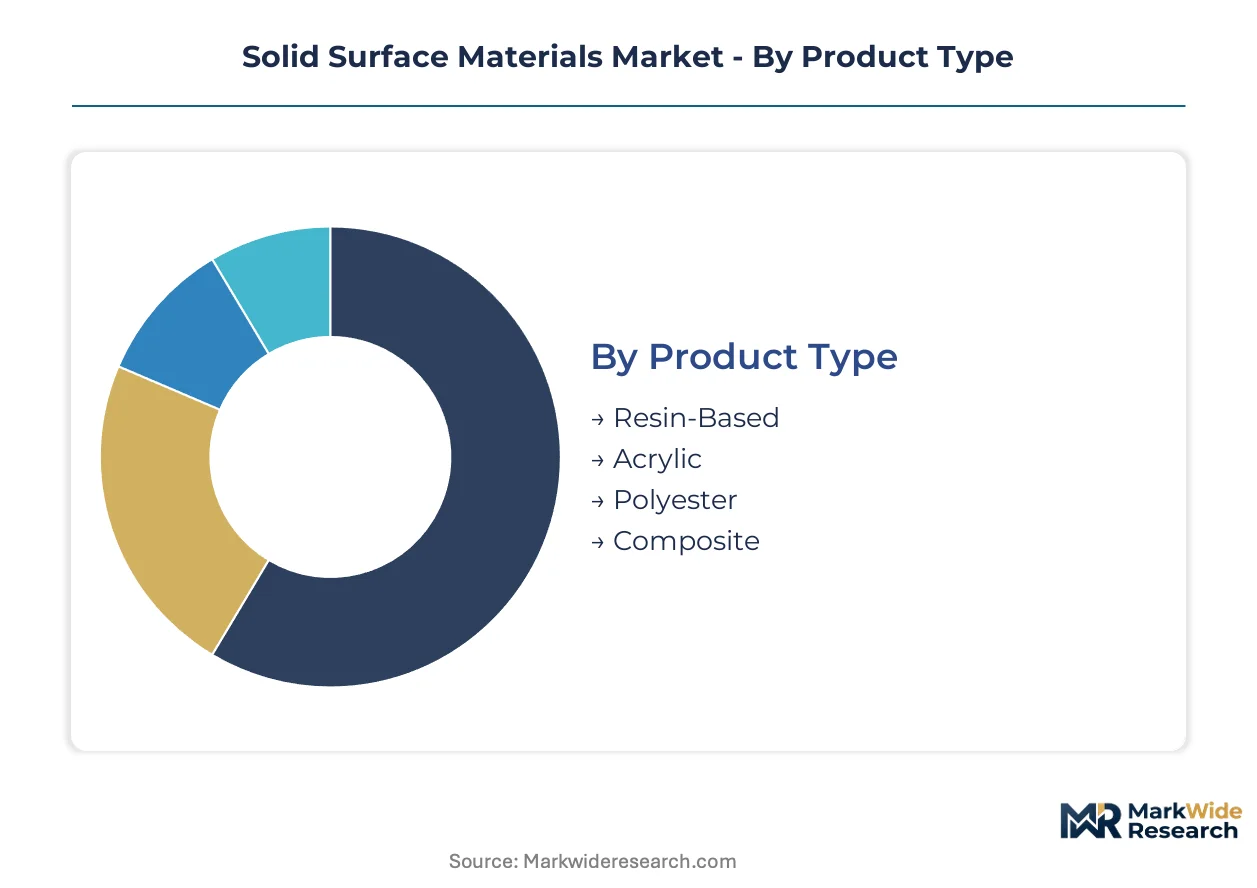
Solid surface specification diverges sharply across resin chemistry, installation context, and procurement channel. Each segmentation axis carries distinct margin structures and regulatory exposure that reshape vendor prioritization.
Product Type:
Resin formulation determines thermoformability, repair protocol, and compliance pathway for end-use certification.
- Acrylic:Premium thermoplastic formulations enable seamless bending and invisible seam repair. US hospitals specify these surfaces for surgical suite integration due to superior cleanability credentials.
- Polyester:Cost-optimized mineral-filled sheets serve residential retrofit demand where fabrication simplicity outweighs performance premiums. China's urban commercial corridors absorb volume for budget-conscious mixed-use fit-outs.
- Resin-Based:Hybrid binder systems balance cost and performance for mid-market hospitality specification.
- Composite:Engineered multi-layer constructions target heavy-traffic commercial installations requiring enhanced impact resistance.
Acrylic leads on scale; Composite leads on momentum.
Application:
Installation geometry dictates fabrication complexity and field labor allocation across project types.
- Countertops:Horizontal work surfaces generate the largest project volume, with modular sink bundling compressing traditional fabricator-distributor relationships. Marriott and Hilton procurement teams now contract directly with fabricator networks.
- Wall Cladding:Vertical installations in healthcare corridors and hospitality lobbies demand fire-rated formulations and seamless panel integration.
- Sinks:Integrated basin fabrication requires specialized thermoforming expertise concentrated among aging technician workforces in mature markets.
- Furniture:Custom millwork and fixture applications serve boutique hospitality and premium residential segments with extended lead times.
Countertops dominate volume; Wall Cladding is expanding most quickly.
End User:
Buyer procurement power and specification stringency create tiered margin structures across demand categories.
- Healthcare:Infection control mandates drive seamless surface specification in US surgical suites and patient rooms. FDA compliance requirements filter vendor eligibility.
- Hospitality:National chains concentrate purchasing power, with procurement teams unbundling after-sales service from material supply.
- Commercial:Office and retail fit-outs respond to EU Green Deal low-emission mandates in France, Germany, and Italy.
- Residential:Cost-driven retrofit demand favors polyester formulations and simplified fabrication protocols.
Healthcare leads on margin per unit; Hospitality leads on project volume.
Distribution Channel:
Channel control determines pricing transparency and customer relationship ownership in a consolidating supply chain.
- Direct Sales:Fabricator-direct relationships bypass distributor markups, accelerating in US Sun Belt construction corridors where national hospitality chains concentrate purchasing.
- Distributors:Traditional stock-and-sell networks retain relevance for fragmented residential and small commercial contractors.
- Showrooms:Specification influence persists among architects and interior designers selecting materials for premium projects.
- Online Retail:Digital templating integration enables made-to-measure ordering with compressed lead times for standardized product configurations.
Distributors retain widest coverage; Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DuPont pioneered solid surface materials in the United States during the 1960s, establishing Corian as the foundational brand before manufacturing spread to Europe and Asia. This historical lineage shapes today's geographic concentration of formulation expertise and specification influence.
United States
Healthcare infection control mandates drive seamless surface specification in surgical suites and patient rooms across Texas Medical Center and Mayo Clinic networks. EPA emissions standards and OSHA workplace exposure limits constrain resin chemistry for domestic manufacturers. Fabricator networks in the US Sun Belt corridor now contract directly with Marriott and Hilton procurement teams, bypassing traditional distributor markups.
Germany
EU Green Deal building renovation targets accelerate low-emission material substitution in commercial hospitality fit-outs across Berlin and Munich. REACH chemical registration requirements filter import access for uncertified Asian resin sheet producers. Industrial clusters in North Rhine-Westphalia concentrate thermoforming expertise serving healthcare and premium residential segments.
China
Dense urban commercial construction in Shanghai, Shenzhen, and Chengdu concentrates demand for premium acrylic formulations in mixed-use towers and luxury retail. GB standards and MIIT industrial policy shape domestic manufacturing compliance pathways. The Yangtze River Delta corridor anchors polyester segment production for budget-conscious fit-out demand.
India
Underpenetrated solid surface specification in Mumbai and Bangalore hospitality projects offers first-mover positioning as BIS standards mature. CDSCO and national building code evolution gradually align with international hygiene certification requirements. Commercial real estate build-out in Hyderabad's HITEC City corridor demonstrates accelerating specification adoption.
United Arab Emirates
Hospitality operators in Dubai and Abu Dhabi specify thermoformable acrylic-nanocomposite formulations for luxury hotel lobbies and guest bathrooms. MOHAP building material regulations and Dubai Municipality green building codes shape product eligibility. Fabrication expertise concentrates in Jebel Ali industrial zone serving Gulf Cooperation Council fit-out demand.
Solid Surface Materials Market Competitive Environment
Premium-margin players sit above commodity-margin players across resin formulation tiers, with acrylic specialists commanding specification value in healthcare and hospitality while polyester manufacturers compete on residential retrofit volume. The vendor base spans multinational chemical conglomerates, regional fabricator networks, and specialized surface material producers. Three archetypes dominate: brand-heritage incumbents leveraging decades of specification relationships, scale-driven Asian manufacturers optimizing mineral filler economics, and sintered stone adjacency players extending portfolio breadth. Competitive moves center on fabricator-direct channel consolidation and modular countertop-sink bundling that compresses traditional distributor relationships.
Among heritage-brand incumbents, DuPont and Wilsonart exemplify premium-tier positioning through specification influence in hygiene-critical environments. LG Hausys represents the scale-driven Korean manufacturer archetype with integrated resin formulation and sheet production capabilities. Cosentino Group occupies a position bridging solid surface and adjacent sintered stone categories, extending portfolio breadth while competing on material science credentials. These three anchors illustrate the strategic divergence between brand-driven specification power and manufacturing-scale cost optimization.
| Leading Market Players |
|---|
| DuPont |
| LG Hausys |
| Wilsonart |
| Aristech Surfaces |
| Formica Corporation |
| Hanwha L&C |
| Cosentino Group |
| Caesarstone |
| Staron |
| Others |
Value Chain & Pricing Dynamics
Aluminum trihydrate spot indices cascade through solid surface manufacturing into three distinct pricing tiers, with bauxite-refining energy costs compressing polyester segment margins while acrylic formulations retain specification premiums in healthcare procurement.
Pricing Analysis
Project-based contract pricing dominates solid surface specification, with three-tier pricing structure across premium, standard, and economy levels separating FDA-compliant acrylic from REACH-certified hybrids and uncertified polyester imports. Price differentiation hinges on certification grade (NSF/ANSI 51, FDA compliance) and volume scale, with national hospitality chains extracting double-digit discounts through direct fabricator contracting. Cost compression in polyester residential retrofit is intensifying because aluminum trihydrate volatility feeds raw material uncertainty into spot purchasing. Small commercial contractors show highest price sensitivity; US hospital systems prioritize infection control performance over unit economics.
Supply Chain Analysis
Regional distribution centers in North Rhine-Westphalia, Texas, and the Yangtze River Delta anchor hub-and-spoke patterns that position sheet stock within 48-hour delivery radius of major fabrication clusters. Manufacturing concentrates in China, South Korea, and Germany, with resin formulation expertise tethered to petrochemical feedstock access and thermoforming technician density. Raw material dependencies draw from bauxite mining corridors, methyl methacrylate monomer supply, and specialized ATH refining capacity. Single-source vulnerability runs through Chinese ATH processing dominance. Distribution runs through fabricator-direct channels bypassing traditional stock-and-sell networks in US Sun Belt corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid surface markets offer margin expansion through premium-tier specification shifts in healthcare and modular bundling economics that capture installation labor value.
For Market Incumbents: Cement specification relationships with US hospital GPOs and national hospitality procurement teams before sintered stone substitutes capture premium kitchen volume. Deepen backward integration into methyl methacrylate supply to defend against petrochemical feedstock volatility. Prioritize REACH SVHC-compliant reformulation to maintain EU market access as candidate list expansion accelerates. For New Entrants and Emerging Players: Begin with underpenetrated commercial real estate corridors in Mumbai and Bangalore where BIS standard maturation creates first-mover windows before heritage brands establish distribution. Target mid-market hospitality retrofit in India's HITEC City corridor with digital templating-enabled made-to-measure bundles that compress lead times versus established import channels. For Investors and Strategic Acquirers: Asymmetric upside sits with acrylic-nanocomposite technology specialists possessing thermoformable sheet patents and healthcare certification pathways. Long-term viability favors fabricator networks controlling direct procurement relationships with Marriott-scale buyers. Watch CDSCO alignment with international hygiene certification as inflection signal for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captures methyl methacrylate margin and insulates against petrochemical feedstock volatility from Korean and Saudi suppliers. |
| FDA-Compliant Acrylic Line Expansion | Locks in surgical suite specification at Texas Medical Center and Mayo Clinic networks ahead of competitor reformulation cycles. |
| Digital Templating-to-Fabrication Integration | Enables made-to-measure sink-countertop bundles with compressed lead times for Hilton and Marriott procurement teams. |
| Circular Material Recovery Program | Captures CSRD-aligned procurement premiums in Netherlands and Denmark disclosed recycled-content mandates. |
| REACH-Compliant Reformulation Investment | Eliminates SVHC candidate list plasticizers to maintain EU import access as ECHA restrictions tighten. |
Study Parameters
Coverage spans the United States, Germany, China, India, and the United Arab Emirates, with primary inputs from each market's fabrication clusters and specification centers. The approach combines interviews with solid surface fabricators, hospitality procurement directors, healthcare facility managers, and resin formulation chemists with secondary validation from customs trade data, SEC filings of surface material producers, EPA emissions disclosures, and ECHA REACH registration databases. Bottom-up project pipeline tracking and top-down construction spend analysis provide triangulation across volume estimation methods.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon, with segmentation modeling across resin chemistry, installation application, end-user category, and procurement channel dimensions. CAGRs derive from weighted average of historical trend extrapolation and driver-based scenario analysis, incorporating aluminum trihydrate price elasticity, healthcare construction permit flows, and EU Green Deal renovation target implementation rates as industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen REACH SVHC list expansions, abrupt bauxite supply disruptions, and sintered stone technological breakthroughs that could accelerate substitution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Steel Cord Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Shock Mat Market
Industrial Materials
Industrial Films Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Injection Molding Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Felt Gasket Market
Industrial Materials
High Modulus Polyethylene Rope Market