

Band File Sander Belts Market Size, Share, and Industry Trends Forecast 2026-2036
Band File Sander Belts Market Insights
Modular grit-size bundling is hardening as the dominant procurement pattern, with buyers shifting from single-SKU orders to configured assortments spanning coarse through extra fine. Norton Abrasives leverages its broad grit portfolio to anchor this bundling trend across North American distribution. Klingspor sustains competitive pressure through specialized ceramic formulations targeting metal fabrication end users. Bosch competes on channel density, extending its retail and direct-to-contractor presence in European markets.
Band file sander belts are continuous-loop abrasive belts engineered to fit compact, handheld band file tools, typically constructed with cloth or polyester backing bonded with aluminum oxide, zirconia alumina, or ceramic grains in widths between 10 mm and 20 mm for precision grinding, weld removal, and surface finishing in confined work areas. The ceramic segment commands premium positioning due to extended life in high-pressure aerospace manufacturing applications, while aluminum oxide retains volume leadership across general-purpose metal fabrication and woodworking shops. Cloth backing dominates structural demand for its tear resistance in aggressive material removal, though polyester backing is gaining share in wet-finishing marine equipment workflows where dimensional stability under coolant exposure matters.
OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants shape abrasive belt manufacturing processes, pushing producers toward engineered ceramic grains that reduce respirable dust generation during use. ISO 9001 quality management and REACH chemical registration requirements in Europe further constrain raw material sourcing and cross-border supply qualification. Stakeholders must monitor evolving grit-size bundling economics and regulatory compliance costs to determine whether captive ceramic grain production or outsourced specialty sourcing delivers sustainable margin protection.
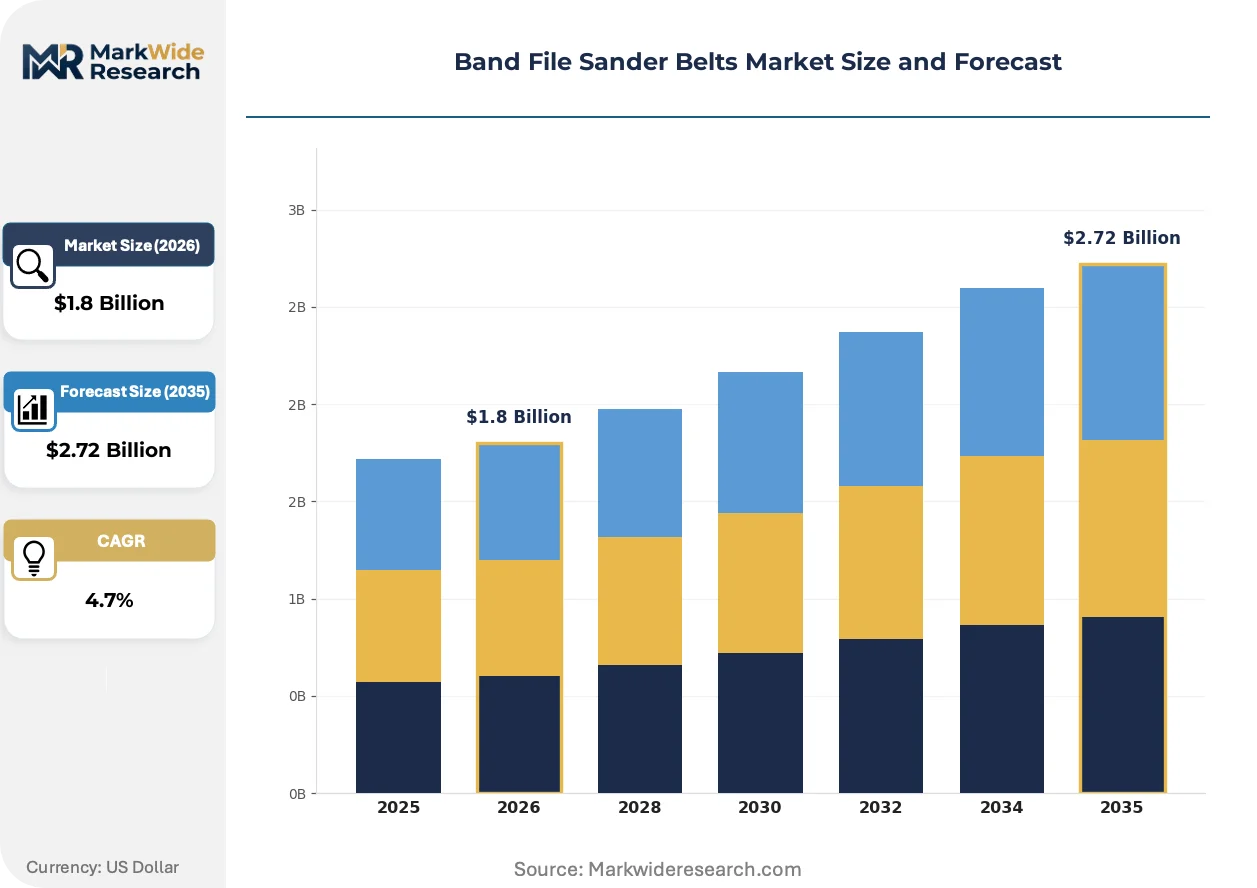
Market Dynamics
Modular grit-size bundling has hardened into the dominant procurement pattern, compressing single-SKU orders into configured assortments spanning coarse through extra fine grades. This structural shift forces abrasive suppliers to reconfigure inventory systems and pricing architectures around assortment economics rather than individual belt SKUs.
Growth Catalysts
- OSHA Silica Exposure Limits:Tighter respirable dust thresholds in US metal fabrication shops are accelerating replacement cycles toward engineered ceramic grains that generate less airborne particulate during aggressive grinding operations.
- Aerospace Manufacturing Concentration:Germany's industrial tooling clusters and automotive supply chains are driving premium ceramic belt consumption for precision weld removal in confined turbine component finishing.
- Wet-Finishing Marine Workflows:Polyester backing formulations are gaining specification share in shipyard maintenance operations where dimensional stability under coolant exposure outperforms traditional cloth alternatives.
Market Restraints
- Alumina Price Volatility:Bauxite refining capacity concentration in Guinea and Australia transmits raw material cost swings directly into aluminum oxide abrasive margins.
- REACH Chemical Registration:European Union substance authorization timelines extend 18-24 months for new ceramic grain chemistries, freezing formulation innovation cycles for EU-bound production.
- Flap Disc Substitution:Angle grinder mounted flap discs are displacing band file belts in open-area metal finishing where tool access constraints do not apply.
Strategic Opportunities
- India Manufacturing Expansion:The country's PLI scheme for capital goods is attracting precision tooling investments that will localize abrasive demand for automotive component finishing.
- Direct-to-Contractor Digital Channels:Specialized industrial distributors are building mobile-optimized procurement platforms that bypass traditional two-step distribution for small-lot MRO replenishment.
- EPA NESHAP Compliance Tailwinds:Hazardous air pollutant standards for abrasive manufacturing are favoring producers with in-house ceramic grain synthesis over outsourced resin-bonded imports.
Industry Challenges
- Ceramic Grain Synthesis Expertise:Sol-gel and seeded-gel production requires materials science PhD-level talent that abrasive manufacturers struggle to recruit against semiconductor and battery sector competition.
- ISO 9001 Certification Timelines:Quality management system audits for new production lines add 8-12 months to facility qualification, delaying regional supply expansion.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Band File Sander Belts Market Trends and Innovations
Abrasive grain engineering and backing material chemistry are undergoing simultaneous refinement, with ceramic formulations and polyester substrates advancing in parallel rather than sequential development cycles.
Ceramic grain microstructure engineering is converging with precision finishing requirements in aerospace turbine blade maintenance. Maintenance repair operations at Frankfurt and Toulouse aviation clusters are specifying seeded-gel alumina belts for controlled stock removal on nickel superalloy welds. This convergence is compressing the performance gap between premium ceramic and standard zirconia alumina in high-pressure applications.
REACH chemical authorization deadlines are forcing reformulation of phenolic resin binders used in belt construction. ECHA substance evaluation protocols now classify certain formaldehyde-based curing agents as Substances of Very High Concern, compelling German and Italian abrasive manufacturers to qualify bio-based alternatives. Metal fabrication end users in the EU are absorbing 12-15% material cost premiums during this transition period.
Assortment-based procurement contracts are displacing single-grit purchasing agreements among North American woodworking cooperatives. Regional buying groups now specify annual volume commitments across 40-60 SKU configurations rather than quarterly spot orders. This pattern is most visible in Pennsylvania and Ohio furniture manufacturing corridors where shared service cooperatives aggregate demand from 200-plus member shops.
Band File Sander Belts Market Segmentation
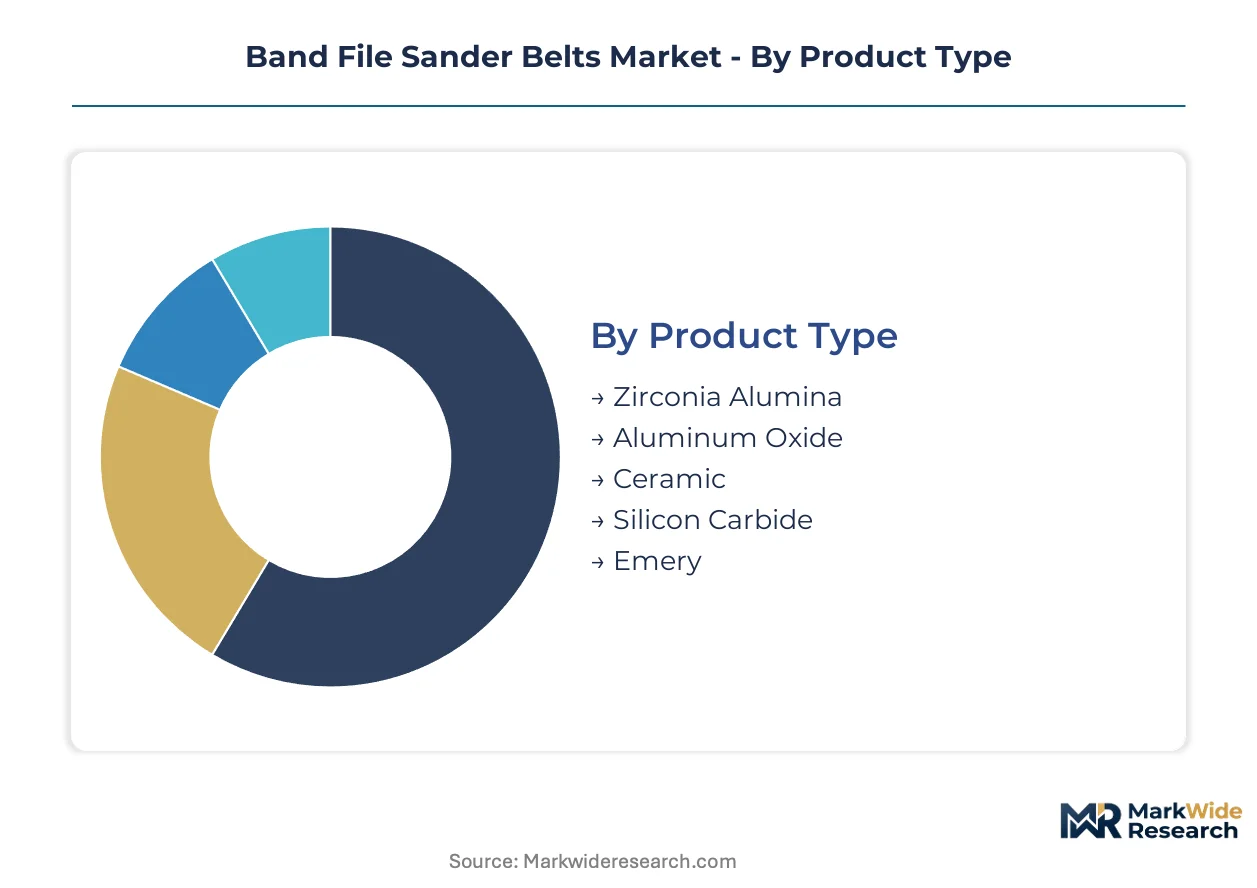
Segmentation in the band file sander belts market determines which abrasive formulations qualify for regulated aerospace workflows versus general-purpose metal fabrication. Certification requirements, backing material durability standards, and grit-size precision specifications create distinct procurement patterns across end-use verticals.
Product Type:
ISO 9001 quality management certification applies universally, while REACH chemical registration requirements in Europe constrain ceramic and zirconia alumina formulations differently than aluminum oxide alternatives.
- Ceramic:Engineered through sol-gel microstructure processes for extended life in high-pressure applications. Frankfurt and Toulouse aviation clusters specify seeded-gel alumina belts for nickel superalloy weld removal in turbine component maintenance, with EPA NESHAP compliance favoring in-house ceramic synthesis over outsourced resin-bonded imports.
- Aluminum Oxide:Retains volume leadership across general-purpose metal fabrication and woodworking shops despite bauxite refining cost volatility from Guinea and Australia capacity concentration. OSHA silica exposure limits are accelerating replacement cycles toward engineered alternatives in US fabrication facilities.
- Zirconia Alumina:Specialized formulations target aggressive material removal in tool and die operations.
- Silicon Carbide:Preferred for wet-finishing marine equipment workflows requiring dimensional stability.
- Emery:Legacy applications in precision hand-finishing operations with limited industrial scale.
Leading the category by volume: Aluminum Oxide. Growing fastest: Ceramic.
Backing Material:
Cost tier differentiation separates premium tear-resistant substrates from economy alternatives, with wet-finishing applications commanding material premiums.
- Cloth:Woven cotton or polyester-cotton blends deliver structural tear resistance for aggressive stock removal. German automotive supply chains and Pennsylvania furniture manufacturing corridors specify cloth-backed belts for continuous production environments where belt failure interrupts automated finishing lines.
- Polyester:Synthetic backing gains specification share in shipyard maintenance operations where dimensional stability under coolant exposure outperforms traditional cloth alternatives. Marine equipment end users in EU waters absorb 12-15% material cost premiums during REACH-mandated phenolic resin binder transitions.
- Paper:Economy positioning for light-duty woodworking and finishing applications with limited durability requirements.
- Film:Precision thickness control for ultra-fine grit finishing in aerospace component polishing.
- Fiber:Reinforced synthetic substrates for aggressive grinding in confined access metal fabrication.
Cloth backing dominates volume. Polyester climbs the fastest on marine workflow specification shifts.
Grit Size:
Application-driven procurement patterns concentrate demand in medium and coarse grades for stock removal, with fine grades specified for precision finishing workflows.
- Coarse:40-60 grit range for aggressive material removal in weld grinding and edge preparation. Metal fabrication shops in Ohio and Michigan specify coarse belts for structural steel processing where rapid stock removal precedes finer finishing stages.
- Medium:80-120 grit range bridges rough preparation and precision finishing in general-purpose workflows.
- Fine:150-220 grit range for surface preparation prior to coating or painting operations.
- Very Fine:240-400 grit range for precision finishing in aerospace component maintenance.
- Extra Fine:600+ grit range for final polishing and aesthetic finishing in woodworking and marine applications.
Medium grit commands the largest volume share. Extra Fine gains share fastest on modular bundling trends.
End User Industry:
Geographic concentration of demand varies sharply, with aerospace manufacturing clustering in specific aviation hubs while metal fabrication disperses across industrial corridors.
- Aerospace Manufacturing:Precision weld removal and surface finishing in confined turbine component access. Maintenance repair operations at Frankfurt, Toulouse, and Hamburg aviation clusters drive premium ceramic belt consumption with stringent OEM qualification requirements.
- Metal Fabrication:General-purpose grinding, deburring, and edge preparation across structural steel and component manufacturing. OSHA silica exposure limits in US shops are accelerating replacement cycles toward engineered ceramic grains that generate less respirable dust.
- Woodworking Shops:Surface finishing and edge treatment in furniture and cabinetry production.
- Marine Equipment:Wet-finishing workflows in shipyard maintenance and vessel component repair.
- Tool & Die:Precision grinding and finishing in mold and die manufacturing operations.
Metal Fabrication leads by volume. Aerospace Manufacturing shows the steepest expansion trajectory on precision finishing specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and industrial tooling clusters in Germany concentrate abrasive belt demand through targeted capital goods incentives and automotive supply chain density.
Germany
Frankfurt and Hamburg aviation clusters drive premium ceramic belt consumption for turbine component maintenance. REACH chemical registration through ECHA constrains new phenolic resin binder formulations. Baden-Württemberg automotive supply chains specify cloth-backed belts for continuous production environments.
United States
OSHA silica exposure limits accelerate replacement cycles toward engineered ceramic grains in metal fabrication. EPA National Emission Standards for Hazardous Air Pollutants favor in-house ceramic synthesis over resin-bonded imports. Ohio and Michigan structural steel processors specify coarse belts for rapid stock removal.
India
The PLI scheme for capital goods attracts precision tooling investments that localize abrasive demand. BIS quality standards govern abrasive product certification for domestic manufacturing. Maharashtra and Gujarat automotive component corridors expand finishing operations requiring medium and fine grit assortments.
China
GB standards and MIIT industrial policy guide abrasive manufacturing capacity expansion in coastal provinces. Dual carbon goals pressure producers toward lower-emission ceramic grain synthesis processes. Yangtze River Delta metal fabrication clusters consume volume-grade aluminum oxide belts for general-purpose grinding.
Japan
METI industrial competitiveness programs support precision abrasive development for aerospace and electronics finishing. JIS standards specify backing material durability and grit-size tolerances for regulated workflows. Nagoya-area automotive tooling manufacturers qualify ceramic belts for high-pressure superalloy applications.
Band File Sander Belts Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with broad abrasive portfolios, European pure-play specialists with ceramic formulation expertise, and Asian scale manufacturers serving volume-grade segments. Competitive moves concentrate on backward integration into ceramic grain synthesis and direct-to-contractor digital channel expansion.
Within the diversified conglomerate tier, 3M and Bosch exemplify portfolio breadth spanning abrasive systems, power tools, and industrial distribution. Norton Abrasives and Klingspor occupy positions as European specialists with differentiated ceramic and zirconia alumina formulations. These archetypes represent contrasting strategic bets on scale economies versus technical specialization in a market where REACH compliance and OSHA exposure limits reshape qualification requirements.
| Leading Market Players |
|---|
| 3M |
| Norton Abrasives |
| Klingspor |
| VSM Abrasives |
| Hermes Abrasives |
| Mirka |
| Bosch |
| Makita |
| Milwaukee Tool |
| Others |
Pricing and Supply Chain Analysis
Sol-gel ceramic grain synthesis expertise concentrates in Baden-Württemberg and Ohio industrial corridors, where materials science PhD-level talent scarcity widens the pricing spread between premium seeded-gel formulations and standard aluminum oxide alternatives.
Pricing Analysis
Short lead-time premiums of 15-20% apply to ceramic belt orders from Frankfurt aviation maintenance clusters requiring same-week turbine component turnaround. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant phenolic resin formulations from standard cloth-backed alternatives. Cost compression in aluminum oxide grades is intensifying because bauxite refining capacity concentration in Guinea and Australia transmits raw material volatility directly into margins. Metal fabrication shops in Ohio and Michigan show highest price sensitivity, while aerospace MRO operations at Toulouse and Hamburg absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
ISO 9001 certification and REACH chemical registration through ECHA gate qualified suppliers for EU-bound aerospace workflows, freezing out unqualified resin-bonded imports. Ceramic grain synthesis concentrates in Germany, the United States, and Japan, where sol-gel production capacity draws from bauxite feedstock processed in Guinea and Australia. Phenolic resin binder chemistry rests on formaldehyde supply chains facing ECHA Substances of Very High Concern reclassification. Single-source vulnerability runs through seeded-gel alumina precursor availability from specialized chemical processors. Distribution runs through industrial abrasives distributors and direct-to-contractor digital platforms serving small-lot MRO replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic grain synthesis capacity constraints prop pricing power for qualified producers, as ECHA registration timelines and OSHA silica exposure limits simultaneously compress supply availability and accelerate specification upgrades.
For Market Incumbents: Anchor defensive positioning through captive sol-gel production capacity in Germany or the United States, insulating margin structures from bauxite refining volatility and REACH compliance cost pass-through. Secure long-term phenolic resin binder supply agreements before ECHA authorization deadlines further constrain formulation alternatives. Prioritize ISO 9001 certification maintenance for facility expansions, as audit timelines add 8-12 months to regional supply qualification. For New Entrants and Emerging Players: The mid-tier pricing gap between premium ceramic and economy aluminum oxide creates white-space opportunity for zirconia alumina formulations targeting tool and die operations in India's Maharashtra automotive corridor. Target wet-finishing marine equipment workflows in EU waters where polyester backing specification shifts absorb 12-15% material cost premiums during REACH-mandated transitions. Pursue direct-to-contractor digital channel partnerships bypassing traditional two-step distribution for small-lot MRO replenishment in North American woodworking cooperatives. For Investors and Strategic Acquirers: Re-rating potential sits with European pure-play specialists with in-house ceramic formulation expertise given EPA NESHAP compliance tailwinds favoring domestic synthesis over resin-bonded imports. Long-term viability over the next decade hinges on backward integration into ceramic grain production rather than outsourced specialty sourcing. Monitor India PLI scheme capital goods investments as inflection indicator for localized abrasive demand generation in automotive component finishing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Grain Synthesis | Captive sol-gel production insulates margins from bauxite volatility and REACH compliance pass-through. |
| Direct-to-Contractor Digital Channel Expansion | Mobile-optimized procurement platforms bypass traditional distribution for small-lot MRO replenishment. |
| REACH-Compliant Phenolic Resin Reformulation | Bio-based binder alternatives qualify German and Italian manufacturers for EU aerospace workflows. |
| India Manufacturing Footprint Establishment | PLI scheme incentives localize supply for Maharashtra and Gujarat automotive component finishing demand. |
| Modular Grit-Size Bundling Configuration | Assortment economics align inventory systems with Pennsylvania and Ohio woodworking cooperative procurement patterns. |
Research Methodology
Document review covered trade association publications, customs records, and SEC filings from diversified industrial conglomerates, complemented by interviews with plant managers at metal fabrication facilities, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at abrasive manufacturers. Primary fieldwork engaged maintenance directors in Ohio and Michigan structural steel processing, aftermarket service heads at aviation clusters in Frankfurt and Toulouse, and supply planners at German automotive supply chains. Secondary validation drew from OSHA regulatory filings, EPA NESHAP compliance databases, ECHA substance registration records, and BIS quality standards documentation. Bottom-up demand modeling triangulated against top-down production capacity assessments across the analysis window.
Cross-referencing historical shipment data against expert panel input established volume and value outputs across product type, backing material, grit size, and end-use industry segmentation. Modeled dimensions included ceramic versus aluminum oxide versus zirconia alumina formulations, cloth versus polyester versus paper substrates, coarse through extra fine grades, and aerospace manufacturing versus metal fabrication versus woodworking shop applications. CAGRs were derived from regression analysis of replacement cycle acceleration patterns and specification upgrade trajectories. Forecast inputs incorporated OSHA silica exposure limit enforcement timelines and REACH chemical authorization deadline impacts on formulation availability.
Inputs from ECHA substance registration databases and OSHA enforcement records were available through the study window; gaps in real-time bauxite refining cost transmission data introduce uncertainty bands around aluminum oxide pricing projections. Forecasts reflect assumptions regarding PLI scheme implementation pace in India and dual carbon goal compliance trajectories in China. A model refresh is warranted upon material change in ECHA phenolic resin binder authorization status or OSHA respirable dust threshold enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.