
 Crimped Wire Brushes Market | 2026-2036
Crimped Wire Brushes Market Size, Share, and Industry Trends Forecast 2026-2036
Crimped Wire Brushes Market Outlook
Industrial distribution channels for abrasive consumables is rewriting how crimped wire brushes reach end users, with integrated supply platforms displacing traditional two-step distribution in North America and Western Europe. Weiler Abrasives leverages direct contractor relationships to sustain volume leadership in metalworking applications. Pferd competes through specialized product lines targeting precision surface preparation. Bosch extends its position via power tool OEM bundling that locks in brush attachment demand.
Crimped wire brushes consist of metal filaments mechanically secured within a ferrule or hub through a crimping process, with typical wire diameters ranging from 0.006 to 0.023 inches and operating speeds up to 20,000 RPM depending on brush configuration. These tools remove rust, paint, weld spatter, and scale from metal substrates while conforming to irregular surfaces better than knot-twist alternatives. Power brushes and wheel brushes dominate volume shipments to manufacturers and maintenance services, where automated and semi-automated surface preparation workflows generate recurring replacement demand. Handheld brushes retain margin strength among contractors and DIY enthusiasts despite slower growth, as premium ergonomic designs command price premiums in professional channels.
OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants shape product design by mandating reduced airborne particulate generation during surface preparation operations. REACH substance restrictions in Europe and evolving GB standards in China further complicate material selection for manufacturers serving multiple regulatory jurisdictions. Stakeholders must monitor how dual carbon goals in China and EU Green Deal procurement criteria redirect specification requirements toward longer-lasting brush designs that reduce consumable waste intensity.
Market Dynamics
Industrial distribution channels for abrasive consumables is rewriting how crimped wire brushes reach end users, with integrated supply platforms displacing traditional two-step distribution in North America and Western Europe. OSHA workplace safety standards and EPA metalworking effluent rules are tightening specification requirements for industrial abrasive tools.
Growth Catalysts
- Reshoring-driven replacement cycles:Metal fabrication shops across the United States are expanding brush procurement for weld cleaning and surface finishing operations as manufacturing capacity returns to domestic facilities.
- REACH substance restrictions:Evolving material compliance mandates in Europe are forcing manufacturers to reformulate brush compositions, creating specification upgrade demand across export-oriented production lines.
- Infrastructure refurbishment programs:Federal and state-level capital deployment for bridge, rail, and utility maintenance is sustaining tool replacement demand among contractor fleets.
Market Restraints
- Steel wire price volatility:Input cost swings for high-carbon and stainless steel filaments compress margin buffers for brush manufacturers without long-term supply contracts.
- Substitution by coated abrasives:Flap discs and fiber-backed sanding products capture light-duty surface preparation work previously assigned to wire brushes.
- OSHA silica exposure limits:Compliance-driven workflow modifications in metalworking shops reduce abrasive consumption intensity per square foot of surface treated.
Strategic Opportunities
- Robotics integration in automated surface preparation:Collaborative robot deployments in automotive and aerospace finishing lines create demand for precision-engineered brush configurations with consistent wear profiles.
- EU Green Deal procurement criteria:Public infrastructure tenders across Germany, France, and Italy now weight lifecycle tool durability, favoring premium brush designs that reduce consumable waste intensity.
- Direct-to-contractor digital platforms:Specialized industrial marketplaces are bypassing traditional two-step distribution, enabling margin capture and usage data collection from professional end users.
Industry Challenges
- Abrasive application engineering expertise:Shortage of technicians capable of matching brush specifications to substrate materials and automated equipment parameters slows adoption of advanced product lines.
- Dual carbon compliance documentation:Manufacturers serving both China and European Union markets must maintain parallel certification systems for carbon intensity reporting under divergent MEE and CSRD frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crimped Wire Brushes Market |
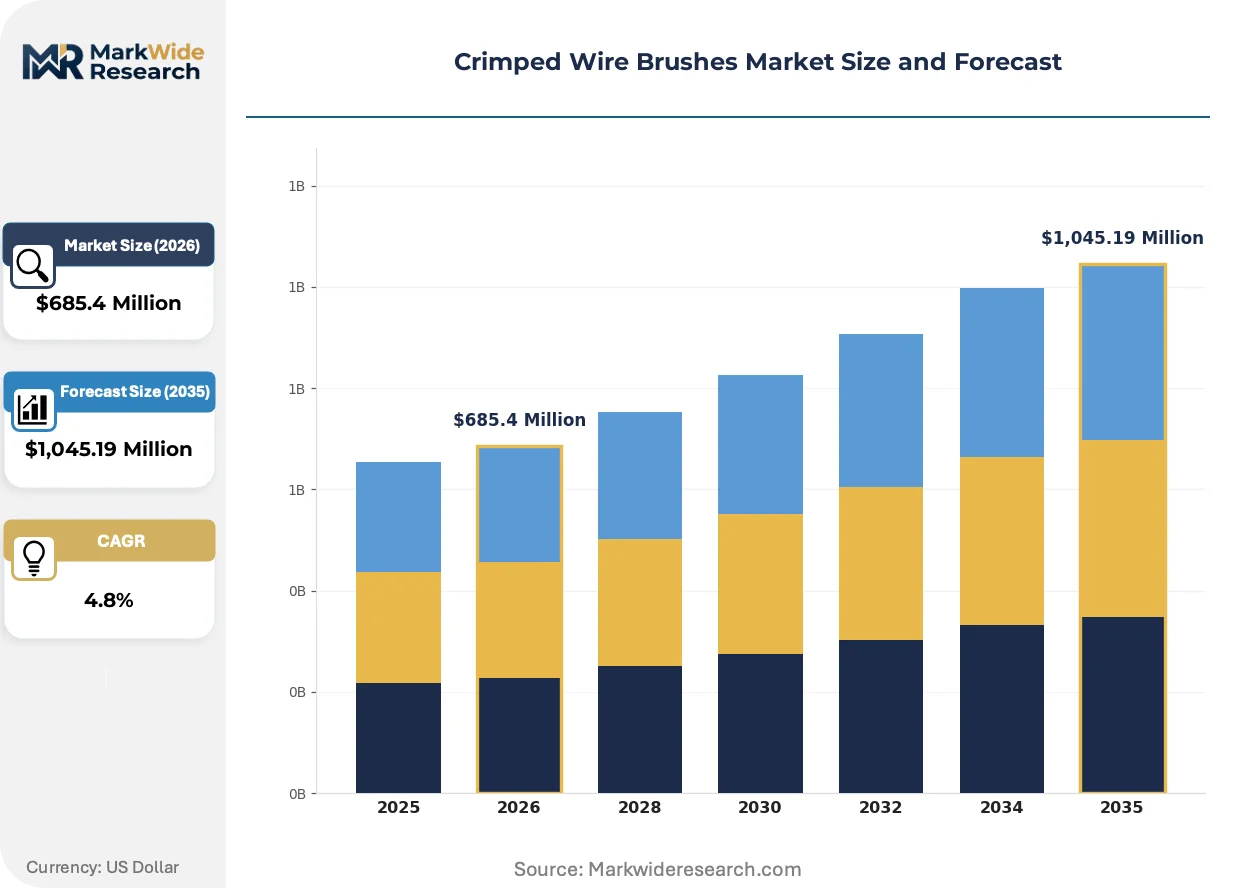
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Brushes, Power Brushes, Wheel Brushes, Cup Brushes Material: Stainless Steel, Brass, Nylon, Carbon Steel Application: Metal Fabrication, Woodworking, Automotive Cleaning, Surface Preparation End User: Manufacturers, Contractors, DIY Enthusiasts, Maintenance Services |
| Companies Covered | Osborn, Pferd, Weiler Abrasives, Bosch, 3M, Saint-Gobain Abrasives, Mill-Rose, Spiral Brushes, Brush Research Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crimped Wire Brushes Market Strategic Shifts
Digital supply chain integration and predictive maintenance systems are reshaping how brush consumption is forecasted and replenished in high-volume manufacturing environments. Three developments are restructuring competitive positioning.
Condition-monitoring sensors embedded in automated surface preparation equipment is virtualizing brush replacement scheduling. Automotive OEMs in Michigan and Bavaria now capture real-time wear data from robotic finishing cells. This capability compresses inventory carrying costs while locking in supplier relationships through integrated procurement platforms.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is tightening allowable particulate generation from metalworking operations. Fabrication shops in Ohio, Texas, and Pennsylvania are retrofitting extraction systems and specifying low-dust brush geometries. Power brush configurations with encapsulated wire designs capture volume share in compliance-sensitive verticals.
Integrated supply contracts now bundle abrasive consumables with capital equipment leases. Maintenance service providers in the Great Lakes industrial corridor are unbundling after-sales brush supply from original equipment vendor relationships. This procurement pattern shift favors distributors with logistics density and technical support capabilities over traditional manufacturer-direct channels.
Crimped Wire Brushes Market Segmentation
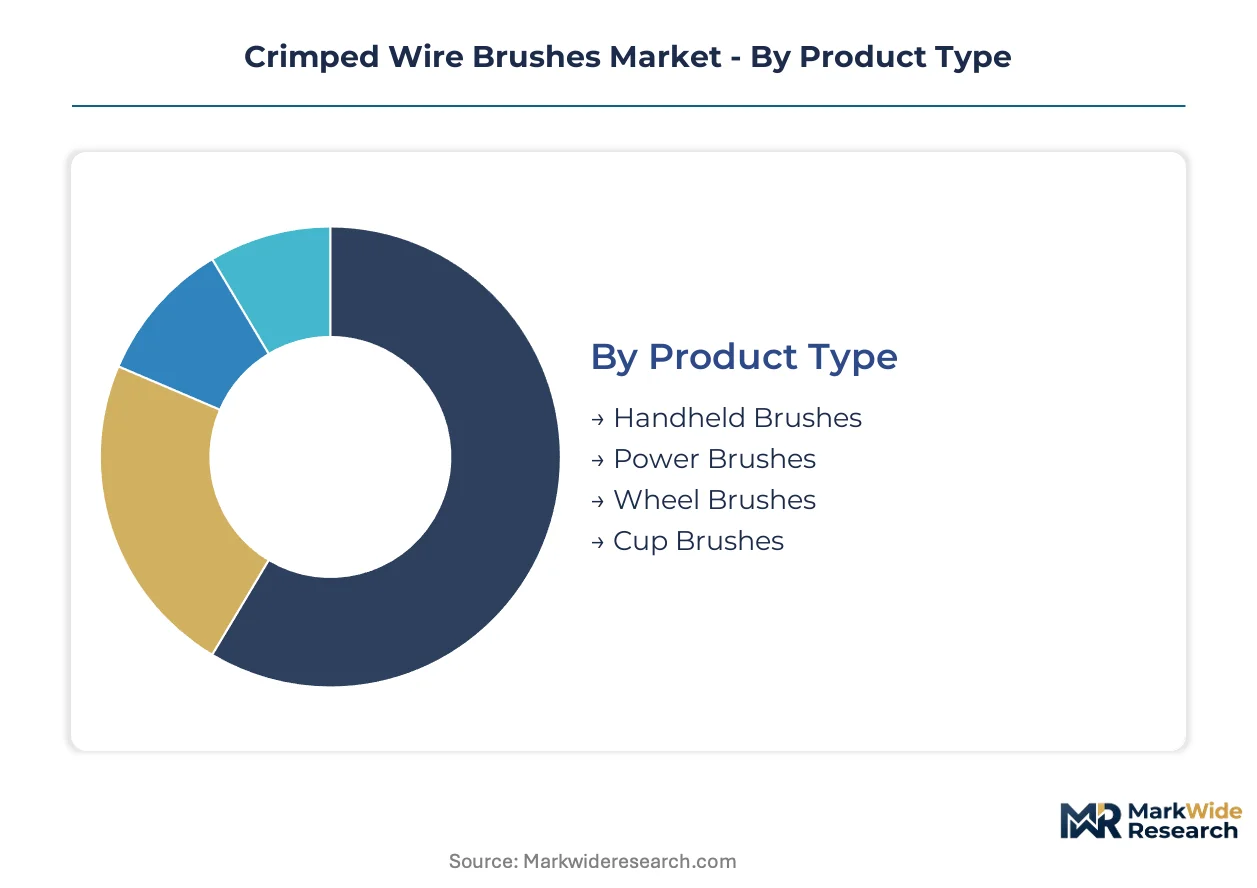
Crimped wire brush procurement patterns diverge sharply across product configurations and user workflows. Specification requirements for automated metalworking cells differ fundamentally from contractor fleet purchases. Material selection, brush geometry, and end-use intensity each create distinct margin profiles and replacement cycle dynamics.
Product Type:
Application intensity separates these configurations, with automated workflows demanding precision-engineered formats and manual operations prioritizing ergonomic handling.
- Power Brushes:Engineered for mounting on angle grinders and stationary equipment, these configurations handle aggressive material removal at operating speeds reaching 20,000 RPM. Demand concentrates in United States metal fabrication shops expanding weld cleaning capacity for reshoring manufacturing programs.
- Wheel Brushes:Circular ferrule designs with radially arranged filaments excel at edge deburring and surface finishing on irregular substrates. Automotive OEMs in Michigan and Bavaria specify these for robotic finishing cells where consistent wear profiles reduce unplanned downtime.
- Handheld Brushes:Manual formats with ergonomic grips serve spot cleaning and confined-space work. Premium designs command price premiums in professional contractor channels despite slower volume growth.
- Cup Brushes:Concave filament arrangements target corner cleaning and weld seam preparation in tight geometries. Maintenance services deploy these for infrastructure refurbishment fieldwork.
Power brushes hold installed capacity. Wheel brushes are rotating up the share rankings.
Material:
Substrate compatibility and corrosion resistance drive specification choices, with regulatory compliance layering additional selection constraints across export markets.
- Carbon Steel:High-tensile filaments deliver aggressive cutting action for heavy rust and scale removal on ferrous substrates. Metal fabrication shops in Ohio and Texas specify these for structural steel surface preparation where substrate damage tolerance permits.
- Stainless Steel:Corrosion-resistant compositions prevent contamination of stainless and aluminum workpieces during finishing. REACH substance restrictions in Europe are forcing reformulation verification across export-oriented production lines.
- Brass:Softer, non-sparking filaments suit hazardous environments and delicate substrates including brass and copper alloys. Marine maintenance contractors favor these for corrosion removal without galvanic damage.
- Nylon:Synthetic abrasive-impregnated filaments generate minimal sparking and suit light-duty cleaning on wood, plastics, and painted surfaces. Woodworking shops specify these for grain-raising and finish preparation.
Carbon steel dominates shipment volumes. Stainless steel is climbing the fastest on specification upgrade demand.
Application:
Surface treatment intensity varies dramatically, with industrial metalworking generating consumable replacement cycles an order of magnitude faster than intermittent maintenance use.
- Metal Fabrication:Weld cleaning, scale removal, and edge preparation consume brushes at the highest replacement frequency. OSHA silica exposure limits are reducing abrasive consumption intensity per square foot in United States fabrication shops.
- Surface Preparation:Coating removal and substrate profiling for protective systems demands consistent filament performance across large areas. EPA National Emission Standards for Hazardous Air Pollutants enforcement is retrofitting extraction systems in Pennsylvania and Ohio facilities.
- Automotive Cleaning:Engine bay detailing and undercarriage refurbishment uses lower-intensity brush configurations. Specialty detailers serving collector and restoration markets sustain premium pricing.
- Woodworking:Grain cleaning and distressing applications favor softer filament materials to prevent substrate damage. Custom furniture producers in North Carolina and Vermont specify nylon-impregnated designs.
Metal fabrication anchors volume demand. Surface preparation is expanding most quickly on infrastructure refurbishment programs.
End User:
Procurement sophistication separates these groups, with integrated manufacturers negotiating supply contracts while fragmented contractor fleets purchase through distribution.
- Manufacturers:High-volume automated and semi-automated operations generate recurring replacement demand with predictable consumption patterns. Predictive maintenance systems in Michigan automotive plants now virtualize brush replacement scheduling.
- Maintenance Services:Fleet-based operations serving infrastructure and industrial asset upkeep require logistics-responsive supply. Great Lakes corridor providers are unbundling after-sales brush supply from original equipment vendor relationships.
- Contractors:Project-based purchasing through industrial distribution favors ergonomic premium designs. Direct-to-contractor digital platforms are capturing usage data and margin previously held by two-step distribution.
- DIY Enthusiasts:Retail-channel purchasers drive minimal volume but validate brand positioning for professional product lines. Big-box hardware placement sustains awareness among future trade professionals.
Manufacturers hold contract volume. Maintenance services are gaining share fastest on infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States metal fabrication clusters where reshoring programs sustain premium procurement, while Chinese manufacturers compete on volume through cost-optimized production for export markets. This asymmetry shapes regional investment priorities and specification standards across the value chain.
United States
Domestic metal fabrication shops in Ohio, Texas, and Pennsylvania are expanding brush procurement for weld cleaning operations as manufacturing capacity returns from offshore locations. OSHA silica exposure limits and EPA National Emission Standards for Hazardous Air Pollutants enforcement are retrofitting extraction systems and mandating low-dust brush geometries. The Great Lakes industrial corridor anchors demand, where automotive OEMs in Michigan deploy predictive maintenance systems that virtualize brush replacement scheduling.
Germany
Automotive OEMs in Bavaria specify precision-engineered wheel brushes for robotic finishing cells where consistent wear profiles reduce unplanned downtime. EU Green Deal procurement criteria now weight lifecycle tool durability in public infrastructure tenders across Germany, France, and Italy. The Stuttgart and Munich manufacturing clusters drive specification upgrades toward longer-lasting designs that reduce consumable waste intensity.
China
Metalworking export production lines are reformulating brush compositions to satisfy REACH substance restrictions in European destination markets. Dual carbon goals under MEE frameworks and evolving GB standards complicate material selection for manufacturers serving multiple regulatory jurisdictions. The Yangtze River Delta and Pearl River Delta industrial zones concentrate production capacity for both domestic infrastructure deployment and export manufacturing.
India
Infrastructure refurbishment programs and expanding metal fabrication capacity are sustaining tool replacement demand among contractor fleets and maintenance services. BIS standards and DGFT export protocols shape product certification requirements for domestic and international market access. The Maharashtra and Gujarat industrial corridors concentrate procurement from manufacturing and maintenance service providers serving domestic capital goods production.
Japan
Precision surface preparation requirements in automotive and aerospace finishing lines create demand for engineered brush configurations with consistent wear profiles. METI industrial standards and JIS certification protocols maintain quality benchmarks for automated manufacturing equipment integration. The Nagoya and Osaka manufacturing clusters specify premium brush designs for high-reliability production workflows.
Crimped Wire Brushes Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream, supplying filament materials and ferrule assemblies to branded brush manufacturers. The vendor base organizes around three strategic archetypes: power tool OEMs bundling brush attachments, specialized abrasive manufacturers with direct contractor relationships, and integrated supply platforms displacing traditional distribution. Dominant competitive moves include M&A to secure filament supply chains and strategic partnerships embedding brush procurement into predictive maintenance platforms.
Among Germany-based specialists, Pferd exemplifies the precision-engineered product line archetype targeting surface preparation applications. Weiler Abrasives occupies a position within the direct contractor relationship tier, sustaining volume leadership through integrated supply platforms in North American metalworking channels. Bosch represents the power tool OEM bundling archetype, locking in brush attachment demand via equipment-integrated procurement relationships. These three anchors illustrate how competitive positioning stratifies across system integration, specialized engineering, and distribution control vectors.
| Leading Market Players |
|---|
| Osborn |
| Pferd |
| Weiler Abrasives |
| Bosch |
| 3M |
| Saint-Gobain Abrasives |
| Mill-Rose |
| Spiral Brushes |
| Brush Research Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Steel wire price volatility determines both the spread between configured-to-order and standard catalog pricing and the geographic concentration of filament sourcing. Manufacturers without long-term supply contracts face margin compression that forces tiered pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Configured-to-order pricing for precision-engineered wheel brushes commands 40-60% premiums over standard power brush catalog listings. Price differentiation rests on certification grade (OSHA-compliant low-dust geometries) and volume scale (automotive OEM blanket orders vs. contractor spot purchases). Cost compression in standard carbon steel configurations is intensifying because of scrap metal input volatility. Maintenance services serving infrastructure fleets exhibit highest price sensitivity, while robotic finishing cell operators prioritize wear consistency over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for ferrule assemblies and crimping operations centers on China, Germany, and the United States. High-carbon steel filaments draw from integrated mills in Ohio and Pennsylvania, while stainless steel wire sources from European specialty producers. Single-source vulnerability exists for precision crimping equipment used in automated brush production. Distribution runs through integrated supply platforms displacing traditional two-step industrial distribution in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as reshoring-driven demand splits between automated manufacturing specifications and contractor fleet procurement patterns. Robotics integration in surface preparation creates distinct performance tiers that favor specialized entrants over generalist suppliers.
For Market Incumbents: Build predictive maintenance platform integration as the primary moat against aftermarket unbundling. Incumbents should deepen backward integration into high-tensile filament production to secure margin buffers against steel price swings. Certification investment in OSHA-compliant low-dust geometries locks in automotive OEM specification control.
For New Entrants and Emerging Players: Direct-to-contractor digital platforms in the Great Lakes industrial corridor represent the most penetrable entry point for bypassing established distribution relationships. White-space exists in EU Green Deal-compliant brush designs for German and Italian public infrastructure tenders. Go-to-market leverage rests on usage data collection enabling predictive replenishment services.
For Investors and Strategic Acquirers: EPA National Emission Standards enforcement reshapes the acquisition landscape toward low-dust brush technology specialists. Long-term viability favors targets with robotics integration capabilities and carbon intensity documentation systems serving dual MEE and CSRD frameworks. Watch for OSHA silica rule expansion into additional metalworking verticals as the inflection signal for specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filament Production | Captive supply of high-carbon steel wire insulates margin buffers from scrap metal volatility. |
| Predictive Maintenance Platform Partnership | Integration with automotive OEM robotic finishing cells locks in recurring replacement demand. |
| EU Green Deal Certification Program | Lifecycle durability documentation captures German and Italian public infrastructure tender preference. |
| Direct-to-Contractor Digital Marketplace | Bypassing traditional distribution captures usage data and margin from professional end users. |
| Robotics-Engineered Brush Configuration | Consistent wear profiles reduce unplanned downtime in Michigan and Bavaria automotive finishing lines. |
Study Parameters
Desk research of trade association publications, customs filings, and regulatory enforcement databases preceded structured interviews with plant engineers, maintenance directors at metal fabrication shops, procurement leads for automotive OEMs, and aftermarket service heads at industrial distributors. Primary fieldwork combined telephone and video interviews with technical validation against OSHA compliance documentation and EPA emission standard filings. Bottom-up brush consumption estimates triangulated against top-down metalworking capacity expansion projections.
Forecast assumptions held fixed the regulatory enforcement trajectory for silica exposure limits and carbon intensity reporting frameworks while varying reshoring velocity and infrastructure deployment timing across the analysis window. Segmentation modeling incorporated product configuration, filament material, application intensity, and end-user procurement sophistication dimensions. CAGRs derived from replacement cycle analysis calibrated to automated equipment utilization rates and contractor fleet activity indices.
Practitioners should monitor steel wire futures pricing, EPA enforcement action frequency, and robotics adoption rates in automotive finishing for early signals of forecast revision. Quarterly review of OSHA regulatory dockets, EU Green Deal tender award patterns, and reshoring announcement pipelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Welding Consumables Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Stainless Steel Cable Ties Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Colored Hard PU Foam Market