
 Steel Wire Rope and Plastic Rope Market | 2026-2036
Steel Wire Rope and Plastic Rope Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Wire Rope and Plastic Rope Market Outlook
Offshore energy contractors are unwinding decades of steel-wire dominance in favor of high-modulus polyethylene and aramid fiber ropes. Usha Martin anchors its position through backward integration into wire rod and specialized alloy production for mining and crane applications. TEUFELBERGER differentiates via advanced plasma rope technology and synthetic fiber braiding systems for maritime and utility sectors.
Steel wire rope and plastic rope encompass load-bearing flexible cables constructed from multiple strands of metal wires or polymer fibers twisted around a central core, with tensile strengths ranging from 1,770 to 2,160 N/mm² for steel variants and specific gravity below 1.0 for synthetic alternatives, manufactured through processes of wire drawing, stranding, closing, and plastic extrusion to serve lifting, mooring, towing, and suspension functions across heavy industry. The rope type dimension shows steel wire rope occupying the largest revenue share due to entrenched infrastructure specifications, while plastic rope captures the fastest expansion as ports and vessels substitute synthetics for corrosion resistance and weight reduction. Application segmentation reveals marine and construction as the twin demand pillars, with mining trailing as a mature replacement-driven segment where margin pools concentrate in specialized corrosion-resistant and high-fatigue product grades.
OSHA governs worker-safety load limits and inspection intervals for crane and hoist ropes in US industrial settings, while the EU Machinery Directive and CE marking enforce minimum breaking strength and traceability standards for rope systems sold across European member states. China's SAMR administers GB standards for steel wire rope dimensional tolerances and plastic rope UV-resistance testing protocols. Stakeholders must monitor evolving decarbonization mandates in shipping and renewable energy installation standards that will determine material substitution timelines and certification requirements for next-generation rope procurement.
Market Dynamics
Offshore wind farm developers are unwinding decades of steel-wire dominance in favor of high-modulus polyethylene and aramid fiber ropes, forcing rope manufacturers to reconfigure production lines and certification protocols around synthetic specifications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases is accelerating marine sector procurement of synthetic lifting lines that eliminate corrosion-prone steel components in subsea environments.
- Port modernization:China's SAMR-backed infrastructure expansion is driving heavy-lift rope consumption as automated container terminals require lighter, fatigue-resistant mooring systems.
- Aramid fiber braiding:Advanced plasma rope technology is opening utility sector applications where dielectric properties and weight reduction justify premium positioning over conventional steel.
Market Restraints
- Alloy input volatility:Specialized wire rod prices fluctuate with mining capex cycles, compressing margins for steel rope producers locked into long-term infrastructure contracts.
- REACH compliance costs:European chemical substance registration requirements are reshaping material specifications, adding certification overhead for synthetic rope manufacturers serving marine and industrial buyers.
- Technical limitation:Synthetic ropes exhibit creep deformation under sustained static loads, restricting their substitution in permanent suspension applications where steel maintains specification lock-in.
Strategic Opportunities
- Floating offshore wind:Dynamic cable support systems for deep-water turbines represent an emerging application where fatigue-resistant synthetics command specification preference.
- India's port privatization:Greenfield container terminal development under the Sagarmala initiative creates underpenetrated demand for corrosion-resistant mooring lines in tropical climates.
- CE marking convergence:Machinery Directive traceability mandates are consolidating procurement toward certified suppliers, rewarding rope manufacturers with integrated testing laboratories.
Industry Challenges
- Certification timeline compression:DNV-ST-N001 type approval for offshore lifting equipment now requires accelerated cyclic bending test protocols that strain laboratory capacity.
- Skill bifurcation:Synthetic rope splicing and inspection demands polymer chemistry expertise distinct from traditional wire rope metallurgy, creating workforce transition friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Wire Rope and Plastic Rope Market |
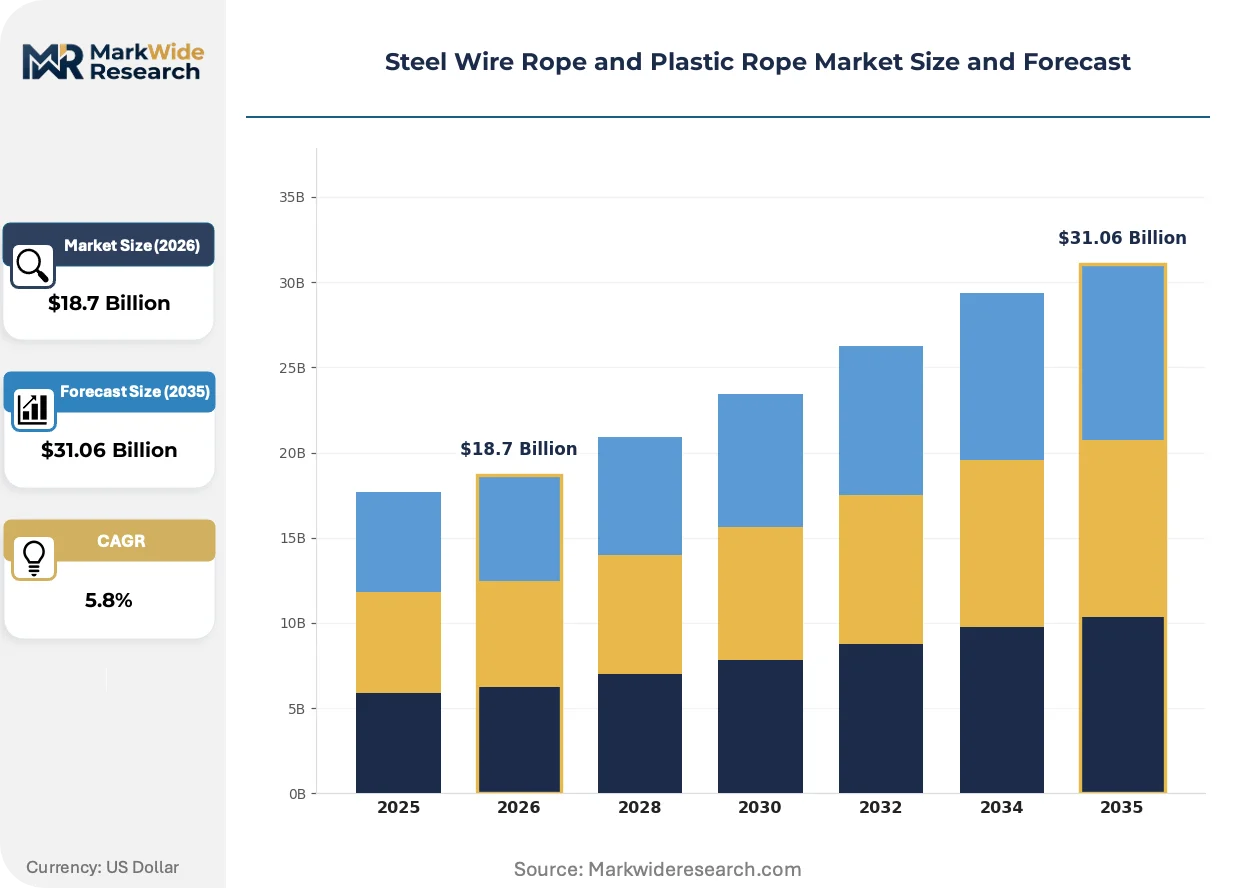
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rope Type: Steel Wire Rope, Plastic Rope, Composite Rope, Specialty Rope Application: Construction, Marine, Mining, Industrial End User: Aerospace, Oil & Gas, Utilities, Agriculture Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra Large Diameter |
| Companies Covered | Usha Martin, Tokyo Rope Mfg. Co., Ltd., Bekaert, Pfeifer Group, Bridon-Bekaert, WireCo World Group, TEUFELBERGER, Samson Rope Technologies, Kiswire Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Wire Rope and Plastic Rope Market Strategic Shifts
Material science breakthroughs and regulatory chemistry constraints are converging to restructure rope procurement specifications across marine, energy, and heavy infrastructure verticals.
High-modulus polyethylene (HMPE) rope is decomposing the traditional steel-wire hierarchy in offshore crane operations. North Sea wind installation vessels now specify 12-strand braided HMPE for primary lifting lines, cutting topside weight by eighty percent versus wire rope equivalents. The structural consequence is compressing steel rope manufacturers into specialized mining and permanent suspension niches where creep resistance and abrasion tolerance favor metal.
REACH authorization requirements are forcing reformulation of polymer coatings and core impregnants used in marine-grade synthetic ropes. ECHA's expanding candidate list of substances of very high concern now captures several flame retardants and UV stabilizers common in aramid rope production. European rope distributors are responding by consolidating supplier bases toward manufacturers with in-house toxicology dossier capabilities.
Buyer organizations are unbundling rope supply from integrated crane maintenance contracts, creating direct procurement channels between end-users and specialized rope manufacturers. Offshore energy contractors now issue standalone lifting line tenders with performance-based replacement intervals rather than accepting OEM-specified packages. This pattern is most visible in the North Sea and Gulf of Mexico, where vessel operators maintain dedicated rope inspection teams and inventory positions.
Steel Wire Rope and Plastic Rope Market Segmentation
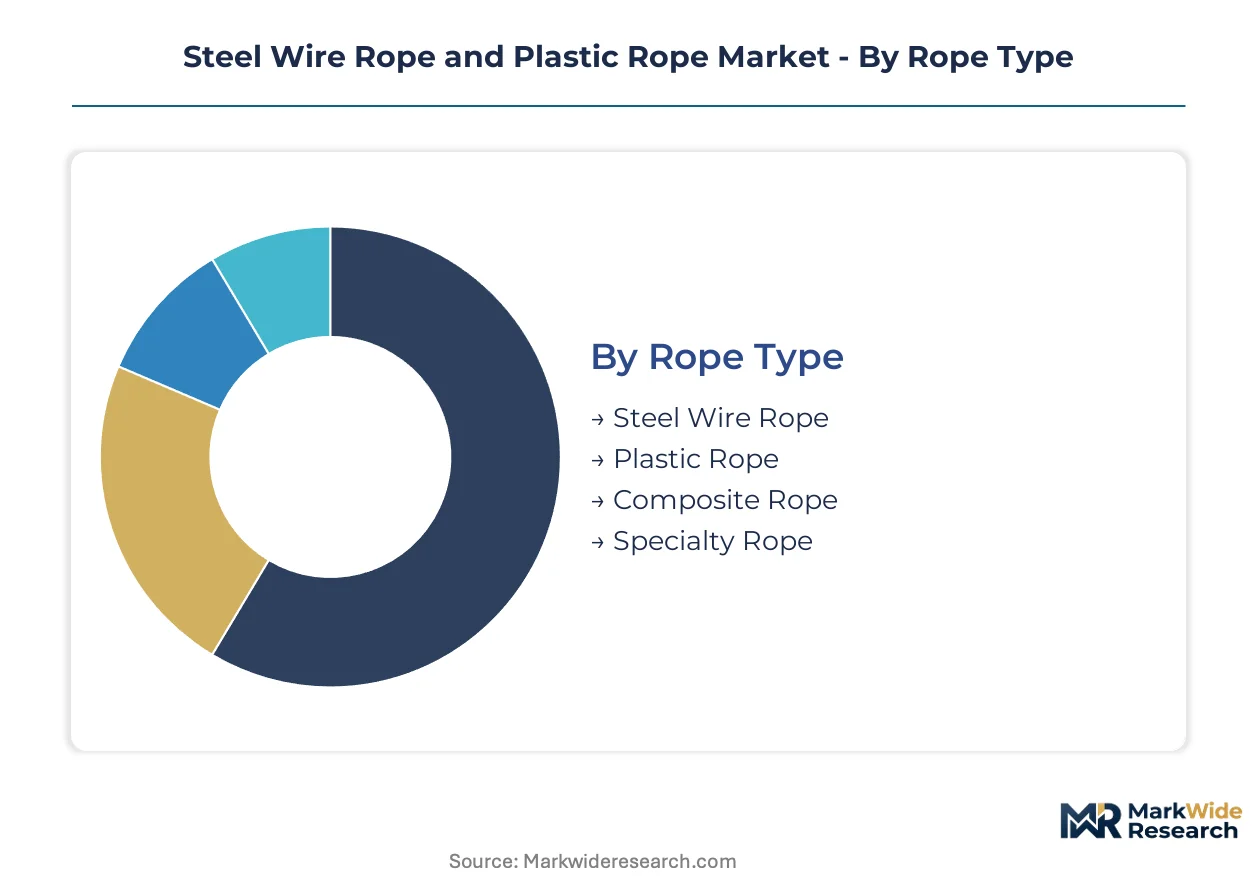
Rope procurement specifications diverge sharply across end-use environments, with regulatory chemistry constraints and load-cycle requirements dictating material selection. Segmentation reveals how certification protocols and performance standards fragment demand into distinct technical tiers with asymmetric margin structures.
Rope Type:
REACH authorization and EU F-Gas Regulation compliance costs reshape competitive economics across material categories, favoring suppliers with in-house toxicology dossier capabilities.
- Steel Wire Rope:Multi-strand cables of carbon or alloy steel wires deliver tensile strengths between 1,770 and 2,160 N/mm² for permanent suspension and heavy-lift infrastructure. Mining operations in Australia and crane OEMs in Germany specify these for abrasion tolerance and creep resistance under sustained static loads, though alloy input volatility compresses margins on long-term contracts.
- Plastic Rope:High-modulus polyethylene and aramid fiber constructions achieve specific gravity below 1.0 with dielectric properties suited to offshore environments. North Sea wind installation vessels and China's automated container terminals drive procurement for weight reduction and corrosion elimination, with DNV-ST-N001 certification now requiring accelerated cyclic bending protocols.
- Composite Rope:Hybrid steel-synthetic cores balance fatigue resistance with weight savings for utility sector applications.
- Specialty Rope:Plasma-treated and coated variants serve nuclear and aerospace inspection regimes with extreme temperature tolerances.
Established volume favors Steel Wire Rope; emerging adoption favors Plastic Rope.
Application:
Load-cycle intensity and environmental exposure separate margin pools, with marine and construction commanding premium positioning over replacement-driven mining.
- Construction:Tower cranes and suspended platforms require rotation-resistant and non-rotating rope configurations with mandated OSHA inspection intervals. High-rise development in the UAE and infrastructure rehabilitation in Japan concentrate demand for certified lifting lines with traceable heat numbers.
- Marine:Mooring, towing, and offshore lifting operations specify synthetic lines for dynamic positioning systems where weight reduction improves vessel stability. EU F-Gas phasedown accelerates substitution away from corrosion-prone steel in subsea environments, though creep deformation restricts permanent anchoring applications.
- Mining:Dragline and shovel hoist ropes face extreme abrasion in open-pit operations across Chile and South Africa.
- Industrial:Overhead cranes and conveyor systems in manufacturing plants require standardized duty classifications.
Marine applications are climbing the fastest; mining remains a mature replacement cycle.
End User:
Procurement centralization varies by sector sophistication, with oil and gas majors and utilities unbundling rope supply from integrated maintenance contracts.
- Oil & Gas:Offshore platform drilling lines and subsea installation ropes must survive corrosive hydrocarbon environments. Gulf of Mexico operators and North Sea contractors now issue standalone lifting line tenders with performance-based replacement intervals, bypassing OEM-specified packages.
- Utilities:Transmission line stringing and tower erection demand dielectric properties for live-line work. TEUFELBERGER's plasma rope technology addresses this segment where aramid fiber braiding justifies premium positioning.
- Aerospace:Control cables and cargo restraint systems require traceable metallurgy and non-destructive testing documentation.
- Agriculture:Baling and irrigation systems utilize commodity-grade synthetic ropes with UV-stabilization requirements.
Direct procurement favors Oil & Gas; distributor channels favor Agriculture.
Diameter:
Manufacturing scale economies concentrate in mid-range diameters, while extreme sizes require specialized stranding equipment and custom alloy formulations.
- Large Diameter:Strands exceeding standard construction ranges serve heavy-lift cranes and deep-water mooring systems. China's port modernization under SAMR-backed infrastructure expansion drives consumption of 60mm+ ropes for automated container terminals requiring fatigue-resistant systems.
- Medium Diameter:General-purpose industrial and marine applications dominate production volumes with standardized GB and JIS tolerances.
- Small Diameter:Precision instruments and control cables demand tight dimensional tolerances.
- Extra Large Diameter:Custom-engineered mining draglines and offshore installation vessels require dedicated closing lines and extended lead times.
Production scale centers on Medium Diameter; specification complexity rises with Extra Large Diameter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningbo-Zhoushan Port anchors Asia-Pacific demand through automated container terminal expansion requiring fatigue-resistant mooring systems. Germany's Hamburg and Bremerhaven port clusters drive European specification standards for offshore wind installation vessels. The United States Gulf Coast offshore energy corridor concentrates heavy-lift procurement for subsea construction.
China
Port modernization at Shanghai Yangshan and Shenzhen Shekou drives heavy-lift rope consumption for automated gantry cranes. SAMR-administered GB standards enforce dimensional tolerances and UV-resistance testing protocols for synthetic lines. Jiangsu and Zhejiang provinces concentrate shipbuilding expansion where high-modulus polyethylene substitution accelerates.
Germany
Offshore wind installation vessels operating from Cuxhaven and Emden specify DNV-ST-N001 certified synthetic lifting lines. REACH compliance and EU F-Gas Regulation reshape material specifications for marine procurement. The Ruhr industrial corridor maintains steel wire rope demand for crane OEMs and mining equipment manufacturers.
United States
Gulf of Mexico offshore platforms and wind lease areas drive procurement of corrosion-resistant mooring systems. OSHA governs crane and hoist rope inspection intervals for industrial settings. Houston and New Orleans anchor the offshore energy supply chain where contractors unbundle rope supply from integrated maintenance contracts.
Japan
Port infrastructure rehabilitation and seismic-resistant construction specifications sustain demand for rotation-resistant rope configurations. METI and JIS standards govern dimensional tolerances and fatigue testing protocols. The Kansai region around Osaka and Kobe concentrates maritime engineering procurement for synthetic line adoption.
India
Sagarmala initiative port privatization creates demand for corrosion-resistant mooring lines at greenfield container terminals. BIS standards and coastal regulation zone clearances shape procurement specifications. Gujarat and Maharashtra coastal zones concentrate heavy-lift infrastructure development where tropical climate conditions favor synthetic alternatives.
Steel Wire Rope and Plastic Rope Market Competitive Environment
Concentration sits with integrated wire rod producers and specialized synthetic fiber braiders serving distinct specification tiers. Steel wire rope manufacturing retains scale advantages in mining and permanent suspension applications where creep resistance favors metal. Three archetypes dominate: backward-integrated alloy producers, advanced polymer specialists, and hybrid composite engineers. Competitive moves center on certification laboratory expansion and geographic proximity to offshore wind installation hubs.
Among integrated steel wire producers, Usha Martin anchors the mining and crane specification tier through captive wire rod supply. Tokyo Rope Mfg. Co., Ltd. and Kiswire Ltd. represent East Asian fabricators serving maritime and industrial segments with JIS-certified production systems. TEUFELBERGER occupies a position within the synthetic specialization tier where plasma rope technology and aramid fiber braiding address utility sector dielectric requirements. These three exemplify how geographic origin and structural integration determine competitive positioning across material categories.
| Leading Market Players |
|---|
| Usha Martin |
| Tokyo Rope Mfg. Co., Ltd. |
| Bekaert |
| Pfeifer Group |
| Bridon-Bekaert |
| WireCo World Group |
| TEUFELBERGER |
| Samson Rope Technologies |
| Kiswire Ltd. |
| Others |
Value Chain & Pricing Dynamics
DNV-ST-N001 certification gates both supplier qualification and price differentiation in offshore lifting lines, compressing procurement toward laboratories with accelerated cyclic bending protocols while segmenting rope manufacturers into certified premium tiers and uncertified commodity suppliers.
Pricing Analysis
Volume-discount tiering structures separate DNV-certified plasma rope manufacturers from uncertified commodity braiders, with certification grade and alloy specification driving price differentiation. Cost compression in standard-grade steel wire rope is intensifying because alloy input volatility and long-term mining contracts lock in margins. Offshore wind contractors demonstrate lowest price sensitivity, accepting premium positioning for fatigue-resistant synthetics, while agriculture and general industrial buyers concentrate procurement on economy-tier UV-stabilized synthetics.
Supply Chain Analysis
China and Germany anchor wire rod and specialized alloy production for mining and crane applications, while Austria and the United States concentrate plasma rope technology and aramid fiber braiding systems. Raw material dependencies center on high-carbon wire rod, high-modulus polyethylene resin, and aramid fiber feedstock. Single-source vulnerability concentrates in DNV-certified testing laboratory capacity, where accelerated approval timelines strain throughput. Distribution runs through direct procurement channels between offshore energy contractors and specialized manufacturers, bypassing traditional OEM-integrated maintenance packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from unbundling of rope supply from integrated crane maintenance contracts, as offshore energy contractors issue standalone lifting line tenders with performance-based replacement intervals.
For Market Incumbents: Shield mining and permanent suspension market share through captive wire rod supply and specialized corrosion-resistant alloy formulations, countering high-modulus polyethylene substitution in offshore applications. Prioritize laboratory certification expansion to capture DNV-ST-N001 type approval bottleneck. For New Entrants and Emerging Players: DNV-ST-N001 fast-track partnerships with established testing laboratories open procurement channels to North Sea and Gulf of Mexico offshore wind installation vessels. Target India's Sagarmala port privatization initiative for greenfield container terminal mooring systems, leveraging tropical climate corrosion resistance as entry wedge. Pursue direct tender participation against OEM-specified packages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized rope manufacturing divisions lacking in-house toxicology dossier capabilities for REACH compliance. Five-to-ten year viability favors synthetic specialization over steel wire consolidation, with material substitution timelines in floating offshore wind as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Expansion | DNV-ST-N001 approval capacity constraints compress procurement toward certified suppliers with in-house testing. |
| Backward Integration into Wire Rod | Usha Martin's captive alloy production anchors margin defense against volatile mining capex cycles. |
| Synthetic Fiber Braiding Scale-Up | TEUFELBERGER's plasma rope technology addresses utility sector dielectric requirements with premium positioning. |
| Direct Procurement Channel Development | Offshore contractors unbundling rope supply from OEM packages rewards manufacturers with inspection team relationships. |
| REACH Compliance Dossier Investment | ECHA substance authorization requirements consolidate European marine procurement toward toxicology-capable suppliers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with offshore wind installation vessel operators, port authority procurement directors, mining maintenance supervisors, crane OEM specification engineers, and synthetic rope laboratory certification managers. Secondary validation drew from DNV type approval registries, SAMR GB standard publications, ECHA REACH authorization databases, and customs trade data for wire rod and high-modulus polyethylene resin. Bottom-up volume triangulation across rope diameter, material grade, and end-use application was cross-checked against top-down market sizing through industry association production statistics.
Across the analysis window, projections integrated rope type substitution dynamics, regulatory chemistry constraint timelines, and port modernization capex cycles. Segmentation modeling captured material category, application intensity, end-user procurement centralization, and diameter specification tier. CAGRs were derived from weighted average of historical replacement cycle compression and emerging adoption curve slopes for synthetic alternatives, with alloy price volatility and certification backlog duration as sensitivity inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained EU F-Gas Regulation phasedown and continued offshore wind installation vessel fleet expansion; material deviation in synthetic rope creep resistance breakthroughs or steel alloy cost spikes would warrant model refresh. Recalibration cycles align with material shifts in REACH candidate list expansions and floating offshore wind commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
High Purity Quartz Market
Industrial Materials
Mesh Nozzle Plates Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Fly Ash Market
Industrial Materials
US Industrial Fasteners Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Asia Pacific Expanded Polyethylene (EPE) Foam Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Metal Based Safety Gratings Market