
 Precision Stainless Steel Market | 2026-2036
Precision Stainless Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Stainless Steel Market Intelligence
Capital-intensity divergence between integrated blast-furnace operators and electric-arc specialists is bifurcating competitive returns in precision stainless steel. Nippon Steel leverages captive raw material streams to sustain margin stability across high-nickel grades. Outokumpu differentiates through cold-rolling mastery in austenitic strip for European medical OEMs. POSCO anchors volume leadership in Asian precision coil through continuous annealing scale.
Precision stainless steel denotes alloyed ferrous material manufactured to tight dimensional tolerances, typically within 0.05 mm thickness variance, with controlled chromium content exceeding 10.5 percent to impart corrosion resistance. Flat Products command the largest revenue pool where surface finish consistency determines qualification for semiconductor processing equipment. Medical Devices represents the fastest-growing end-use channel as surgical instrument OEMs migrate toward 316LVM vacuum-arc remelted grades for implantable applications. Grade 304 retains volume dominance in food processing contact surfaces where NSF/3A sanitary standards apply.
FDA enforces material traceability through 21 CFR Part 820 quality system regulations for medical-grade stainless inputs. ECHA administers REACH substance restrictions affecting nickel release thresholds in consumer-touch applications. Japan's METI coordinates JIS standards revision for precision strip used in hydrogen infrastructure seals. Stakeholders must monitor alloy surcharge volatility and regulatory divergence between medical and food-grade certification pathways.
Market Dynamics
Material traceability mandates from FDA and ECHA are compressing supplier qualification timelines while simultaneously extending audit cycles, forcing precision stainless steel producers to choose between compliance infrastructure investment or customer base attrition in regulated end-uses.
Growth Catalysts
- Medical Device Migration:Surgical instrument OEMs are accelerating qualification of 316LVM vacuum-arc remelted grades for implantable applications, tightening material specifications across the supply base.
- REACH Nickel Thresholds:ECHA substance restrictions on nickel release in consumer-touch applications are disqualifying conventional grades and creating premium positioning for controlled-release alloys.
- German Industrial Corridor Concentration:Demand clustering around Düsseldorf and Essen is pulling cold-rolling capacity expansion toward Rhine-Ruhr logistics hubs.
Market Restraints
- Nickel Surcharge Volatility:London Metal Exchange nickel price swings transmit directly to high-austenitic grade quotations, destabilizing contract pricing for medical OEMs locked into multi-year supply agreements.
- Blast Furnace Concentration:Integrated operators in East Asia control captive ore-to-strip production, limiting electric-arc specialists' access to competitively priced ferrochrome and refined nickel units.
- 316LVM Capacity Scarcity:Vacuum-arc remelt furnace availability constrains surgical-grade output expansion, with current installed base concentrated among three qualified suppliers.
Strategic Opportunities
- Hydrogen Infrastructure Seals:Japan's METI-coordinated JIS standards revision for precision strip in high-pressure hydrogen containment creates first-mover positioning for fatigue-resistant austenitic grades.
- Semiconductor Equipment Surfaces:Ultra-high-purity 316L with sub-5 ppm sulfur content is penetrating wafer processing chamber fabrication as chip fabrication node sizes contract below 3nm.
- Direct Mill-to-OEM Platforms:Digital order-to-delivery systems are disintermediating traditional steel service centers for qualified medical device manufacturers with certified internal metallurgy labs.
Industry Challenges
- Vacuum Metallurgy Talent Scarcity:Qualified VAR furnace operators and remelt process engineers command premium compensation, constraining capacity expansion timelines for surgical-grade producers.
- Dual Certification Complexity:Simultaneous FDA 21 CFR Part 820 and ISO 13485 compliance for medical-grade strip requires parallel quality system maintenance, extending qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Stainless Steel Market |
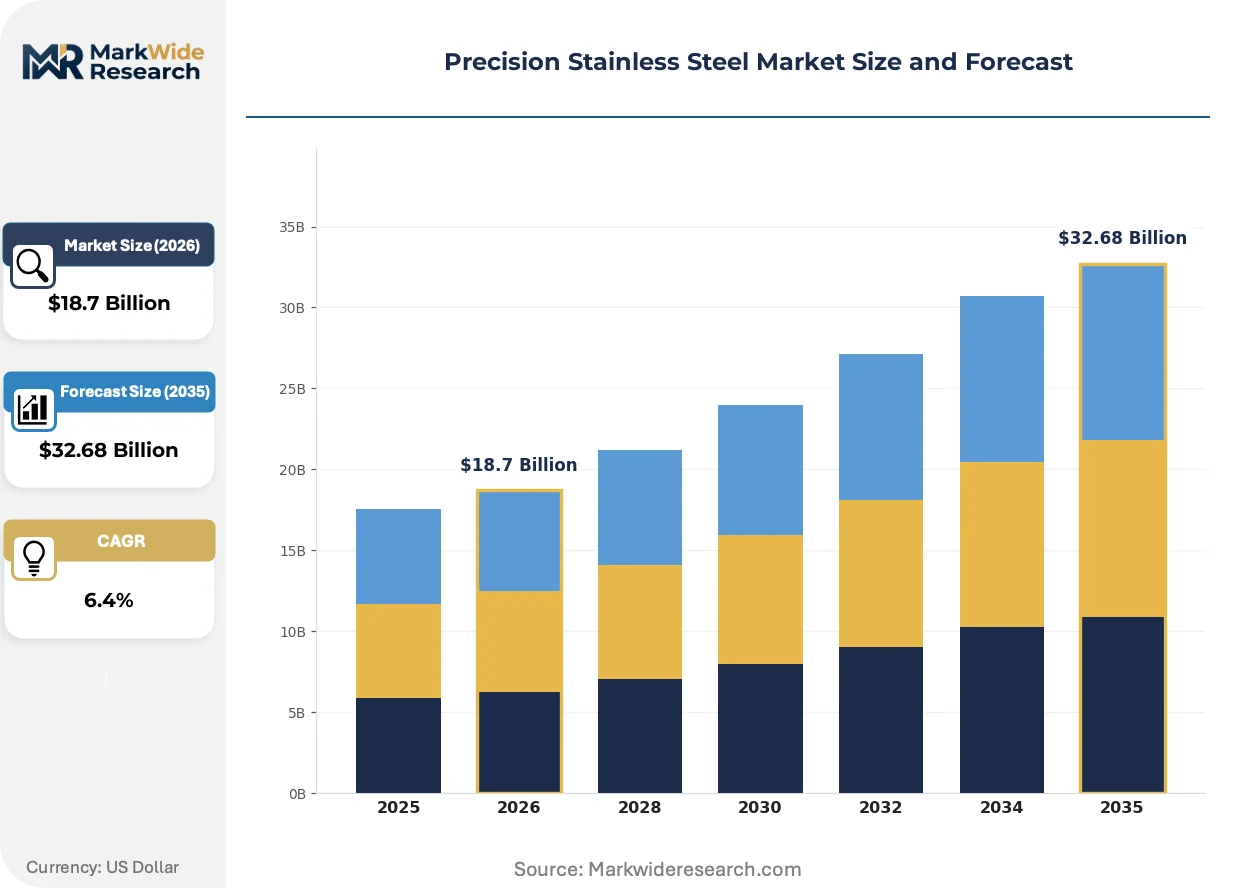
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Products, Long Products, Bars, Sheets End Use Industry: Food Processing, Aerospace, Automotive, Medical Devices Grade: 304, 316, 410, 430 Form: Welding Wire, Pipe, Coil, Plate |
| Companies Covered | Nippon Steel, ArcelorMittal, Outokumpu, JFE Steel, Baosteel, Aperam, POSCO, Voestalpine AG, Thyssenkrupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Stainless Steel Market Strategic Shifts & Innovations
Process digitization and alloy specificity are bifurcating competitive positioning in precision stainless steel, separating producers capable of lot-level traceability from commodity-grade operators facing margin compression in undifferentiated flat products.
Continuous annealing process control systems with inline surface inspection are fragmenting quality consistency outcomes across the supplier base. Semiconductor equipment fabricators in South Korea and Taiwan are demanding sub-micron surface roughness specifications that only digitally integrated cold-rolling lines can reliably deliver. This capability gap is compressing market access for legacy batch-annealing operators unable to justify retrofit capital.
EU Medical Device Regulation (MDR) technical documentation requirements are extending material certificate retention periods to device lifetime plus ten years. Stainless steel suppliers serving European medical OEMs must now maintain immutable digital twin records for each heat and coil. This regulatory burden is favoring integrated producers with captive IT infrastructure over merchant mills dependent on third-party certification services.
Consolidation of surgical instrument manufacturing into specialized contract manufacturers in Tuttlingen, Germany and Sialkot, Pakistan is compressing supplier relationship structures. These concentrated buyers are unbundling metallurgical testing from material supply, performing incoming inspection in-house and disqualifying mills with inconsistent certificate accuracy. The shift rewards producers with transparent process data sharing capabilities and penalizes traditional arm's-length commercial relationships.
Precision Stainless Steel Market Segmentation
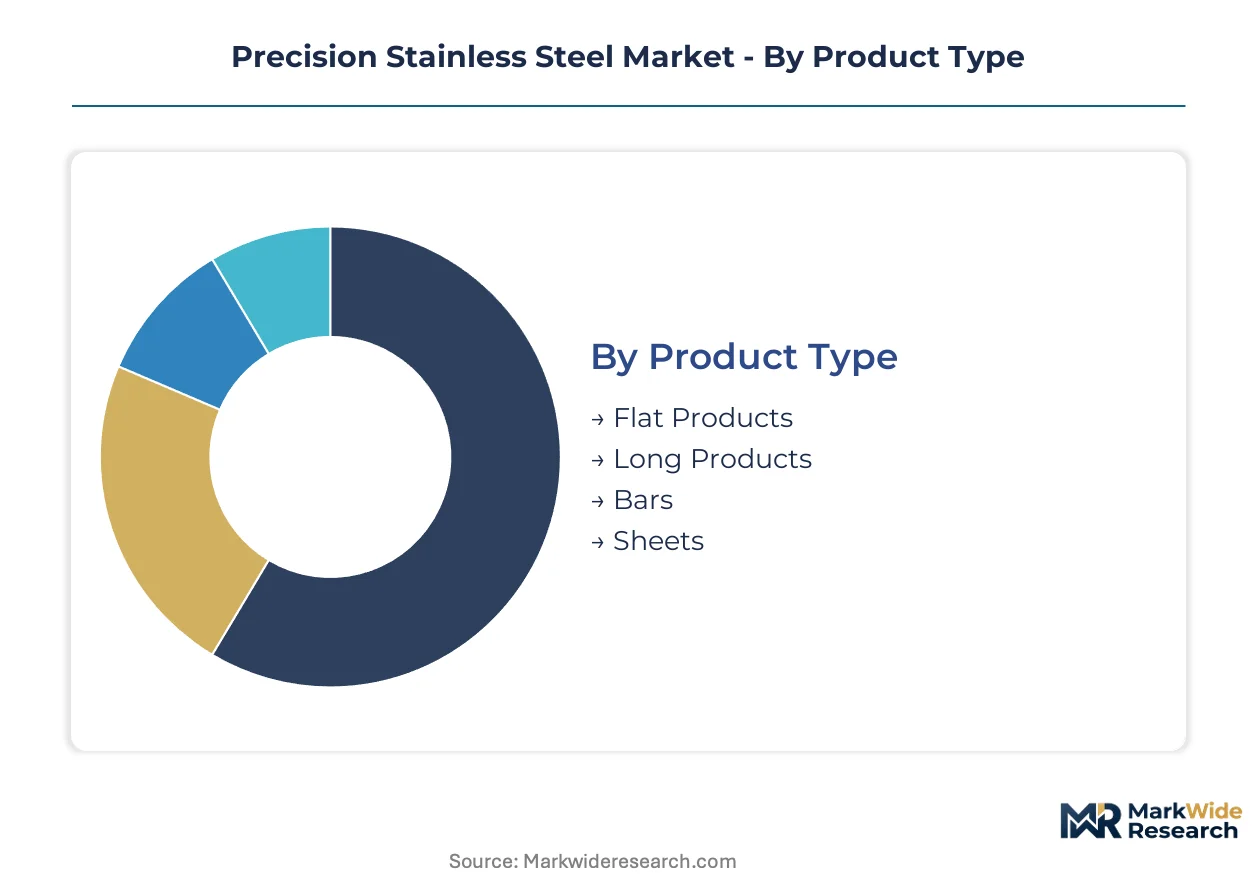
Segmentation in precision stainless steel separates producers who command specification premiums from commodity operators facing margin erosion. Grade purity, surface finish tolerances, and regulatory certification pathways determine contract pricing power across each dimensional split.
Product Type:
Margin pools concentrate in cold-rolled strip where surface finish consistency commands qualification premiums for semiconductor and medical OEMs.
- Flat Products:Cold-rolled strip and sheet manufactured to sub-0.05 mm thickness tolerances with controlled surface roughness. Demand clusters in South Korean wafer processing equipment fabrication as chip node sizes contract below 3nm, tightening sub-micron surface specifications.
- Long Products:Bar, rod, and wire forms produced to tight dimensional straightness and diameter control. German surgical instrument manufacturers in Tuttlingen specify vacuum-arc remelted long products for orthopedic implant machining, tightening material traceability requirements.
- Bars:Precision-ground bar stock for CNC machining applications with diameter tolerances within 0.025 mm.
- Sheets:Annealed sheet products for formed components where surface cosmetic quality determines acceptance.
Flat Products holds installed capacity. Long Products is rotating up the share rankings.
End Use Industry:
Application-driven certification requirements fragment pricing tiers, with medical and semiconductor end-uses extracting 40-60% premiums over food-grade commoditized supply.
- Medical Devices:Implantable-grade 316LVM vacuum-arc remelted material with sub-5 ppm sulfur and enhanced corrosion resistance. FDA 21 CFR Part 820 traceability mandates compress supplier qualification timelines to 18-24 months while extending material certificate retention to device lifetime plus ten years under EU MDR.
- Food Processing:NSF/3A sanitary standard grades for contact surfaces with controlled surface roughness and passivation requirements. European dairy equipment OEMs concentrate procurement around Essen and Düsseldorf logistics corridors, pulling cold-rolling capacity toward Rhine-Ruhr hubs.
- Aerospace:High-strength precipitation-hardening grades for structural fasteners and control surface actuators.
- Automotive:Exhaust system grades and fuel injection components with thermal cycling resistance specifications.
Food Processing commands volume scale. Medical Devices is expanding most quickly.
Grade:
Alloy surcharge mechanisms transmit London Metal Exchange nickel volatility directly to customer quotations, destabilizing multi-year contract structures for austenitic grades.
- 304:General-purpose austenitic grade with 18% chromium and 8% nickel content, dominating food processing and architectural applications. Japanese hydrogen infrastructure seal manufacturers under METI-coordinated JIS revisions specify modified 304 variants for high-pressure fatigue resistance.
- 316:Molybdenum-bearing austenitic grade with enhanced chloride corrosion resistance for marine and chemical processing. South Korean semiconductor equipment fabricators specify ultra-high-purity 316L with sub-5 ppm sulfur for wafer chamber fabrication.
- 410:Hardenable martensitic grade for cutlery and industrial blades requiring heat treatment response.
- 430:Ferritic grade with reduced nickel content for automotive trim and appliance applications.
304 anchors volume leadership. 316 is climbing the fastest.
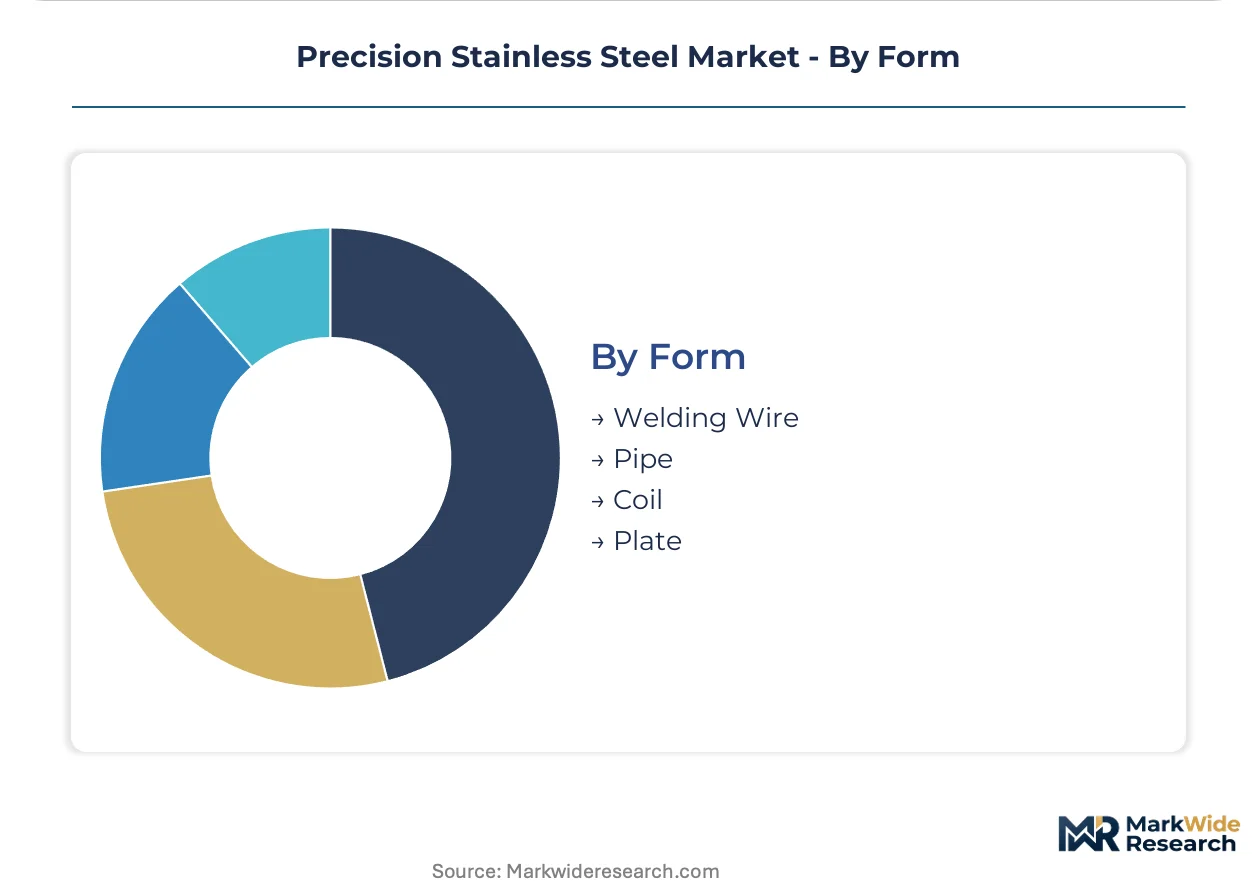
Form:
Continuous annealing process control separates digitally integrated producers from legacy batch-annealing operators facing quality consistency gaps.
- Coil:Continuously processed strip wound for automated stamping and roll-forming operations. POSCO anchors Asian precision coil leadership through continuous annealing scale, while Outokumpu differentiates European supply through cold-rolling mastery in austenitic grades.
- Pipe:Seamless and welded tubular products for fluid handling systems with dimensional tolerances controlling flow characteristics.
- Welding Wire:Precision-drawn wire with controlled chemistry for automated joining processes.
- Plate:Hot-rolled and descaled plate products for structural fabrications requiring thickness over 6 mm.
Coil dominates throughput economics. Pipe is gaining share fastest in hydrogen infrastructure applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in medical device clusters absorb nickel surcharge volatility with minimal demand elasticity, while food processing OEMs in commodity-grade segments exhibit acute price sensitivity. This divergence concentrates premium supply negotiations around Düsseldorf and Essen, whereas volume purchasers arbitrage across Asian coil sources.
United States
FDA 21 CFR Part 820 traceability mandates compress supplier qualification timelines for surgical-grade strip, while semiconductor equipment fabricators in Oregon and Arizona demand sub-micron surface roughness specifications. The EPA maintains emission standards for electric-arc furnace operations, influencing regional capacity siting decisions. Greater Boston anchors orthopedic implant machining clusters where 316LVM vacuum-arc remelted grades command qualification premiums.
Germany
EU MDR technical documentation requirements extend material certificate retention to device lifetime plus ten years, reshaping supplier-auditor relationships for Tuttlingen surgical instrument manufacturers. ECHA REACH nickel release thresholds disqualify conventional grades in consumer-touch applications. The Rhine-Ruhr corridor around Düsseldorf and Essen concentrates cold-rolling capacity expansion as logistics hubs pull European medical OEM procurement.
Japan
METI-coordinated JIS standards revision for precision strip in hydrogen infrastructure seals creates specification windows for fatigue-resistant austenitic grades. PMDA medical device regulations align with global traceability norms, accelerating domestic VAR capacity investment. Nagoya industrial clusters integrate precision stainless into high-pressure containment systems for hydrogen mobility pilots.
South Korea
MFDS pharmaceutical and medical device regulations enforce parallel quality systems for implantable-grade material imports, extending qualification cycles for European and Japanese suppliers. Semiconductor equipment fabricators in Gyeonggi Province specify ultra-high-purity 316L with sub-5 ppm sulfur for wafer processing chambers. POSCO anchors regional precision coil supply through continuous annealing scale.
China
GB standards for sanitary stainless in food processing equipment converge with NSF/3A international norms, opening export qualification pathways for domestic mills. MIIT industrial policy prioritizes domestic VAR capacity for surgical-grade applications, reducing import dependency. Yangtze River Delta clusters around Shanghai integrate precision strip into semiconductor fabrication tool supply chains.
Precision Stainless Steel Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with blast-furnace operators commanding captive ore-to-strip economics while electric-arc specialists compete on alloy flexibility. The structure rewards backward integration into ferrochrome and refined nickel units, particularly for high-austenitic medical grades. Strategic archetypes include: integrated blast-furnace giants with captive raw material streams; cold-rolling mastery specialists focused on surface finish consistency; and continuous annealing scale operators anchoring Asian volume leadership. Dominant competitive moves encompass digital order-to-delivery platform deployment and vacuum-arc remelt furnace capacity expansion.
Among integrated Japanese producers, Nippon Steel exemplifies the captive raw material archetype, while JFE Steel occupies a parallel position in high-nickel grade stability. Outokumpu represents the cold-rolling mastery specialist tier, anchoring European medical OEM relationships through austenitic strip qualification. These three names illustrate how geographic origin and corporate structure align with distinct competitive positioning in precision stainless steel supply.
| Leading Market Players |
|---|
| Nippon Steel |
| ArcelorMittal |
| Outokumpu |
| JFE Steel |
| Baosteel |
| Aperam |
| POSCO |
| Voestalpine AG |
| Thyssenkrupp |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four month qualification timelines for surgical-grade strip concentrate pricing power among pre-qualified suppliers while compressing margin flexibility for unqualified entrants attempting to serve regulated end-uses. This lead-time band reflects the intersection of FDA traceability mandates, VAR furnace capacity constraints, and the geographic clustering of qualified buyers around Düsseldorf and Essen logistics corridors.
Pricing Analysis
After-sales service and metallurgical testing bundling drives lifetime value for precision stainless steel producers serving medical device OEMs with certified internal labs. Three-tier pricing structure across implant-grade, food-grade, and architectural levels segments buyers by certification burden and surface finish tolerance. Cost compression in commodity 304 sheet intensifies because Asian blast-furnace operators transmit nickel surcharge volatility directly to spot quotations. Food processing OEMs exhibit acute price sensitivity and arbitrage across coil sources, while Tuttlingen surgical instrument manufacturers absorb premium positioning with minimal demand elasticity.
Supply Chain Analysis
Inventory cycles stretching to device lifetime plus ten years under EU MDR reshape working capital requirements for European medical OEM procurement. Geographic supply concentration centers on Japan, South Korea, and Germany for VAR-equipped surgical-grade capacity, while China and Finland anchor cold-rolling scale for commodity austenitic strip. Raw material dependencies draw from Indonesian nickel ore, South African ferrochrome, and Australian metallurgical coal. Single-source vulnerability pervades vacuum-arc remelt furnace operations, where qualified installed base rests on three supplier groups. Distribution runs through mill-direct digital platforms disintermediating traditional steel service centers for certified medical device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precision stainless steel market sits in cyclical recovery as surgical instrument OEMs restock implant-grade inventory following pandemic-deferred elective procedure backlogs.
For Market Incumbents: Secure VAR furnace operator talent through apprenticeship pipelines and retention premiums before capacity expansion timelines extend further. Defend margin position by deepening backward integration into refined nickel units and ferrochrome smelting, insulating against London Metal Exchange volatility that threatens multi-year medical supply agreements. For New Entrants and Emerging Players: Differentiate on hydrogen infrastructure seal qualification under Japan's METI-coordinated JIS standards revision, where fatigue-resistant austenitic grades face limited domestic competition. Target South Korean semiconductor equipment fabricators demanding sub-5 ppm sulfur 316L for wafer chamber fabrication, penetrating through transparent process data sharing and immutable digital twin record capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated steel parents seeking to divest non-core precision strip assets with captive medical OEM relationships but underutilized cold-rolling capacity. Long-term viability hinges on regulatory certification moats widening under FDA and ECHA traceability convergence. Watch nickel price volatility amplitude as inflection indicator for contract pricing renegotiation frequency and working capital stress across the supplier base.| Strategic Initiative | Industry Significance |
|---|---|
| VAR Capacity Expansion | Vacuum-arc remelt furnace additions address 316LVM scarcity constraining surgical-grade output growth for implantable applications. |
| Digital Twin Implementation | Immutable lot-level traceability systems satisfy EU MDR certificate retention mandates extending to device lifetime plus ten years. |
| Backward Integration | Captive ferrochrome and refined nickel production insulates margin stability against London Metal Exchange price transmission. |
| Continuous Annealing Retrofit | Inline surface inspection capability qualifies supply for South Korean semiconductor fabricators demanding sub-micron roughness specifications. |
| Hydrogen Seal Qualification | First-mover positioning under Japan's METI-coordinated JIS standards revision captures high-pressure containment specification windows. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VAR furnace operators, cold-rolling line managers, surgical instrument procurement heads at Tuttlingen and Sialkot contract manufacturers, and biomedical engineers at German orthopedic implant machining clusters. Secondary validation drew from FDA 21 CFR Part 820 guidance documents, ECHA REACH substance restriction databases, JIS standards revision notices, SEC filings of listed steel producers, and customs trade data tracking nickel and ferrochrome flows. Bottom-up capacity assessments triangulated against top-down end-use demand modeling across medical device, semiconductor equipment, and hydrogen infrastructure segments.
Across the projection horizon, the analytical framework modeled volume and value outputs through grade purity tiers, surface finish tolerance bands, regulatory certification pathways, and regional production hub clusters. CAGRs were derived from elasticity-adjusted demand curves incorporating nickel price volatility scenarios and qualification timeline compression effects. Industry-specific forecast inputs included vacuum-arc remelt furnace utilization rates and semiconductor fabrication node contraction trajectories driving sub-5 ppm sulfur specifications.
The analysis sits within stated boundaries; outcomes outside sustained nickel price stability or accelerated VAR capacity commissioning would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization between FDA and EU MDR traceability requirements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Metals
Global Metal Bellows Market
Specialty Metals
Case Hardening Steel Market
Specialty Metals
Precious Metal Plating Market
Specialty Metals
North America Metal Turned Precision Product Manufacturing Market
Specialty Metals
Global Special Steel Market
Specialty Metals
Specialty Metallic Pigments Market
Specialty Metals
Metal Halide Market
Specialty Metals
Europe Metal Precision Turned Product Manufacturing Market
Specialty Metals
Dysprosium Market