
 Global Brazing Consumable Market | 2026-2036
Global Brazing Consumable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Brazing Consumable Market Foresight
Commercial HVAC contractors are collapsing their historical reliance on general-purpose filler metals in favor of flux-cored wire systems engineered for aluminum-to-copper joints. Johnson Matthey Plc leverages its precious metals refining heritage to dominate high-integrity aerospace filler metal supply. Lucas-Milhaupt Inc anchors North American distribution through captive wire drawing capacity and direct mill relationships. Harris Products Group specializes in phosphor-copper formulations for air conditioning and refrigeration service technicians.
Brazing consumables encompass filler metals, fluxes, and allied materials engineered to create metallurgical bonds between base metals without melting the substrates, typically operating at temperatures between 450°C and 900°C with compositions tailored to match thermal expansion coefficients and service environment demands. Filler metals command the dominant value share due to silver and copper commodity exposure, while flux-cored wires represent the fastest-growing product configuration as fabricators seek to eliminate separate fluxing steps and reduce rework rates. Brazing pastes concentrate margin pools in electronics assembly applications where stencil-printable formulations enable high-volume surface-mount device attachment.
REACH and RoHS frameworks in Europe restrict cadmium and lead content in brazing alloys, compelling alloy developers to validate silver-copper-tin substitutes for historical cadmium-bearing compositions. The EPA and OSHA in the United States enforce exposure limits on fluoride-bearing flux fumes, driving demand for low-fume and fluoride-free flux formulations in confined fabrication environments. Stakeholders must monitor evolving alloy qualification protocols from aerospace OEMs and assess captive versus merchant supply strategies for precious metal feedstock security.
Market Dynamics
Flux-cored wire systems are compressing traditional two-step brazing workflows as fabricators prioritize joint quality consistency and labor hour reduction in high-volume production environments.
Growth Catalysts
- REACH cadmium restrictions:European alloy developers are accelerating silver-copper-tin validation programs to replace historical cadmium-bearing compositions in safety-critical applications.
- Aerospace turbine procurement:Component manufacturers in Germany's industrial corridor are expanding nickel-based filler metal orders for blade assembly operations.
- HVAC aluminum-to-copper transition:Commercial contractors are adopting flux-cored wire systems engineered specifically for dissimilar metal joints in refrigeration equipment.
Market Restraints
- Silver commodity volatility:Precious metal price swings compress margin predictability for high-integrity aerospace filler metal producers.
- Fluoride-bearing flux exposure limits:OSHA confined-space regulations increase compliance costs for fabrication shops using traditional flux formulations.
- Plasma arc welding substitution:Thick-section fabricators in heavy equipment manufacturing are evaluating solid-state alternatives for structural joints.
Strategic Opportunities
- Stencil-printable paste expansion:Electronics assembly lines in South Korea and Taiwan are adopting high-volume surface-mount brazing paste formulations.
- EU Green Deal industrial decarbonization:Carbon border adjustment mechanisms create preference for low-emission brazing processes in export-oriented manufacturing.
- Direct-to-technician distribution:Refrigeration service channels are bypassing traditional wholesale tiers through mobile-optimized ordering platforms.
Industry Challenges
- Alloy qualification timelines:Aerospace OEM validation protocols extend 18-24 months for new filler metal compositions, freezing supplier switching.
- Precious metal feedstock security:Merchant refiners face working capital intensity when securing silver and palladium against volatile spot markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Brazing Consumable Market |
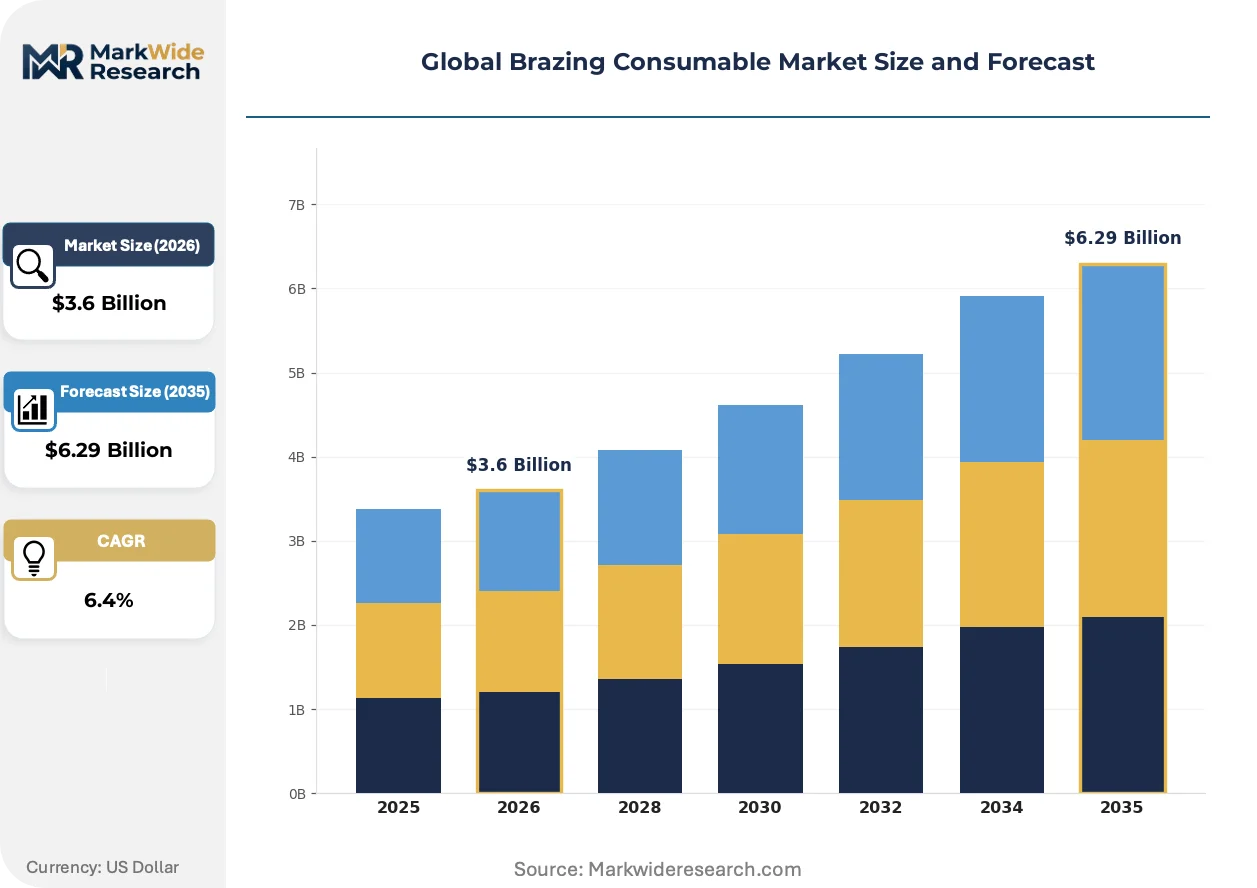
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filler Metals, Fluxes, Flux-Cored Wires, Brazing Pastes, Brazing Powders Application: HVAC, Power Generation, Aerospace Components, Electronics Assembly, Jewelry Manufacturing End User: Fabricators, Aircraft Manufacturers, Electrical Equipment Makers, Jewelry Artisans, Power Plant Operators Distribution Channel: Direct Sales, Specialty Stores, Distributors, Online Marketplaces, Industrial Suppliers |
| Companies Covered | Lucas-Milhaupt Inc, Harris Products Group, Johnson Matthey Plc, Umicore N.V., Morgan Advanced Materials, Bellman-Melcor LLC, Castolin Eutectic, Prince & Izant Company, Lincoln Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Brazing Consumable Market Shifts & Advancements
Active brazing paste formulations are redefining electronics attachment workflows while regulatory chemistry restrictions force simultaneous alloy reformulation across multiple industrial geographies.
Self-fluxing nickel-chromium-boron alloys are fragmenting traditional silver-copper dominance in high-temperature turbine applications. Aerospace component manufacturers in Germany and the United States are qualifying these compositions for blade root attachments. The shift is fragmenting historical supplier relationships as captive powder metallurgy capabilities become decisive for OEM approval.
REACH Annex XVII cadmium restrictions are compelling systematic alloy redesign across European supply chains. ECHA enforcement actions against non-compliant imports have accelerated laboratory validation investments. German and French distributors now stock exclusively cadmium-free alternatives, forcing Asian exporters to reformulate or exit the market.
Consolidated procurement by HVAC original equipment manufacturers is compressing supplier counts to three approved vendors per alloy family. Tier-one equipment builders in the United States are mandating flux-cored wire qualifications for all new refrigeration platform designs. This concentration is most visible in Texas and Florida state markets where residential construction volume drives annual contract negotiations.
Global Brazing Consumable Market Segmentation
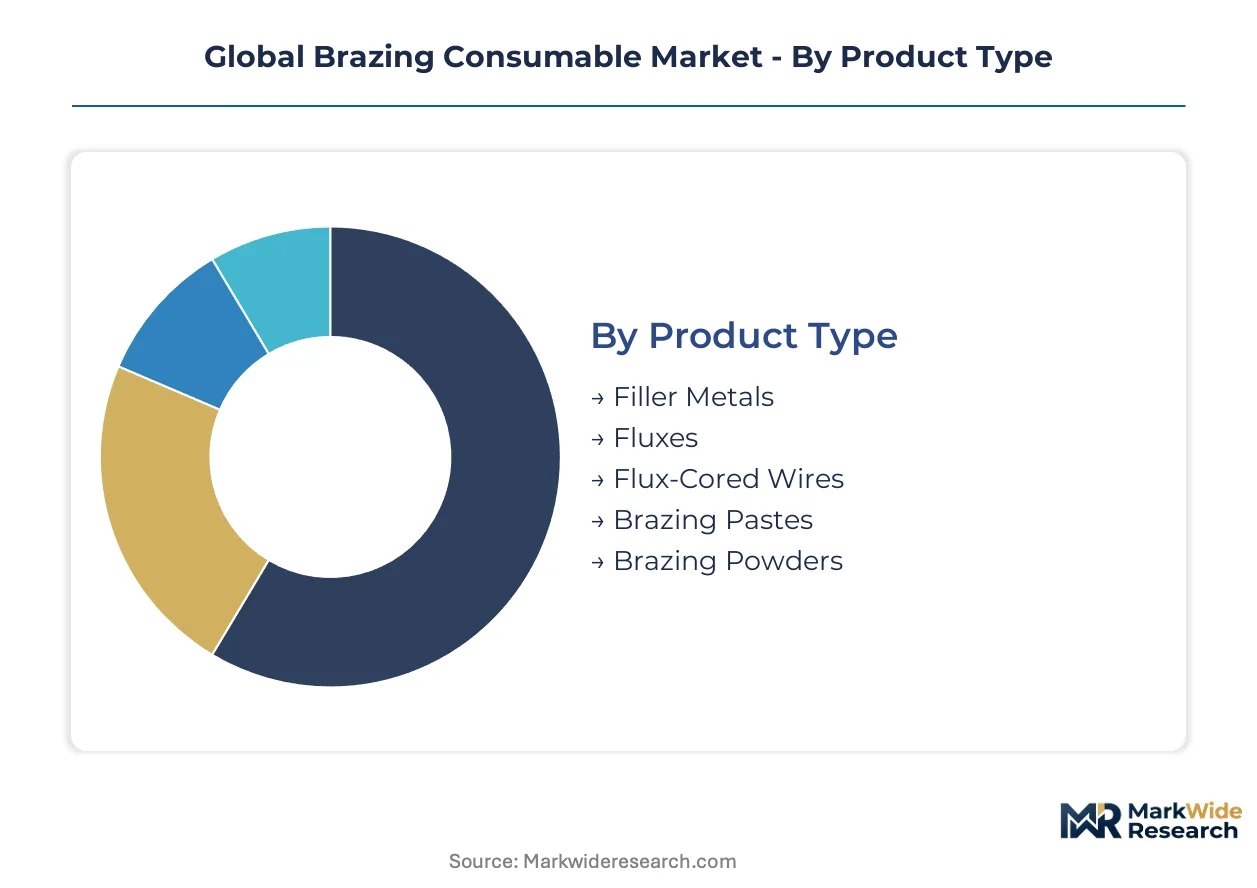
Brazing consumables fragment across five distinct taxonomies that govern procurement behavior. Product configuration determines workflow economics while application verticals dictate alloy chemistry requirements and regulatory exposure.
Product Type:
Domestic production concentrates in Germany and the United States for high-integrity filler metals, whereas flux-cored wires and brazing pastes flow disproportionately from South Korean and Taiwanese export facilities.
- Filler Metals:Silver-copper, nickel-chromium-boron, and phosphor-copper formulations constitute the value core. Demand clusters in Düsseldorf-Essen industrial corridor for turbine blade assembly and in Texas HVAC manufacturing zones.
- Fluxes:Fluoride-bearing and fluoride-free chemical systems enable oxide removal during joint formation. OSHA confined-space regulations in the United States are compressing traditional formulations in favor of low-fume alternatives.
- Flux-Cored Wires:Aluminum-to-copper engineered systems eliminate separate fluxing steps. Commercial refrigeration contractors in Florida and Texas state markets are mandating these configurations for new equipment platforms.
- Brazing Pastes:Stencil-printable formulations serve high-volume electronics attachment. South Korean surface-mount device lines are expanding paste procurement for consumer electronics boards.
- Brazing Powders:Atomized metal particles enable specialized furnace brazing operations. Captive powder metallurgy capabilities in Germany and the United States are becoming decisive for aerospace OEM approval.
Filler metals command the established base. The steepest expansion runs through flux-cored wire systems.
Application:
Cost-tier stratification separates safety-critical aerospace specifications from commodity HVAC service grades, with electronics assembly occupying a precision-premium middle tier.
- HVAC:Air conditioning and refrigeration equipment dominates volume consumption. REACH cadmium restrictions are forcing alloy reformulation across European service channels.
- Power Generation:Turbine component repair and heat exchanger fabrication require nickel-based high-temperature formulations. German power plant operators are consolidating procurement through three-vendor qualification frameworks.
- Aerospace Components:Blade root attachments and structural joints demand validated silver and palladium-bearing compositions. EASA and FAA qualification protocols extend 18-24 months for new alloy introductions.
- Electronics Assembly:Surface-mount device attachment relies on active brazing pastes with precise melting ranges. Taiwanese contract manufacturers are expanding stencil-printable formulation orders.
- Jewelry Manufacturing:Precious metal soldes and decorative alloys serve artisan and industrial production. Italian and Indian jewelry clusters maintain distinct specification preferences.
HVAC absorbs the highest absolute tonnage. Aerospace components generate the steepest margin expansion.
End User:
Customer-type concentration separates large OEM captive procurement from fragmented service-technician spot purchasing, with distribution infrastructure adapting accordingly.
- Fabricators:General metalworking shops consume standardized filler metal forms across automotive and industrial equipment repair. OSHA fluoride exposure limits are elevating compliance costs for smaller fabrication shops.
- Aircraft Manufacturers:Boeing and Airbus tier-one suppliers enforce strict alloy qualification protocols. German component manufacturers in the Düsseldorf-Essen corridor are expanding nickel-based filler metal orders.
- Electrical Equipment Makers:Transformer and switchgear producers utilize phosphor-copper and silver-bearing compositions for electrical conductivity.
- Jewelry Artisans:Small-batch precious metal users prioritize color match and flow characteristics over mechanical properties.
- Power Plant Operators:Maintenance departments procure high-temperature alloys for turbine blade repair and heat exchanger restoration.
Fabricators represent the broadest installed base. Aircraft manufacturers concentrate the highest specification value.
Distribution Channel:
Supply concentration varies sharply by customer scale, with direct mill relationships dominating aerospace procurement while mobile-optimized platforms penetrate refrigeration service technician segments.
- Direct Sales:Mill-direct relationships serve high-volume OEMs with customized alloy specifications. Johnson Matthey and Lucas-Milhaupt anchor North American and European direct channels.
- Specialty Stores:Local welding supply outlets stock standard filler metal forms for immediate technician needs.
- Distributors:Regional industrial distributors aggregate demand across fragmented fabrication accounts. German and French distributors now stock exclusively REACH-compliant cadmium-free alternatives.
- Online Marketplaces:Mobile-optimized platforms are bypassing traditional wholesale tiers for refrigeration service channels in Texas and Florida.
- Industrial Suppliers:Broad-line MRO distributors serve maintenance departments with consolidated procurement.
Direct sales capture the premium specification tier. Online marketplaces are climbing the fastest through service-technician penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European brazing consumable distribution through its specialized metals handling terminals, while the Trans-Siberian Railway corridor funnels Asian-manufactured flux-cored wire into Central European fabrication centers.
Germany
REACH cadmium restrictions are accelerating alloy reformulation investments across the Düsseldorf-Essen industrial corridor. ECHA enforcement actions have eliminated non-compliant imports from distributor shelves. Nickel-based filler metal orders for turbine blade assembly are expanding at Siemens Energy and MTU Aero Engines facilities in North Rhine-Westphalia.
United States
OSHA fluoride exposure limits are compressing traditional flux formulations in Texas and Florida HVAC manufacturing zones. The EPA's National Emission Standards for Hazardous Air Pollutants affect furnace brazing operations in Ohio and Pennsylvania. Commercial refrigeration contractors in Houston and Miami are mandating flux-cored wire qualifications for new equipment platforms.
China
Dual carbon goals under MIIT guidance are reshaping energy-intensive brazing alloy production in Shandong and Jiangsu provinces. GB standards enforcement for workplace chemical exposure is elevating compliance costs for export-oriented fabricators. The Yangtze River Delta cluster around Shanghai concentrates stencil-printable brazing paste manufacturing for consumer electronics export.
South Korea
MFDS chemical substance registration requirements are extending validation timelines for imported brazing flux formulations. The Busan-Ulsan industrial corridor hosts expanding surface-mount device assembly lines consuming active brazing pastes. Samsung and LG Electronics suppliers are consolidating procurement through three-vendor frameworks for high-volume electronics attachment.
Japan
METI's Green Transformation initiative is creating procurement preference for low-emission brazing processes in automotive component manufacturing. JIS Z 3261 standards govern silver filler metal specifications for precision equipment. The Nagoya-Toyota industrial zone maintains captive powder metallurgy capabilities for aerospace OEM qualification.
Global Brazing Consumable Market Competitive Landscape
Concentration sits with precious metals refiners and captive wire drawing specialists who control alloy formulation IP and direct mill relationships. The vendor base separates into three tiers: integrated precious metals houses with aerospace qualification heritage, regional wire drawing specialists with distribution scale, and formulation-focused paste manufacturers serving electronics assembly. M&A activity concentrates on acquiring REACH-compliant alloy portfolios, while capacity expansion targets flux-cored wire systems for HVAC dissimilar metal joints.
Among UK-based precious metals specialists, Johnson Matthey Plc occupies a position exemplifying the integrated refiner-to-filler-metal archetype with aerospace heritage. Lucas-Milhaupt Inc and Harris Products Group represent North American distribution-anchored players with captive wire drawing capabilities and direct technician channel penetration. These three entities illustrate the competitive fault line between precious metals integration and distribution scale economics.
| Leading Market Players |
|---|
| Lucas-Milhaupt Inc |
| Harris Products Group |
| Johnson Matthey Plc |
| Umicore N.V. |
| Morgan Advanced Materials |
| Bellman-Melcor LLC |
| Castolin Eutectic |
| Prince & Izant Company |
| Lincoln Electric Company |
| Others |
Supply & Pricing Matrix
Silver-copper-tin alloy substitution for historical cadmium-bearing compositions is redrawing procurement geography across European supply chains while compressing margin structures for reformulation investments. REACH Annex XVII enforcement has eliminated price-competitive Asian imports from German and French distributor shelves, forcing buyers toward qualified domestic suppliers with embedded compliance costs.
Pricing Analysis
Three-tier pricing structure across aerospace-specification, industrial-grade, and service-technician economy levels governs contract negotiations. Aerospace OEM qualification heritage commands substantial premia over commodity HVAC grades, while volume-scale discounts concentrate procurement power among Texas and Florida equipment manufacturers. Price erosion runs through standard phosphor-copper formulations as consolidated three-vendor frameworks squeeze supplier margins. Commercial refrigeration contractors exhibit highest price sensitivity due to thin installation margins, whereas turbine blade assemblers prioritize thermal performance over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for South Korean-manufactured flux-cored wire destined for Central European fabrication centers. Supply concentrates in Germany and the United States for high-integrity nickel-based filler metals, while brazing paste production clusters in the Yangtze River Delta around Shanghai. Raw material sourcing draws from silver spot markets, copper cathode contracts, and palladium merchant refiner relationships. Single-source vulnerability sits with precious metal feedstock security against volatile commodity swings. Distribution runs through direct mill relationships for aerospace OEMs and mobile-optimized platforms penetrating refrigeration service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EASA and FAA qualification protocols create eighteen-to-twenty-four-month switching costs that freeze incumbent positions. Network effects concentrate in approved vendor lists that consolidate procurement through three-supplier frameworks.
For Market Incumbents: Secure captive powder metallurgy capabilities in Germany and the United States to defend aerospace OEM approval positions against emerging nickel-chromium-boron specialists. Deepen backward integration into precious metal refining to buffer silver spot volatility compressing margin predictability. Prioritize REACH-compliant alloy portfolio acquisition targets that eliminate reformulation lag for European market access. For New Entrants and Emerging Players: Differentiate on stencil-printable active brazing paste formulations for South Korean and Taiwanese surface-mount device assembly lines, where electronics contract manufacturers seek qualified second-source suppliers outside established precious metals houses. Target direct-to-technician distribution platforms in Texas and Florida HVAC markets, leveraging mobile-optimized ordering to bypass entrenched wholesale tiers with thinner overhead structures. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated precious metals refiners with aerospace heritage over pure-play wire drawing specialists lacking formulation IP. Long-term viability over the next decade rests on regulatory entrenchment deepening rather than commodity cyclicality. Acquisition candidates should demonstrate captive qualification relationships with Siemens Energy or MTU Aero Engines. The signal to watch is ECHA enforcement action intensity against non-compliant imports, which would accelerate compliant-portfolio premia.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Alloy Reformulation | ECHA enforcement actions against cadmium-bearing imports are eliminating price-competitive Asian suppliers from European shelves. |
| Flux-Cored Wire Capacity Expansion | Texas and Florida HVAC manufacturers are mandating these configurations for aluminum-to-copper joint platforms. |
| Captive Powder Metallurgy Investment | Aerospace OEM qualification protocols favor suppliers with in-house atomization capabilities for nickel-chromium-boron alloys. |
| Direct-to-Technician Distribution Platform | Mobile-optimized ordering is bypassing traditional wholesale tiers in commercial refrigeration service channels. |
| Precious Metal Refining Backward Integration | Silver and palladium spot volatility compresses margins for merchant refiners lacking upstream feedstock security. |
Research Methodology
Initial hypotheses were tested against primary input from brazing alloy technical directors, aerospace OEM procurement managers, HVAC equipment manufacturer sourcing leads, and commercial refrigeration service contractors, then refined through secondary validation. Primary fieldwork combined structured interviews with distribution channel partners and plant-level fabrication engineers across the Düsseldorf-Essen corridor and Texas manufacturing zones. Secondary sources encompassed ECHA regulatory enforcement databases, EPA National Emission Standards filings, SEC 10-K disclosures from precious metals refiners, and customs trade flow records for silver-bearing filler metal categories. Bottom-up demand modeling from end-use application volumes was triangulated against top-down supply-side capacity assessments.
Variance decomposition across product configuration, application vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include filler metal chemistry family, flux-cored versus solid wire form, aerospace versus HVAC versus electronics assembly end-use, and direct mill versus distributor versus online channel. CAGRs were derived from weighted average growth contributions across these segments. Industry-specific forecast inputs incorporated REACH compliance transition timelines and EASA qualification protocol durations.
Material uncertainties — silver spot price volatility, ECHA enforcement intensity, and aerospace OEM vendor consolidation decisions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory phase-in schedules and alloy substitution adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Ferrosilicon Magnesium Market
Metals
US Copper Scrap Market
Metals
Tungsten Metal Powder Market
Metals
Zirconium Market
Metals
Global Bronze Market
Metals
Stainless Steel Market
Metals
Lanthanum Market
Metals
Heat-Treated Steel Plates Market
Metals
Brazil Aluminum Market
Metals
Nickel Oxide Target Market
Metals
Global Mercury Market
Metals
North America Aluminium Powder Market
Metals
Copper Azoles Market
Metals
Rhodium Market
Metals
Saudi Arabia Aluminum Market
Metals
Metal Recycling Market