
 Polycarbonate Panels Market | 2026-2036
Polycarbonate Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Panels Market Intelligence
Divergence in performance requirements for specialty applications versus standard construction is consolidating the market into distinct tiers. SABIC leverages its vast chemical production scale to supply high-purity resins for premium panels used in architectural glazing. Covestro specializes in advanced material science, developing panels with specific properties like enhanced fire resistance or thermal insulation. Palram Industries, in contrast, competes effectively in the high-volume multiwall and corrugated sheet segments for agricultural and general construction use.
Polycarbonate panels are transparent or translucent thermoplastic sheets produced primarily through an extrusion process using polycarbonate resin. Valued for their high impact resistance, lightweight nature, and inherent UV filtering capabilities, they serve as a durable alternative to glass in glazing and roofing applications. Multiwall sheets represent a significant volume segment due to their thermal insulation properties favored in greenhouse and conservatory construction. Solid sheets, offering superior optical clarity and strength, are gaining share in transportation glazing and protective barrier applications.
Product standards are shaped by multiple regulatory frameworks, including CE marking requirements in Europe for construction products and ASTM standards in the United States for material properties. In parallel, ISO 9001 certification influences procurement decisions by large-scale building contractors and vehicle manufacturers seeking consistent quality. Future competitive advantage depends on developing panels that meet stricter fire safety codes and circular economy principles for recyclability.
Market Dynamics
The primary structural force is a bifurcation of the market, driven by diverging performance requirements. This split separates high-purity, optically clear panels for architectural glazing from high-volume, cost-sensitive multiwall sheets for general construction and agricultural applications.
Growth Catalysts
- Building Energy Codes:Stricter thermal insulation mandates in European building regulations, aligned with the EU Green Deal, are spurring adoption of multiwall polycarbonate panels in conservatory and commercial roofing to reduce energy consumption.
- Transportation Sector Demand:The need for lightweight, impact-resistant materials in public transit vehicles, including buses and trains, is increasing the specification of solid polycarbonate sheets for windows, partitions, and interior components.
- Asian Infrastructure Expansion:Large-scale commercial and industrial construction projects across China and Southeast Asia create sustained volume demand for corrugated and solid polycarbonate panels for roofing, cladding, and daylighting systems.
Market Restraints
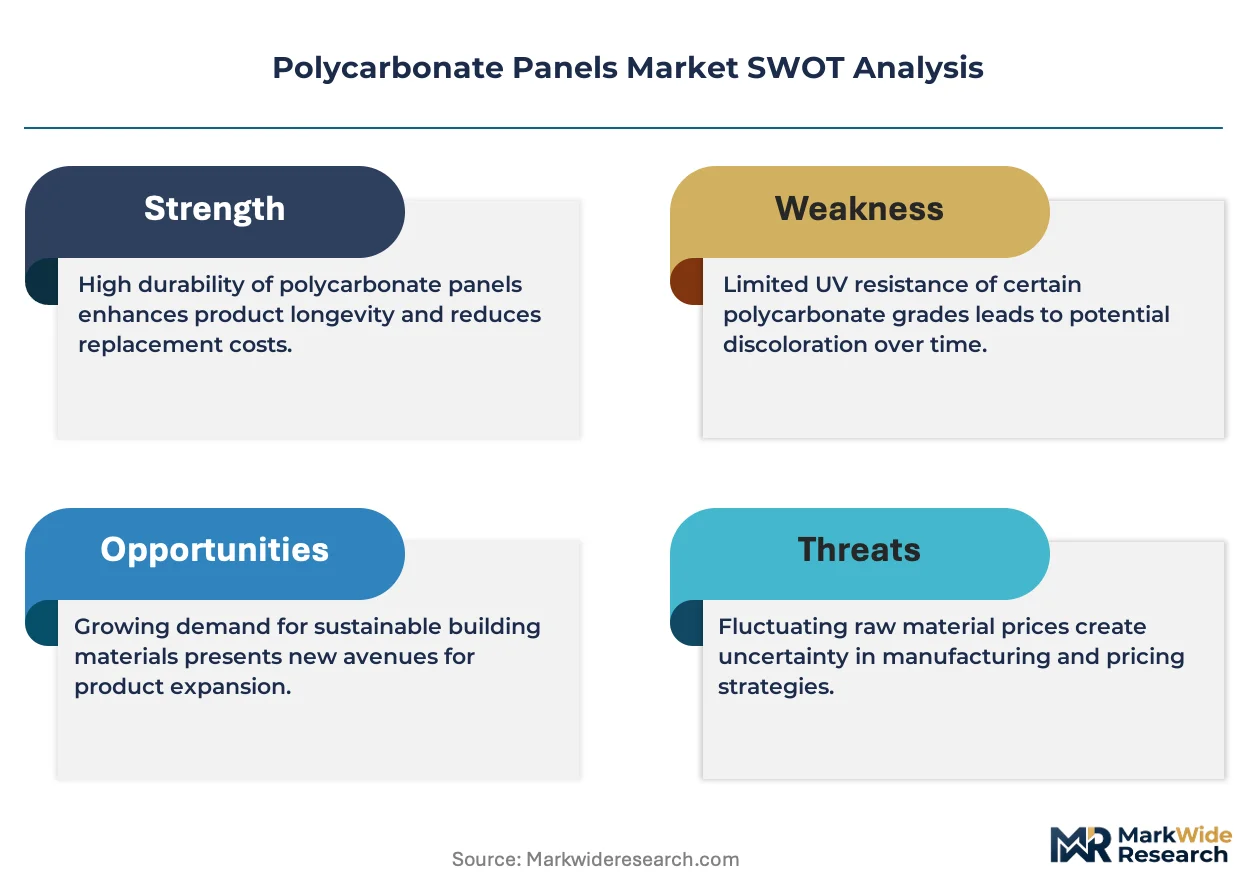
- Raw Material Price Volatility:Panel production costs are directly tied to the price of polycarbonate resins, which are derived from petrochemical feedstocks like bisphenol A (BPA), making margins susceptible to fluctuations in global oil and chemical markets.
- Threat from Substitutes:Acrylic (PMMA) sheets offer a competing transparent glazing solution, often at a lower price point for applications not requiring polycarbonate's superior impact resistance, limiting market penetration in certain segments.
- Surface Durability Limitations:Polycarbonate's lower scratch resistance compared to glass necessitates the application of hard coatings, adding cost and complexity to the manufacturing process, which can be a barrier in highly abrasive environments.
Strategic Opportunities
- Advanced Fire-Retardant Panels:Developing panels that meet stringent fire safety classifications, such as those required for high-rise buildings and public infrastructure, opens a premium-priced market segment currently underserved by standard products.
- Electric Vehicle Components:The push for vehicle lightweighting provides an opportunity for polycarbonate sheets in applications beyond glazing, including battery pack enclosures and interior structural components where impact strength and low weight are critical.
- Circular Economy Integration:Establishing certified recycling streams and developing panels with high recycled content can create a competitive advantage, appealing to contractors and specifiers focused on meeting LEED and BREEAM green building standards.
Industry Challenges
- Complex Compliance Landscape:Manufacturers selling globally face the operational challenge of designing and testing products to meet a matrix of disparate standards, including Europe's CE marking, US ASTM material specifications, and ISO quality certifications.
- Recycling Infrastructure Gaps:The lack of widespread, standardized collection and reprocessing systems for post-consumer polycarbonate construction waste hinders the development of a true circular economy, limiting the supply of high-quality recycled resin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Panels Market |
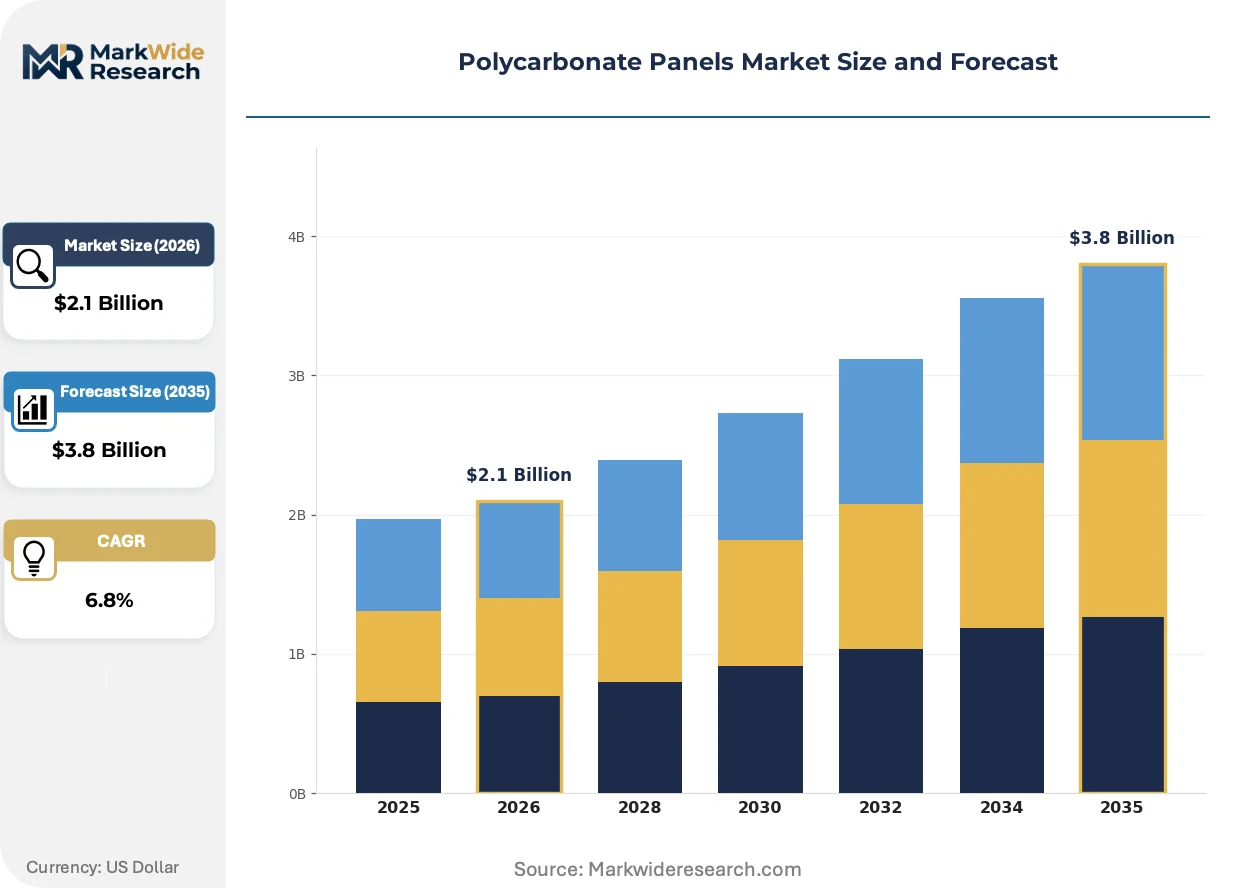
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Multwall Sheets, Corrugated Sheets, Textured Sheets, Twinwall Sheets Technology: Extrusion, Injection Molding, Thermoforming, Compression Molding, Lamination Application: Construction Roofing, Transportation Glazing, Electronics Housing, Solar Panel Covers, Protective Barriers End User Industry: Building Contractors, Vehicle Manufacturers, Electronic Device Makers, Renewable Energy Firms, Safety Equipment Providers |
| Companies Covered | SABIC, Palram Industries, Covestro, Plazit, UG-Plast, Gallina, Polygal, Brett Martin, Koscon Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Panels Market Strategic Shifts & Innovations
Material science advancements are converging with manufacturing process improvements to create panels with highly specialized properties. This evolution allows producers to address niche performance requirements in architecture, transportation, and electronics while navigating new sustainability mandates.
Co-extrusion technology is a key process innovation allowing the creation of multi-layer panels in a single production step. This enables the integration of specific functional layers, such as a UV-protective cap stock or an infrared-blocking core. Architectural and agricultural segments are rapidly adopting these advanced sheets for enhanced durability and climate control, and this process is automating the application of protective coatings, improving consistency and output.
The European Union's Construction Products Regulation (CPR) is reshaping material specification for building envelopes. It establishes harmonized rules and mandates specific performance declarations, including crucial reaction-to-fire classifications known as Euroclasses. This directly affects manufacturers targeting the European commercial construction sector, forcing investment in non-halogenated fire-retardant additives and extensive third-party testing to achieve compliance for roofing and facade systems.
A shift from transactional, project-by-project sales toward specification-driven procurement is altering channel dynamics. Large architectural firms and general contractors increasingly use material libraries and certifications like ISO 9001 as a primary filter, sidelining suppliers who cannot provide extensive performance and sustainability documentation. This pattern is most pronounced in North American and European commercial projects where lifecycle cost and compliance are paramount concerns for developers.
Polycarbonate Panels Market Segmentation
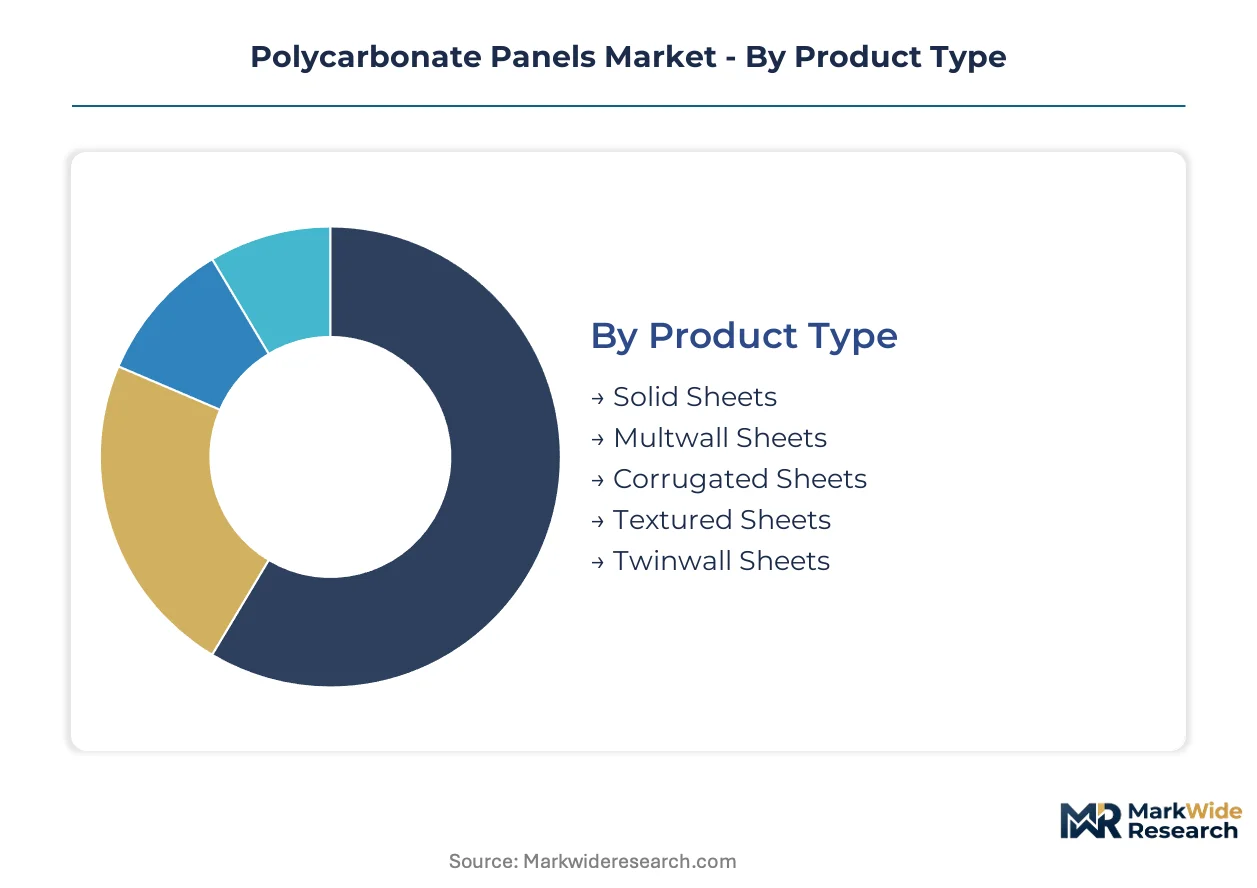
The polycarbonate panels market exhibits diverse requirements across its various segments, necessitating a granular analysis to understand specific demand drivers and competitive landscapes. This segmentation helps identify distinct performance needs and regulatory compliance pathways for different product types and applications.
Product Type:
Compliance with specific product standards, such as ASTM E84 for flame spread or CE marking for construction applications, significantly influences the adoption of different polycarbonate panel types.
- Solid Sheets:Solid sheets offer superior optical clarity and exceptional impact resistance, making them a preferred alternative to glass in high-security environments. Demand concentrates in the transportation sector, particularly for public transit vehicles in Germany and Japan, driven by stringent safety regulations and lightweighting initiatives.
- Multiwall Sheets:Multiwall sheets feature internal flutes that provide excellent thermal insulation properties, crucial for energy efficiency in controlled environments. European building codes, including those aligned with the EU Green Deal, drive significant adoption in conservatory and greenhouse construction across the Netherlands and France.
- Corrugated Sheets:Corrugated sheets provide structural rigidity and are widely used for industrial and agricultural roofing applications in China.
- Textured Sheets:Textured sheets diffuse light, reducing glare, and are specified for privacy screens and decorative panels in commercial interiors.
- Twinwall Sheets:Twinwall sheets, a subset of multiwall, offer a balance of insulation and light transmission for general glazing in residential projects.
Leading the category by volume: Multiwall Sheets. Growing fastest: Solid Sheets.
Technology:
The choice of manufacturing technology often dictates the achievable cost structure and the final panel properties, influencing market competitiveness.
- Extrusion:Extrusion is the primary method for producing continuous polycarbonate sheets, offering high volume output and cost efficiency for standard panel forms. This process supports the mass production of multiwall and solid sheets for construction projects across Southeast Asia.
- Injection Molding:Injection molding enables the creation of complex, precisely formed polycarbonate components with tight tolerances, ideal for intricate parts. This technology is critical for producing specialized lenses and housing components for electronics in South Korea and the US.
- Thermoforming:Thermoforming shapes pre-existing polycarbonate sheets into custom forms for skylights and protective covers.
- Compression Molding:Compression molding is employed for high-strength, thick-walled components requiring superior structural integrity.
- Lamination:Lamination combines multiple layers of polycarbonate or other materials to enhance ballistic resistance or optical performance.
Extrusion technology accounts for the largest production volume, while injection molding is gaining adoption for high-precision applications.
Application:
Different applications require distinct performance attributes, driving material selection based on end-user specifications and operational demands.
- Construction Roofing:Polycarbonate panels in construction roofing provide durable, lightweight, and often translucent solutions for industrial buildings and commercial structures. Significant demand stems from large-scale infrastructure developments in India and Brazil, where daylighting is a priority.
- Transportation Glazing:Transportation glazing utilizes polycarbonate for its high impact resistance and lightweight properties, contributing to vehicle safety and fuel efficiency. Automakers in Germany and the US specify these panels for bus windows and train interiors, adhering to strict safety standards like ECE R43.
- Electronics Housing:Electronics housing benefits from polycarbonate's durability and electrical insulation for device protection.
- Solar Panel Covers:Solar panel covers protect photovoltaic cells from environmental damage while maximizing light transmission.
- Protective Barriers:Protective barriers leverage polycarbonate's strength for security screens and machine guards in industrial settings.
Construction Roofing generates the most significant revenue contribution, with Transportation Glazing exhibiting strong growth potential.
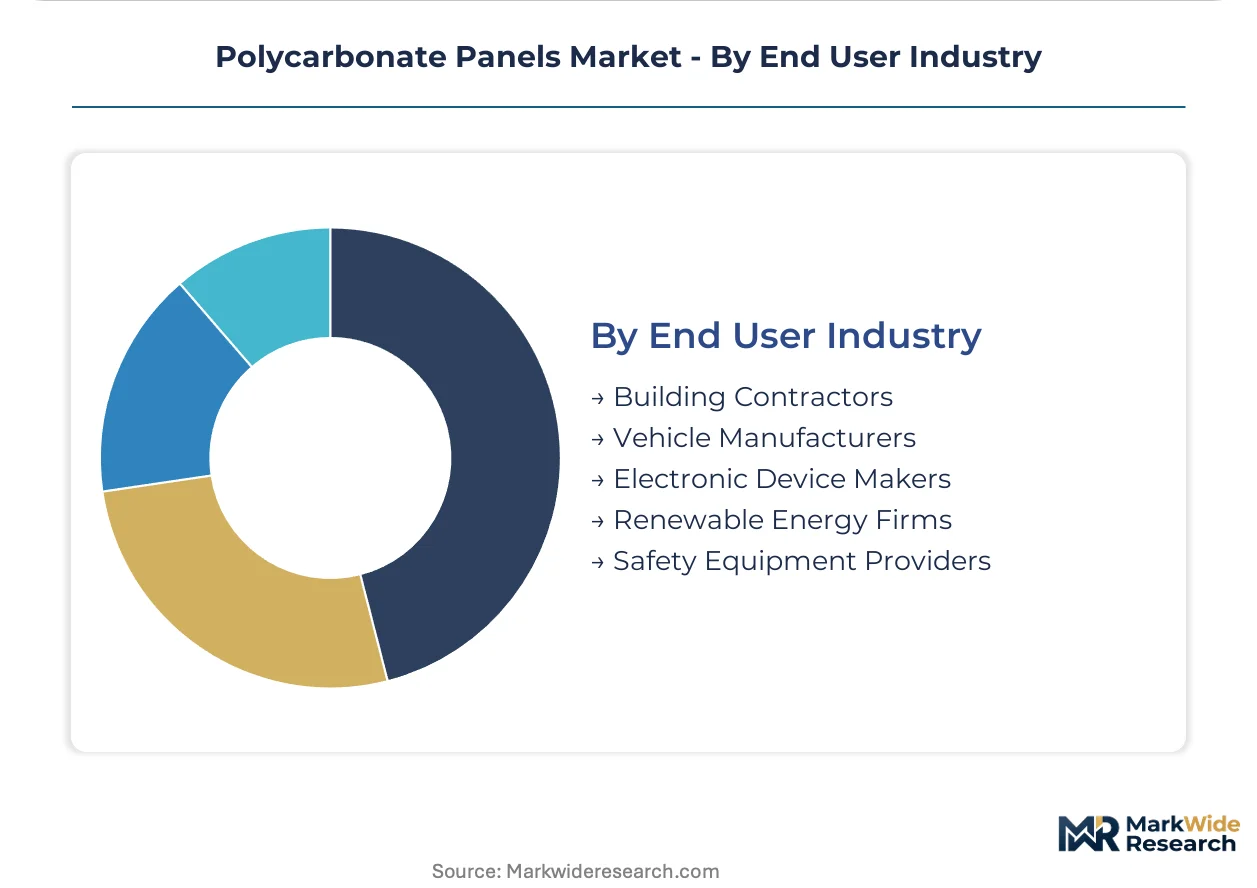
End User Industry:
The specific needs and purchasing power of each end-user industry influence demand patterns and potential profit margins for panel manufacturers.
- Building Contractors:Building contractors represent a high-volume segment, specifying polycarbonate panels for roofing, cladding, and daylighting systems in residential and commercial projects. Procurement decisions are often influenced by cost-effectiveness and compliance with local building codes, such as those in Australia and Canada.
- Vehicle Manufacturers:Vehicle manufacturers require specialized, high-performance polycarbonate sheets for windows, partitions, and interior components, prioritizing impact resistance and lightweight characteristics. This segment demands materials meeting automotive standards like ISO 16949 for suppliers in Japan and the UK.
- Electronic Device Makers:Electronic device makers use polycarbonate for durable, lightweight enclosures and displays in consumer electronics.
- Renewable Energy Firms:Renewable energy firms utilize polycarbonate for protective covers on solar panels and wind turbine components.
- Safety Equipment Providers:Safety equipment providers incorporate polycarbonate into helmets, face shields, and machine guards for impact protection.
Building Contractors form a mature, high-volume market, while Vehicle Manufacturers represent a segment with evolving material requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hubs across China anchor significant demand for polycarbonate panels, particularly for large-scale construction projects. These regions benefit from sustained government investment in infrastructure development. The Yangtze River Delta, a key economic zone, sees extensive use of these panels in commercial and industrial roofing applications.
China
China's robust infrastructure expansion drives demand for corrugated and solid polycarbonate panels in industrial and agricultural roofing. The national dual carbon goals encourage energy-efficient building materials. Manufacturing centers in the Yangtze River Delta concentrate production and consumption for commercial structures.
Germany
Germany's automotive sector specifies solid polycarbonate sheets for lightweight, impact-resistant transportation glazing in public transit vehicles. ECE R43 safety standards mandate high-performance materials for vehicle components. Bavarian automotive clusters, such as Munich and Stuttgart, are key specifiers for bus and train interiors.
United States
United States building codes increasingly favor durable and lightweight materials for protective barriers and architectural glazing. ASTM standards guide material selection for polycarbonate panels in diverse applications. Major urban centers like New York City and Los Angeles drive demand for high-security and aesthetic installations.
India
Indian infrastructure developments create substantial volume demand for polycarbonate roofing panels, particularly for daylighting in industrial and commercial buildings. The Bureau of Indian Standards (BIS) influences material specifications for construction projects. Delhi-NCR and Mumbai regions show strong adoption in new commercial complexes.
Netherlands
Netherlands' advanced horticulture sector significantly adopts multiwall polycarbonate sheets for energy-efficient greenhouse and conservatory construction. EU Green Deal objectives promote thermal insulation in building envelopes. The Westland region, a global leader in greenhouse farming, extensively utilizes these panels for climate control.
Polycarbonate Panels Market Key Industry Players
Premium-margin players sit above commodity-margin players across the polycarbonate panel market, differentiated by product performance and application specificity. The market structure exhibits a tiered consolidation, with a few large chemical producers supplying high-purity resins and specialized panel manufacturers serving niche segments. Strategic archetypes include integrated material scientists, high-volume sheet extruders, and application-specific solution providers. Capacity expansion and technology licensing are dominant competitive moves.
SABIC, a Saudi Arabian multinational chemical manufacturing company, exemplifies the integrated material supplier archetype, leveraging its vast chemical production scale to provide high-purity resins for premium architectural glazing. This positioning allows them to serve demanding applications requiring superior optical clarity and durability. German-based Covestro AG occupies a distinct position as an advanced material science specialist, developing polycarbonate panels with specific properties like enhanced fire resistance or superior thermal insulation. Their focus is on high-performance solutions for specialized industrial and transportation needs. Palram Industries Ltd., an Israeli-headquartered company, anchors the high-volume multiwall and corrugated sheet segments, competing effectively in agricultural and general construction applications across various geographies. They provide cost-effective solutions for widespread use.
| Leading Market Players |
|---|
| SABIC |
| Palram Industries |
| Covestro |
| Plazit |
| UG-Plast |
| Gallina |
| Polygal |
| Brett Martin |
| Koscon Industrial |
| Others |
Cost & Logistics Intelligence
The clear performance divergence between premium architectural glazing and high-volume general construction panels shapes both pricing strategies and supply chain configurations. This bifurcation necessitates distinct market approaches for manufacturers.
Pricing Analysis
Value-based pricing for advanced panels ties directly to enhanced fire resistance and superior thermal insulation performance. The dominant pricing model for high-performance panels is project-based, while high-volume sheets use per-unit transactional pricing. CE marking and ASTM certification levels drive significant price differentiation, with raw material price volatility from petrochemical feedstocks creating persistent margin pressure. Building contractors for agricultural roofing exhibit the highest price sensitivity, whereas vehicle manufacturers prioritize performance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate efficient delivery of polycarbonate panels to construction sites. Supply concentration centers in China for high-volume sheets and in Saudi Arabia for high-purity resins, drawing from bisphenol A (BPA) and other petrochemical feedstocks. Commodity price volatility represents a structural risk. Downstream distribution runs through specialized building material suppliers and direct sales to large industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycarbonate panels market operates as a supply-constrained environment, with specialized resin production capacity serving as a primary bottleneck propping pricing for high-performance applications. This constraint influences strategic decisions across the value chain.
For Market Incumbents: Anchor market share by deepening vertical integration into polycarbonate resin production, securing critical raw material supply. Invest in advanced co-extrusion technology to enhance product differentiation against substitute materials like acrylic. Focus R&D on non-halogenated fire-retardant additives to meet evolving fire safety codes, leveraging ISO 9001 certification to reinforce quality. This strategy defends against margin pressure from volatile input costs.
For New Entrants and Emerging Players: Enter via niche applications requiring specific performance attributes, such as advanced fire resistance or high recycled content panels. Target localized agricultural projects in regions with less stringent product standards, or small-scale custom architectural projects. A go-to-market angle focused on sustainability certifications like LEED and BREEAM can attract environmentally conscious specifiers. This approach bypasses direct competition with high-volume players.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized material science firms with proprietary technologies for enhanced fire resistance or advanced thermal insulation. The market demonstrates long-term viability over a 5-10 year window, driven by sustained demand in construction and transportation. Acquisition targets should possess strong intellectual property and certified recycling streams. A key signal to watch is increasing M&A activity for companies with established circular economy integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures supply for growing Asian infrastructure projects, reducing lead times. |
| Green Manufacturing Transition | Attracts specifiers focused on LEED and BREEAM standards. |
| Long-term Supply Agreement | Stabilizes raw material costs against petrochemical market volatility. |
| Advanced Material R&D | Develops panels meeting stricter fire safety codes for premium markets. |
| Circular Economy Program | Establishes certified recycling streams for post-consumer polycarbonate waste. |
Research Approach
Industry association reports, government publications detailing EU Green Deal objectives, and company financial filings formed the secondary backbone of this analysis. Primary interviews with R&D directors, procurement managers at vehicle manufacturers, and building contractors provided crucial qualitative insights. This approach facilitated a robust bottom-up data collection, validated through top-down market sizing and competitive intelligence.
Bottom-up analysis of end-use applications, validated by top-down market sizing, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were extrapolated from historical trends and projected demand drivers like infrastructure project pipelines and automotive production forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of geopolitical instability or rapid substitute material emergence. These forecasts reflect assumptions regarding current regulatory trajectories and technological development rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
United Kingdom Foam Insulation Market
Industrial Materials
Global Metal Anodizing Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
Global Friction Products and Materials Market
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Welding Consumables Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Metal Molds Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Tooling Board Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market