
 Gypsum Plaster Market | 2026-2036
Gypsum Plaster Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum Plaster Market Outlook
Residential construction is shifting toward faster interior finishing systems, pulling demand away from traditional cement-based renders toward gypsum-based alternatives. Saint-Gobain leverages its European formulation expertise to supply high-performance finishing plasters across multiple continents. Knauf Gips KG anchors its position through captive gypsum reserves and integrated wall-system distribution. Beijing New Building Materials dominates domestic supply chains in China while extending its technical plaster portfolio into Southeast Asian markets.
Gypsum plaster consists primarily of calcium sulfate hemihydrate (CaSO₄·½H₂O), produced through controlled calcination of raw gypsum at approximately 150–180°C to achieve workability and set-time predictability; it serves as an interior surfacing material that provides fire resistance, acoustic dampening, and smooth substrate preparation for paint or wallpaper. Finishing plaster captures premium margin pools where ultra-smooth aesthetic standards command price premiums in commercial fit-outs. Ready-mix formulations are expanding fastest as site-labor constraints and quality consistency requirements intensify across residential and infrastructure verticals. Powder form still occupies the largest volume share due to lower transport costs and extended shelf stability in price-sensitive developing markets.
China's GB standards and SAMR enforcement shape product composition limits and factory certification requirements for domestic gypsum plaster manufacturers. India's BIS certification and PLI scheme for building materials are redirecting procurement toward domestically produced, quality-assured formulations in government-backed housing projects. Etex Group navigates European REACH compliance and CE marking obligations while positioning its specialty plasters for energy-efficient retrofit demand. Stakeholders must monitor how evolving fire-safety and carbon-footprint regulations in key construction markets reshape material specification criteria and supplier qualification thresholds.
Market Dynamics
The gypsum plaster market is being fundamentally restructured by the acceleration of ready-mix formulations, which compress site labor requirements while tightening quality consistency across large-scale residential and commercial projects in emerging economies.
Growth Catalysts
- India's PLI scheme for construction products:Government-backed incentives are redirecting procurement toward domestically manufactured, quality-assured gypsum plaster in urban housing programs.
- Site-labor constraints:Skilled plasterer shortages across Southeast Asian construction markets are pulling demand toward pre-formulated, predictable-setting products that reduce application variability.
- Fire-resistance specifications:Evolving building codes in commercial real estate are mandating interior surfacing materials with certified fire-retardant properties, favoring gypsum-based systems over cement renders.
Market Restraints
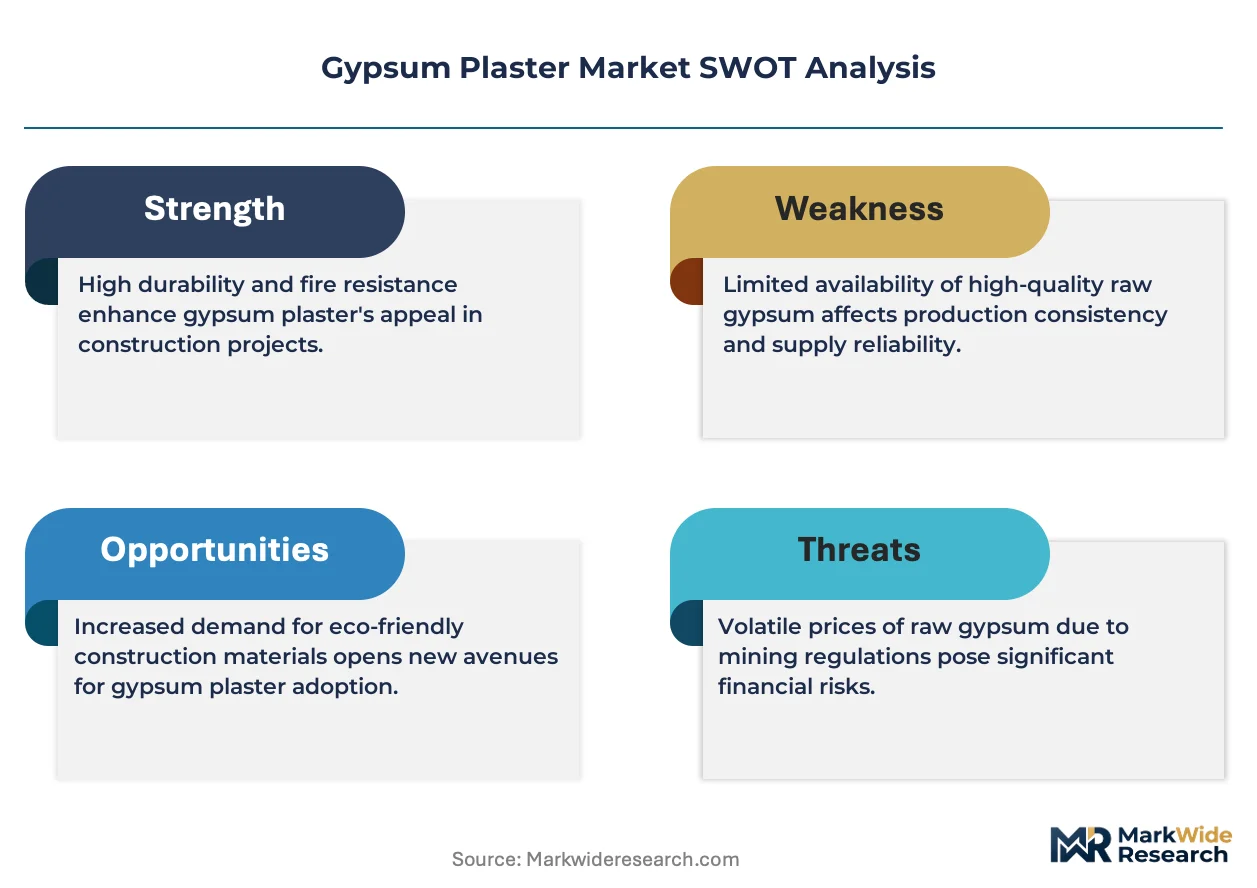
- Raw gypsum supply concentration:Captive reserves held by integrated manufacturers create input cost volatility for independent compounders lacking upstream control.
- Cement-based render substitution:Traditional cement-lime plasters retain cost advantages in exterior and wet-zone applications, limiting gypsum penetration in climate-exposed construction.
- Transport economics of ready-mix:Water-weight in wet formulations multiplies logistics costs, constraining distribution radius and market reach beyond manufacturing clusters.
Strategic Opportunities
- Retrofit energy-efficiency demand:European renovation wave programs are creating specification pull for specialty plasters with thermal-acoustic performance in building envelope upgrades.
- Prefabricated wall system integration:Off-site construction modules require factory-applied interior finishes, opening channel partnerships with modular housing producers.
- Southeast Asian urbanization corridors:Vietnam and Indonesia's commercial real estate expansion presents underpenetrated demand for premium finishing plasters in hospitality and office fit-outs.
Industry Challenges
- Skilled applicator certification gaps:Inconsistent training standards across developing markets produce installation quality variation that damages product reputation and triggers warranty claims.
- Multi-jurisdiction compliance complexity:Manufacturers supplying cross-border must navigate divergent GB standards, BIS certification, and REACH obligations simultaneously, extending product registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum Plaster Market |
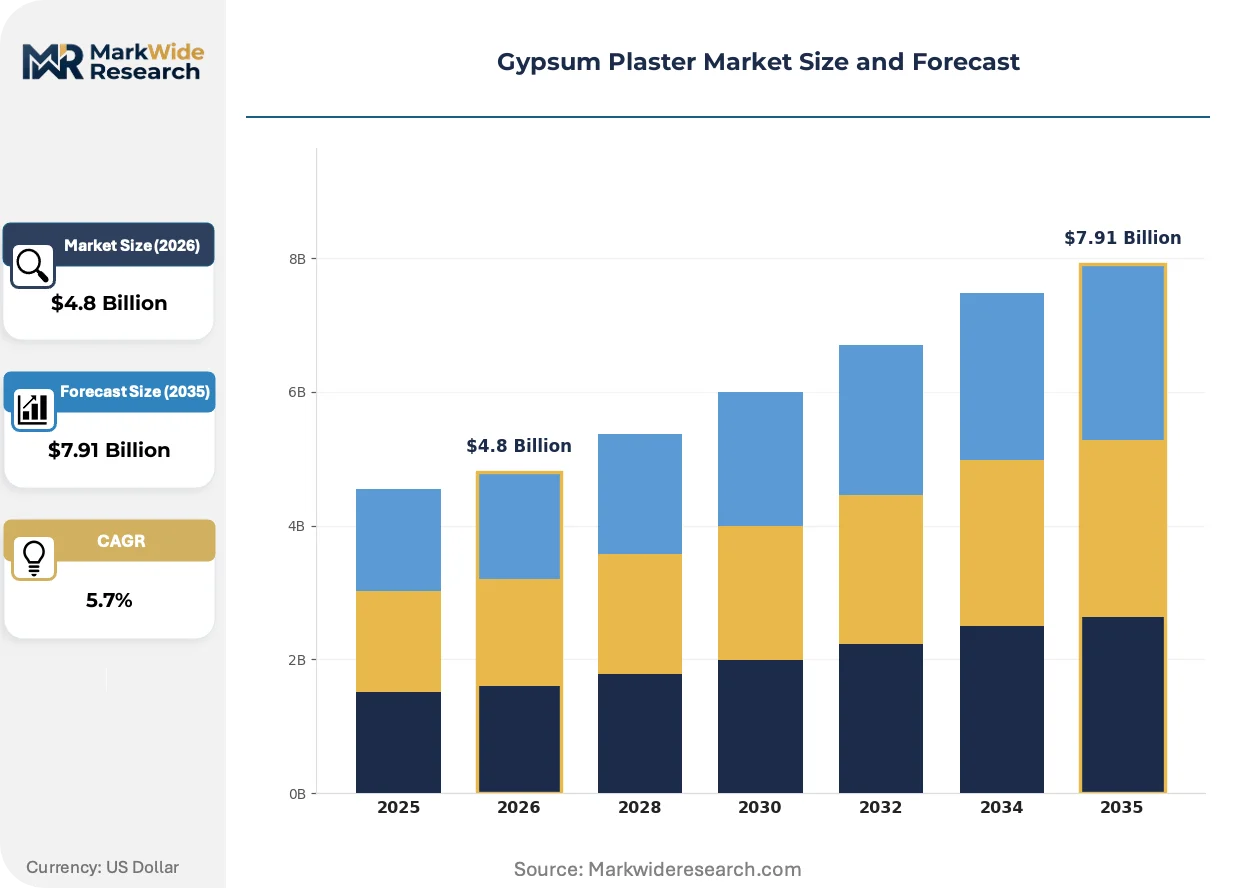
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finishing Plaster, Intermediate Plaster, Bonding Plaster, Molding Plaster End User: Residential, Commercial, Industrial, Infrastructure Application: Interior Walls, Ceilings, External Walls, Decorative Elements Form: Powder, Ready Mix, Pre-mixed, Spray |
| Companies Covered | Georgia-Pacific Gypsum II LLC, YOSHINO GYPSUM CO., LTD, Saint-Gobain, Etex Group, American Gypsum Company LLC, Knauf Gips KG, National Gypsum Company, Beijing New Building Materials, USG Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum Plaster Market Strategic Shifts
Formulation chemistry and application logistics are converging to redefine how interior surfacing materials are specified, procured, and deployed across construction value chains.
Lightweight aggregates and microsphere additives are expanding into high-rise commercial projects where dead-load reduction directly impacts structural engineering economics. Developers in India's Mumbai and Bangalore corridors specify these formulations for tower interiors, compressing material transport costs and accelerating floor-cycle times. The technology is expanding into mid-rise residential segments as price premiums erode with manufacturing scale.
China's GB standards for building materials, enforced through SAMR factory certification protocols, are tightening compositional limits on heavy-metal content and crystalline silica exposure in finished plaster products. Domestic manufacturers must retest legacy formulations, while importers face extended conformity assessment timelines. India's BIS certification requirements are producing parallel compliance investments as the PLI scheme ties incentives to quality-assured domestic production.
Large residential developers are consolidating specification authority away from subcontractor discretion toward centralized procurement departments with pre-approved vendor lists. This channel compression rewards suppliers with national distribution networks and penalizes regional compounders lacking scale. The pattern is most visible in China's tier-one cities and India's government-backed affordable housing programs, where developer concentration enables volume commitments in exchange for price positioning.
Gypsum Plaster Market Segmentation
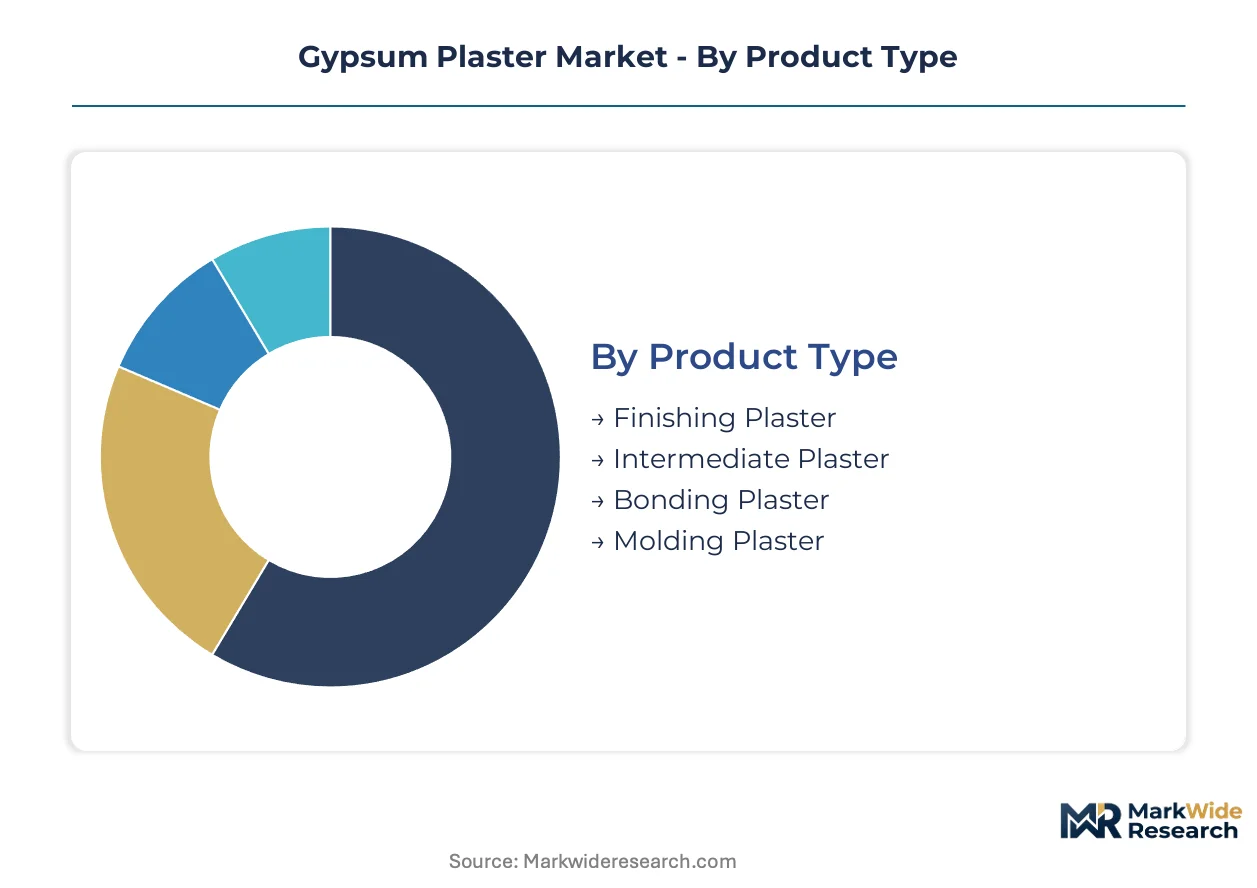
Segmentation in gypsum plaster markets reveals how specification authority shifts between architects, contractors, and procurement departments. Each dimension—product grade, end-use vertical, application surface, and physical form—carries distinct margin structures and channel access requirements that reshape supplier strategies.
Product Type:
Upgrade cycles in interior finishing systems drive specification migration from basic substrates toward performance-graded surfaces that compress total project timelines.
- Finishing Plaster:Ultra-fine calcium sulfate hemihydrate formulations achieve surface tolerances below 0.5mm deviation across commercial fit-outs in Mumbai and Bangalore. Premium aesthetic standards in hospitality and corporate interiors command price positioning that rewards manufacturers with consistent batch-to-batch color stability.
- Intermediate Plaster:Medium-density substrates bridge leveling compounds and final finish coats in high-rise residential towers across China's tier-one cities. Dead-load reduction specifications in tower construction favor lightweight variants that cut structural steel requirements.
- Bonding Plaster:High-adhesion base coats anchor subsequent layers to concrete and blockwork substrates in renovation applications.
- Molding Plaster:Rapid-setting formulations enable ornate cornice and ceiling rose production for heritage restoration projects.
Finishing plaster sits at the top of the volume ranking, with bonding plaster climbing the fastest as retrofit activity accelerates across aging building stocks.
End User:
Cost tier differentiation separates specification authority between centralized procurement departments and decentralized subcontractor discretion.
- Residential:Government-backed affordable housing programs in India concentrate demand through pre-approved vendor lists that penalize regional compounders lacking national distribution scale. Ready-mix formulations gain share fastest as site-labor constraints intensify across Southeast Asian construction corridors.
- Commercial:Fire-resistance certifications and acoustic performance specifications dominate office and retail fit-outs where developer concentration enables volume commitments. Large mixed-use projects in Vietnam and Indonesia specify gypsum systems for interior partition assemblies that must meet multi-hour fire ratings.
- Industrial:Chemical-resistant and anti-static formulations serve manufacturing facilities with specialized contamination control requirements.
- Infrastructure:Transit tunnels and station interiors specify gypsum-based fire protection systems for egress corridor lining.
Residential captures the largest revenue pool, while commercial expands most quickly as urban office construction rebounds across emerging Asian markets.
Application:
Volume concentration varies sharply by surface orientation and exposure conditions that determine formulation chemistry and installation methodology.
- Interior Walls:Vertical surfacing consumes the majority of gypsum plaster volume across residential and commercial verticals, with smooth substrate preparation for paint or wallpaper driving specification consistency. India's urban housing programs specify gypsum interior finishes for millions of standardized dwelling units.
- Ceilings:Overhead application demands lightweight formulations with extended open time that accommodate slower placement rates without premature setting. High-rise towers in China's Pearl River Delta specify these systems for soffit finishing that accelerates floor-cycle times.
- External Walls:Limited penetration due to moisture sensitivity; specialized water-resistant variants serve protected exterior applications in arid climates.
- Decorative Elements:Architectural moldings and feature walls require rapid-setting, high-definition surface reproduction capability.
Interior walls dominate absolute tonnage, with ceilings gaining share fastest as tower construction intensifies across dense urban corridors.
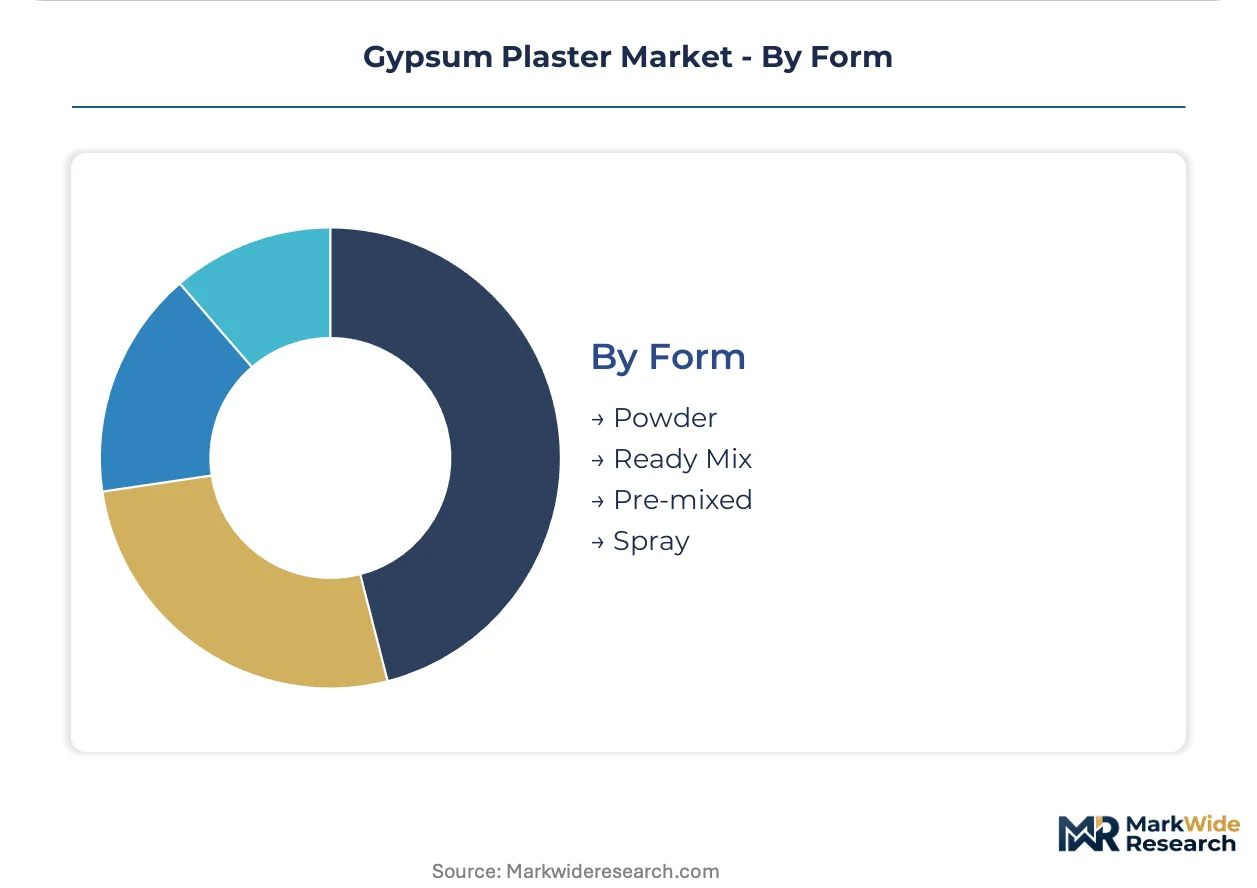
Form:
Supply concentration around manufacturing clusters shapes distribution economics and market reach for each physical state of gypsum plaster delivery.
- Powder:Dry-mix formulations retain the largest volume share due to extended shelf stability and lower transport costs in price-sensitive developing markets. Bagged products serve remote construction sites beyond ready-mix distribution radius in India's secondary cities.
- Ready Mix:Pre-hydrated wet formulations eliminate on-site water addition variability and compress skilled labor requirements. Site-labor shortages across Indonesia and Vietnam pull demand toward predictable-setting products that reduce application defects and warranty exposure.
- Pre-mixed:Factory-blended compounds with proprietary additive packages target premium renovation segments.
- Spray:Mechanically applied systems maximize coverage rates in large-scale commercial and infrastructure projects.
Powder maintains volume leadership, while ready-mix demonstrates the steepest expansion trajectory as labor constraints reshape construction economics across emerging economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta industrial corridor concentrates the densest gypsum plaster manufacturing capacity, feeding construction demand across Asia-Pacific urbanization corridors while regulatory tightening reshapes quality benchmarks.
China
Urban housing programs in tier-one cities absorb volume for interior wall finishing, while SAMR factory certification protocols enforce GB standards on heavy-metal content limits. Manufacturers in the Pearl River Delta retest legacy formulations to maintain market access.
India
Government-backed affordable housing drives standardized dwelling unit construction, with BIS certification requirements redirecting procurement toward quality-assured domestic production. Mumbai and Bangalore developers specify lightweight formulations for high-rise tower interiors.
United States
Commercial retrofit activity and fire-resistance code evolution sustain demand for specialty interior surfacing materials. EPA and OSHA exposure guidelines influence formulation chemistry in manufacturing clusters across the Southeast and Southwest construction corridors.
Germany
Energy-efficient renovation wave programs create specification pull for thermal-acoustic performance plasters in building envelope upgrades. REACH compliance and CE marking obligations structure product registration timelines for suppliers serving cross-border European markets.
Vietnam
Commercial real estate expansion in hospitality and office fit-outs generates underpenetrated demand for premium finishing plasters. Site-labor constraints across Southeast Asian construction markets accelerate uptake of ready-mix formulations with predictable setting characteristics.
Gypsum Plaster Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers scale ready-mix production to capture labor-constrained construction markets. The vendor base organizes around three strategic archetypes: integrated miners with captive gypsum reserves, formulation specialists with national distribution networks, and regional compounders serving price-sensitive secondary cities. M&A activity and backward integration into raw material sourcing represent the primary competitive vectors reshaping supplier positioning.
Among European-originated building materials groups, Saint-Gobain and Knauf Gips KG occupy positions exemplifying integrated supply chain control, while Etex Group represents the specialist tier navigating multi-jurisdiction compliance complexity. Beijing New Building Materials anchors the Asia-Pacific manufacturing concentration with domestic supply chain dominance extending into Southeast Asian export markets.
| Leading Market Players |
|---|
| Georgia-Pacific Gypsum II LLC |
| YOSHINO GYPSUM CO., LTD |
| Saint-Gobain |
| Etex Group |
| American Gypsum Company LLC |
| Knauf Gips KG |
| National Gypsum Company |
| Beijing New Building Materials |
| USG Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap compounders across India's secondary cities anchor supply behavior through informal credit networks and seasonal inventory cycles, while their pricing discipline erodes under pressure from national distributors consolidating specification authority in government housing programs. Captive gypsum reserves held by integrated European and Chinese producers create asymmetric input-cost exposure that independent formulators offset through regional freight arbitrage and bulk procurement alliances.
Pricing Analysis
Distributor margin compression in India's tier-two and tier-three cities separates price-sensitive regional compounders from premium-positioned national suppliers with BIS-certified product lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with government-backed housing projects extracting bulk discounts that narrow spreads at the standard tier. Cost compression in economy-grade powder formulations intensifies because cement-render substitution threats cap ceiling prices in climate-exposed construction zones. Residential developers in affordable housing programs exhibit highest price sensitivity, while hospitality fit-out contractors in Vietnam and Indonesia absorb premiums for color-stable finishing plasters.
Supply Chain Analysis
GB standards and SAMR factory certification protocols gate market access for imported formulations, forcing retesting investments that extend product registration timelines and concentrate procurement relationships with domestic certificate holders. Manufacturing gravity centers on China, India, and Germany, with raw gypsum extraction and synthetic gypsum from flue-gas desulfurization feeding calcination capacity clusters. Supply chain risk hinges on single-source vulnerability where captive reserves held by Knauf and Saint-Gobain create input cost volatility for independent compounders lacking upstream control. Distribution runs through national building-material distributors with pre-approved vendor lists that compress regional compounder access to large-scale residential projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play where India's PLI scheme incentives and China's GB compliance costs create divergent margin structures for identical formulation investments. Regulatory friction in cross-border certification multiplies effective capital requirements for suppliers attempting simultaneous market penetration.
For Market Incumbents: Cement specification authority through backward integration into synthetic gypsum sourcing from coal-power FGD streams, securing input cost stability against captive-mineral competitors. Defend channel position by locking multi-year supply agreements with India's centralized affordable housing procurement departments before PLI scheme qualification windows narrow. Capacity addition in Vietnam's Mekong Delta corridor captures Southeast Asian labor-constrained demand while Chinese manufacturers face extended SAMR recertification cycles. For New Entrants and Emerging Players: Begin with ready-mix formulation partnerships in Indonesia's secondary cities where site-labor shortages outpace established distribution networks. The most penetrable segment sits in mid-rise residential towers across Vietnam's Da Nang and Indonesia's Surabaya corridors, where developer concentration remains below threshold for national supplier direct contracts. A go-to-market angle through equipment-leasing bundled with product supply reduces upfront capital barriers and locks recurring revenue through consumable attachment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional Indian compounders with BIS certification gaps that PLI scheme technical assistance could close within a single investment cycle. Long-term viability framing centers on synthetic gypsum feedstock access as natural reserve depletion and carbon-footprint regulations reshape input economics. Acquisition target archetype: mid-scale formulators with existing SAMR or BIS certificates and underutilized capacity in secondary cities. The signal to watch is consolidation velocity in India's affordable housing procurement as developer concentration crosses threshold for direct-supplier preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Gypsum | FGD sourcing from coal-power plants secures input cost stability against captive mineral reserves. |
| Ready-Mix Capacity Expansion | Wet formulation investments capture labor-constrained construction markets across Southeast Asian urban corridors. |
| BIS Certification Investment | Quality-assured domestic production qualification unlocks PLI scheme incentives in India's government housing programs. |
| Prefabricated Wall System Partnership | Factory-applied finish integration opens channel access to modular housing producers in European renovation markets. |
| Lightweight Aggregate Formulation Development | Dead-load reduction specifications in Mumbai and Bangalore tower construction command price premiums. |
Study Parameters
Multiple input streams — technical discussions with plant managers at calcination facilities, procurement leads at Indian affordable housing developers, and distribution channel partners across Southeast Asia — were reconciled against customs trade data, BIS certification registries, and SAMR factory audit disclosures. Secondary validation drew from SEC filings of listed building materials groups, European REACH registration databases, and project pipeline tracking across China's tier-one city construction bureaus. Bottom-up volume estimates from application-specific consumption rates and top-down market sizing from production capacity utilization were triangulated to constrain forecast variance.
Data-stream reconciliation across product grade, end-use vertical, physical form, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted demand modeling that linked urban housing program targets to per-unit plaster consumption coefficients. Industry-specific forecast inputs included synthetic gypsum supply growth from coal-power FGD retrofits and skilled plasterer shortage indices across Southeast Asian construction labor markets.
Caveats apply where India's PLI scheme incentive revisions or China's GB standards enforcement intensity could materially shift the outlook for domestic manufacturing competitiveness. Forecasts reflect assumptions around construction labor availability and synthetic gypsum feedstock expansion that warrant reassessment if coal-power phaseout accelerates or immigration policy reshapes workforce composition. A model refresh is warranted upon material change in cross-border certification reciprocity agreements between India, China, and ASEAN markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Encapsulated Gaskets/Seals Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
North America Activated Carbon Market