
 United Kingdom Foam Insulation Market | 2026-2036
United Kingdom Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Foam Insulation Market Analytics
Retrofit contracting revenue is rewriting profit allocation across the United Kingdom foam insulation value chain. Kingspan Group leverages its rigid board manufacturing scale to dominate distribution through merchant channels. BASF SE anchors the upstream polyol supply with integrated chemical production at its UK facilities. Huntsman International LLC differentiates through spray-applied system formulations tailored to heritage building envelopes.
United Kingdom foam insulation encompasses thermoset and thermoplastic cellular materials engineered to reduce thermal transmittance, with polyurethane foams achieving lambda values below 0.025 W/mK through closed-cell structures blown with pentane or hydrofluoroolefin agents. These materials primarily serve to minimise space-conditioning energy loads in building envelopes and industrial process equipment. Polyurethane foam leads product type value generation due to its superior R-value per inch and adhesion properties in cavity wall applications. Spray applied installation methods are expanding fastest among retrofit contractors seeking to minimise disruption in occupied dwellings. Polystyrene foam occupies the economy tier for below-grade and perimeter insulation where moisture resistance outweighs thermal performance premium.
The Building Regulations Approved Document L, enforced by local authority building control bodies, mandates escalating U-value thresholds that directly specify minimum foam thicknesses in renovation work. BSI Kitemark certification and BBA agrément certificates govern product acceptance for warranty-backed installations by major lenders and insurers. The Future Homes Standard trajectory will eliminate fossil fuel heating in new builds, intensifying demand for high-performance envelope insulation. Stakeholders must monitor PAS 2035 retrofit coordinator requirements and their impact on contractor accreditation costs and project viability.
Market Dynamics
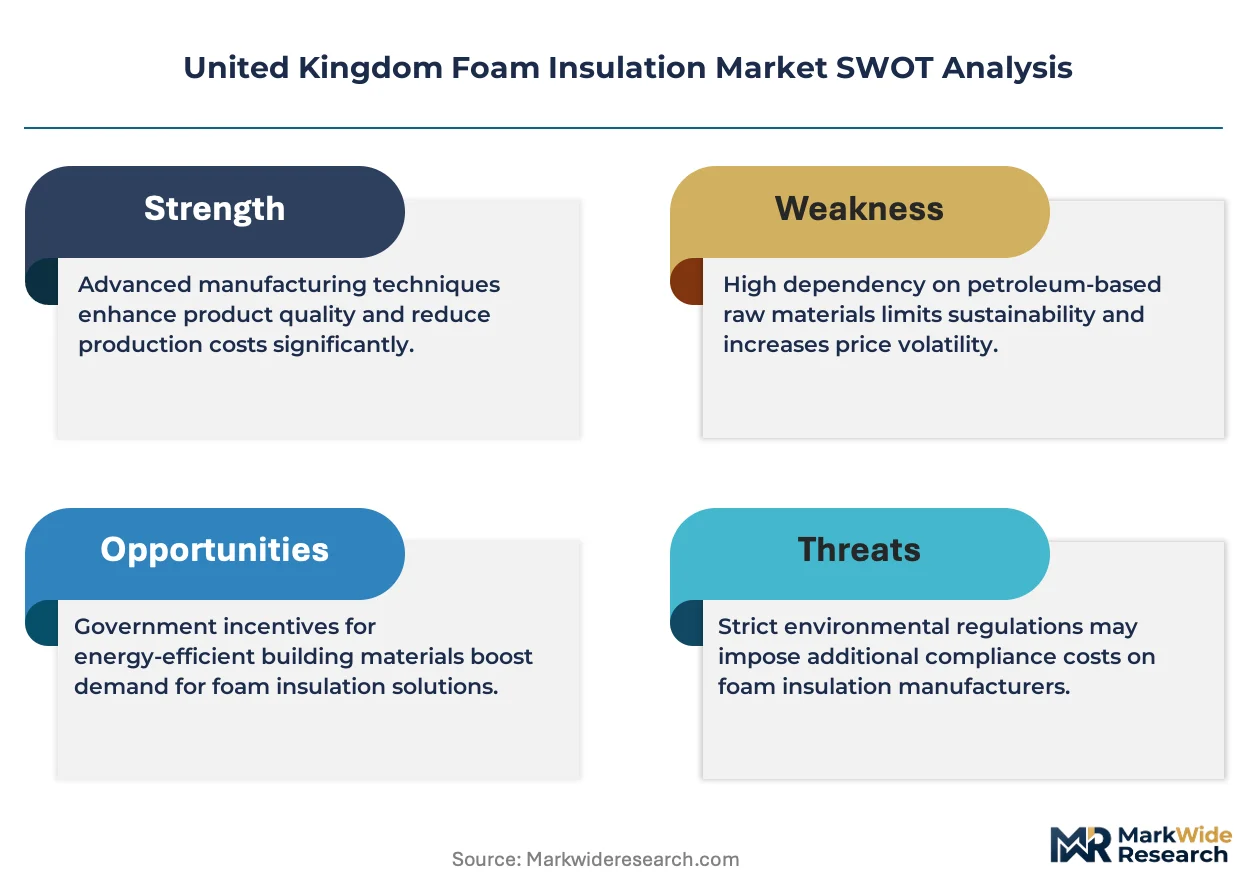
The United Kingdom foam insulation market is being structurally reshaped by the PAS 2035 retrofit coordinator mandate, which imposes professional accreditation requirements on contractors executing energy efficiency upgrades in existing dwellings. This regulatory layer is compressing project timelines while elevating compliance costs across the value chain.
Growth Catalysts
- Future Homes Standard:The trajectory toward fossil fuel heating elimination in new builds is mandating envelope performance thresholds that only high-lambda foam systems can satisfy cost-effectively.
- Social housing retrofit programmes:Local authority-led renovation schemes across Midlands and northern England are aggregating demand into multi-dwelling contracts that favor spray-applied installation methods.
- Closed-cell polyurethane chemistry:Advancements in pentane and hydrofluoroolefin blowing agents are delivering sub-0.025 W/mK thermal conductivity without the regulatory burden of legacy hydrofluorocarbon formulations.
Market Restraints
- Polyol feedstock volatility:Crude oil derivative pricing fluctuations directly compress polyurethane foam margins, with producers lacking backward integration into chemical precursors bearing disproportionate exposure.
- Heritage building envelope constraints:Listed structure regulations prohibit cavity wall intervention in approximately 20% of England's pre-1919 housing stock, excluding spray foam application entirely.
- Mineral wool substitution in below-grade applications:Polystyrene foam faces displacement by inorganic insulation where fire performance certification outweighs moisture resistance requirements.
Strategic Opportunities
- PAS 2035 coordinator services:Accreditation bottlenecks are creating white space for specialized compliance consultancies to capture margin from traditional contracting firms lacking in-house retrofit coordination capability.
- Midlands social housing aggregation:Aging terraced housing stock in Birmingham and Manchester corridors presents concentrated demand for external wall insulation systems with minimal occupant displacement.
- Building Regulations Part L tightening:Approved Document L revision cycles are compressing U-value thresholds faster than competing insulation technologies can adapt, favoring polyurethane's performance density.
Industry Challenges
- Retrofit coordinator talent scarcity:PAS 2035 accreditation requires combined building physics and project management competency that the existing workforce supply cannot satisfy at current training throughput rates.
- BBA agrément certification timelines:Product acceptance for warranty-backed installations by major lenders requires 12-18 month testing cycles that delay market entry for reformulated chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Foam Insulation Market |
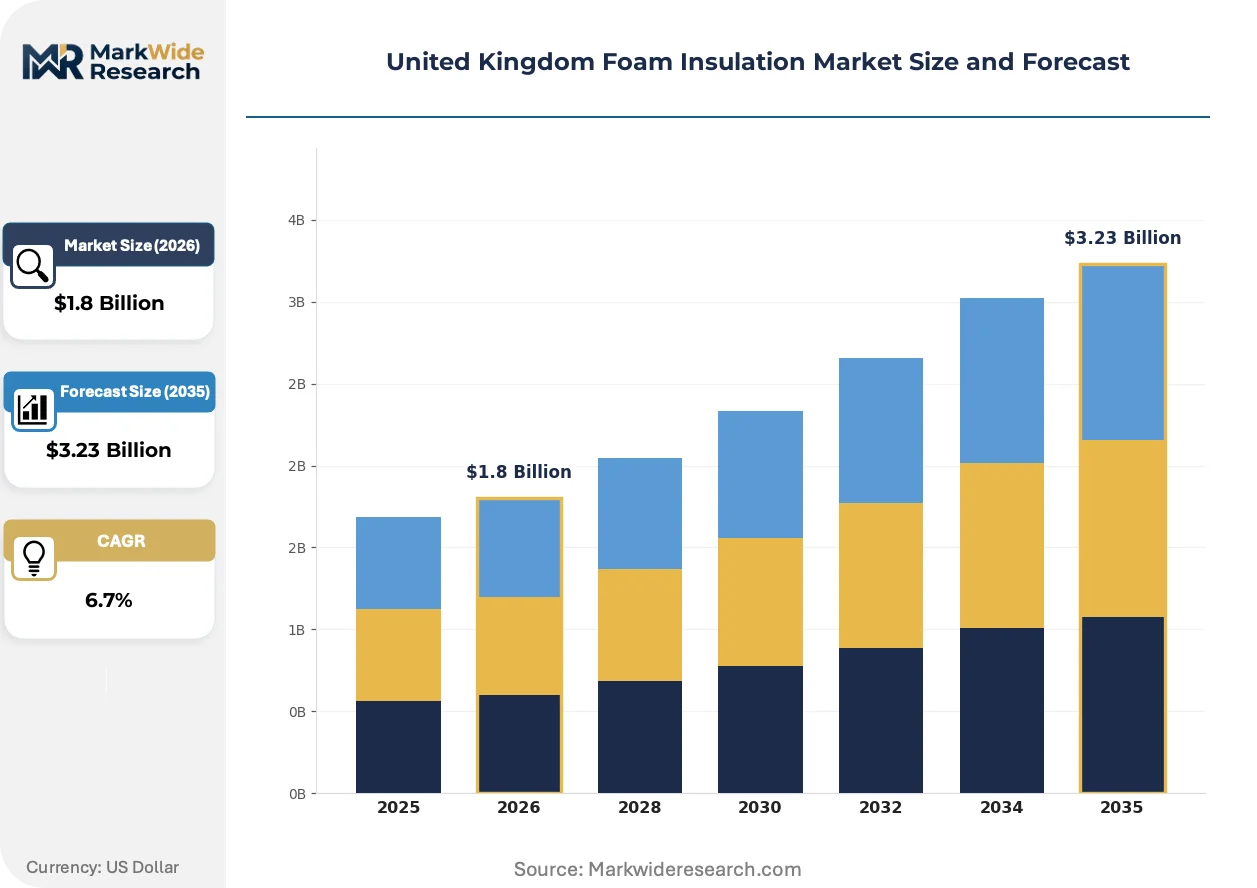
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Polyethylene Foam, Mineral Wool Application: Roof Insulation, Wall Insulation, Floor Insulation, Pipe Insulation End User: Residential, Commercial, Industrial, Construction Installation Method: Spray Applied, Rigid Board, Flexible Roll, Injection |
| Companies Covered | BASF SE, Huntsman International LLC, Kingspan Group, Xtratherm Ltd, Armacell, Saint-Gobain, Dow, Zotefoams PLC, Owens Corning, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Foam Insulation Market Evolving Landscape
Material science convergence and installation methodology evolution are compressing project economics while elevating performance verification requirements across the United Kingdom foam insulation value chain.
Polyurethane spray foam is hybridizing with phase-change material additives to deliver thermal mass buffering alongside primary insulation function. Heritage building contractors in Yorkshire and Cumbria are piloting these formulations in solid-wall applications where traditional cavity solutions are structurally impossible. The technology is hybridizing two previously separate performance categories—insulation and thermal storage—into single-application systems that command premium pricing against commodity alternatives.
The Future Homes Standard implementation timeline is eliminating fossil fuel heating system specifications in new dwelling consents from 2025. Building control bodies in England are already rejecting plans that fail to demonstrate fabric-first efficiency strategies incorporating high-performance foam envelope solutions. New-build developers in the South East are responding by specifying closed-cell polyurethane thicknesses 40% above current Part L minima to future-proof against anticipated regulatory tightening.
Social housing providers are consolidating procurement through framework agreements that bundle insulation with heating system replacement, displacing spot-contracting relationships with multi-year service partnerships. Registered providers in the West Midlands are selecting contractors on whole-life cost models rather than capital expenditure alone. This behavioral shift is most visible in Birmingham and Coventry, where three-year retrofit programmes are replacing traditional single-measure installations.
United Kingdom Foam Insulation Market Segmentation
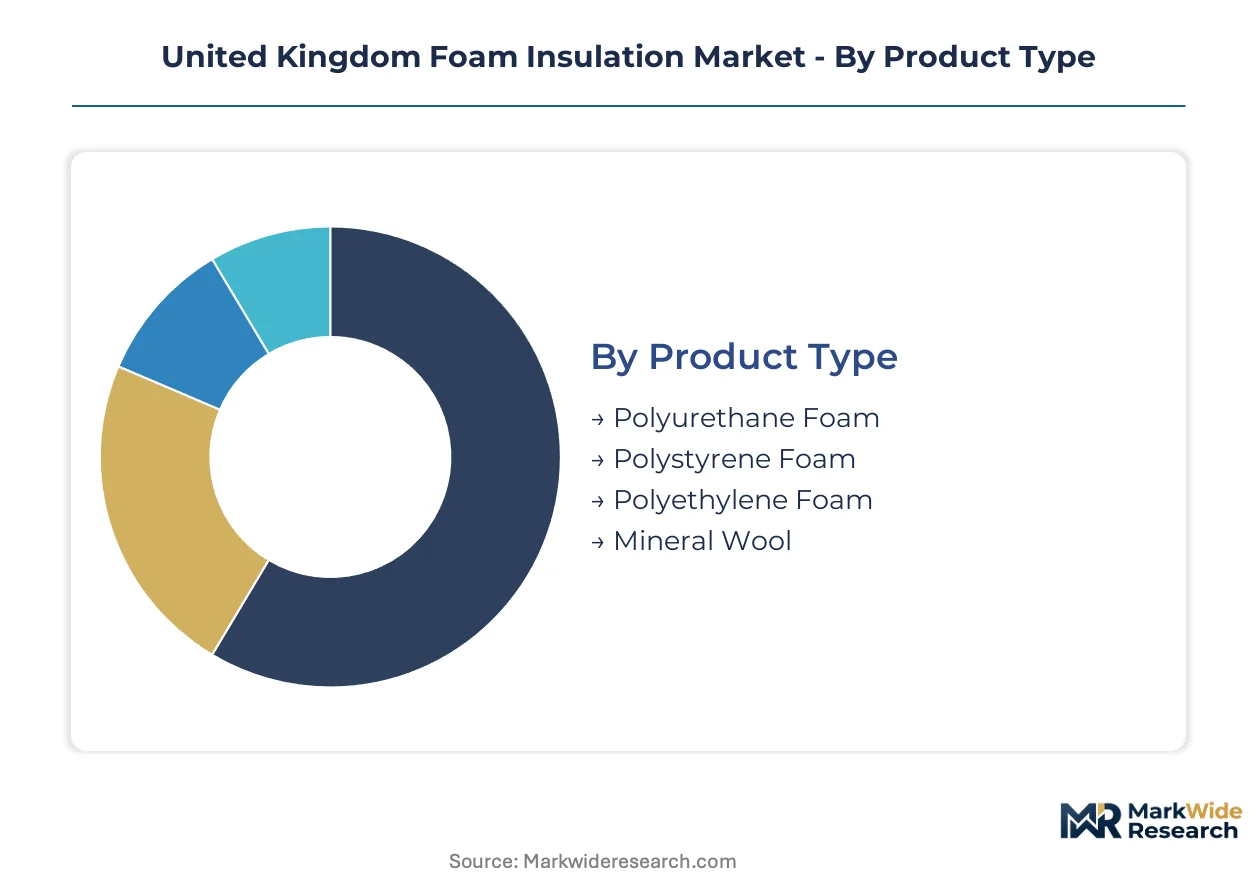
Foam insulation procurement in the United Kingdom fragments across four distinct dimensions. Each segmentation axis reveals divergent margin structures, regulatory exposure, and contractor capability requirements that reshape competitive positioning.
Product Type:
The use-case spectrum spans high-performance envelope systems to economy-grade perimeter solutions with fundamentally different thermal conductivity specifications.
- Polyurethane Foam:Closed-cell thermoset chemistry achieves lambda values below 0.025 W/mK through pentane or hydrofluoroolefin blowing agents. Demand concentrates in residential retrofit across Birmingham and Manchester corridors where spray-applied installation minimizes occupant displacement during social housing upgrades.
- Polystyrene Foam:Expanded and extruded variants occupy the moisture-resistant tier for below-grade and perimeter applications. The Midlands social housing aggregation programmes favor this material for external wall insulation where cost-per-R-value dominates procurement decisions over thermal performance density.
- Polyethylene Foam:Semi-rigid closed-cell structure delivers vibration damping alongside moderate thermal resistance. Industrial pipe lagging specifications in northern England chemical processing facilities specify this material where mechanical protection outweighs pure insulation function.
- Mineral Wool:Inorganic fiber insulation captures fire-performance-critical specifications that exclude organic foams. Below-grade applications in London high-rise developments increasingly substitute mineral wool where Building Regulations Part B fire certification requirements override moisture resistance considerations.
The dominant share belongs to Polyurethane Foam, while Mineral Wool is closing the gap fastest through fire safety specification tailwinds.
Application:
Building envelope thermal bridges dictate material selection through U-value threshold compression in Approved Document L revision cycles.
- Roof Insulation:Attic and warm-deck specifications concentrate spray-applied polyurethane demand. Yorkshire and Cumbria heritage contractors pilot phase-change material hybrid formulations in solid-wall dwellings where cavity solutions are structurally impossible.
- Wall Insulation:Cavity fill and external wall systems absorb the majority of social housing retrofit volume. The West Midlands framework agreements bundle wall insulation with heating replacement, displacing spot-contracting with multi-year service partnerships.
- Floor Insulation:Suspended timber and solid ground floor applications favor rigid board installation methods. New-build developers in the South East specify closed-cell polyurethane thicknesses 40% above current Part L minima to future-proof against anticipated regulatory tightening.
- Pipe Insulation:Industrial process equipment and district heating networks drive flexible roll and pre-formed segment demand. Northern England manufacturing clusters specify high-temperature polyurethane formulations for steam distribution efficiency.
Wall Insulation commands procurement volume concentration, though Roof Insulation is gaining share fastest through PAS 2035 coordinator-mandated whole-dwelling assessments.
End User:
Customer-type segmentation reveals divergent decision-making authority and contract structure preferences across the value chain.
- Residential:Single-dwelling owners and social housing registered providers generate divergent demand patterns. Owner-occupiers in southern England prioritize warranty-backed installations requiring BBA agrément certification, while Midlands social housing aggregators optimize whole-life cost models.
- Commercial:Office and retail developers face accelerated Building Regulations compliance timelines. The Future Homes Standard trajectory is already influencing commercial refurbishment specifications as landlords anticipate regulatory spillover.
- Industrial:Process equipment insulation and cold storage facilities demand specialized high-temperature or cryogenic formulations. Chemical production sites in northern England specify captive maintenance contracts over spot procurement.
- Construction:Speculative housebuilders and principal contractors operate on fixed-price frameworks that compress material margin. Merchant channel relationships with Kingspan Group and similar rigid board manufacturers dominate this tier.
Residential retains volume leadership, yet Industrial is climbing the fastest through energy price volatility driving process efficiency investment.
Installation Method:
Application technique determines project economics, workforce skill requirements, and disruption tolerance thresholds.
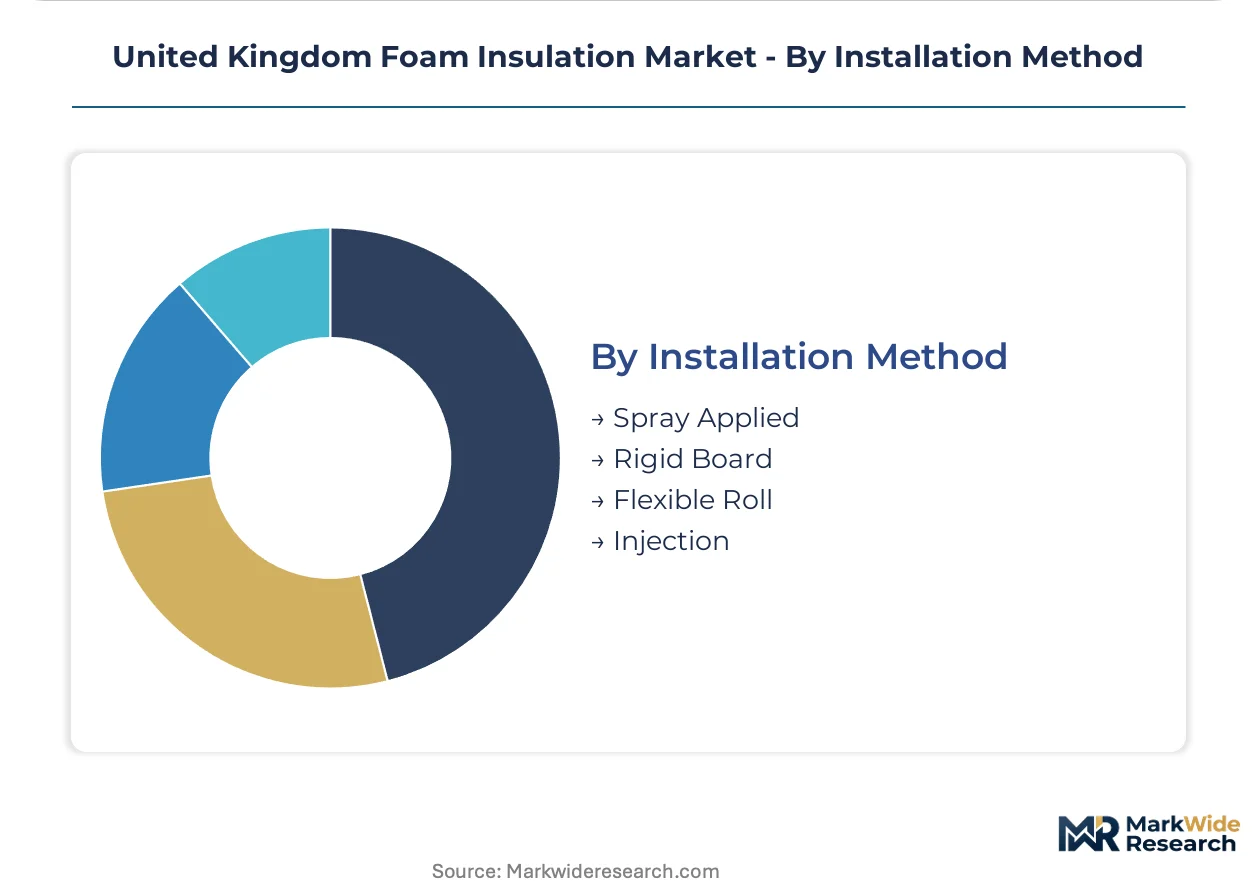
- Spray Applied:On-site chemical reaction delivery enables complex geometry coverage with minimal thermal bridging. Retrofit contractors across Midlands and northern England favor this method for occupied dwelling upgrades where displacement costs outweigh material premiums.
- Rigid Board:Factory-manufactured panels with established supply chains through merchant distribution. New-build developers in the South East specify standardized dimensions to accelerate envelope closure timelines.
- Flexible Roll:Batt and blanket formats suit accessible loft spaces and industrial equipment with regular maintenance access. This method requires lowest contractor accreditation burden under PAS 2035 retrofit coordinator requirements.
- Injection:Cavity wall fill applications target pre-1919 housing stock with existing wall cavities. Listed structure regulations exclude this method from approximately 20% of England's heritage housing stock where cavity intervention is prohibited.
Spray Applied holds the dominant position, while Injection is expanding most quickly through social housing aggregation programmes seeking rapid deployment scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane foam manufacturing clusters concentrate in northern England and the Midlands, with distribution networks radiating toward high-retrofit-demand corridors. The regional landscape reflects housing stock age gradients and regulatory enforcement intensity across English sub-regions.
London and Southeast England
New-build developers in Surrey and Kent specify closed-cell polyurethane thicknesses exceeding current Building Regulations Part L minima by 40 percent. The Future Homes Standard trajectory is accelerating fabric-first specifications ahead of 2025 implementation. High land values in Greater London compress project timelines, favoring spray-applied methods that minimize envelope closure delays.
Midlands
Social housing aggregation programmes in Birmingham and Coventry are consolidating three-year retrofit frameworks that bundle insulation with heating replacement. The West Midlands Combined Authority channels funding toward terraced housing stock built 1919-1945. Spray contractors dominate procurement through PAS 2035 coordinator-mandated whole-dwelling assessments.
North England
Yorkshire and Cumbria heritage contractors pilot phase-change material hybrid formulations in solid-wall dwellings where cavity solutions are structurally impossible. Local authority building control bodies enforce BBA agrément certification strictly for warranty-backed installations. Manchester corridor demand concentrates in pre-1919 stock requiring external wall insulation with minimal occupant displacement.
Scotland
Scottish Building Standards exceed English U-value thresholds, mandating thicker foam specifications in new-build and renovation work alike. Registered social landlords in Glasgow and Edinburgh operate multi-year retrofit programmes similar to Midlands frameworks. The colder climate shifts specification preference toward highest-lambda polyurethane systems regardless of capital cost premium.
United Kingdom Foam Insulation Market Competitive Landscape
Chemical conglomerates and rigid board specialists split the market along feedstock control versus distribution scale vectors. The structure tiers into upstream polyol producers, midstream formulation houses, and downstream installation contractors. Three archetypes dominate: integrated chemical manufacturers with captive precursor supply, rigid board fabricators leveraging merchant channel relationships, and spray-applied system specialists targeting heritage retrofit niches. Competitive moves center on backward integration into blowing agent chemistry and accreditation bundling under PAS 2035 coordinator frameworks.
Within the integrated chemical tier, BASF SE anchors upstream positioning through polyol production at UK facilities. Huntsman International LLC exemplifies the formulation-specialist archetype with spray-applied system capabilities. Kingspan Group occupies the rigid board manufacturing position, leveraging scale to dominate merchant distribution channels. These three entities represent distinct strategic postures without overlapping core competencies.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman International LLC |
| Kingspan Group |
| Xtratherm Ltd |
| Armacell |
| Saint-Gobain |
| Dow |
| Zotefoams PLC |
| Owens Corning |
| Others |
Value Network & Pricing Analysis
Polyol feedstock volatility tethered to crude oil derivative markets compresses polyurethane foam margins while simultaneously widening pricing spreads between backward-integrated chemical producers and formulation-dependent contractors. This single-source dependency on petrochemical precursors determines both three-tier pricing stratification across premium, standard, and economy certification levels and the geographic clustering of manufacturing capacity around Teesside and Hull chemical corridors.
Pricing Analysis
Building Regulations Approved Document L dictates the pricing tier structure through escalating U-value thresholds that mandate minimum foam thicknesses. Premium-mid-economy pricing differentiation separates BBA agrément-certified installations from standard merchant-channel products and uncertified spot-contracting alternatives. Cost compression in the economy tier is intensifying because social housing aggregators optimize whole-life cost models over capital expenditure alone. Registered providers in the West Midlands exhibit highest price sensitivity, while owner-occupiers in southern England prioritize warranty-backed specifications regardless of premium.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk for blowing agent imports and specialty chemical additives. Manufacturing gravity centers on Teesside, Hull, and Antwerp chemical clusters, with formulation houses drawing from Belgian and Dutch precursor supply. Single-source vulnerability concentrates in hydrofluoroolefin blowing agent supply chains where two European producers control capacity. Distribution runs through merchant channel partnerships with rigid board fabricators and direct-to-contractor relationships for spray-applied systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom foam insulation market builds defensive moats through regulatory entrenchment: PAS 2035 coordinator accreditation creates switching costs that lock contractors into compliance-capable supply relationships.
For Market Incumbents: Entrench position through captive polyol production capacity and PAS 2035 coordinator service bundling. Mineral wool substitution in below-grade fire-critical applications threatens polyurethane's perimeter insulation share. Backward integration into blowing agent chemistry secures margin against feedstock volatility while accelerating BBA agrément certification timelines for reformulated systems. For New Entrants and Emerging Players: Pursue heritage building envelope niches in Yorkshire and Cumbria where phase-change material hybrid formulations command premium pricing against commodity alternatives. Spray-applied solid-wall applications in pre-1919 stock present the most penetrable segment given cavity intervention prohibitions. Establish PAS 2035 coordinator accreditation as the primary go-to-market credential to unlock social housing framework eligibility. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulation specialists with spray-applied capabilities and captive distribution relationships. Long-term viability rests on regulatory trajectory certainty around Future Homes Standard implementation and thermal performance threshold compression. Acquisition target archetype: mid-cap spray contractors with PAS 2035 coordinator capacity in Midlands social housing corridors. Watch BBA agrément certification backlog duration as the signal for supply-constrained pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Chemistry | Captive supply of hydrofluoroolefin precursors insulates margin from petrochemical volatility and REACH regulatory shifts. |
| PAS 2035 Coordinator Accreditation Buildout | Compliance capability unlocks social housing framework eligibility and creates contractor switching costs. |
| Phase-Change Material Hybrid Formulation Launch | Thermal mass buffering differentiation captures heritage retrofit premium in solid-wall Yorkshire and Cumbria applications. |
| Merchant Channel Partnership Expansion | Rigid board distribution scale through Kingspan-type relationships secures new-build developer specification lock-in. |
| Long-Term Social Housing Framework Agreement | Multi-year service partnerships with West Midlands registered providers displace spot-contracting revenue volatility. |
Research Methodology
A standing panel of spray contracting operations directors, social housing procurement leads, building control officers, and polyol plant managers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with retrofit coordinators and merchant channel category buyers against secondary validation through Building Regulations compliance databases, BBA agrément certification records, and local authority framework agreement disclosures. Bottom-up project pipeline aggregation from Midlands and northern England social housing providers triangulated against top-down chemical production capacity assessments from Teesside and Hull manufacturing clusters.
Scenario-bracketing around Future Homes Standard implementation intensity and PAS 2035 coordinator training throughput produced volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry tier, installation methodology, end-user procurement structure, and regional building stock age profile. CAGRs derived from regression against historical retrofit programme deployment rates and thermal performance regulatory compression curves, with specific inputs from social housing registered provider capital programme disclosures and chemical sector capacity utilization trends.
Macroeconomic conditions sit as an overlay; deviation in crude oil pricing, interest rate environments affecting housing retrofit financing, or construction labor availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and accreditation training capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Fly Ash Market
Industrial Materials
Briquetting Press Market
Industrial Materials
Paint Knife Market
Industrial Materials
Anode Carbon Block Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Noise Reduction Plastic Gear Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
High Speed Steels Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
GCC Heat Treating Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Industrial Silica Sand Market