
 Electronic Grade Choline Hydroxide Market | 2026-2036
Electronic Grade Choline Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Grade Choline Hydroxide Market Insights
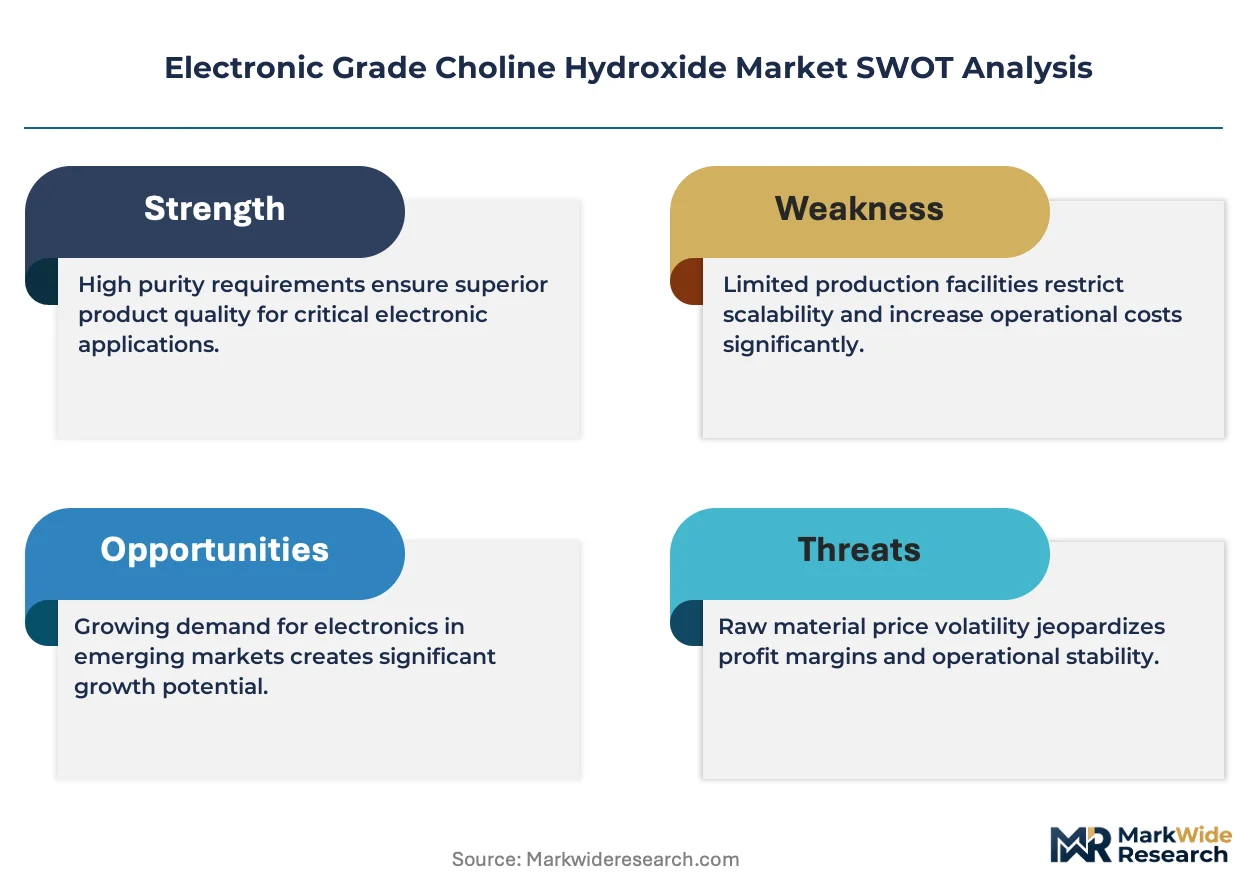
SEMI Grade 3 and Grade 4 purity certifications are reorganizing supplier eligibility for electronic-grade choline hydroxide, disqualifying general chemical producers from foundry qualification programs. Entegris leverages its contamination-control infrastructure to sustain fab-direct relationships across leading-edge nodes. BASF SE anchors European supply through integrated choline chemistry platforms certified to SEMI standards. Jiangyin Jianghua Micro-Eltr Mtrl dominates domestic qualification pathways for China's semiconductor self-sufficiency procurement mandates.
Electronic grade choline hydroxide designates a quaternary ammonium hydroxide compound manufactured to sub-ppb metal-impurity thresholds, typically supplied as aqueous solutions for photoresist stripping, post-CMP cleaning, and organic residue removal in semiconductor fabrication. The compound functions as a mild alkaline etchant that selectively attacks organic films without attacking underlying silicon, copper, or low-k dielectric layers. Pure choline hydroxide commands the dominant volume position among product types due to its direct use in dilute formulations at leading foundries, while blended variants capture margin pools from fabs seeking pre-mixed pH-buffered solutions. Semiconductor applications absorb the majority of electronic-grade volume, with flat panel display manufacturing representing a secondary but structurally growing outlet as OLED fabrication expands.
SEMI standards, REACH registration requirements, and China's GB/T national standards for electronic chemicals collectively define the regulatory perimeter for market access, with each framework imposing distinct impurity testing protocols and documentation burdens. EPA reporting obligations in the United States add environmental handling constraints that favor suppliers with established hazardous waste management systems. Buyers must monitor evolving purity thresholds at sub-3nm nodes, track dual-sourcing requirements spreading from memory to logic foundries, and assess whether captive choline production by integrated device manufacturers will reshape merchant supply dynamics.
Market Dynamics
Sub-3nm node migration at Taiwan Semiconductor Manufacturing and Samsung Foundry is compressing metal-impurity tolerances for photoresist strippers, forcing choline hydroxide suppliers to recalibrate purification infrastructure around SEMI Grade 4 specifications.
Growth Catalysts
- SEMI Grade 4 Certification:Leading foundries in Taiwan and South Korea now mandate sub-ppb purity thresholds for organic residue removal chemistries, expanding the qualified supplier pool for electronic-grade choline hydroxide.
- China's GB/T National Standards:Domestic semiconductor procurement mandates under China's integrated circuit self-sufficiency campaigns are creating parallel qualification pathways for local choline hydroxide manufacturers.
- OLED Panel Expansion:Flat panel display fabrication lines in South Korea and Japan are absorbing increasing volumes of high-purity choline hydroxide for post-CMP cleaning of organic light-emitting diode substrates.
Market Restraints
- Trimethylamine Feedstock Volatility:Choline hydroxide synthesis depends on petrochemical-derived trimethylamine, exposing producers to natural gas price fluctuations and supply disruptions from Gulf Coast chemical complexes.
- East Asian Supply Concentration:Over seventy percent of electronic-grade purification capacity resides in Taiwan, South Korea, and Japan, creating geographic vulnerability to seismic events and trade route interruptions.
- Fluorinated Solvent Substitution:Emerging supercritical CO2 and fluorinated gas stripping technologies threaten choline hydroxide's position in legacy node photoresist removal applications.
Strategic Opportunities
- India Semiconductor Mission:India's PLI scheme for display and chip fabrication is attracting choline hydroxide suppliers to establish local blending and distribution facilities ahead of fab commissioning.
- Pre-Mixed pH-Buffered Formulations:Fabs seeking reduced chemical handling complexity are creating margin pools for suppliers offering blended choline hydroxide solutions with integrated stabilizers.
- EU REACH Registration Tailwinds:European foundries transitioning from generic chemical suppliers to REACH-registered electronic-grade specialists are opening procurement windows for certified choline hydroxide vendors.
Industry Challenges
- SEMI Qualification Timelines:Foundry certification programs for new choline hydroxide sources require eighteen to twenty-four months of metal-impurity testing and process integration validation, delaying revenue recognition.
- Analytical Chemistry Talent Scarcity:Sub-ppb impurity detection using ICP-MS and TXRF instrumentation demands specialized technicians that semiconductor chemical suppliers struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Grade Choline Hydroxide Market |
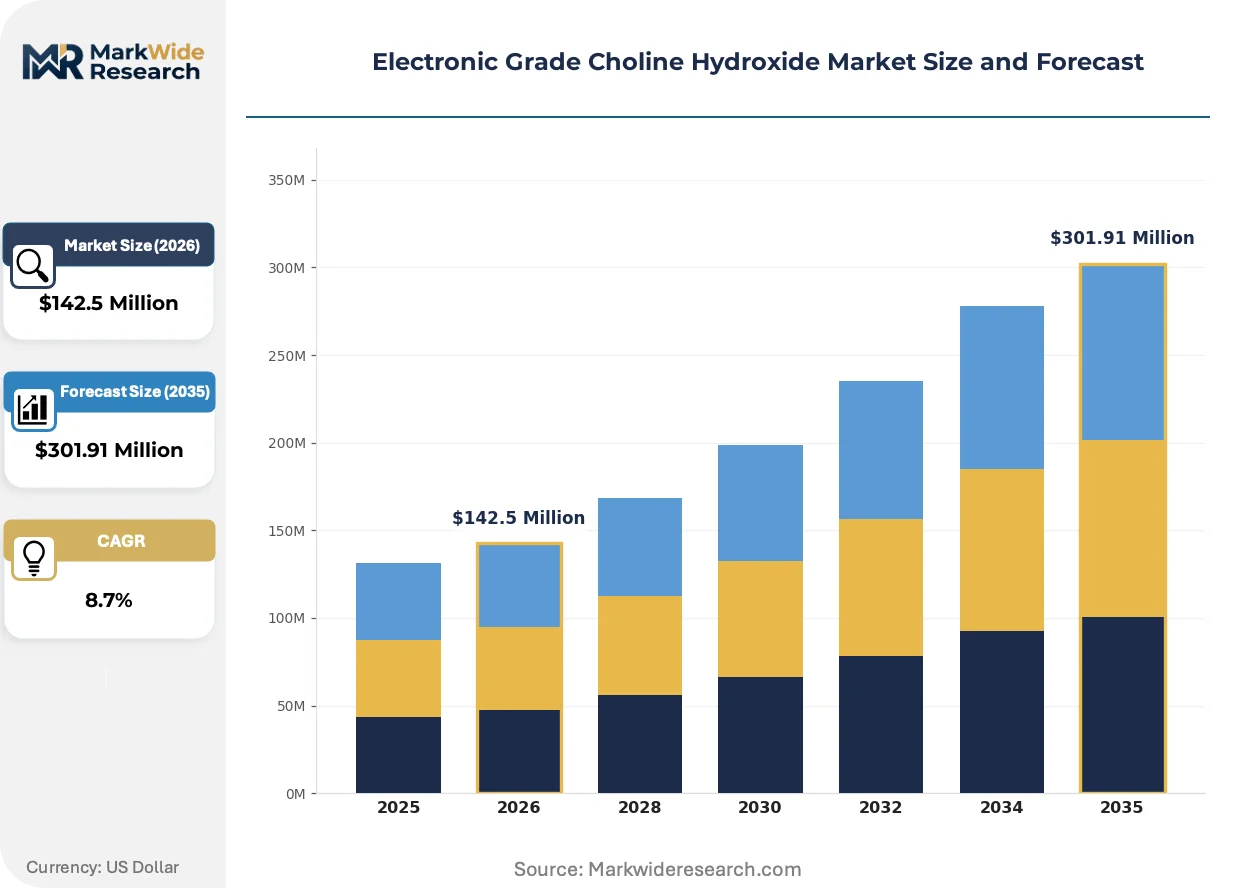
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Choline Hydroxide, Blended Choline Hydroxide, Anhydrous Choline Hydroxide, Choline Chloride Application: Semiconductors, Flat Panel Displays, Solar Cells, Chemical Reagents Delivery Mode: Powder, Liquid, Aqueous Solution, Granulated Form End User: Electronics Manufacturers, Research Laboratories, Chemical Industries, Automotive Suppliers |
| Companies Covered | Columbus Chemicals, Entegris, Meden Pharma, Palm International, Jiangyin Jianghua Micro-Eltr Mtrl, Sunheat Chemical, BASF SE, Merck KGaA, Avantor Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Grade Choline Hydroxide Market Trends and Innovations
Photoresist stripping chemistry is undergoing specification compression as foundries push organic residue removal to atomic-scale precision, requiring choline hydroxide suppliers to synchronize purification advances with node roadmaps.
Membrane-based electrodialysis purification is decomposing traditional solvent extraction methods for electronic-grade choline hydroxide production. TSMC and Intel Foundry Services are qualifying electrodialysis-supplied material for 2nm pilot lines. This technology is decomposing incumbent purification infrastructure investments by enabling continuous rather than batch processing at lower capital intensity.
REACH authorization requirements for quaternary ammonium compounds are tightening documentation burdens for choline hydroxide importers into European Union member states. ECHA's 2024 substance evaluation roadmap is forcing suppliers to generate extended safety data sets for semiconductor chemical applications. German and Dutch foundries are consolidating procurement around pre-registered suppliers to avoid authorization delays.
Dual-sourcing mandates are spreading from memory to logic foundries as supply chain resilience protocols harden. Buyers at Samsung and Micron are requiring qualified secondary choline hydroxide sources for each fabrication facility. This pattern is most visible in Taiwan's Hsinchu Science Park, where foundries are splitting volumes between merchant suppliers and captive chemical operations.
Electronic Grade Choline Hydroxide Market Segmentation
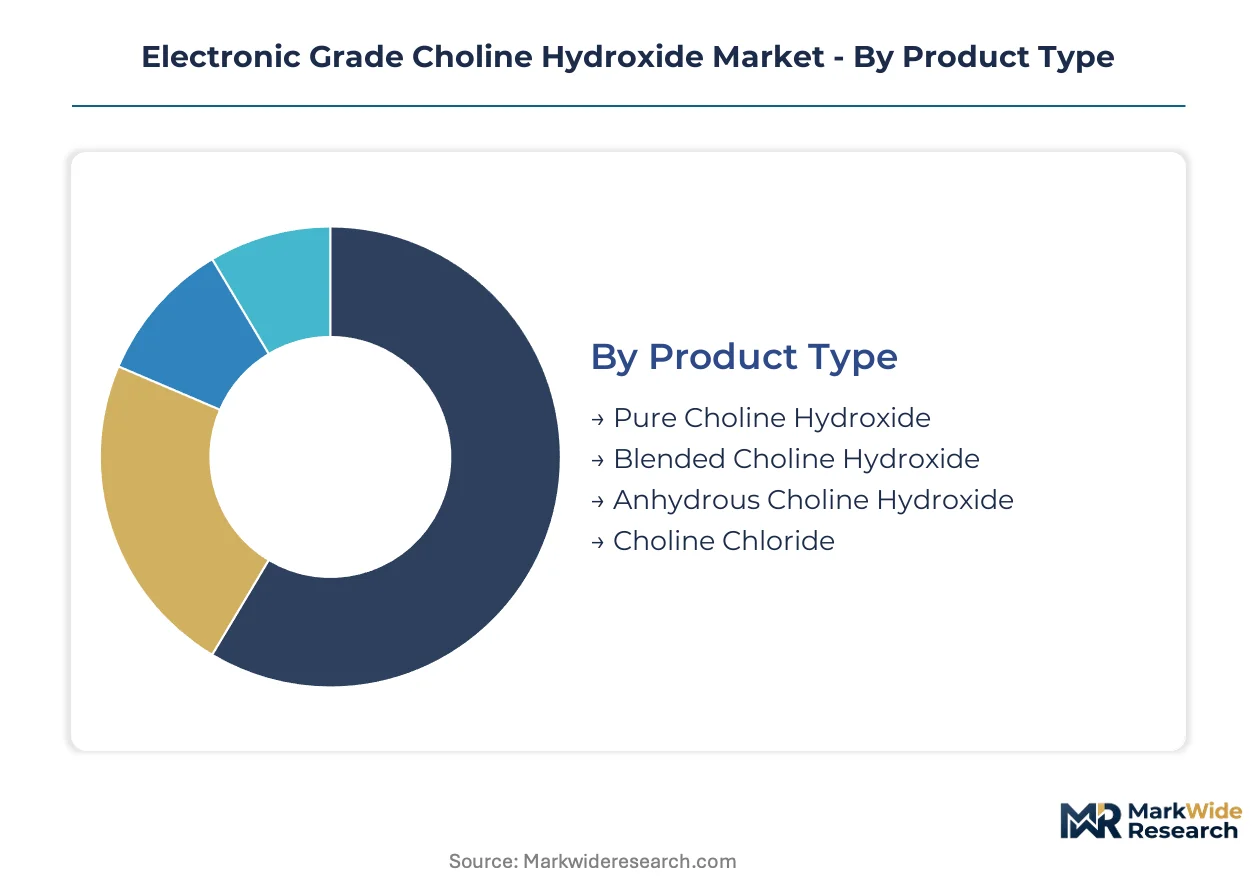
Segmentation in electronic-grade choline hydroxide tracks how purity grades, delivery formats, and end-use specifications fragment procurement requirements across semiconductor and display fabrication ecosystems. Suppliers must calibrate product portfolios against diverging technical thresholds rather than treating the category as a homogeneous commodity.
Product Type:
Pure choline hydroxide commands the widest margin pools due to its direct use in dilute formulations at leading-edge foundries requiring SEMI Grade 4 certification.
- Blended Choline Hydroxide:Pre-mixed pH-buffered solutions incorporate stabilizers and co-solvents for fabs seeking reduced chemical handling complexity. Samsung Foundry and Micron Technology are expanding procurement of blended formats for legacy node photoresist stripping, trading formulation control for operational simplicity.
- Pure Choline Hydroxide:Aqueous solutions manufactured to sub-ppb metal-impurity thresholds serve as the baseline chemistry for photoresist stripping and post-CMP cleaning. Taiwan Semiconductor Manufacturing and Intel Foundry Services specify pure grades for sub-3nm node qualification programs.
- Anhydrous Choline Hydroxide:Solid-phase material with moisture content below specification limits, used in specialized vapor-phase cleaning applications at Japanese display panel manufacturers.
- Choline Chloride:Precursor compound for downstream choline hydroxide synthesis, purchased primarily by integrated chemical producers with in-house electrodialysis purification infrastructure.
Pure choline hydroxide holds installed capacity. Blended choline hydroxide is rotating up the share rankings.
Application:
Volume concentration tracks the capital intensity of fabrication facilities, with semiconductor fabs consuming the highest per-site tonnages of certified electronic-grade material.
- Semiconductors:Photoresist stripping, post-CMP cleaning, and organic residue removal at logic and memory foundries. TSMC's Arizona and Kumamoto facilities are qualifying local choline hydroxide sources for their 4nm and 3nm production lines.
- Flat Panel Displays:Post-CMP cleaning of OLED substrates and thin-film transistor arrays. LG Display and Samsung Display fabs in South Korea absorb increasing volumes as OLED panel production expands.
- Solar Cells:Texturing and cleaning of silicon wafers in photovoltaic manufacturing, primarily in China's Jiangsu and Zhejiang provinces.
- Chemical Reagents:Laboratory-scale applications in analytical chemistry and materials science research, representing a price-insensitive niche with low volume.
Semiconductor applications dominate absolute consumption. Flat panel displays are climbing the fastest in share contribution.
Delivery Mode:
Foundry preference for aqueous solutions reflects the operational hazards and contamination risks associated with solid-phase handling in cleanroom environments.
- Aqueous Solution:Ready-to-use dilutions at standardized concentrations, delivered in fluoropolymer-lined containers to prevent metal leaching. This format eliminates on-site dissolution steps that introduce particulate contamination.
- Liquid:Higher concentration stock solutions requiring fab-side dilution, preferred by facilities with centralized chemical distribution systems.
- Powder:Solid material for captive formulation by integrated device manufacturers with internal chemical blending operations.
- Granulated Form:Free-flowing solid for automated dispensing systems in research laboratory settings.
Aqueous solution holds installed capacity. Liquid formats are rotating up the share rankings.
End User:
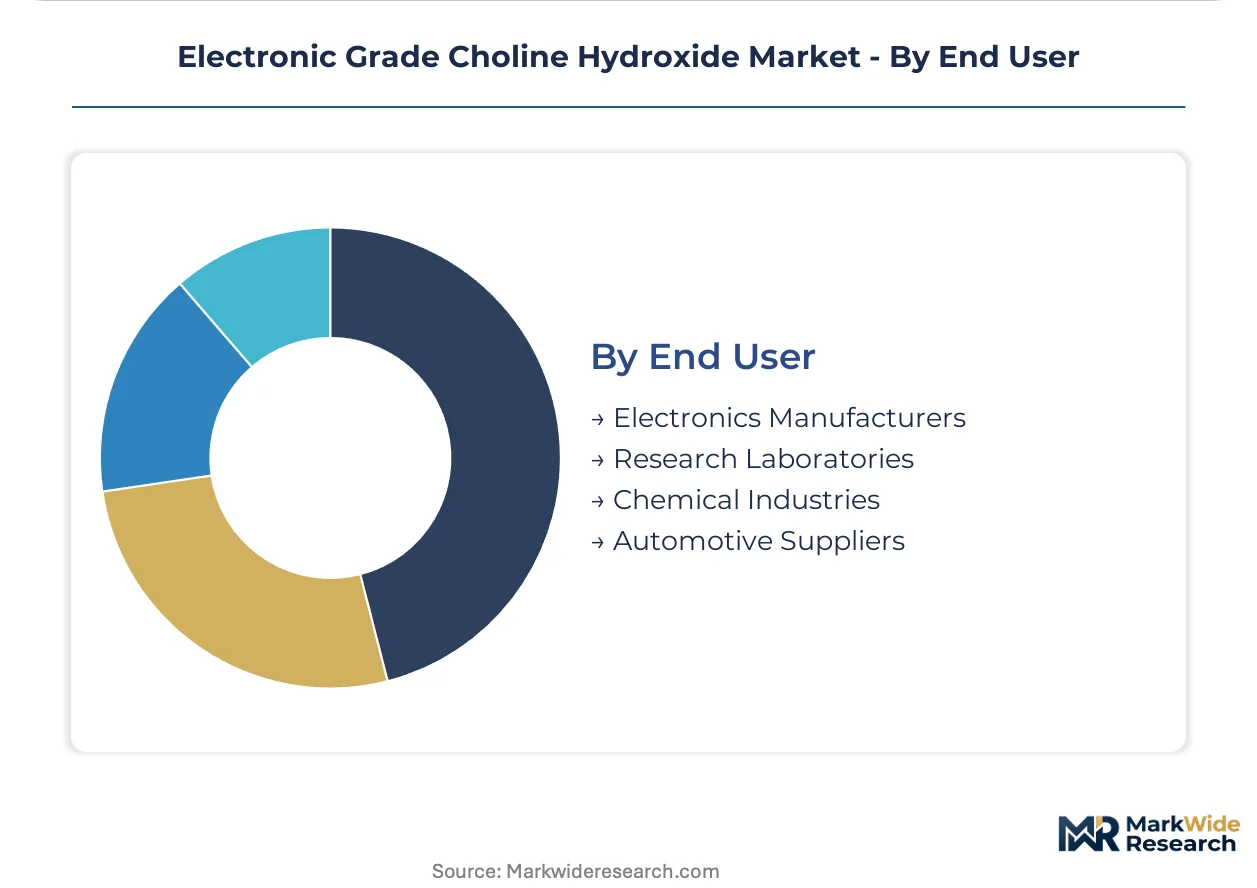
Procurement sophistication varies sharply between high-volume electronics manufacturers with dedicated chemical qualification teams and fragmented research laboratory purchasing.
- Electronics Manufacturers:Semiconductor and display foundries with multi-year supplier qualification programs, dual-sourcing mandates, and direct fab-level chemical management. These buyers negotiate volume commitments tied to node roadmaps.
- Chemical Industries:Merchants and distributors serving secondary applications, purchasing standard-grade material without SEMI certification requirements.
- Research Laboratories:Academic and government facilities with small-batch, high-frequency purchasing patterns and limited price sensitivity.
- Automotive Suppliers:Emerging demand from battery cell manufacturers exploring choline hydroxide for electrode cleaning, still in pilot qualification phases.
Electronics manufacturers hold installed capacity. Automotive suppliers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for semiconductor manufacturing is attracting electronic-grade chemical suppliers to establish local blending facilities ahead of fab commissioning. Taiwan and South Korea maintain the densest concentrations of leading-edge foundry demand. China's domestic chip self-sufficiency campaigns are creating parallel qualification pathways for local choline hydroxide manufacturers.
Taiwan
TSMC's 3nm and 2nm node expansion at Hsinchu Science Park and Tainan is compressing metal-impurity tolerances for photoresist strippers. The Industrial Development Bureau enforces GB/T-aligned import standards for electronic chemicals. Kaohsiung's emerging semiconductor material cluster is attracting secondary choline hydroxide qualification programs from merchant suppliers seeking dual-source positioning.
South Korea
Samsung Foundry and SK Hynix are mandating SEMI Grade 4 certification for organic residue removal chemistries at Pyeongtaek and Icheon fabs. The Ministry of Trade, Industry and Energy coordinates domestic chemical self-sufficiency targets under the K-Semiconductor Belt initiative. Yongin's semiconductor material innovation zone is hosting electrodialysis purification pilot lines for next-generation choline hydroxide supply.
China
SMIC and Hua Hong Semiconductor are expanding 28nm and 14nm production lines in Shanghai and Wuxi, driving procurement of GB/T-certified electronic-grade material. MIIT enforces national standards for electronic chemicals under integrated circuit self-sufficiency mandates. Jiangyin's specialty chemical corridor is consolidating domestic choline hydroxide purification capacity for foundry direct qualification.
United States
Intel Foundry Services and TSMC Arizona are qualifying local choline hydroxide sources for 4nm and 3nm production lines under CHIPS Act incentives. EPA reporting obligations for hazardous waste handling favor suppliers with established environmental management systems. Phoenix's emerging semiconductor cluster is attracting chemical distribution infrastructure for Southwest fab operations.
Japan
Tokyo Electron and Shin-Etsu Chemical are integrating high-purity choline hydroxide into advanced packaging process flows at Yokkaichi and Hiroshima facilities. METI coordinates supply chain resilience protocols for critical electronic chemicals under the Economic Security Promotion Act. Kyushu's silicon island ecosystem is hosting collaborative qualification programs between material suppliers and memory manufacturers.
Electronic Grade Choline Hydroxide Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where scale-driven multinationals anchor premium-grade supply while regional fabricators capture legacy node volume. The market stratifies around SEMI qualification status, with Grade 4-certified suppliers commanding foundry-direct relationships and uncertified merchants serving secondary applications. Three archetypes dominate: integrated chemical conglomerates with captive choline chemistry platforms, contamination-control specialists leveraging fab-direct infrastructure, and domestic champions aligned with national semiconductor self-sufficiency programs. Competitive intensity centers on purification technology licensing and geographic expansion into emerging fab clusters.
Within the integrated chemical tier, BASF SE and Merck KGaA exemplify European anchors with REACH-registered electronic-grade portfolios. Entegris occupies a position among contamination-control specialists sustaining direct foundry relationships across leading-edge nodes. Jiangyin Jianghua Micro-Eltr Mtrl represents the domestic champion archetype, positioned within China's parallel qualification pathways for semiconductor procurement mandates.
| Leading Market Players |
|---|
| Columbus Chemicals |
| Entegris |
| Meden Pharma |
| Palm International |
| Jiangyin Jianghua Micro-Eltr Mtrl |
| Sunheat Chemical |
| BASF SE |
| Merck KGaA |
| Avantor Performance Materials |
| Others |
Pricing and Supply Chain Analysis
SEMI Grade 4 certification gates both supplier qualification and price differentiation simultaneously, compressing the qualified vendor pool for sub-ppb purity thresholds while expanding margin capture for certified specialists serving Taiwan and South Korea foundries.
Pricing Analysis
Certification level (SEMI Grade 3 versus Grade 4) creates the primary spread between commodity chemical merchants and fab-direct suppliers. Pure choline hydroxide commands premium positioning against blended formats due to formulation control requirements at leading-edge nodes. Cost compression in legacy node supply is intensifying because memory foundries are consolidating procurement around pre-mixed pH-buffered solutions. Research laboratories exhibit the lowest price sensitivity, while display panel manufacturers represent the most cost-conscious volume buyers.
Supply Chain Analysis
Trimethylamine feedstock sourcing from Gulf Coast petrochemical complexes constitutes a critical chokepoint for non-integrated choline hydroxide producers. Manufacturing gravity centers on Taiwan, South Korea, and Japan, with purification capacity concentrated in Hsinchu Science Park and Pyeongtaek chemical corridors. The supply chain rests on petrochemical-derived amine precursors, fluoropolymer-lined containment systems, and specialized electrodialysis membrane stacks. Single-source vulnerability runs through East Asian seismic zones. Distribution runs through fab-direct chemical management systems with secondary merchant channels serving research and solar cell applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic-grade choline hydroxide procurement is approaching a platform-economics inflection as foundries harden dual-sourcing mandates and electrodialysis purification creates interoperability between supplier qualification programs.
For Market Incumbents: Consolidate purification infrastructure around electrodialysis platforms to defend against membrane technology licensing threats from emerging specialists. Entrench fab-direct relationships through captive chemical management contracts at TSMC and Samsung Foundry expansion sites. Certification investment in China's GB/T pathways secures parallel revenue streams as domestic self-sufficiency mandates proliferate. For New Entrants and Emerging Players: Lead with India Semiconductor Mission blending facilities ahead of fab commissioning to capture first-mover positioning in emerging supply corridors. Target automotive battery cell manufacturers for electrode cleaning pilots as the most penetrable white-space segment. Pursue joint qualification programs with display panel OEMs seeking secondary choline hydroxide sources for OLED post-CMP cleaning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contamination-control specialists holding SEMI Grade 4 certifications but lacking geographic diversification. Long-term viability hinges on electrodialysis technology ownership and fab-direct contract tenure rather than commodity chemical scale. Watch for captive chemical production announcements by integrated device manufacturers as the signal indicating merchant supply displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodialysis Purification Scale-Up | TSMC and Intel Foundry Services qualification for 2nm pilot lines validates continuous processing economics. |
| Backward Integration into Trimethylamine | BASF SE and Merck KGaA captive amine production shields margin from Gulf Coast feedstock volatility. |
| GB/T Certification Pathway Investment | Jiangyin Jianghua Micro-Eltr Mtrl domestic qualification captures China semiconductor self-sufficiency procurement mandates. |
| India Blending Facility Establishment | PLI scheme incentives attract chemical distribution infrastructure ahead of fab commissioning in Gujarat. |
| Dual-Source Contract Structuring | Samsung and Micron procurement protocols require qualified secondary suppliers for each fabrication facility. |
Research Methodology
Operator-level perspectives from fab chemical managers, electrodialysis equipment specialists, semiconductor procurement leads, and REACH compliance officers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from SEC filings, SEMI standards documentation, customs trade data, and foundry capex disclosures. Bottom-up capacity modeling and top-down demand triangulation from wafer start projections converged on segment-level outputs.
Sensitivity analysis around electrodialysis adoption rates and captive chemical production timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, delivery format, end-use application, and regional fab cluster. CAGRs were derived from supply-demand balance equations incorporating wafer start forecasts and chemistry consumption intensity per node. Forecast inputs encompassed SEMI qualification pipeline visibility and China domestic substitution policy implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained leading-edge node migration or abrupt trade restriction escalation would require recalibration. Forecasts reflect documented assumptions around electrodialysis technology diffusion and foundry dual-sourcing protocol adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Vinyl Acetate Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Glyoxylic Acid Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
Perchloric Acid Market
Chemicals
Chemical Distribution Market
Chemicals
Japan Methanol Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Iso Nonanol Market
Chemicals
SLS and LABSA Market
Chemicals
Global Glycine Market
Chemicals
Cumene Market