
 Industrial Strainers Market | 2026-2036
Industrial Strainers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Strainers Market Foresight
Buyer concentration across municipal water authorities is rebalancing as regional utilities merge procurement functions and private operators fragment into specialized facility-management contracts. Parker Hannifin Corporation leverages its fluid power distribution network to anchor aftermarket strainer sales across North American industrial corridors. Eaton Corporation competes through integrated system protection portfolios that bundle filtration with electrical infrastructure. Krone Filtertechnik specializes in custom-engineered duplex configurations for European chemical processors with stringent batch-purity requirements.
Industrial strainers are mechanical filtration devices installed in piping systems to remove suspended solids and protect downstream pumps, valves, and process equipment, typically rated for pressures from 150 to 600 psi and constructed with perforated or mesh-lined baskets sized from 40 to 4000 microns. Their primary purpose spans liquid filtration and flow control across continuous-process industries where unplanned downtime from particulate damage carries substantial cost penalties. Basket strainer configurations command the largest installed base in chemical processing due to their high dirt-holding capacity and inline serviceability, while duplex strainer demand accelerates fastest in oil and gas applications where process continuity precludes shutdown for cleaning cycles. Stainless steel material grades dominate specification sheets in food and beverage end uses where FDA surface-finish requirements and caustic washdown regimes exclude carbon steel alternatives.
EPA effluent limitation guidelines and EU F-Gas Regulation compliance timelines are reshaping strainer specification criteria in water treatment and HVAC-related process cooling circuits across the United States and Germany. BIS pressure vessel standards and state-level pollution control mandates in India are forcing domestic fabricators toward certified welding procedures and traceable material documentation. ISO 9001 quality system certification and sector-specific hygiene standards such as 3A Sanitary Standards in dairy processing increasingly function as market-access gatekeepers rather than optional differentiators. Stakeholders must monitor evolving regional certification reciprocity agreements and pre-position localized fabrication or assembly capacity to avoid tariff and lead-time exposure in fragmented procurement environments.
Market Dynamics
Stringent effluent mandates from the EPA Clean Water Act and EU Urban Waste Water Treatment Directive are forcing utilities and processors to accelerate replacement cycles and upgrade to automated duplex systems that eliminate process interruptions during cleaning cycles.
Growth Catalysts
- EPA effluent limitation guidelines:US municipal water authorities face compliance deadlines that mandate filtration upgrades, driving basket strainer procurement for secondary clarifier protection.
- Stainless steel Y-strainer specifications:India's chemical processing corridors in Gujarat and Maharashtra require BIS-certified pressure equipment, shortening replacement intervals for carbon steel legacy installations.
- Continuous-process industries:Oil and gas midstream operators prioritize duplex configurations to maintain flow during maintenance windows, eliminating revenue loss from unplanned shutdowns.
Market Restraints
- Nickel alloy price volatility:Stainless steel grades 316 and 317L face input cost swings that compress fabricator margins and delay project approvals.
- Specialized welding certification scarcity:Certified procedures for duplex stainless fabrication concentrate among a limited pool of European and North American shops, extending lead times.
- Carbon steel substitution limits:FDA surface-finish requirements and caustic washdown regimes in dairy processing exclude lower-cost alternatives regardless of price differentials.
Strategic Opportunities
- EU F-Gas Regulation compliance timelines:HVAC-related process cooling circuits in Germany require upgraded filtration to protect heat exchangers from particulate fouling during refrigerant transitions.
- Condition monitoring integration:Pressure differential sensors linked to predictive maintenance platforms enable service unbundling and recurring revenue streams for strainer OEMs.
- 3A Sanitary Standards certification:Dairy and beverage processors in Wisconsin and California specify hygienic basket designs that command premium positioning against uncertified competitors.
Industry Challenges
- ASME Section VIII welding qualification:Pressure vessel fabricators face extended timeline and documentation burdens to maintain multiple jurisdiction certifications simultaneously.
- Legacy system integration:Brownfield chemical plants require custom flange configurations and piping adapters that complicate standardized product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Strainers Market |
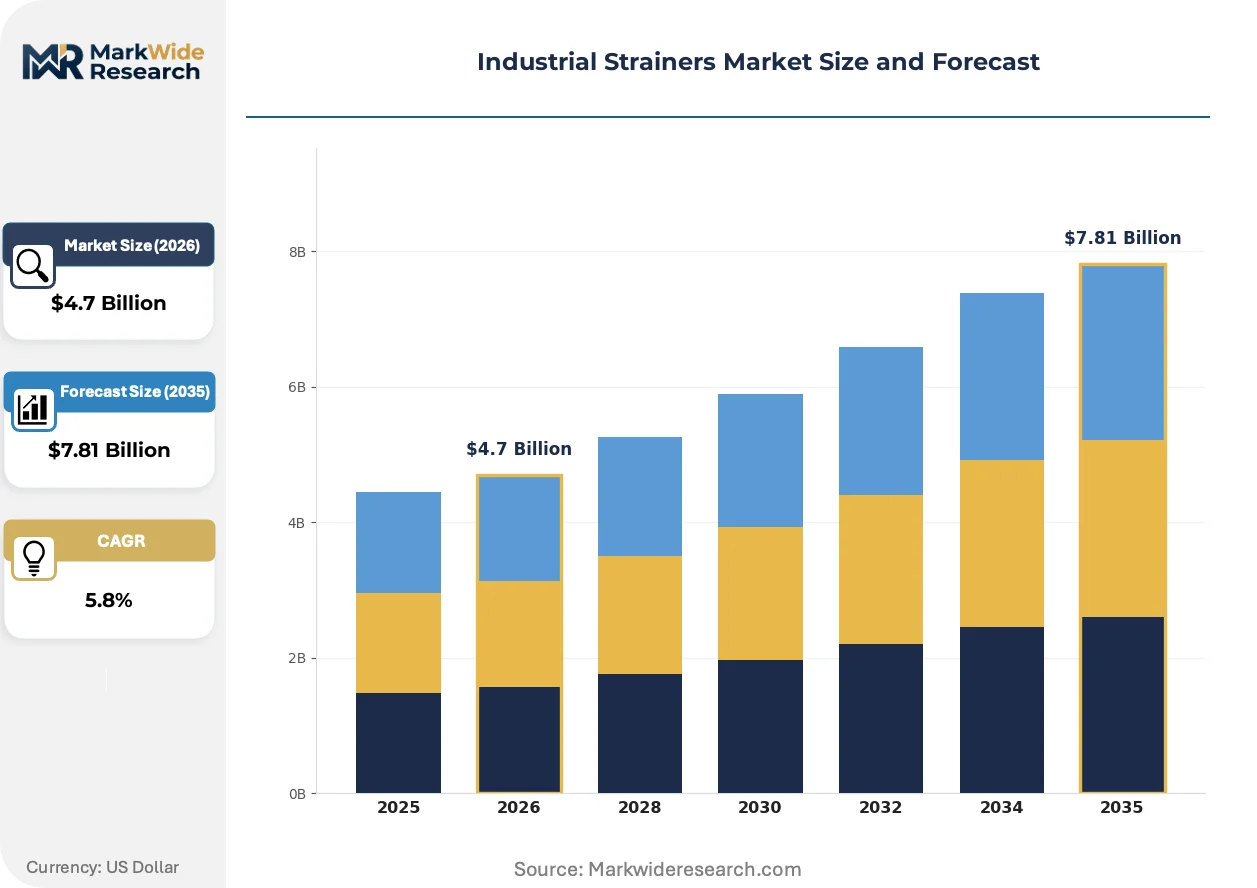
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Y-Strainers, Basket Strainers, Duplex Strainers, Inline Strainers End User: Oil & Gas, Water Treatment, Food & Beverage, Chemical Processing Application: Filtration, Flow Control, System Protection, Liquid Filtration Material: Stainless Steel, Carbon Steel, Plastic, Bronze |
| Companies Covered | Watts Water Technologies, Hayward Flow Control, Parker Hannifin Corporation, Kitz Corporation, Smith & Loveless, Eaton Corporation, Krone Filtertechnik, Metraflex, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Strainers Market Shifts & Advancements
Smart filtration systems with embedded diagnostics are compressing maintenance intervals and reshaping how operators manage particulate loading across continuous-process environments.
Self-cleaning backflush mechanisms with programmable logic controllers are rewriting operational economics for high-solids applications. Mining slurry and pulp paper processors in Minnesota and British Columbia deploy these units to eliminate manual basket removal. The technology is rewriting labor allocation models by reducing technician hours per filtration cycle from hours to minutes.
REACH substance restrictions on PFAS-containing coatings are forcing fabricators to qualify ceramic and plasma-sprayed alternatives for corrosion protection. Surface treatment suppliers in the Netherlands and Belgium accelerate testing protocols to maintain CE marking eligibility. European chemical processors now specify coating documentation traceability as a mandatory bid requirement.
Consolidated procurement functions at merged regional utilities are displacing fragmented purchasing authority. Texas and Florida water authorities now centralize strainer specifications across multi-facility portfolios, compressing vendor count and standardizing on duplex configurations. This concentration shifts negotiation leverage toward buyers and pressures mid-tier fabricators to demonstrate lifecycle cost advantages.
Industrial Strainers Market Segmentation
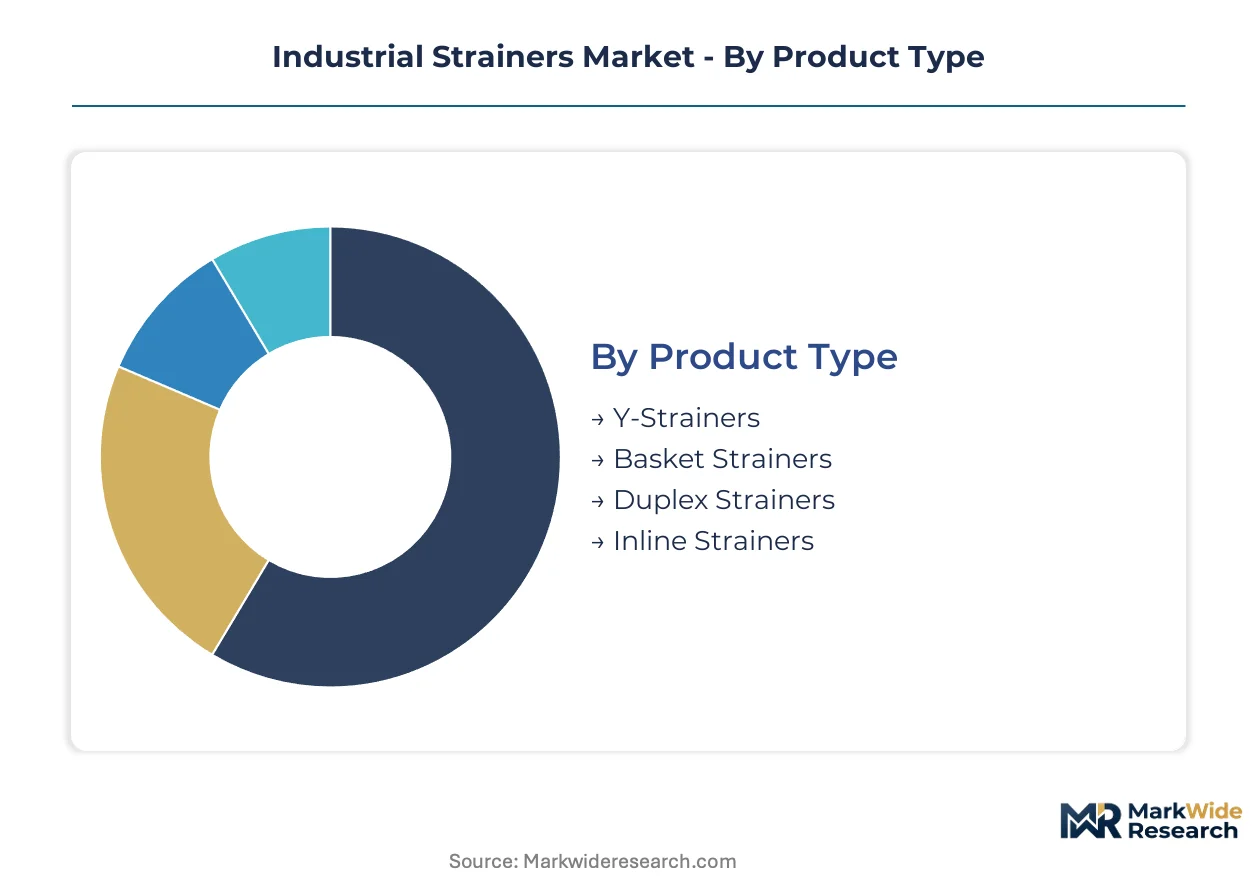
Strainer specification criteria diverge sharply across end-use environments, with material grade and configuration geometry determining lifecycle economics in corrosive chemical corridors versus hygienic food processing lines. Procurement patterns fragment further by pressure rating and automation requirements, creating distinct competitive arenas that resist one-size-fits-all product strategies.
Product Type:
Replacement cycles accelerate where process continuity commands premium positioning over upfront capital cost.
- Basket Strainers:Perforated or mesh-lined cylindrical housings with inline serviceability dominate chemical processing corridors in Gujarat and Maharashtra where high dirt-holding capacity offsets frequent cleaning cycles. BIS pressure equipment certification mandates in India compress replacement intervals for legacy carbon steel installations.
- Duplex Strainers:Twin-chamber configurations with automated switching mechanisms eliminate process interruptions during cleaning cycles. Oil and gas midstream operators across Texas and Alberta prioritize these systems to maintain flow during maintenance windows and avoid revenue loss from unplanned shutdowns.
- Y-Strainers:Angled body designs with compact footprints suit space-constrained piping layouts in HVAC and utility applications.
- Inline Strainers:Straight-through configurations minimize pressure drop across high-volume water treatment circuits.
Volume placements concentrate in Basket Strainers; the faster expansion belongs to Duplex Strainers.
End User:
Regulatory enforcement intensity varies by geography, concentrating upgrade demand in jurisdictions with active EPA or EU mandate timelines.
- Water Treatment:Municipal utilities face compliance deadlines under the EPA Clean Water Act and EU Urban Waste Water Treatment Directive that mandate filtration upgrades for secondary clarifier protection. Consolidated procurement functions at merged regional utilities in Texas and Florida now centralize specifications across multi-facility portfolios.
- Chemical Processing:Continuous-process operations with zero-tolerance for unplanned downtime drive specification toward automated duplex configurations. Stainless steel grades 316 and 317L face nickel alloy price volatility that compresses fabricator margins and delays project approvals.
- Oil & Gas:Midstream infrastructure protection against particulate damage to pumps and valves sustains baseline demand.
- Food & Beverage:FDA surface-finish requirements and caustic washdown regimes in dairy processing exclude carbon steel alternatives regardless of price differentials.
Water Treatment anchors current procurement volume; Chemical Processing claims the steepest expansion trajectory.
Application:
Functional specification depth correlates with downstream equipment replacement cost exposure.
- System Protection:Pump and valve safeguarding in continuous-process environments carries substantial cost penalties from unplanned downtime. Mining slurry and pulp paper processors in Minnesota and British Columbia deploy self-cleaning backflush mechanisms with programmable logic controllers to reduce technician hours per filtration cycle.
- Filtration:Suspended solids removal across 40 to 4000 micron ratings protects downstream equipment integrity. REACH substance restrictions on PFAS-containing coatings force fabricators to qualify ceramic and plasma-sprayed alternatives for corrosion protection.
- Flow Control:Pressure management functions integrate with differential monitoring for predictive maintenance platforms.
- Liquid Filtration:General-purpose clarification spans municipal and industrial water circuits with varying solids loading profiles.
System Protection commands premium positioning; Filtration delivers the broadest installed base.
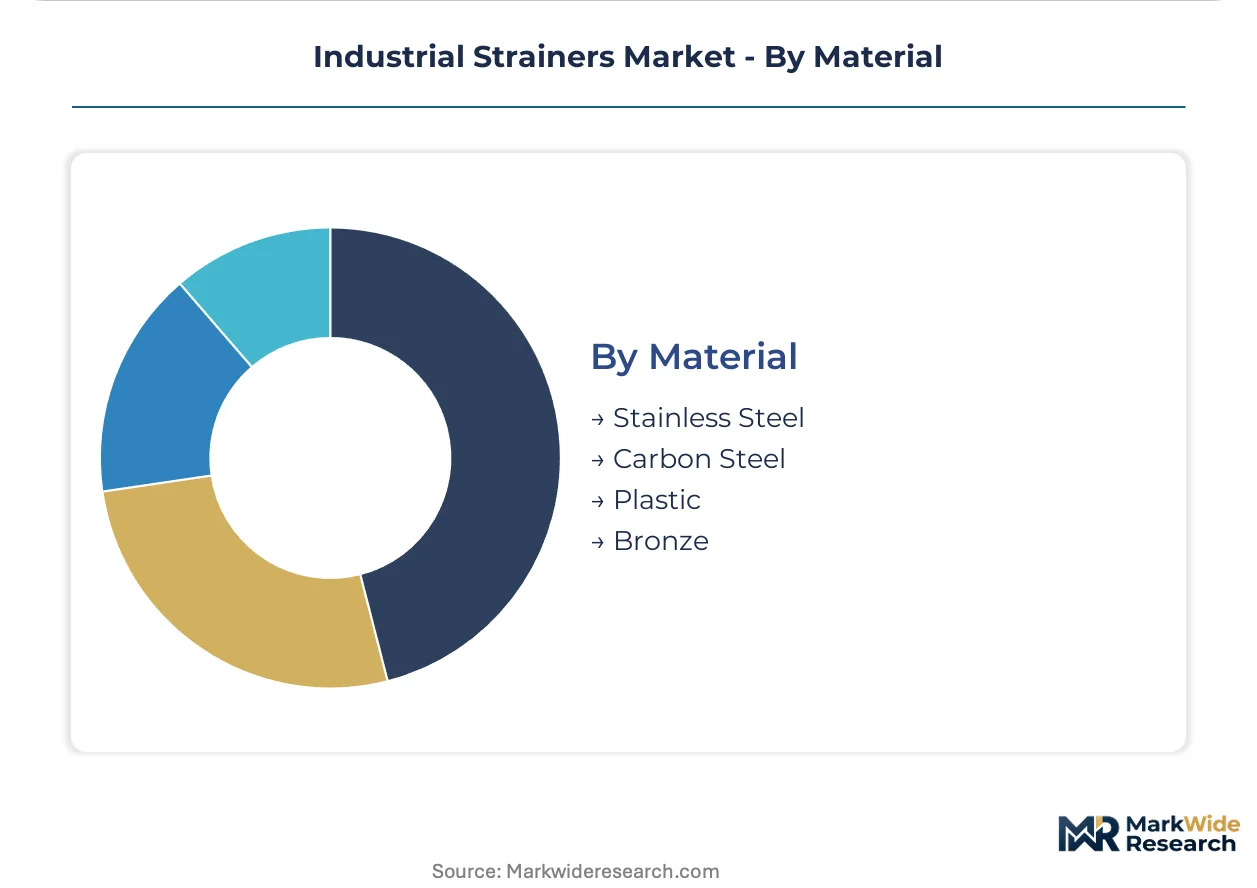
Material:
Cost tier stratification sharpens where certification requirements create non-negotiable specification floors.
- Stainless Steel:Grades 316 and 317L with FDA-compliant surface finishes dominate food and beverage end uses where 3A Sanitary Standards function as market-access gatekeepers. ASME Section VIII welding qualification burdens concentrate certified fabrication capacity among limited European and North American shops.
- Carbon Steel:Lower-cost alternatives retain relevance in non-corrosive utility applications with shorter replacement horizons. State pollution control mandates in India force domestic fabricators toward certified welding procedures and traceable material documentation that narrows the cost gap with stainless alternatives.
- Plastic:Polymer housings serve low-pressure chemical transfer with aggressive fluid compatibility requirements.
- Bronze:Marine and saltwater environments leverage corrosion resistance without stainless steel price exposure.
Stainless Steel dominates specification value; Carbon Steel retains volume in cost-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel scrap availability in Jamshedpur and nickel alloy processing in Norilsk anchor procurement networks for fabricators serving chemical corridors across multiple continents.
United States
Municipal water authorities in Texas and Florida consolidate procurement across merged regional utilities. EPA effluent limitation guidelines mandate filtration upgrades for secondary clarifier protection. Houston midstream operators specify duplex configurations to eliminate revenue loss from unplanned shutdowns.
Germany
Water treatment utilities expand duplex and basket strainer procurement to meet EU Urban Waste Water Treatment Directive requirements. EU F-Gas Regulation compliance timelines reshape specification criteria in HVAC-related process cooling circuits. Ruhr industrial clusters drive demand for automated switching mechanisms.
India
Chemical processing corridors in Gujarat and Maharashtra concentrate stainless steel Y-strainer demand. BIS pressure equipment certification and state pollution control mandates accelerate replacement cycles for carbon steel legacy installations. Domestic fabricators face forced migration toward certified welding procedures.
Japan
Continuous-process industries prioritize system protection against particulate damage to pumps and valves. METI industrial standards influence specification depth for downstream equipment replacement cost exposure. Osaka-Kobe chemical clusters sustain baseline demand for high dirt-holding capacity configurations.
Canada
Mining slurry and pulp paper processors in British Columbia deploy self-cleaning backflush mechanisms with programmable logic controllers. Health Canada environmental guidelines intersect with provincial water quality mandates. Vancouver fabrication shops serve cross-border utility contracts.
Industrial Strainers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart filtration integration and condition monitoring services. The vendor base stratifies across three maturity levels: multinational fluid power conglomerates with aftermarket distribution networks, regional specialists in custom-engineered duplex configurations, and domestic fabricators competing on certified welding documentation. Two strategic archetypes dominate: integrated system protection portfolios that bundle filtration with adjacent infrastructure, and focused component suppliers leveraging localized certification reciprocity. Competitive moves concentrate on M&A to capture consolidated utility procurement functions and capacity pre-positioning near tariff-sensitive import corridors.
Among North American-based conglomerates, Parker Hannifin Corporation and Eaton Corporation exemplify divergent strategic vectors. Parker Hannifin anchors aftermarket sales through fluid power distribution networks across industrial corridors. Eaton occupies a position emphasizing integrated system protection portfolios. Krone Filtertechnik represents the European specialist archetype, sitting within custom-engineered duplex configurations for chemical processors with stringent batch-purity requirements. These three entities illustrate how geographic origin and organizational structure shape competitive positioning without mandating identical capability investments.
| Leading Market Players |
|---|
| Watts Water Technologies |
| Hayward Flow Control |
| Parker Hannifin Corporation |
| Kitz Corporation |
| Smith & Loveless |
| Eaton Corporation |
| Krone Filtertechnik |
| Metraflex |
| Xylem Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ASME-qualified fabricators and uncertified competitors manifests in both pricing power and supply chain access, with pressure-rated duplex configurations commanding premium positioning while commodity basket strainers face margin compression from nickel alloy volatility and buyer consolidation.
Pricing Analysis
Warranty and predictive maintenance bundling separates premium OEM positioning from transactional component sales, with Parker Hannifin and Eaton anchoring recurring revenue through condition-monitoring subscriptions while regional fabricators compete on unit economics. Three-tier pricing structure across certified-premium, standard-grade, and economy-level configurations reflects ASME Section VIII welding documentation, 3A Sanitary Standards compliance, and bare carbon steel alternatives. Pricing pressure stems from consolidated utility procurement in Texas and Florida that compresses vendor counts and standardizes specifications. Municipal water authorities exhibit highest price sensitivity due to budget cycle constraints, while chemical processors with zero-tolerance downtime requirements show lowest sensitivity to upfront capital cost.
Supply Chain Analysis
Stainless steel feedstock dependency rests on Jamshedpur scrap processing and Norilsk nickel refining, with grade 316 and 317L plate availability tethered to alloy surcharge fluctuations and certified mill documentation requirements. Raw material inputs span nickel cathodes, molybdenum additives, and ASME-qualified welding consumables. Single-source vulnerability concentrates in European shops holding multiple jurisdiction certifications simultaneously, extending lead times for duplex fabrication. Distribution runs through fluid power distributors, OEM direct channels, and consolidated utility procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with upstream control over certified welding capacity and downstream capture of predictive maintenance platforms emerging as the decisive levers for margin defense.
For Market Incumbents: Cement aftermarket lock-in by embedding pressure differential sensors and predictive maintenance platforms into duplex strainer installations, converting capital sales into recurring revenue streams. Acquire certified fabrication capacity in tariff-proximate locations to defend against lead-time exposure from European shop concentration. Condition-monitoring integration represents the critical defensive lever against smart-filtration entrants.
For New Entrants and Emerging Players: Capture white-space in self-cleaning backflush mechanisms for mining slurry and pulp paper applications in British Columbia and Minnesota, where labor-hour reduction commands premium positioning. Target mid-tier chemical processors in India's Gujarat corridor seeking BIS-certified alternatives to legacy carbon steel installations. Lead with programmable logic controller integration and remote diagnostics as the differentiated go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with custom-engineered duplex specialists given EU F-Gas Regulation compliance timelines and HVAC cooling circuit upgrade cycles. Long-term viability favors fabricators with demonstrated ASME Section VIII qualification depth and traceable material documentation systems. Watch for nickel alloy price inflection and consolidated utility procurement function announcements as demand signal triggers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Welding Capacity | Captures ASME Section VIII qualification scarcity and compresses lead times for duplex fabrication. |
| Condition Monitoring Platform Development | Converts Parker Hannifin-style aftermarket sales into recurring revenue and predictive service contracts. |
| Geographic Capacity Pre-positioning | Localizes fabrication near Texas and Florida consolidated procurement functions to avoid tariff exposure. |
| 3A Sanitary Standards Certification Investment | Unlocks premium positioning in Wisconsin and California dairy processing with FDA-compliant surface finishes. |
| Self-cleaning Backflush Mechanism Launch | Targets Minnesota and British Columbia mining slurry applications with labor-hour reduction value proposition. |
Research Methodology
Multi-period observation of municipal procurement consolidation patterns, nickel alloy price trajectories, and certification reciprocity agreement developments anchored the trend analysis, supplemented by interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and utility engineering managers. Secondary validation drew from EPA effluent limitation guideline filings, EU Urban Waste Water Treatment Directive implementation timelines, BIS pressure equipment certification registers, and SEC 10-K disclosures from listed fluid power conglomerates. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, end user, application, material, and regional production hub dimensions.
Segment-weighting approaches applied differential growth assumptions to duplex strainer configurations versus commodity basket alternatives, with automation requirements and certification intensity serving as cross-cutting modifiers throughout the projection horizon. CAGRs derived from installed base replacement cycle analysis, regulatory compliance deadline clustering, and process continuity premium capture in continuous-process industries. Industry-specific forecast inputs included REACH substance restriction implementation pace for PFAS coating alternatives and consolidated utility procurement function formation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel alloy price volatility, welding certification shop capacity constraints, and tariff regime shifts. Projections reflect documented assumptions regarding regulatory enforcement intensity and buyer consolidation trajectories. A small set of triggers—nickel LME price movements, ASME qualification expansion announcements, and EU F-Gas Regulation compliance deadline adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Polymer Bearing Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Polyurethane Processing Machine Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Wedge Wire Screen Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Investment Casting Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Injection Molding Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Isotropic Graphite Market