
 Acrylic Sheet Market | 2026-2036
Acrylic Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Sheet Market Analysis
Modular panel systems with pre-cut dimensions and interlocking edge profiles is expanding buyer choice in architectural glazing and retail fixture markets. Evonik Industries leverages captive MMA monomer supply to sustain cost discipline across European and Asian plants. Mitsubishi Chemical anchors Asia-Pacific demand through high-optical-grade cast acrylic output for precision lighting applications. Plaskolite competes aggressively in North American distribution channels with broad extruded sheet inventories and rapid fulfillment networks.
Acrylic sheet denotes thermoplastic polymethyl methacrylate (PMMA) panels manufactured through extrusion, cell casting, or continuous casting, typically transmitting percent light values exceeding percent and offering tensile strength roughly half that of glass at under half the density. Its primary commercial purpose spans transparent protective barriers, illuminated signage faces, and aircraft-grade windows where weight reduction and impact resistance outweigh material cost premiums. Extruded acrylic dominates volume throughput due to faster production cycles and thinner-gauge availability, while cast acrylic commands margin pools in thick-section and optical-grade applications where molecular uniformity determines performance. Cell cast acrylic occupies a defensible niche in museum vitrines and high-end retail displays where surface hardness and solvent resistance justify extended lead times and price premiums over extruded alternatives.
FDA food-contact regulations, EPA emissions standards for VOC-releasing fabrication processes, and REACH substance restrictions on residual monomer content collectively shape product formulation and market access across major consumption zones. CE marking requirements under the EU Construction Products Regulation mandate fire-reaction classification testing that filters out uncertified suppliers from commercial building specifications. Stakeholders must monitor evolving building codes in California and the EU that tighten flammability thresholds for interior transparent materials, as compliance repositioning will determine which manufacturing configurations retain specification access.
Market Dynamics
REACH compliance deadlines in Europe and California's evolving fire-safety codes are compressing specification windows for uncertified extruded grades, redirecting procurement toward cast acrylic with verified reaction-to-fire classifications and residual monomer documentation.
Growth Catalysts
- Retail display replacement cycles:Brands are accelerating glass-to-acrylic conversions in flagship stores and pop-up installations, prioritizing shatter resistance and reduced shipping weight over material cost premiums.
- REACH substance restrictions:ECHA mandates on residual methyl methacrylate content are filtering supplier pools, creating specification advantages for European cell-cast producers with certified monomer recovery systems.
- Guangdong production cluster:Dense extrusion and casting capacity in China's Pearl River Delta enables rapid turnaround on custom gauge and color orders for North American signage distributors.
Market Restraints
- MMA monomer volatility:Acetone cyanohydrin route feedstock costs fluctuate with propylene and ammonia pricing, squeezing margin predictability for non-integrated sheet converters.
- Cell-cast capacity concentration:Thick-section optical-grade supply concentrates among a handful of European and Japanese producers, creating lead-time vulnerability for museum and aviation glazing programs.
- Polycarbonate substitution:Impact-resistant polycarbonate sheets penetrate price-sensitive safety barrier applications where optical clarity requirements are secondary to ballistic performance.
Strategic Opportunities
- Modular architectural systems:Pre-cut interlocking panel formats with integrated edge profiles open specification access in commercial interior fit-out contracts previously reserved for glass curtain wall specialists.
- India building code alignment:BIS fire-performance testing protocols for transparent cladding materials are converging with EN 13501 standards, enabling European-certified suppliers to enter commercial construction specifications.
- UV-curable coating convergence:Hard-coat surface treatment lines integrated at extrusion exit points are collapsing the performance gap between extruded and cast grades in high-traffic retail environments.
Industry Challenges
- Optical-grade metrology talent:Cell-cast production requires technicians skilled in interferometry and haze measurement protocols, with training pipelines failing to match capacity expansion timelines in Asia-Pacific.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of CE marking, FDA food-contact clearance, and FAA aircraft transparency approval extends product launch cycles by 18-24 months for specialized grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Sheet Market |
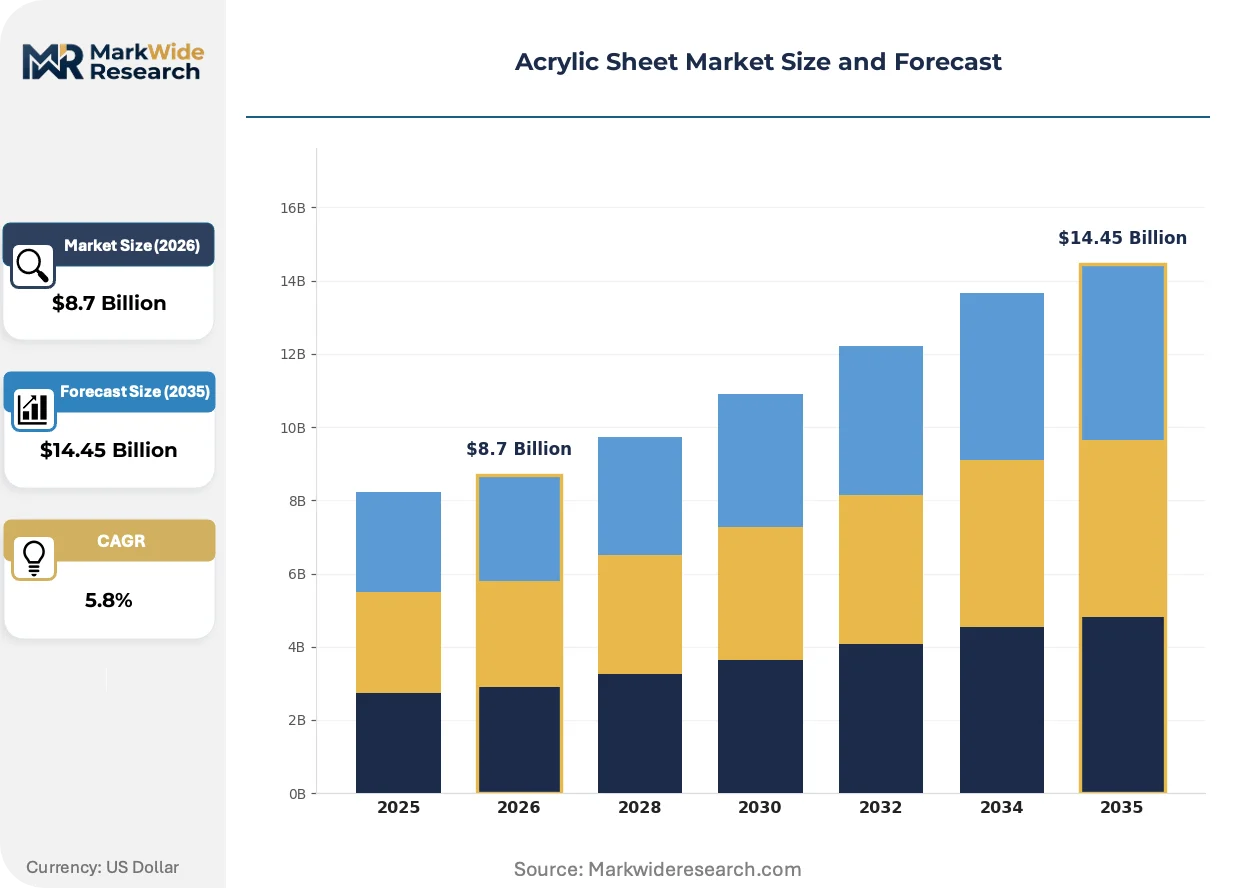
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Acrylic, Cast Acrylic, Cell Cast Acrylic, Injection Molded Acrylic Application: Signage, Windows, Displays, Lighting End User: Construction, Automotive, Electronics, Retail Thickness Range: Thin, Standard, Thick, Ultra-Thick |
| Companies Covered | Schweiter Technologies, Evonik Industries, Polyventis, Arkema, Palram Industries, Mitsubishi Chemical, Plaskolite, Chimei, Trinseo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Sheet Market Emerging Trajectories
Acrylic sheet manufacturing is pivoting from commodity gauge production toward configured-to-order systems where surface treatment, dimensional precision, and embedded functionality determine competitive position more than base resin cost.
Co-extruded capstock technology is modularizing. Thin-layer UV-absorbing and abrasion-resistant polymers fused during continuous extrusion eliminate secondary coating steps. Architectural glazing contractors in Germany and the Netherlands are specifying these pre-finished sheets for atrium canopies and skylight retrofits. The technology is modularizing supply chains by collapsing fabrication stages and reducing field-labor dependencies.
EU Construction Products Regulation fire-reaction classifications are tightening. EN 13501-1 B-s1,d0 ratings are becoming mandatory for interior transparent barriers in commercial buildings above three stories. French and Spanish specification writers are rejecting uncertified extruded grades for lobby partitions and elevator enclosures. Italian producers are investing in halogen-free flame-retardant masterbatch compounding to retain access to public-sector tenders.
Signage fabricators are consolidating purchase volumes through distributor-managed inventory programs. Large-format print shops in Texas and Florida are shifting from spot-buying standard sheet sizes to annual framework agreements with pre-allocated extrusion capacity. This concentration is visible most acutely in the out-of-home advertising vertical, where national rollouts of retail network rebranding campaigns require guaranteed availability of color-matched batch runs across multiple fabrication sites.
Acrylic Sheet Market Segmentation
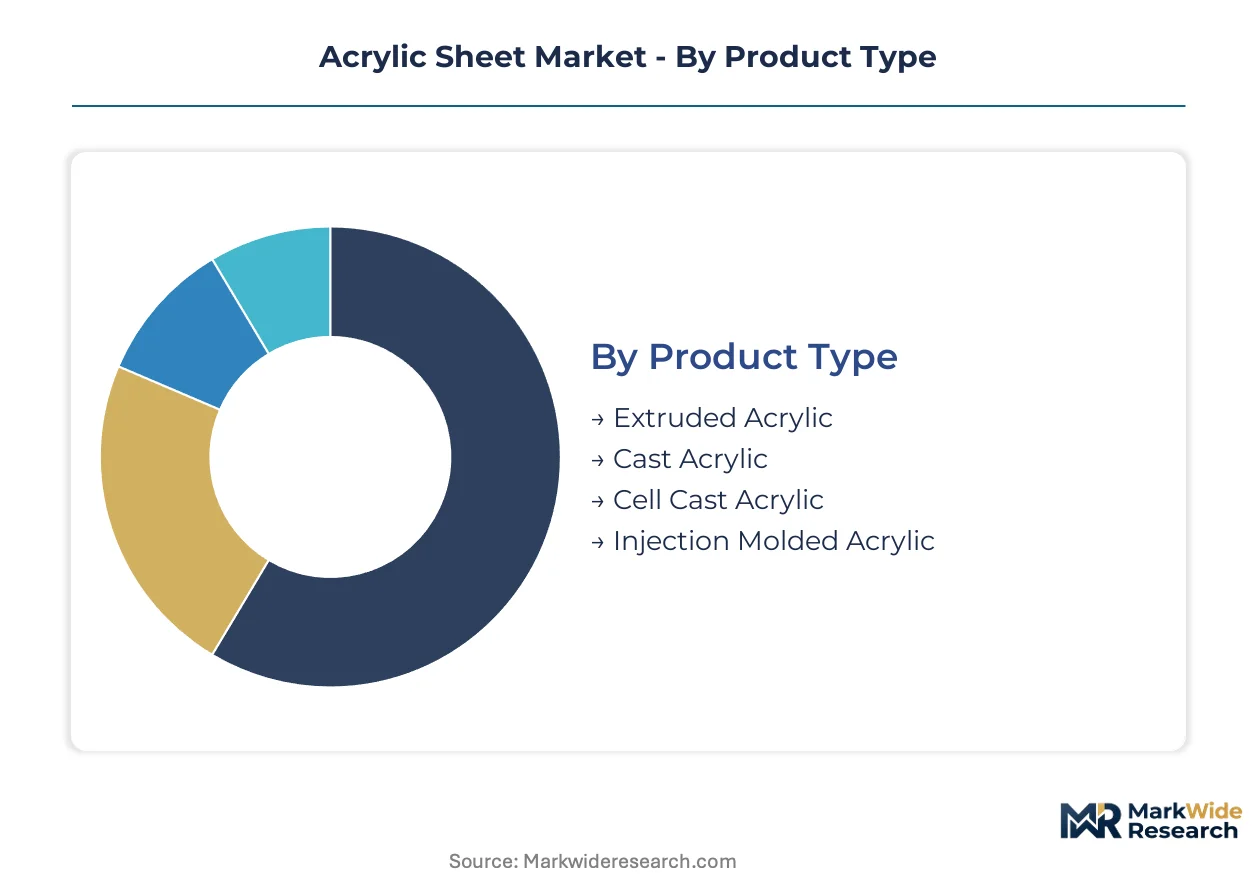
Acrylic sheet procurement divides sharply between high-volume extruded grades and premium-positioned cast variants, with specification requirements from EU fire codes and FDA food-contact rules further fragmenting supplier pools. Understanding where volume throughput concentrates versus where margin accrues enables targeted positioning across architectural, automotive, and retail display verticals.
Product Type:
Volume throughput concentrates in extruded grades, while cast and cell-cast variants command specification premiums in optical and thick-section applications.
- Extruded Acrylic:Continuous production through heated dies yields thinner gauges at faster cycle times than casting methods. Demand concentrates in North American signage distributors and Guangdong-based export fabricators serving retail fixture programs where cost sensitivity outweighs optical perfection requirements.
- Cast Acrylic:Liquid monomer polymerization in molds delivers superior molecular uniformity and surface hardness. German and Japanese producers dominate specification access for museum vitrines and aircraft glazing where REACH-compliant residual monomer documentation and FAA transparency approval are mandatory.
- Cell Cast Acrylic:Glass-cell manufacturing achieves the highest optical clarity and solvent resistance. Premium retail displays in Paris and Tokyo flagship stores specify this grade despite extended lead times.
- Injection Molded Acrylic:Pellet-fed molding suits complex geometries and integrated fastening features. Automotive interior trim programs in Stuttgart and Detroit leverage this format for curved instrument cluster lenses.
Today's leader: Extruded Acrylic. Tomorrow's challenger: Cell Cast Acrylic.
Application:
End-use requirements range from weathering resistance in exterior glazing to haze control in precision lighting, reshaping formulation priorities across production lines.
- Signage:UV-stabilized formulations with co-extruded capstock dominate large-format outdoor advertising. Texas and Florida print shops consolidate annual volumes through distributor-managed inventory programs guaranteeing color-matched batch availability.
- Windows:Thermal insulation and impact resistance specifications vary by building code jurisdiction. California's evolving fire-safety codes compress approval windows for uncertified grades.
- Displays:Shatter-resistant barriers replace glass in flagship retail environments. Brands prioritize reduced shipping weight and fabrication flexibility over material cost premiums.
- Lighting:High-transmission optical grades with sub-1% haze values enable LED diffusion and precision luminaire applications. Dutch and German architectural glazing contractors specify pre-finished sheets for atrium canopies.
Signage absorbs the highest volume. Lighting commands the steepest expansion trajectory as LED retrofit programs accelerate.
End User:
Customer technical sophistication varies from commodity procurement in construction to certified material traceability requirements in automotive and electronics.
- Construction:CE marking under EU Construction Products Regulation and EN 13501-1 fire-reaction classifications filter supplier access for commercial interior barriers above three stories.
- Automotive:Weight reduction mandates drive polycarbonate-acrylic hybrid glazing programs. KBA certification requirements in Germany and NHTSA standards in the US govern optical distortion limits.
- Electronics:Display cover lenses and light-guide plates demand ultra-low birefringence. Japanese and South Korean panel manufacturers specify metrology protocols exceeding standard commercial grades.
- Retail:Pop-up installation cycles and modular fixture systems favor rapid-turn extruded sheet with pre-cut dimensions. National rebranding campaigns require guaranteed availability across multiple fabrication sites.
Construction generates baseline demand. Electronics is gaining share fastest as display manufacturers reshore optical-grade supply chains.
Thickness Range:
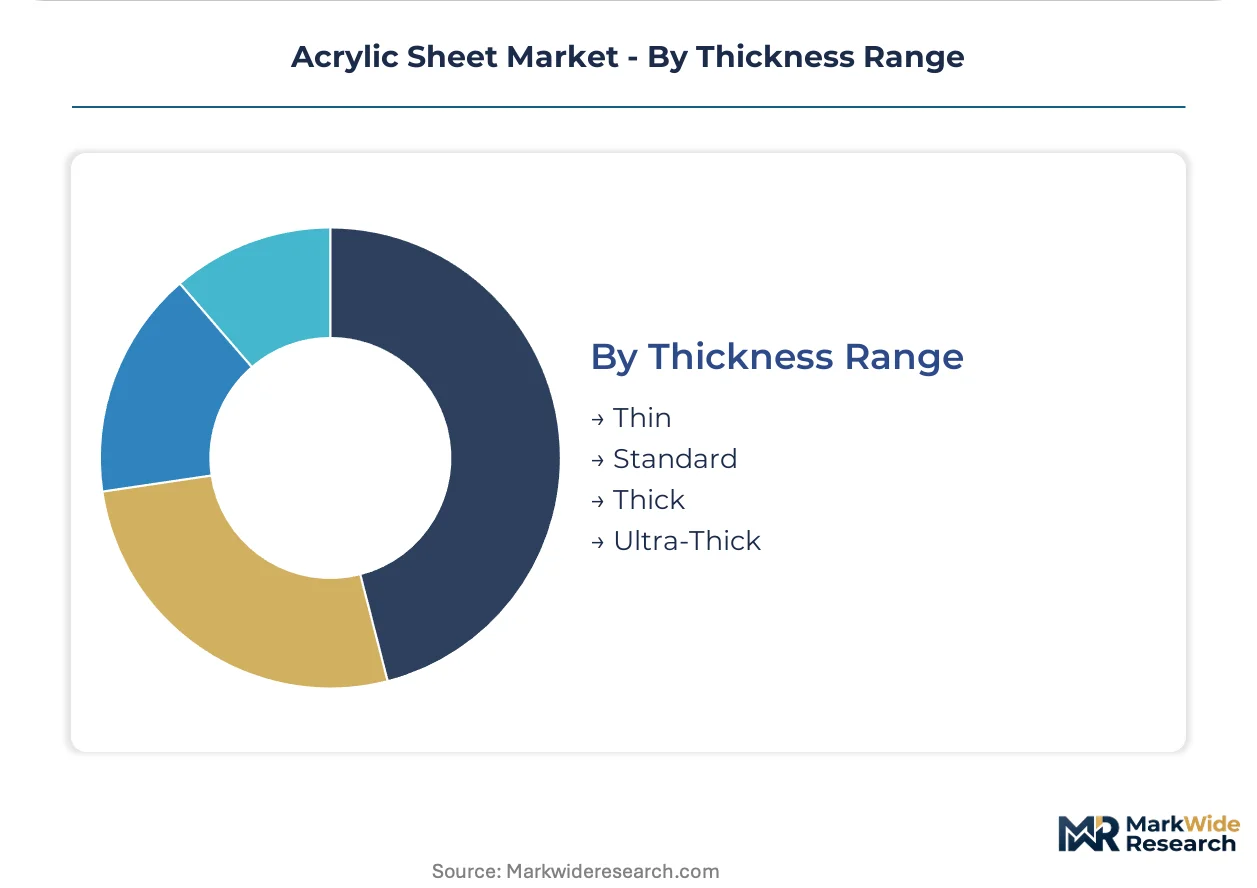
Gauge selection determines manufacturing process compatibility and end-use structural performance, with thick and ultra-thick segments concentrating among limited cell-cast capacity.
- Thin:Sub-2mm gauges suit thermoformed packaging and decorative overlays. High-speed extrusion lines in China's Pearl River Delta optimize throughput in this range.
- Standard:2-6mm thickness covers general-purpose signage and interior glazing. Volume availability supports distributor stocking programs across North American channels.
- Thick:6-12mm sections require cast production for optical uniformity. European and Japanese producers control specification access for aquarium and security barrier applications.
- Ultra-Thick:Above 12mm, cell-cast methods dominate with extended cure cycles. Museum vitrine and ballistic glazing programs absorb limited supply from specialized producers.
Standard thickness anchors procurement volumes. Ultra-Thick faces persistent lead-time vulnerability as optical-grade metrology talent pipelines lag capacity expansion timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylic sheet manufacturing traces its industrial roots to German chemical innovation in the 1930s, with subsequent capacity scaling across North America and Asia-Pacific. Regional demand patterns now diverge sharply between mature replacement markets and emerging construction economies.
China
Guangdong province hosts the densest concentration of extrusion and cell-cast production capacity worldwide. GB standards for building materials and automotive glazing tighten certification requirements for transparent polymers. Shenzhen and Dongguan fabrication clusters supply both domestic signage exports and local EV glazing programs.
Germany
REACH compliance deadlines and EN 13501-1 fire-reaction classifications filter supplier access for commercial interior applications. KBA certification requirements govern optical distortion limits in automotive glazing specifications. Baden-Württemberg and North Rhine-Westphalia retain specialized cell-cast capacity for museum and aviation-grade output.
United States
Texas and Florida print shops consolidate annual volumes through distributor-managed inventory programs for large-format outdoor advertising. California's evolving fire-safety codes compress approval windows for uncertified extruded grades. NHTSA standards and FDA food-contact regulations shape formulation priorities across Midwestern extrusion corridors.
Japan
Ultra-low birefringence specifications from display manufacturers in Osaka and Tokyo drive demand for precision optical grades. METI industrial standards and JIS certification protocols govern material traceability for electronics applications. Nagoya-area producers specialize in high-transmission grades for LED diffusion and precision luminaire programs.
India
BIS fire-performance testing protocols for transparent cladding materials are converging with EN 13501 standards. Construction activity in Maharashtra and Gujarat generates baseline demand for architectural glazing and retail fixture applications. Mumbai and Ahmedabad fabrication hubs increasingly specify certified cast grades for commercial interior fit-outs.
Acrylic Sheet Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and optical-grade capability. The vendor base stratifies into three tiers: integrated monomer-to-sheet producers with captive MMA supply, specialized cell-cast fabricators with metrology-intensive quality systems, and high-volume extrusion houses competing on gauge availability and fulfillment velocity. Strategic moves concentrate on backward integration into monomer production and co-extrusion technology licensing to collapse secondary coating steps.
Within the integrated chemical conglomerate tier, Evonik Industries and Mitsubishi Chemical exemplify archetypes leveraging upstream control over methyl methacrylate supply to sustain cost discipline across European and Asian manufacturing footprints. Among North American distribution-focused players, Plaskolite occupies a position emphasizing rapid fulfillment networks and broad extruded sheet inventories. Cell-cast specialists including Schweiter Technologies represent the premium-grade vector where molecular uniformity and surface hardness command specification access in museum vitrine and aircraft glazing programs.
| Leading Market Players |
|---|
| Schweiter Technologies |
| Evonik Industries |
| Polyventis |
| Arkema |
| Palram Industries |
| Mitsubishi Chemical |
| Plaskolite |
| Chimei |
| Trinseo |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up North American distributors have consolidated procurement volumes across Texas and Florida print-shop networks, compressing spot-market liquidity while extending payment terms that strain non-integrated extrusion houses. This ownership pattern concentrates buyer leverage against fragmented upstream supply, translating volume commitments into preferential gauge availability and color-matched batch prioritization that independent fabricators cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified cell-cast grades from commodity extruded sheet and import-dependent thin-gauge supply. Certification grade under EU Construction Products Regulation and FDA food-contact clearance command substantial premiums over uncertified alternatives. Cost compression in standard extruded tiers is intensifying because MMA monomer volatility squeezes non-integrated converters. Signage distributors exhibit the highest price sensitivity, while museum and aviation glazing programs demonstrate minimal elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive and electronics demand, while distributor-managed inventory programs serve fragmented signage and retail fixture buyers. Manufacturing concentrates in China, Germany, and Japan, with Guangdong province anchoring extrusion throughput and Baden-Württemberg retaining cell-cast specialization. Feedstock draws from acetone cyanohydrin-derived methyl methacrylate, propylene, and ammonia streams. Single-source vulnerability concentrates in thick-section optical-grade capacity. Distribution runs through regional stocking locations in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Acrylic Sheet Market functions as a stable compounder where replacement-driven demand from retail display retrofit cycles generates predictable volume baselines. Regulatory compliance investments create durable moats for certified producers.
For Market Incumbents: Deepen backward integration into captive MMA monomer production to insulate margin predictability from acetone cyanohydrin feedstock volatility. Expand cell-cast capacity in Germany or Japan to reduce lead-time vulnerability for museum and aviation glazing programs. Polycarbonate substitution in safety barrier applications represents the most pressing substitution threat requiring optical-grade performance differentiation. For New Entrants and Emerging Players: The mid-tier price gap between premium REACH-certified cast grades and economy extruded imports offers entry space for halogen-free flame-retardant extruded products. Target Indian commercial construction specifications as BIS protocols converge with EN 13501 standards. Pursue co-extrusion technology licensing to collapse secondary coating steps and accelerate specification access. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion houses lacking certification depth but possessing established distributor relationships. Five-to-ten-year viability favors integrated monomer-to-sheet producers with European and Asian manufacturing footprints. Monitor ECHA substance restriction enforcement intensity as an inflection indicator for specification-driven margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Monomer | Captive supply from Evonik Industries insulates margin predictability against acetone cyanohydrin feedstock swings. |
| Co-extrusion Capstock Technology Licensing | Hard-coat surface treatment at extrusion exit collapses fabrication stages for German atrium canopy contractors. |
| REACH Certification Investment | ECHA residual monomer documentation filters supplier pools for European museum vitrine specifications. |
| Guangdong Capacity Expansion | Pearl River Delta extrusion scaling serves North American signage distributor consolidation trends. |
| Halogen-Free Flame-Retardant Masterbatch Development | EN 13501-1 B-s1,d0 compliance retains Italian producer access to public-sector tender opportunities. |
Methodological Framework
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, technical R&D directors, and distribution channel partners — were reconciled against secondary validation from customs and trade data, SEC 10-K filings, and Cefic industry reports. Bottom-up and top-down triangulation cross-checked volume estimates across extrusion and cell-cast production configurations.
Data-stream reconciliation anchored analytical framework development across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry, thickness range, and regional production hub. CAGRs were derived through growth driver decomposition and substitution elasticity assessment. Forecast inputs incorporated MMA monomer price trajectory assumptions and regulatory compliance timeline convergence.
Caveats apply where ECHA enforcement intensity, California fire-code evolution, or polycarbonate substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions subject to revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Fly Ash Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Industrial Silica Sand Market
Industrial Materials
Polymer Bearing Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Global Jet Mill Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Magnet Rings Market