
 Conveyor Belt Materials Market | 2026-2036
Conveyor Belt Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Belt Materials Market Analysis
The conveyor belt materials market is recalibrating around a widening split between premium reinforced compounds for extreme-temperature mining and commodity-grade PVC for light manufacturing. Continental AG leverages captive polymer research to dominate heat-resistant formulations for steel and cement applications. Bridgestone Corporation anchors its position through integrated rubber sourcing from Southeast Asian plantations. Fenner Dunlop competes on aramid-reinforced belt architectures that extend service life in Australian iron ore corridors.
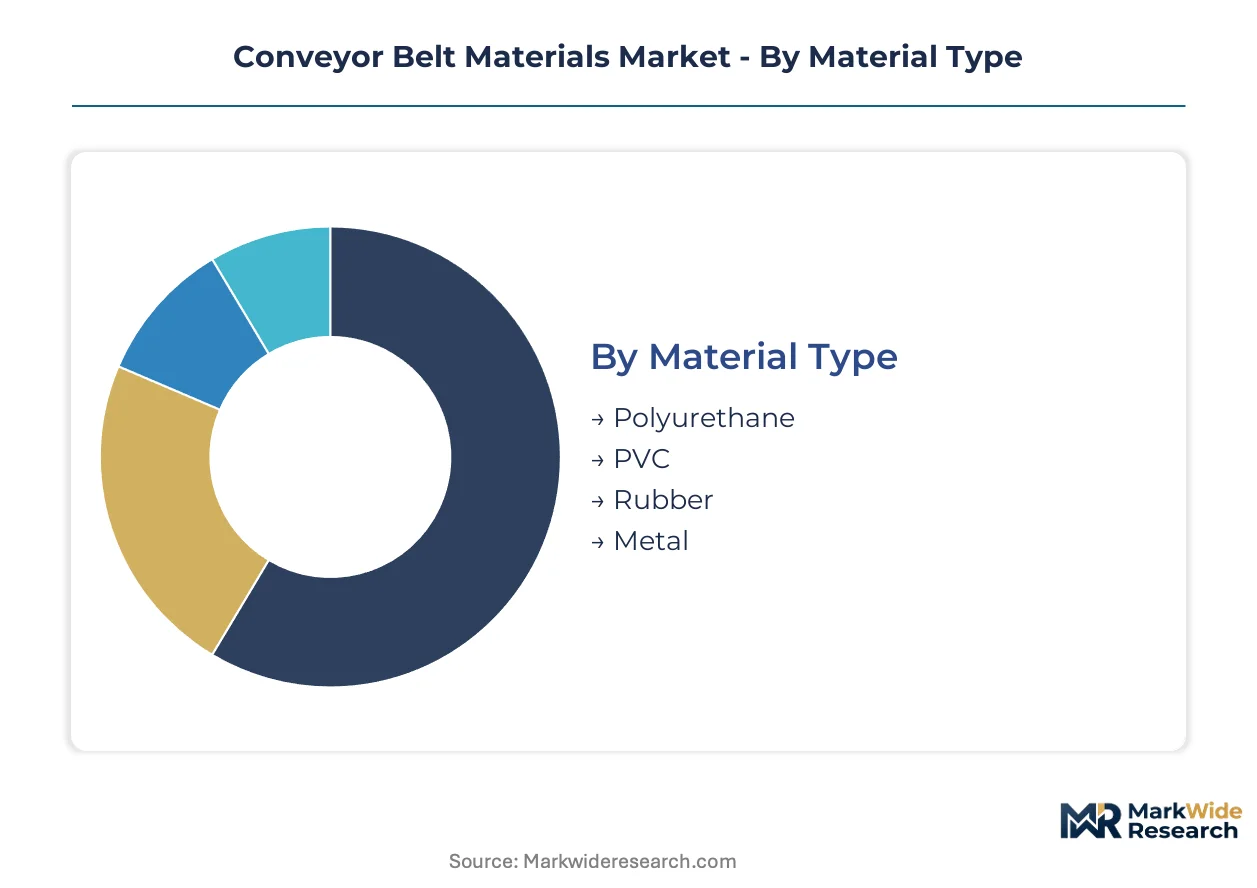
Conveyor belt materials comprise layered elastomeric or thermoplastic compounds, typically reinforced with fabric plies or steel cords, engineered to transmit bulk solids across fixed distances under tensile loads exceeding 1,000 N/mm. Rubber formulations incorporate styrene-butadiene or natural latex for abrasion resistance, while PVC and polyurethane alternatives serve food-grade and chemical-contact environments where oil or moisture exposure demands non-porous surfaces. The material type dimension shows rubber retaining the largest volume share due to mining dependency, though polyurethane is gaining fastest in food and beverage sanitation lines where thermoplastic cleanability outperforms cured elastomers. End use industry segmentation reveals mining as the margin pool leader, with thick-section belts commanding premium pricing against thin-profile manufacturing belts where commoditization pressures concentrate.
OSHA mandates in the United States govern workplace conveyor safety and fire-resistance ratings, while REACH and the EU Green Deal restrict hazardous plasticizers and accelerate recycled-content thresholds in European supply chains. China's GB standards and MEE enforcement on industrial emissions shape domestic compound formulations and cross-border certification requirements for belt exporters. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance fragmentation threatens to partition supply chains into region-locked product lines with incompatible material specifications.
Market Dynamics
REACH and EU Green Deal mandates are forcing compound reformulation across the supply base, while Australian and Chilean mining procurement concentrates demand for heat-resistant reinforced belts. This regulatory-mining tension is compressing margins on legacy rubber formulations while rewarding thermoplastic recyclability investments.
Growth Catalysts
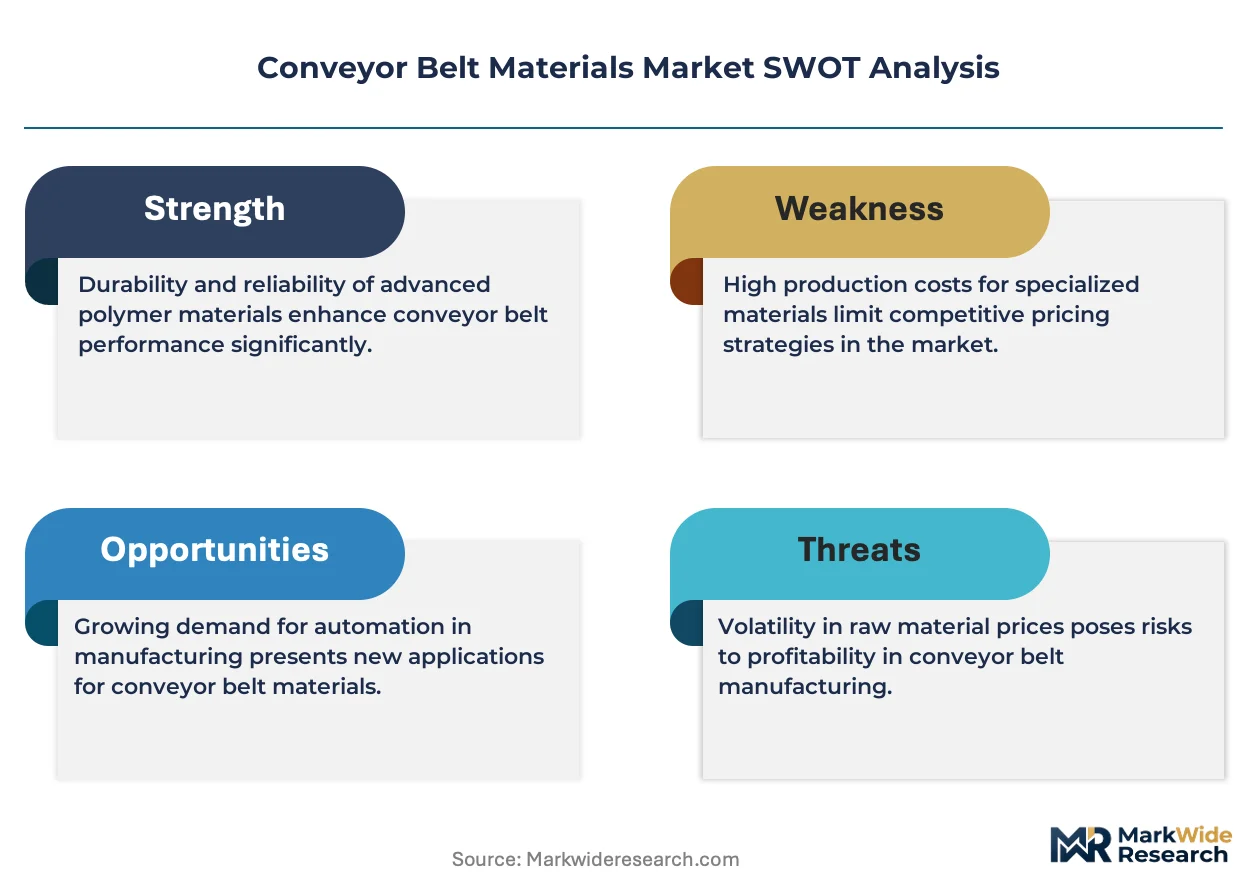
- REACH plasticizer restrictions:European manufacturers accelerate phthalate-free compound development, creating certified product lines that command premium positioning in cross-border tenders.
- Port automation in China:Automated coal and ore handling systems sustain heavy replacement cycles for steel-cord reinforced belts in the Bohai Rim industrial corridor.
- Aramid reinforcement adoption:Mining operators in Australian iron ore corridors specify aramid carcass architectures to extend service intervals in high-tensile bulk transport applications.
Market Restraints
- Natural rubber price volatility:Southeast Asian plantation output fluctuations transmit directly to compound cost structures, compressing margin stability for non-integrated manufacturers.
- Recycled-content certification timelines:EU Green Deal recycled-threshold mandates impose multi-year validation cycles that delay product qualification and lock out smaller compounders.
- Thermoplastic substitution in food-grade:Polyurethane cleanability advantages are displacing PVC in beverage sanitation lines, eroding volume in a historically stable segment.
Strategic Opportunities
- Underpenetrated Indian mining:Domestic coal and bauxite expansion under CEA power-sector mandates creates demand for heat-resistant compounds currently served by imports.
- Carbon-capture retrofit belts:Cement and steel producers installing emission-capture equipment require modified belt chemistries resistant to amine-based solvent exposure.
- Digital-twin integration:Predictive maintenance platforms from industrial automation vendors are converging with belt sensorization to enable condition-based replacement contracts.
Industry Challenges
- Compounder chemist scarcity:Formulation expertise for high-temperature elastomer blends concentrates among retiring specialists, constraining R&D throughput.
- Multi-jurisdiction certification overlap:Belt exporters face redundant testing for OSHA fire-resistance, REACH substance restrictions, and China's GB standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Belt Materials Market |
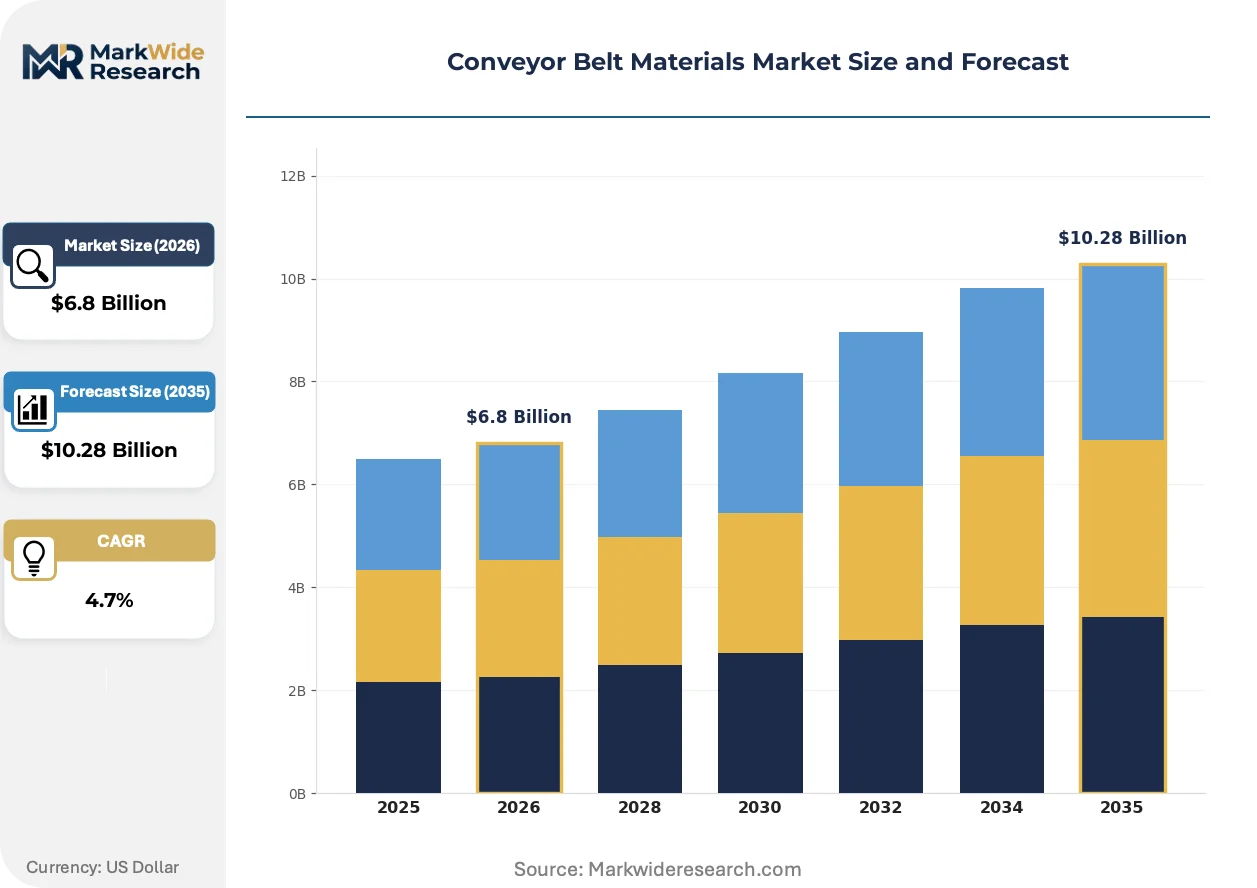
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, PVC, Rubber, Metal End Use Industry: Food & Beverage, Mining, Manufacturing, Agriculture Thickness: Thin, Medium, Thick, Extra Thick Surface Finish: Smooth, Textured, Coated, Reinforced |
| Companies Covered | Continental AG, Bridgestone Corporation, Fenner Dunlop, Bando Chemical Industries, The Yokohama Rubber Co., Goodyear, Qingdao Rubber Six Conveyor Belt, Zhejiang Double Arrow, Nitta Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Belt Materials Market Emerging Trajectories
Material science advances are compressing the performance gap between commodity PVC and premium rubber compounds, while regulatory chemistry restrictions force simultaneous reformulation across multiple product tiers. These pressures are accelerating modular belt architectures that simplify field splicing and reduce total installed cost.
Sensor-embedded belt carcasses are converging with industrial IoT platforms to enable real-time tension monitoring and predictive failure alerting. Mining operators in Australian Pilbara corridors are piloting these systems to optimize maintenance windows. The technology is compressing traditional time-based replacement schedules toward condition-triggered procurement models.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing compounders to rebuild plasticizer portfolios from base chemistry. Belt manufacturers serving European steel and cement customers must requalify entire product lines under tightened substance thresholds. The regulatory pressure is most acute in heat-resistant formulations where legacy flame-retardant packages face phased elimination.
Maintenance outsourcing contracts are displacing in-house belt management at port and mining operators facing skilled technician shortages. Third-party service providers now bundle installation, splicing, and monitoring into multi-year agreements. This pattern is most visible in China's automated coal terminals where labor cost inflation meets uptime guarantee requirements.
Conveyor Belt Materials Market Segmentation
Material specification drives pricing power in conveyor belt procurement, with compound chemistry and reinforcement architecture determining suitability for temperature extremes, chemical exposure, and tensile loads. Segmentation reveals how mining operators prioritize durability premiums while food processors optimize for cleanability compliance.
Material Type:
Rubber formulations anchor the technology hierarchy through styrene-butadiene and natural latex blends engineered for abrasion resistance and heat tolerance in bulk transport.
- Rubber:Layered elastomeric compounds reinforced with fabric plies or steel cords transmit bulk solids under tensile loads exceeding 1,000 N/mm. Mining corridors in Australia and Chile specify thick-section rubber belts for iron ore transport, with procurement cycles tied to pit expansion schedules and port automation timelines.
- Polyurethane:Thermoplastic elastomers offer non-porous surfaces resistant to oils, moisture, and microbial colonization. Food and beverage sanitation lines in European processing plants specify polyurethane for cleanability advantages that outperform cured elastomers under HACCP protocols.
- PVC:Commodity-grade thermoplastic serves light manufacturing and package handling where cost sensitivity outweighs performance extremes. Chinese industrial clusters deploy PVC belts in automated sorting facilities for e-commerce fulfillment.
- Metal:Stainless steel and carbon steel constructions withstand extreme temperatures and sharp-edged materials in foundry and slag handling applications.
Rubber leads on scale; polyurethane leads on momentum.
End Use Industry:
Application environment dictates compound selection, with regulatory chemistry restrictions and mechanical stress profiles creating divergent procurement priorities across sectors.
- Mining:Thick-section belts with aramid or steel-cord reinforcement handle high-tensile bulk transport in Australian Pilbara iron ore corridors. Replacement cycles concentrate around automated port expansions and pit deepening projects that extend haul distances.
- Food & Beverage:Thermoplastic belts with smooth or textured surfaces meet FDA and EU food-contact regulations for cleanability and allergen control. Brewery and dairy processors specify polyurethane formulations that withstand caustic washdown protocols.
- Manufacturing:Light-duty PVC and rubber belts serve assembly lines and package conveyance where moderate tensile loads and standard temperature ranges apply.
- Agriculture:Grain handling and processing facilities utilize medium-duty rubber compounds resistant to abrasion from seed and feed materials.
Mining commands premium pricing; food and beverage shows steepest expansion trajectory.
Thickness:
Section dimension correlates directly with tensile rating and service interval expectations, with thick profiles commanding disproportionate margin contribution.
- Thick:Multi-ply constructions exceeding standard gauges serve mining and heavy aggregate transport where puncture resistance and load distribution determine operational uptime. Australian and Chilean procurement specifications prioritize thick-section belts for bulk ore corridors.
- Extra Thick:Specialized profiles for extreme impact zones and primary crusher feeds absorb shock loads that would degrade standard constructions.
- Medium:General-purpose industrial applications balance durability against installed cost in manufacturing and logistics environments.
- Thin:Lightweight profiles for package handling and precision positioning where flexibility and energy efficiency outweigh abrasion resistance.
Thick profiles dominate revenue contribution; extra thick segments expand most quickly in mining automation retrofits.
Surface Finish:
Top-cover architecture determines friction coefficients, release properties, and compliance with product-contact regulations across end-use environments.
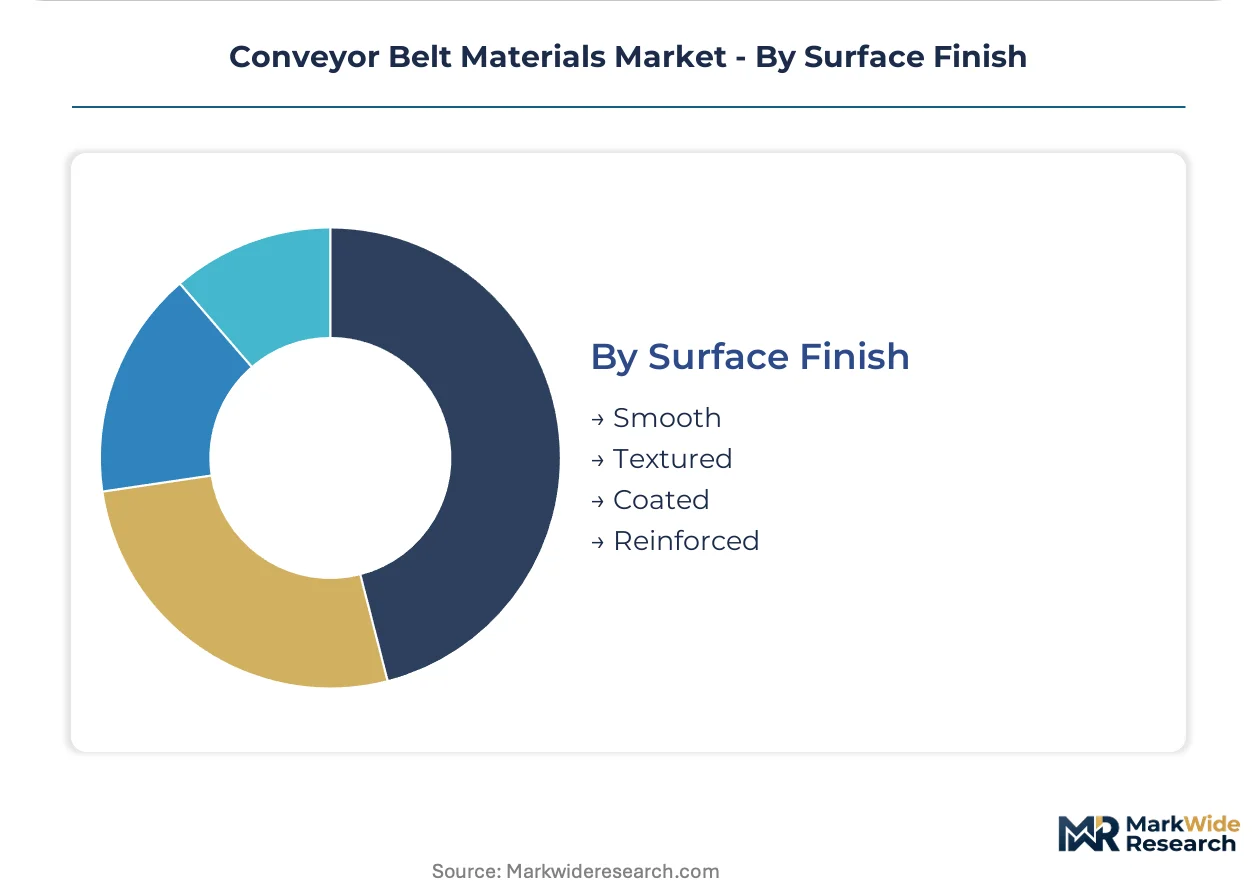
- Reinforced:Embedded fabric or metallic layers beneath the running surface extend service life in high-impact zones and sharp-edged material streams. Cement and steel producers specify reinforced finishes for clinker and slag handling.
- Smooth:Non-porous surfaces facilitate cleaning and sanitation in food processing and pharmaceutical applications where residue accumulation risks contamination.
- Textured:Patterned surfaces increase friction coefficients for inclined transport and package handling where slippage would disrupt throughput.
- Coated:Specialized polymer overlays provide chemical resistance or low-friction properties for specific process environments.
Reinforced finishes anchor mining procurement; smooth surfaces gain share fastest in food-grade specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rubber compounders and polymer engineers concentrate in mining-adjacent industrial zones, anchoring regional supply capabilities to ore transport corridors and port automation clusters.
Australia
Pilbara iron ore operators specify aramid-reinforced belts for high-tensile bulk transport across extended haul distances. TGA certification requirements govern fire-resistance ratings for underground mining applications. Perth-based procurement offices coordinate replacement cycles tied to automated port expansions at Port Hedland and Dampier.
Germany
Steel and cement producers drive specification for heat-resistant compounds resistant to clinker and slag exposure. REACH Annex XVII restrictions on short-chain chlorinated paraffins force base-chemistry rebuilds of plasticizer portfolios. Industrial belt fabricators in North Rhine-Westphalia serve Ruhr Valley heavy industry with requalified product lines.
China
Automated coal handling systems in the Bohai Rim industrial corridor sustain heavy replacement cycles for steel-cord reinforced belts. MEE enforcement on industrial emissions shapes domestic compound formulations and cross-border certification requirements. Qingdao and Shanghai port clusters concentrate procurement for iron ore and coal logistics automation.
Chile
Copper mining expansion in the Atacama Desert generates procurement for thick-section belts in bulk ore transport applications. National mining safety regulations govern fire-resistance and tensile rating specifications for underground operations. Antofagasta and Calama mining corridors anchor demand concentration for heat-resistant reinforced compounds.
United States
Cement and steel producers installing carbon-capture equipment require modified belt chemistries resistant to amine-based solvent exposure. OSHA mandates govern workplace conveyor safety and fire-resistance ratings in surface and underground operations. Appalachian coal logistics and Great Lakes bulk terminals concentrate replacement demand for heavy-duty rubber constructions.
Conveyor Belt Materials Market Vendor Landscape
Capital-heavy producers with captive polymer research compete with asset-light compounders sourcing elastomer blends from merchant suppliers. The vendor base stratifies across integrated rubber processors, specialized reinforcement architects, and regional fabrication shops serving proximity-sensitive installation contracts. Three archetypes dominate: plantation-integrated compounders controlling natural latex supply chains; aramid-reinforcement specialists extending service intervals through carcass innovation; and thermoplastic formulators targeting food-grade sanitation compliance. Competitive moves concentrate on backward integration into Southeast Asian rubber sourcing and multi-jurisdiction certification stacking for cross-border tender eligibility.
Among plantation-integrated compounders, Bridgestone Corporation exemplifies upstream control over natural latex supply chains. Continental AG occupies a position within the heat-resistant formulation tier, representing captive polymer research capabilities for extreme-temperature mining applications. Fenner Dunlop anchors the aramid-reinforcement specialist archetype, exemplifying service-life extension through carcass architecture innovation in Australian iron ore corridors.
| Leading Market Players |
|---|
| Continental AG |
| Bridgestone Corporation |
| Fenner Dunlop |
| Bando Chemical Industries |
| The Yokohama Rubber Co. |
| Goodyear |
| Qingdao Rubber Six Conveyor Belt |
| Zhejiang Double Arrow |
| Nitta Corporation |
| Others |
Supply Flow & Price Mechanics
Australian and Chilean mining procurement offices concentrate demand for thick-section aramid-reinforced belts, anchoring contract-based long-term offtake pricing that rewards compounders with heat-resistant formulation capabilities and multi-jurisdiction certification stacks.
Pricing Analysis
Service bundling separates equipment-only transactions from comprehensive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion. Cost compression in commodity PVC tiers is intensifying because polyurethane substitution in food-grade applications erodes volume. Small-scale manufacturing buyers exhibit highest price sensitivity; mining operators with uptime guarantee requirements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian natural rubber plantations that feed compound formulations. Manufacturing draws from Thailand, Indonesia, and Malaysia for latex supply; China and Germany for steel-cord and aramid reinforcement fabrication. Commodity price volatility in plantation output threatens margin stability for non-integrated compounders. Distribution runs through regional fabrication shops serving proximity-sensitive installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as mining operators shift procurement specifications toward aramid-reinforced architectures that extend service intervals and reduce total cost of ownership.
For Market Incumbents: Deploy captive polymer research capabilities to accelerate phthalate-free compound development ahead of REACH Annex XVII enforcement timelines. Backward integration into Southeast Asian rubber sourcing defends margin position against plantation output volatility. Certification investment across OSHA, REACH, and China's GB standards preserves cross-border tender eligibility against emerging regional compounders. For New Entrants and Emerging Players: Begin with underpenetrated Indian mining corridors where domestic coal and bauxite expansion under CEA power-sector mandates creates import substitution opportunities. Target carbon-capture retrofit applications in cement and steel sectors requiring modified belt chemistries resistant to amine-based solvent exposure. Pursue digital-twin integration partnerships with industrial automation vendors to enable condition-based replacement contracting. For Investors and Strategic Acquirers: Industrial automation vendors are the most active acquirer in this space, seeking sensor-embedded belt capabilities to complete predictive maintenance platforms. Long-term viability hinges on compounders with demonstrated REACH requalification execution and thermoplastic recyclability investments. Watch for aramid-reinforcement specialists with retiring formulation chemist benches as consolidation catalysts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Sourcing | Plantation control insulates Continental AG and Bridgestone from Southeast Asian supply volatility. |
| REACH-Compliant Compound Requalification | Phthalate-free portfolios enable premium positioning in European steel and cement procurement. |
| Aramid Carcass Architecture Development | Fenner Dunlop extends service intervals in Australian Pilbara iron ore corridors. |
| Sensor-Embedded Belt Pilot Programs | Real-time tension monitoring compresses time-based replacement toward condition-triggered procurement. |
| Maintenance Outsourcing Contract Bundling | Third-party service providers capture installation and monitoring revenue in China's automated coal terminals. |
Methodological Framework
Direct dialogue with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads grounds qualitative assessment in operational realities. Secondary validation draws from customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and mining operator procurement disclosures. Bottom-up volume estimates triangulate against top-down market sizing across material type, end-use industry, and regional production hub dimensions.
Bottom-up modeling builds from segment-level volume and pricing assumptions; top-down verification cross-checks against macroeconomic indicators and industry association aggregates. Segmentation across material chemistry, reinforcement architecture, thickness profile, and surface finish drives analytical granularity. CAGRs derive from fitted growth curves incorporating mining capital expenditure cycles, port automation deployment timelines, and regulatory phase-in schedules.
Caveats apply where REACH enforcement intensity, natural rubber harvest variability, or mining project deferrals could materially shift the outlook. Forecasts reflect documented assumptions about replacement cycle timing and certification adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Wood Protein Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Industrial Round Wood Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Tension Spring Market
Industrial Materials
North America Machined Seals Market
Industrial Materials
Fiberglass Tanks Market