
 UHP Graphite Electrode Market | 2026-2036
UHP Graphite Electrode Market Size, Share, and Industry Trends Forecast 2026-2036
UHP Graphite Electrode Market Analytics
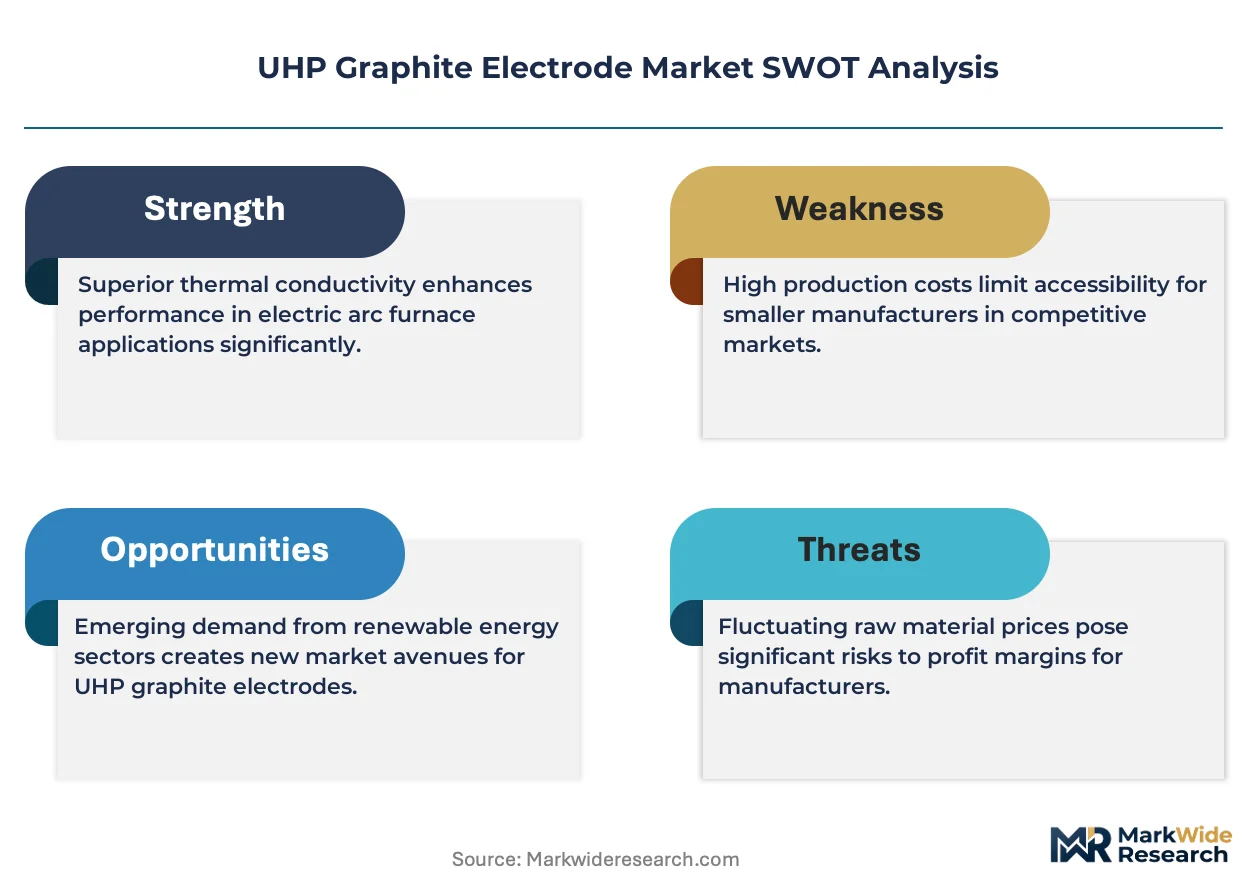
Multi-source procurement among EAF steel mills is expanding as buyers diversify beyond traditional Japanese and American suppliers to secure electrode supply chains. GrafTech International leverages its integrated needle coke-to-electrode production to sustain margin stability across volatile raw material cycles. Graphite India Limited anchors its competitive position through cost-optimized manufacturing scale at its Durgapur and Nashik facilities. Tokai Carbon Co., Ltd. differentiates via advanced thermal treatment technologies that extend electrode consumption rates in high-power furnace operations.
UHP graphite electrodes are manufactured from premium needle coke blended with coal tar pitch, then graphitized at temperatures exceeding 2,800°C to achieve electrical resistivity below 5.0 μΩ·m and flexural strength above 10 MPa for ultra-high-power electric arc furnace applications. Artificial graphite electrodes dominate volume consumption in arc furnace steelmaking, where thermal shock resistance and low oxidation rates justify premium pricing over natural graphite alternatives. Specialty-grade electrodes represent the fastest-expanding quality tier as custom alloy producers and silicon metal smelters adopt higher-specification consumables for extended campaign life. Steel production end-users command the largest demand share, though foundry applications are gaining traction in precision casting segments requiring consistent thermal profiles.
EPA emissions standards under the Clean Air Act constrain U.S. electrode manufacturing facility expansions, while China's MEE enforces dual carbon goals that limit graphite electrode plant energy intensity and carbon output per ton. The EU's CBAM and REACH frameworks are reshaping import competitiveness for Chinese and Indian electrode exporters serving European EAF operators. Stakeholders must monitor evolving carbon border adjustments and needle coke supply concentration to anticipate cost pass-through dynamics and sourcing strategy recalibration.
Market Dynamics
Needle coke supply concentration among petroleum refiners is forcing EAF steelmakers to restructure long-term electrode procurement contracts around raw material security rather than unit pricing alone.
Growth Catalysts
- EU CBAM implementation:Carbon border adjustments on imported steel are accelerating EAF capacity additions across Germany, Italy, and Poland, directly expanding electrode consumption in furnace operations rated above 100 MW.
- Scrap-based steel corridors:Turkey, India, and Vietnam are expanding electric arc furnace output faster than integrated blast furnace routes, creating concentrated demand nodes for UHP-grade consumables with low electrical resistivity specifications.
- Silicon metal smelting:Photovoltaic and semiconductor supply chains are adopting higher-power electrode specifications for extended campaign life in submerged arc furnaces producing metallurgical-grade silicon.
Market Restraints
- Needle coke supply oligopoly:Decant oil feedstock availability constrains premium needle coke output, with fewer than ten global refiners capable of producing battery-grade and electrode-grade coke simultaneously.
- Energy intensity caps:China's MEE enforces dual carbon goals that limit graphitization furnace operating hours and per-ton carbon output, constraining electrode production expansion regardless of demand signals.
- Petroleum coke price volatility:Needle coke costs fluctuate with fluid catalytic cracker yields and decant oil competition from lithium-ion battery anode manufacturers, compressing electrode producer margins unpredictably.
Strategic Opportunities
- Vietnam EAF buildout:Greenfield steel projects in Ba Ria-Vung Tau and Hai Phong are specifying UHP electrodes from project inception, creating first-mover positioning for suppliers establishing local technical service presence.
- Graphite recycling infrastructure:Spent electrode recovery and re-graphitization technologies are emerging as alternative feedstock streams, reducing dependence on virgin needle coke from petroleum refining.
- India PLI scheme extension:Steel ministry proposals for production-linked incentives on specialty steel grades are redirecting capital toward EAF-based stainless and alloy production, expanding addressable electrode demand beyond carbon steel.
Industry Challenges
- Graphitization furnace engineering:Constructing Acheson or LWG furnaces capable of 2,800°C sustained operation requires 18-24 month commissioning timelines and specialized refractory installation expertise that remains concentrated in Japan and China.
- ISO 9001 and IATF 16949 certification:Automotive steel qualification protocols demand exhaustive electrode batch traceability and thermal performance documentation, extending supplier approval cycles for Tier-1 mill integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UHP Graphite Electrode Market |
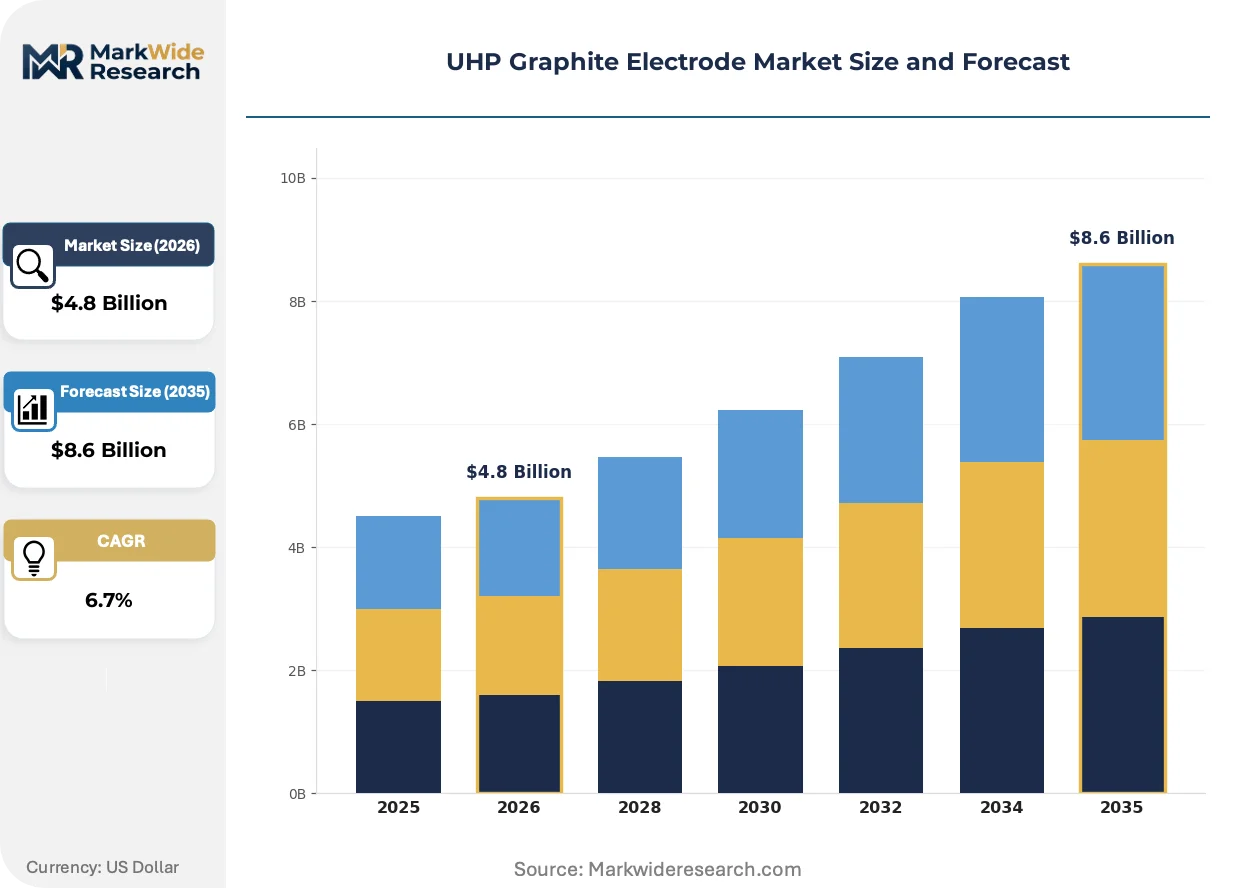
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isostatic Graphite, Artificial Graphite, Natural Graphite, Synthetic Graphite End User: Steel Production, Foundries, Aerospace, Automotive Application: Arc Furnaces, Electrode Manufacturing, Metallurgy, Chemical Processes Quality Grade: UHP, HP, RP, Specialty |
| Companies Covered | Tokai Carbon Co., Ltd., Graphite India Limited, GrafTech International, SGL Carbon SE, Resonac Holdings Corporation, HEG Limited, Showa Denko K.K., Nippon Carbon Co., Ltd., Fangda Carbon New Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UHP Graphite Electrode Market Evolving Landscape
Electrode manufacturing is converging with carbon materials science and furnace control automation, compressing the gap between commodity consumables and engineered thermal systems.
Impregnated graphite electrodes are integrating pitch-based densification treatments that reduce end-face oxidation rates by one-third in high-oxygen EAF environments. Specialty steel producers in South Korea and Japan are specifying these enhanced electrodes for campaigns exceeding 700 heats, compressing per-ton steelmaking costs despite 15-20% upfront price premiums. The technology is integrating with automated electrode joint detection systems that optimize consumption algorithms in real-time furnace control.
China's MIIT carbon intensity mandates are capping energy consumption per ton of electrode at 1,200 kWh for graphitization processes, forcing producers to retrofit LWG furnace insulation and recover waste heat for preheating green electrodes. Plants in Heilongjiang and Shandong provinces are responding by consolidating batch sizes and extending furnace cycles to meet intensity targets without capacity reduction. The regulatory pressure is accelerating adoption of continuous graphitization technologies previously confined to laboratory-scale production.
Steel mills are consolidating electrode purchasing through consortium arrangements that pool volume commitments across multiple furnace operators. Turkish EAF producers in Iskenderun and Izmir are forming procurement cooperatives to negotiate needle coke-linked pricing formulas directly with electrode manufacturers, displacing distributor intermediaries that previously managed inventory and technical service. This behavioral shift is most visible in Mediterranean basin steel corridors where freight optimization and shared technical audits reduce total procurement costs.
UHP Graphite Electrode Market Segmentation
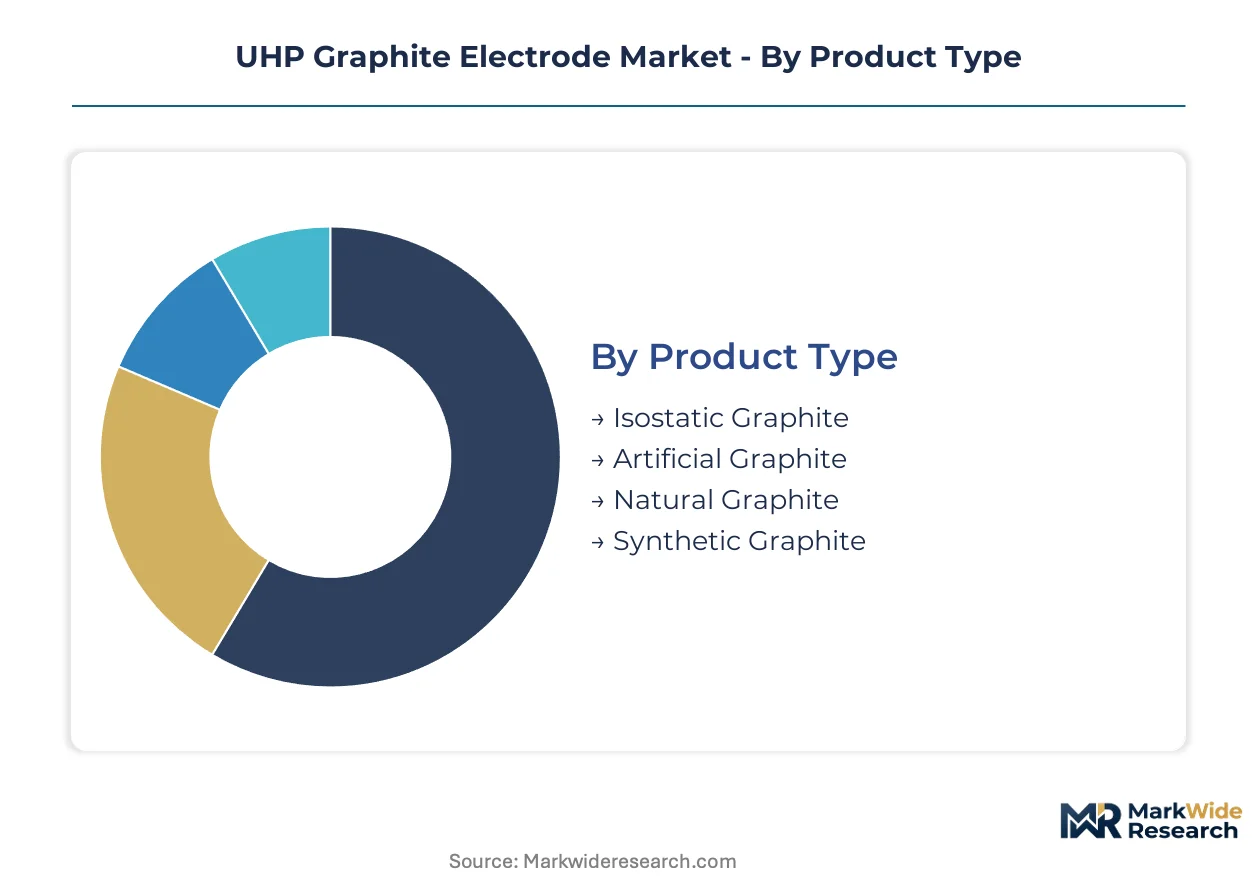
UHP graphite electrode segmentation separates volume-driven commodity tiers from precision-engineered premium grades. Steelmakers in Turkey and India source differently across these categories based on furnace power ratings and campaign duration requirements.
Product Type:
Artificial graphite commands volume leadership while isostatic grades capture premium positioning in high-power furnace operations.
- Isostatic Graphite:Manufactured through isostatic pressing to achieve uniform density and minimal anisotropy. South Korean silicon metal smelters specify these electrodes for submerged arc furnaces requiring consistent thermal conductivity across 800+ heat campaigns.
- Artificial Graphite:Produced from needle coke and coal tar pitch graphitized above 2,800°C, delivering electrical resistivity below 5.0 μΩ·m. Turkish EAF operators in Iskenderun consume these electrodes at scale for scrap-based steel production rated above 100 MW.
- Natural Graphite:Mined and processed without synthetic graphitization, offering cost advantages in lower-temperature metallurgical applications.
- Synthetic Graphite:Engineered from carbon precursors through controlled thermal treatment, bridging performance gaps between natural and artificial grades in specialty alloy production.
Today's leader: Artificial Graphite. Tomorrow's challenger: Isostatic Graphite.
End User:
Steel production absorbs the majority of electrode tonnage while foundry applications demand tighter dimensional tolerances.
- Steel Production:Electric arc furnace operators consume UHP electrodes as primary consumables in scrap-based steelmaking. Indian EAF capacity additions under the PLI scheme for specialty steel are redirecting procurement toward higher-grade electrodes with extended tip life.
- Foundries:Precision casting operations require electrodes with consistent thermal profiles for controlled solidification in superalloy components. German automotive foundries specify batch-traceable electrodes meeting IATF 16949 certification protocols.
- Aerospace:Titanium and superalloy melting in vacuum arc remelting furnaces drives demand for ultra-low impurity electrodes.
- Automotive:Tier-1 steel suppliers qualify electrodes through exhaustive thermal performance documentation for high-strength steel production.
Steel production anchors current volume. Foundry applications are climbing the fastest as precision casting expands.
Application:
Arc furnace operations dominate consumption while chemical process applications represent emerging demand nodes.
- Arc Furnaces:Ultra-high-power electric arc furnaces rated above 100 MW consume electrodes with flexural strength exceeding 10 MPa. Vietnamese greenfield steel projects in Hai Phong specify UHP electrodes from project inception, creating concentrated demand corridors.
- Electrode Manufacturing:Secondary processing and joint fabrication require intermediate graphite forms with machinability-optimized properties.
- Metallurgy:Silicon metal and ferroalloy production in submerged arc furnaces drives consumption of large-diameter electrodes with enhanced oxidation resistance.
- Chemical Processes:Chlor-alkali and other electrolytic applications utilize graphite electrodes for corrosion-resistant anode functions.
Arc furnaces maintain structural dominance. Chemical processes present the steepest expansion trajectory as electrolytic applications diversify.
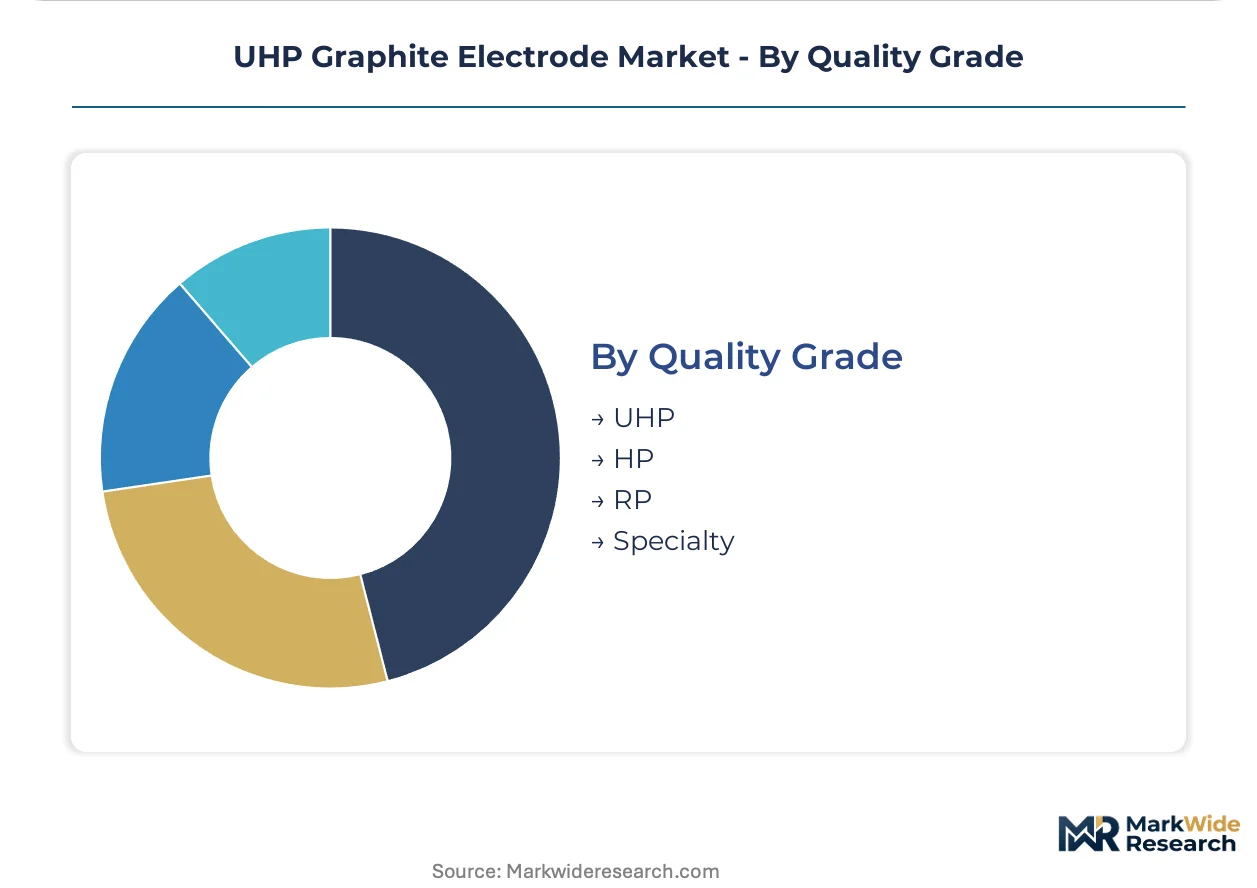
Quality Grade:
UHP grades command premium pricing while specialty tiers capture margin in custom alloy segments.
- UHP:Ultra-high-power electrodes manufactured from premium needle coke with electrical resistivity specifications below 5.0 μΩ·m. EU CBAM implementation is accelerating EAF capacity additions across Germany and Poland, directly expanding UHP electrode consumption in furnace operations requiring minimum 700-heat campaign life.
- HP:High-power electrodes serve intermediate furnace ratings with balanced performance-cost positioning for mid-scale steel producers.
- RP:Regular power electrodes address lower-power furnace applications and developing market price sensitivity.
- Specialty:Custom-engineered electrodes for silicon metal smelting and superalloy production feature enhanced thermal shock resistance and tailored oxidation profiles. Photovoltaic supply chain expansion is driving specification upgrades in metallurgical-grade silicon production.
UHP grades define current premium positioning. Specialty grades are gaining share fastest as custom alloy production expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iskenderun anchors the most concentrated demand corridor for UHP graphite electrodes, where Turkish EAF steelmakers cluster procurement cooperatives to negotiate needle coke-linked pricing directly with manufacturers.
Turkey
EAF operators in Iskenderun and Izmir consume UHP electrodes at scale for scrap-based steel rated above 100 MW. The country's steel ministry monitors carbon intensity benchmarks for metallurgical operations. Greenfield capacity in Mediterranean coastal zones specifies premium-grade consumables from project inception.
India
Specialty steel producers under the PLI scheme redirect capital toward EAF-based stainless and alloy production. The Steel Ministry's production-linked incentive proposals expand addressable electrode demand beyond carbon steel. Durgapur and Nashik facilities anchor cost-optimized manufacturing scale for domestic procurement.
China
Heilongjiang and Shandong province producers retrofit LWG furnace insulation to meet MIIT carbon intensity caps at 1,200 kWh per ton for graphitization. The Ministry of Ecology and Environment enforces dual carbon goals limiting furnace operating hours. Plants consolidate batch sizes and extend cycles to meet intensity targets without capacity reduction.
Vietnam
Greenfield steel projects in Ba Ria-Vung Tau and Hai Phong specify UHP electrodes from project inception for ultra-high-power furnace operations. The Ministry of Industry and Trade oversees metallurgical investment approvals. Northern coastal industrial zones attract first-mover suppliers establishing local technical service presence.
Germany
EAF capacity additions accelerate across Germany under EU CBAM implementation, directly expanding electrode consumption in furnace operations requiring minimum 700-heat campaign life. The European Commission's carbon border adjustment mechanism reshapes import competitiveness for electrode suppliers. Ruhr Valley steel corridors concentrate demand for premium-grade consumables with extended tip life specifications.
UHP Graphite Electrode Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty-grade positioning and recycling infrastructure. The supplier base consolidates around integrated needle coke-to-electrode manufacturers and independent electrode fabricators. Three archetypes dominate: integrated petroleum coke refiners with captive electrode operations, standalone electrode manufacturers sourcing third-party needle coke, and emerging recyclers developing spent electrode recovery technologies. Capacity expansion and backward integration into needle coke supply represent the dominant competitive moves across all tiers.
Within the integrated-manufacturer tier, GrafTech International exemplifies upstream control over raw material cycles, while Graphite India Limited anchors cost-optimized scale positioning. Tokai Carbon Co., Ltd. occupies the advanced-technology archetype through thermal treatment specialization. These three companies represent distinct strategic postures: captive supply security, manufacturing scale efficiency, and premium performance engineering.
| Leading Market Players |
|---|
| Tokai Carbon Co., Ltd. |
| Graphite India Limited |
| GrafTech International |
| SGL Carbon SE |
| Resonac Holdings Corporation |
| HEG Limited |
| Showa Denko K.K. |
| Nippon Carbon Co., Ltd. |
| Fangda Carbon New Material |
| Others |
Value Network & Pricing Analysis
Decant oil feedstock pricing cascades through needle coke spot markets into electrode manufacturing cost structures, compressing margins at non-integrated producers while amplifying pricing power for refiners with captive electrode operations. Turkish EAF procurement cooperatives in Iskenderun negotiate needle coke-linked formulas that transfer raw material volatility risk back to manufacturers.
Pricing Analysis
Input-cost pass-through dominates contract structures, with needle coke price movements indexed to petroleum refinery decant oil yields. Three-tier pricing structure across premium UHP, standard HP, and economy RP levels separates furnace campaign life specifications. Cost compression in mid-tier HP electrodes is intensifying because battery anode manufacturers compete for the same decant oil feedstock. Carbon steel producers exhibit highest price sensitivity, while silicon metal smelters accept premiums for extended heat campaigns.
Supply Chain Analysis
Dual-sourcing requirements now mandate Turkish and Indian EAF operators qualify at least two needle coke suppliers per contract, displacing single-source dependencies. Manufacturing concentrates in China, Japan, and the United States, with graphitization furnace engineering expertise tethered to Heilongjiang and Shandong provinces. Supply chain risk centers on single-source vulnerability for premium needle coke from petroleum refiners. Distribution runs through technical service partnerships rather than distributor intermediaries in Mediterranean and Southeast Asian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UHP graphite electrode market functions as a regulatory compounder where EU CBAM implementation accelerates EAF capacity additions and electrode consumption across German and Polish steel corridors.
For Market Incumbents: Extend captive needle coke supply through refinery partnerships or acquisition of decant oil processing assets to defend against margin compression from battery anode feedstock competition. Add graphitization capacity in Vietnam's Ba Ria-Vung Tau zone to capture greenfield EAF demand before local competitors establish technical service presence. For New Entrants and Emerging Players: Launch via spent electrode recycling and re-graphitization technology to bypass virgin needle coke supply constraints. Target India's PLI-supported specialty steel segment with certified UHP electrodes for stainless and alloy production, leveraging cost-optimized manufacturing partnerships with existing Durgapur or Nashik facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where needle coke supply oligopoly meets carbon intensity caps limiting production expansion regardless of demand signals. Long-term viability favors integrated producers with upstream petroleum coke control and downstream technical service networks. Watch MIIT enforcement intensity in Heilongjiang as inflection indicator for Chinese supply availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke | Captive decant oil supply insulates electrode margins from battery anode competition. |
| Graphite Recycling Infrastructure Buildout | Spent electrode recovery reduces dependence on petroleum refinery feedstock availability. |
| Vietnam Technical Service Expansion | Local presence captures greenfield EAF demand in Hai Phong and Ba Ria-Vung Tau. |
| Continuous Graphitization Technology Adoption | MIIT carbon intensity compliance enables capacity expansion under energy consumption caps. |
| Procurement Cooperative Partnership | Turkish EAF consortium arrangements displace distributor intermediaries for direct manufacturer relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with EAF procurement managers, electrode plant operations directors, needle coke refinery supply planners, and metallurgical engineers with secondary validation. Trade data from customs authorities, MIIT production statistics, SEC filings from listed electrode manufacturers, and EU CBAM implementation documents anchored supply-side assessment. Bottom-up furnace capacity modeling and top-down steel production forecasts were triangulated against consumption intensity benchmarks.
Comparable-period anchoring linked projection assumptions to historical EAF steel output trends and electrode consumption rates across the analysis window. Segmentation dimensions modeled include quality grade tier, end-use application, furnace power rating, and regional regulatory cluster. CAGRs were derived from intensity-based consumption modeling tied to scrap-based steel capacity expansion. Forecast inputs incorporated needle coke supply elasticity and carbon border adjustment implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt needle coke supply disruption or accelerated battery anode demand growth. Deviation in MIIT enforcement intensity or EU CBAM expansion scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Wood Protein Market
Industrial Materials
Polycarbonate Panels Market
Industrial Materials
Crimped Wire Brushes Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Felt Gasket Market
Industrial Materials
Shrink Tanks Market
Industrial Materials
Global Jet Mill Market