
 Industrial Furnaces Market | 2026-2036
Industrial Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Furnaces Market Intelligence
The industrial furnaces sector is pivoting sharply between premium thermal processing systems and commodity batch equipment, with the former commanding extended lifecycles and precision control while the latter competes on throughput metrics alone. Andritz AG leverages its Austrian engineering heritage to dominate large-scale continuous furnace installations for metals processing. SECO/WARWICK anchors its position through specialized vacuum heat treatment lines serving aerospace certification requirements. Ipsen International GmbH differentiates via controlled atmosphere technology leadership across European automotive supplier networks.
An industrial furnace is a thermally insulated chamber designed to generate and sustain controlled temperatures exceeding 1,000°C for material transformation, utilizing refractory linings, burner systems, and atmosphere control mechanisms to achieve specific metallurgical, ceramic, or chemical outcomes. Electric furnaces are capturing margin pools as carbon pricing mechanisms reshape fuel economics across manufacturing bases, while induction furnaces sustain rapid growth in foundry modernization programs due to melting efficiency advantages. Gas furnaces occupy mature demand channels in glass manufacturing where flame chemistry control remains technically essential, though oil furnaces face structural displacement outside remote or grid-constrained installations.
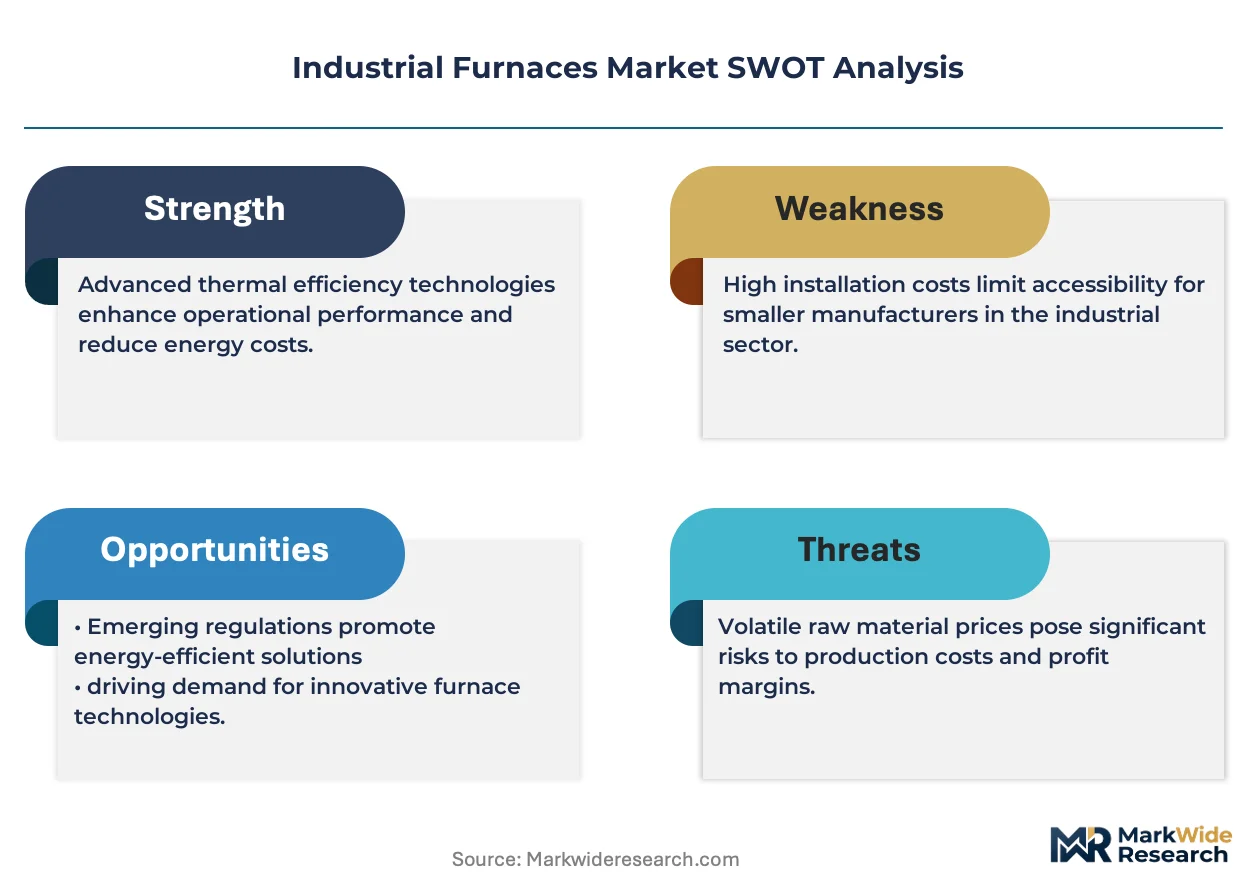
EPA emissions standards under the Clean Air Act constrain combustion furnace deployments across US metalworking facilities, while EU F-Gas Regulation phases down fluorinated greenhouse gases used in certain thermal insulation and cooling systems tied to furnace operations. China's MEE enforces increasingly stringent industrial emissions thresholds that redirect procurement toward electric and induction alternatives. Stakeholders must monitor regulatory divergence between carbon-intensive and electrified thermal processing pathways as compliance costs reshape equipment replacement cycles.
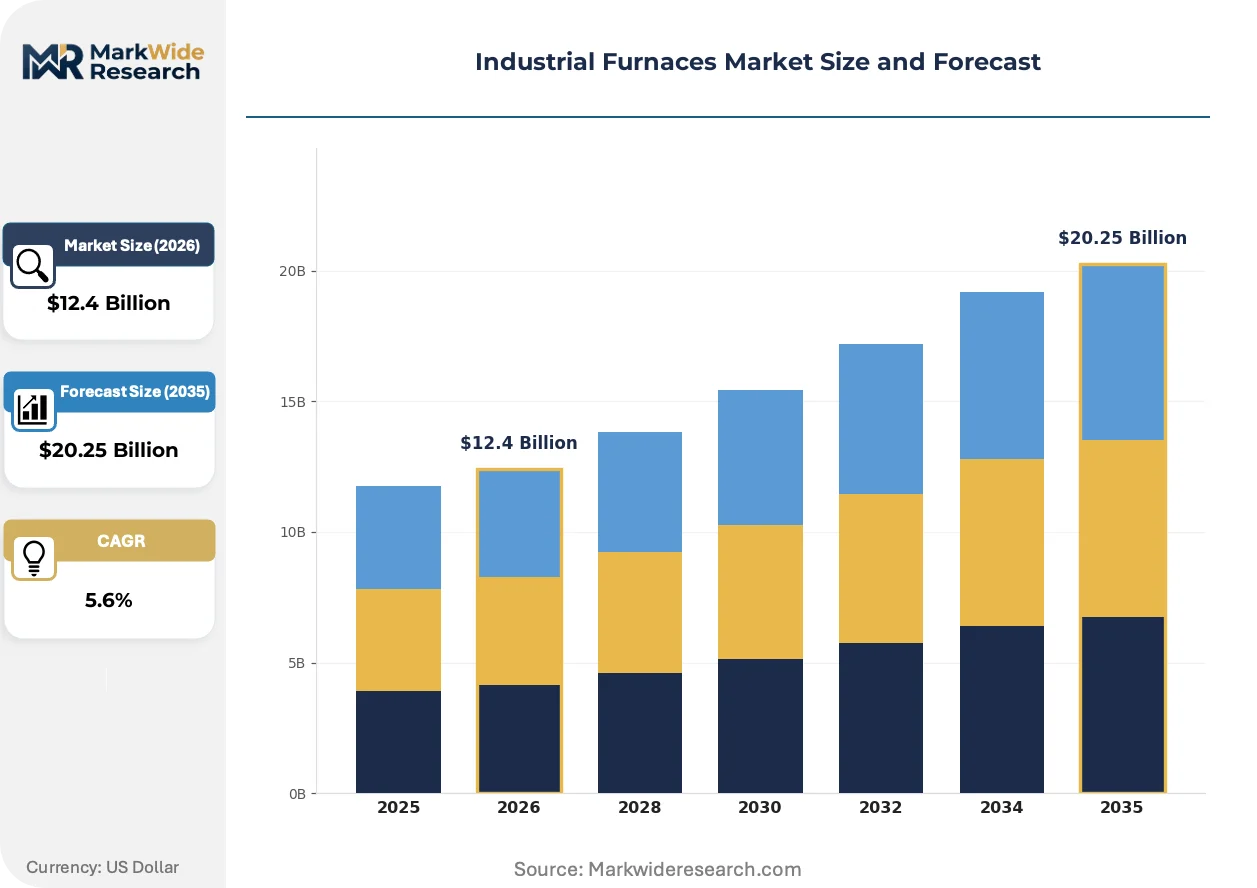
Market Dynamics
Carbon pricing mechanisms and electrification mandates are compressing fuel economics for thermal processing equipment, redirecting capital toward electric and induction furnace architectures while stranding gas-fired assets in emissions-intensive manufacturing corridors.
Growth Catalysts
- Aerospace Certification Requirements:Heat treatment specifications for turbine components and airframe alloys are expanding vacuum furnace deployments across European and North American supplier networks.
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating replacement cycles for thermal insulation systems in existing furnace installations.
- China's Dual Carbon Goals:National emissions intensity targets are channeling foundry investment toward induction melting technologies with superior energy conversion efficiency.
Market Restraints
- Refractory Supply Concentration:High-purity alumina and magnesia sourcing clusters in limited geographies expose furnace builders to input cost volatility and supply disruption.
- Grid Infrastructure Lag:Electrification of large-scale thermal processing confronts transmission capacity constraints in industrial zones lacking substation upgrades.
- EPA New Source Review:Combustion furnace permitting timelines extend project completion horizons, compressing returns on capital-intensive installations.
Strategic Opportunities
- India PLI Scheme for Specialty Steel:Production-linked incentives for high-grade alloy manufacturing are stimulating vacuum heat treatment capacity additions.
- Digital Twin Convergence:Integration of physics-based furnace modeling with IoT sensor networks enables predictive maintenance and energy optimization services.
- Hydrogen-Ready Burner Retrofit:Dual-fuel combustion systems position existing gas furnace infrastructure for future hydrogen fuel switching.
Industry Challenges
- Control Systems Integration:Legacy PLC architectures resist seamless interfacing with modern SCADA and MES platforms, complicating smart manufacturing transitions.
- Certification Timeline Compression:Aerospace NADCAP accreditation cycles for new heat treatment lines extend 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Furnaces Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Furnaces, Gas Furnaces, Oil Furnaces, Induction Furnaces End User: Metalworking, Glass Manufacturing, Ceramics, Aerospace Installation: Onshore, Offshore, Permanent, Portable Capacity: Small, Medium, Large, Custom |
| Companies Covered | Andritz AG, Carbolite Gero Limited, Ipsen International GmbH, Inductotherm Group, SECO/WARWICK, Gasbarre Products Inc, Epcon Industrial Systems LP, International Thermal Systems, NUTEC Bickley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Furnaces Market Strategic Shifts & Innovations
Active sensor networks and machine learning algorithms are penetrating furnace control architectures, converting thermal processing from empirical craft to data-optimized production with measurable yield and energy consequences.
Advanced atmosphere monitoring is integrating laser-based gas analysis and real-time carbon potential calculation into continuous furnace operations. Automotive tier-one suppliers in Germany and Japan are deploying these systems to eliminate batch-to-batch variation in gear hardening processes. The technology is integrating quality assurance directly into the thermal cycle, compressing post-process inspection requirements and reducing scrap rates.
REACH authorization procedures for hexavalent chromium compounds are restricting traditional protective atmosphere chemistries in European heat treatment operations. Furnace operators are reformulating process gases and accelerating adoption of vacuum alternatives to maintain surface treatment capabilities. Aerospace component manufacturers face the most acute compliance pressure, with several German and French facilities completing atmosphere system conversions ahead of regulatory deadlines.
Equipment-as-a-service contracting is displacing traditional capital purchase models for mid-scale heat treatment operations. Tier-two automotive and general engineering buyers in the US Midwest and Northern Italy are adopting performance-based agreements that bundle furnace availability, energy consumption, and maintenance into unit-cost metrics. This restructuring transfers operational risk to OEMs while aligning vendor incentives with uptime and efficiency outcomes.
Industrial Furnaces Market Segmentation
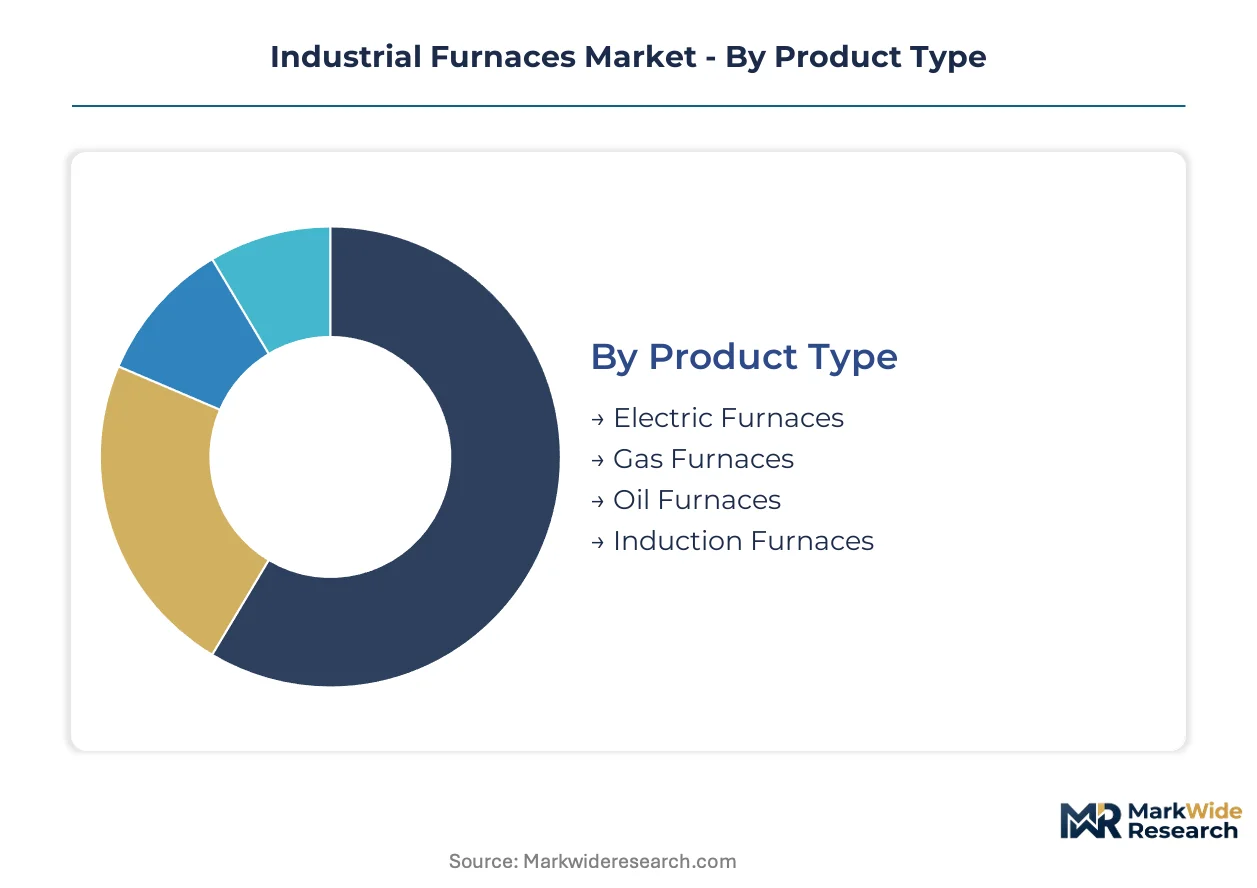
Thermal processing requirements diverge sharply across metallurgical, ceramic, and chemical applications, forcing furnace architectures to specialize around fuel type, atmosphere control, and thermal uniformity specifications. Segmentation reveals where capital is concentrating versus where legacy equipment faces replacement pressure.
Product Type:
Supply concentration for combustion system components clusters around German burner engineering and Japanese control electronics, concentrating procurement leverage among integrated furnace builders with captive component sourcing.
- Electric Furnaces:Resistance and arc heating architectures deliver precise temperature uniformity through refractory-lined chambers with embedded heating elements. Carbon pricing mechanisms in Germany and California are redirecting foundry investment toward electric alternatives as grid decarbonization accelerates.
- Induction Furnaces:Electromagnetic field generation enables contactless melting with energy conversion efficiencies exceeding conventional combustion systems. China's MEE emissions enforcement is channeling steel foundry modernization toward induction technology across Hebei and Jiangsu provinces.
- Gas Furnaces:Direct-fired radiant tube and regenerative burner systems dominate glass tank operations where flame chemistry control determines product optical quality.
- Oil Furnaces:Heavy fuel oil and diesel combustion systems persist in remote mining installations and grid-constrained industrial zones lacking pipeline gas access.
Gas furnaces absorb the bulk of installed capacity; induction furnaces are expanding most quickly.
End User:
Application-specific thermal cycles dictate furnace specification, with aerospace certification requirements imposing the most stringent atmosphere and temperature uniformity standards.
- Metalworking:Heat treatment lines for ferrous and non-ferrous alloys require controlled atmosphere or vacuum capability to achieve specified mechanical properties. Automotive transmission component manufacturing in Stuttgart and Detroit concentrates demand for continuous belt furnace installations.
- Aerospace:Vacuum heat treatment specifications for nickel-based superalloys and titanium airframe components mandate NADCAP-accredited processing capability. Turbine blade manufacturers in France and the UK are expanding vacuum furnace capacity to meet OEM qualification requirements.
- Glass Manufacturing:Float glass and container production relies on regenerative furnace technology with heat recovery systems optimizing fuel consumption.
- Ceramics:Kiln firing for technical ceramics and refractory products employs periodic and tunnel furnace configurations with programmable thermal profiles.
Metalworking commands the largest equipment installed base; aerospace represents the steepest expansion trajectory.
Installation:
Project logistics and operational mobility requirements split procurement between fixed industrial infrastructure and relocatable thermal processing assets.
- Permanent:Foundation-mounted furnace systems with integrated material handling and atmosphere infrastructure serve high-volume continuous production. Germany's industrial manufacturing corridor concentrates permanent installation demand for metals processing.
- Portable:Modular furnace units with containerized or skid-mounted configurations enable field heat treatment for pipeline construction and infrastructure repair. Oil and gas maintenance contractors in Texas and Alberta deploy portable systems for weld stress relief operations.
- Onshore:Land-based installations dominate manufacturing facility deployments with established utility connections and emissions permitting pathways.
- Offshore:Platform-adapted furnace systems with compact footprints and marine-grade corrosion protection serve subsea equipment manufacturing and repair.
Permanent installations anchor capital expenditure; portable configurations are gaining share fastest in energy sector maintenance.
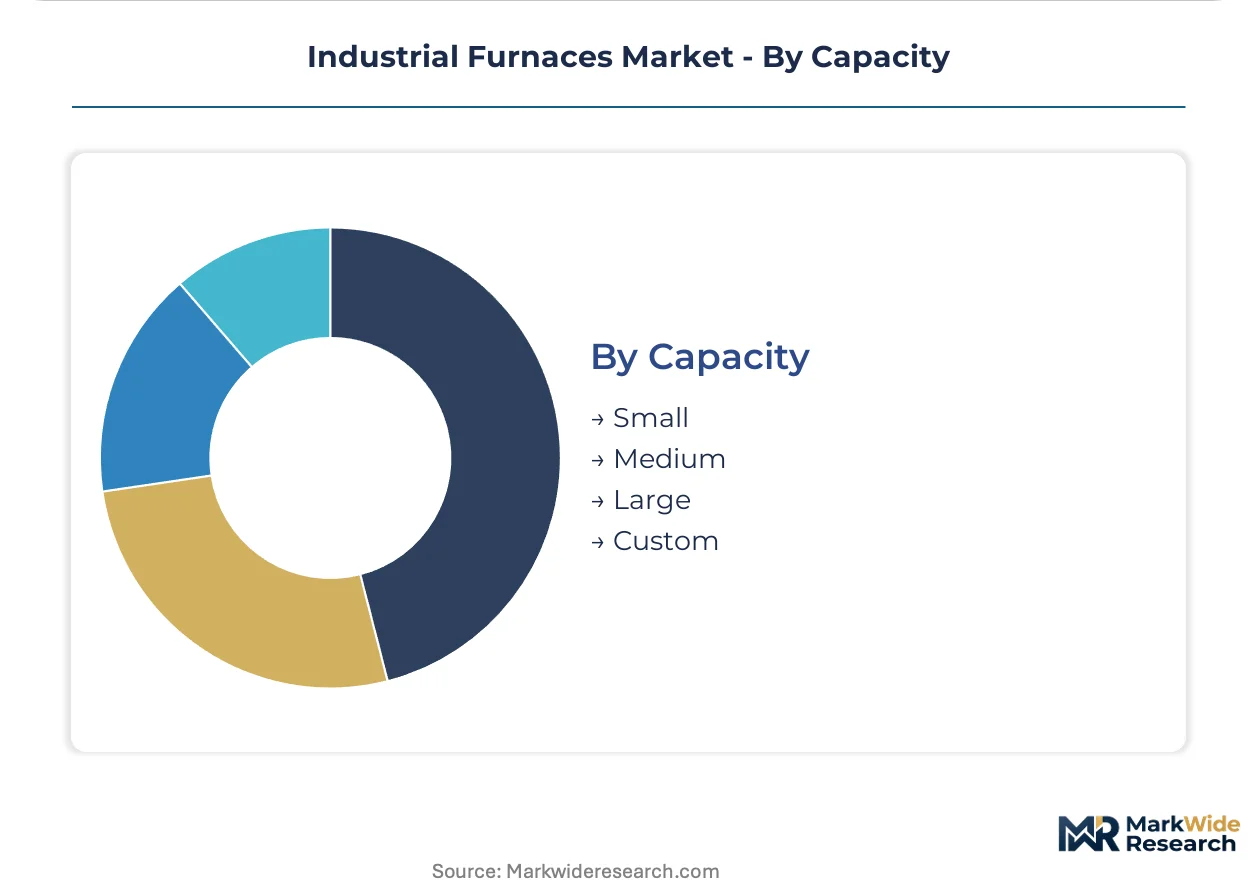
Capacity:
Scale economics and batch flexibility tradeoffs shape procurement decisions across volume production and specialty processing segments.
- Large:Continuous pusher and roller hearth furnaces with tonnage-per-hour throughput serve automotive and appliance component mass production. Steel heat treatment facilities in Indiana and Ohio operate large-capacity lines for tier-one supplier networks.
- Custom:Engineered-to-order furnace systems accommodate non-standard work envelopes, atmosphere chemistries, or thermal profiles for research and specialty manufacturing. Aerospace material development laboratories in California and Massachusetts commission custom vacuum furnaces for alloy qualification.
- Medium:Batch and semi-continuous configurations balance throughput with product mix flexibility for general engineering applications.
- Small:Laboratory and pilot-scale furnaces support process development, quality control, and low-volume specialty production.
Large capacity systems dominate revenue concentration; custom configurations command the highest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors thermal processing demand through its dense automotive supplier ecosystem, where continuous belt furnaces harden transmission components for Mercedes-Benz and Porsche production networks.
United States
EPA New Source Review timelines constrain combustion furnace permitting across Indiana and Ohio steel heat treatment corridors. The Clean Air Act enforcement redirects capital toward electric alternatives in Detroit's automotive component manufacturing belt. Foundry modernization programs in Wisconsin and Pennsylvania prioritize induction melting to circumvent emissions compliance delays.
Germany
Carbon pricing under the EU ETS compresses fuel economics for gas-fired assets across Bavaria's industrial manufacturing corridor. The EU F-Gas Regulation accelerates replacement cycles for thermal insulation systems in Baden-Württemberg heat treatment facilities. Aerospace vacuum furnace capacity expands in Hamburg and Munich to serve turbine blade qualification requirements.
China
MEE emissions intensity targets channel Hebei province steel foundry investment toward induction melting technologies with superior energy conversion. Dual carbon goals redirect procurement away from coal-fired reverberatory furnaces in Jiangsu province ceramic manufacturing clusters. Yangtze River Delta technical ceramics producers adopt electric kiln firing to meet provincial decarbonization mandates.
India
PLI scheme incentives for specialty steel stimulate vacuum heat treatment capacity additions across Maharashtra and Gujarat industrial zones. BIS certification requirements for automotive-grade alloys concentrate furnace procurement in Pune and Chennai supplier parks. Induction furnace adoption accelerates in Haryana and Tamil Nadu as grid infrastructure expands to serve foundry electrification.
Japan
METI energy efficiency standards drive regenerative burner retrofits in Osaka-Kobe glass manufacturing corridors. JIS certification requirements for aerospace alloys sustain vacuum furnace demand across Nagoya's turbine component supplier network. Automotive tier-one heat treatment lines in Toyota City deploy advanced atmosphere monitoring to eliminate batch-to-batch variation in gear hardening.
Industrial Furnaces Market Key Industry Players
Capital-heavy furnace builders compete with asset-light engineering specialists across procurement channels, with integrated manufacturers controlling captive component supply while niche consultants capture retrofit and optimization contracts. The vendor base organizes around three strategic archetypes: Austrian-German engineering conglomerates with metals processing heritage, Polish-American vacuum specialists serving aerospace certification chains, and Japanese precision control technology providers. Consolidation pressure concentrates among mid-scale batch furnace fabricators facing margin compression from electrification mandates. Dominant competitive moves include hydrogen-ready burner retrofit partnerships and digital twin service bundling.
Among Austrian engineering conglomerates, Andritz AG exemplifies the integrated metals processing archetype through its captive burner engineering and refractory sourcing capabilities. Ipsen International GmbH anchors the controlled atmosphere technology tier, occupying a position calibrated to European automotive supplier network requirements. SECO/WARWICK represents the vacuum heat treatment specialist archetype, with its geographic origin in Poland and US market presence supporting aerospace NADCAP accreditation service delivery.
| Leading Market Players |
|---|
| Andritz AG |
| Carbolite Gero Limited |
| Ipsen International GmbH |
| Inductotherm Group |
| SECO/WARWICK |
| Gasbarre Products Inc |
| Epcon Industrial Systems LP |
| International Thermal Systems |
| NUTEC Bickley |
| Others |
Cost & Logistics Intelligence
NADCAP-certified vacuum furnace systems command 40-60% price premiums over standard batch equipment, with that certification ladder simultaneously concentrating procurement leverage among Austrian-German engineering conglomerates and Polish-American vacuum specialists who control captive burner engineering and aerospace accreditation service delivery. Carbon pricing mechanisms under the EU ETS and California cap-and-trade programs are compressing fuel economics for gas-fired assets, redirecting buyer procurement toward electric alternatives while stranding combustion furnace margins in emissions-intensive manufacturing corridors.
Pricing Analysis
Throughput-guaranteed contracting anchors value-based pricing for mid-scale heat treatment operations, with performance-based agreements bundling furnace availability, energy consumption, and maintenance into unit-cost metrics. Price differentiation separates NADCAP-accredited vacuum systems from commodity batch equipment, with certification grade and after-sales service bundling driving tier stratification. Cost compression in standard batch furnace segments is intensifying because electrification mandates are collapsing residual value for gas-fired assets. Tier-two automotive and general engineering buyers in the US Midwest exhibit the highest price sensitivity, while aerospace component manufacturers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Refurbishment flows for refractory linings and burner system components create secondary material loops that extend furnace lifecycle economics and reduce virgin input dependency. High-purity alumina and magnesia sourcing clusters in China, Brazil, and Australia expose furnace builders to commodity price volatility and geopolitical disruption risk. Control electronics dependencies draw from Japanese precision component manufacturers, while German burner engineering supplies anchor combustion system architectures. Single-source vulnerability concentrates in high-purity refractory grades essential for aerospace heat treatment specifications. Distribution runs through integrated OEM direct sales for large-scale installations and specialized industrial equipment distributors for mid-scale batch configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial furnaces sector operates as a cost-of-compliance story where EPA New Source Review timelines and EU F-Gas Regulation phase-down mandates erect barrier-to-entry moats for players with established emissions permitting pathways and atmosphere system certification expertise.
For Market Incumbents: Deepen captive supply control over high-purity refractory sourcing and hydrogen-ready burner engineering to defend margin position against emerging electric furnace specialists. Consolidate vacuum heat treatment accreditation service capabilities in Hamburg and Munich to capture aerospace turbine blade qualification demand. Prioritize digital twin service bundling to lock in aftermarket revenue streams and displace asset-light retrofit competitors.
For New Entrants and Emerging Players: Induction melting technology deployment in Hebei and Jiangsu provinces offers the most penetrable entry corridor given China's MEE emissions enforcement and grid infrastructure expansion. Target portable furnace configurations for Texas and Alberta oil and gas maintenance contractors where field heat treatment demand outstocks established vendor coverage. Pursue equipment-as-a-service contracting models to transfer operational risk and align revenue with customer uptime outcomes.
For Investors and Strategic Acquirers: Re-rating potential sits with vacuum heat treatment specialists possessing NADCAP accreditation infrastructure given aerospace certification timeline compression and turbine component demand expansion. Long-term viability favors players with hydrogen-ready burner retrofit capabilities and digital twin integration expertise. Monitor EPA permitting backlog clearance rates and EU carbon price trajectories as inflection indicators for combustion furnace asset stranding velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Retrofit | Positions existing gas furnace infrastructure for future fuel switching under EU ETS carbon pricing. |
| Digital Twin Service Bundling | Enables predictive maintenance contracts with Stuttgart automotive transmission component manufacturers. |
| Backward Integration into Refractory Supply | Secures high-purity alumina sourcing against Brazilian and Australian supply disruption risks. |
| NADCAP Accreditation Infrastructure Expansion | Captures aerospace turbine blade qualification demand in Hamburg and Munich manufacturing clusters. |
| Equipment-as-a-Service Contracting | Aligns vendor incentives with uptime outcomes for US Midwest tier-two automotive buyers. |
Research Approach
Document review covered SEC filings from furnace builders and component suppliers, trade customs data for refractory material flows, and EPA enforcement action databases, complemented by interviews with plant engineers at automotive heat treatment facilities, procurement leads at aerospace tier-one suppliers, aftermarket service heads at European OEMs, and technical directors at induction melting foundries. Secondary validation drew from EIA industrial energy consumption surveys, EU ETS emissions registry data, and China MEE enforcement bulletins. Bottom-up equipment shipment analysis triangulated against top-down manufacturing value-added estimates across the analysis window.
Installed base and revenue projections reflect segment-level modeling across fuel type, atmosphere control technology, and end-use application dimensions, with capacity utilization assumptions calibrated to regional industrial production indices. CAGRs were derived from equipment replacement cycle analysis and regulatory-driven upgrade demand elasticity. Forecast inputs incorporated carbon price trajectory scenarios under EU ETS market stability reserve mechanisms and China dual carbon goal implementation timelines.
Several conditions sit outside the modeled scope, including unannounced breakthroughs in solid-state heating technologies and abrupt shifts in aerospace OEM qualification requirements. Forecasts reflect assumptions about grid infrastructure expansion pacing and refractory supply chain stability that may require revision. Practitioners should monitor EPA New Source Review policy adjustments and EU F-Gas Regulation phase-down acceleration announcements for early signals of regulatory timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Polycarbonate Sheets Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
United States Ceramic Roller Bearings Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
High Modulus Polyethylene Rope Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
High Purity Quartz Market