
 Wire Drawing Dies Market | 2026-2036
Wire Drawing Dies Market Size, Share, and Industry Trends Forecast 2026-2036
Wire Drawing Dies Market Insights
Die reconditioning and refurbishment services is shifting from a cost-saving sideline to a core revenue stream for major suppliers. Esteves Group leverages its European service network to capture recurring maintenance contracts across cable producers. Element Six anchors its position through captive synthetic diamond production, insulating margin pools from raw material volatility. Woodburn Diamond Die specializes in precision conical geometries for fine-wire applications, occupying a defensible niche above commodity carbide tiers.
A wire drawing die is a hardened tooling insert with an internal bore profile—typically conical entry, bearing, and back-relief zones—that reduces cross-sectional area of metal wire through plastic deformation under tensile pull. Carbide dies tolerate high-volume ferrous drawing, while synthetic polycrystalline diamond variants handle non-ferrous fine wires below 0.1 mm where surface finish and die life determine throughput economics. Diamond material commands premium positioning in electrical wire and copper alloy segments where micron-level tolerance prevents conductor scrap. Carbide dominates automotive cable volumes where cost-per-ton drawn outweighs absolute precision requirements.
EPA metalworking effluent guidelines and OSHA silica exposure limits shape domestic manufacturing compliance costs for die producers serving North American wire mills. REACH substance restrictions and EU Green Deal embodied-carbon tracking pressure European suppliers toward synthetic diamond and recycled carbide feedstocks. China's GB standards for wire rod quality and MEE environmental enforcement tighten die performance benchmarks for export-oriented cable manufacturers. Stakeholders must monitor how regulatory divergence between jurisdictions fragments certification requirements and reshapes sourcing geography for precision die supply.
Market Dynamics
Die reconditioning economics are compressing replacement cycles as wire mills prioritize capital preservation over new tooling procurement. This shift toward service-based revenue models is redrawing competitive boundaries between captive maintenance networks and independent refurbishment specialists.
Growth Catalysts
- EPA metalworking effluent guidelines:Tightening discharge standards are accelerating die replacement frequency among US wire producers seeking compliance through precision tooling upgrades.
- Grid modernization:State-backed transmission expansion in China is pulling diamond-coated die consumption through cable manufacturing capacity additions.
- Synthetic polycrystalline diamond:Advances in PCD synthesis are extending die life in fine copper wire applications below 0.1 mm, reducing per-meter tooling cost.
Market Restraints
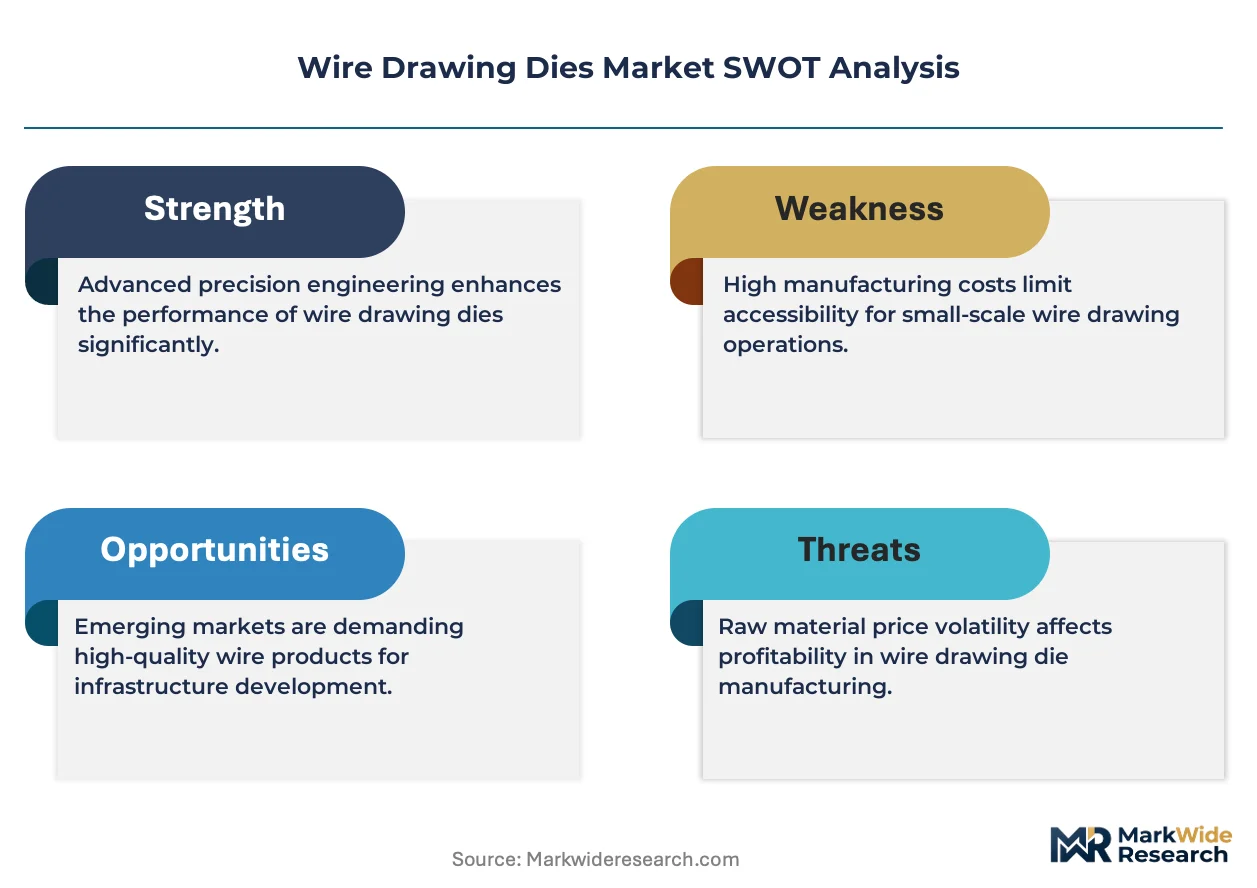
- Tungsten carbide price volatility:Raw material cost swings constrain margin stability for commodity die producers serving automotive cable volumes.
- Supply concentration in synthetic diamond:Captive production by a limited set of advanced materials specialists creates procurement bottlenecks for precision die manufacturers.
- REACH substance restrictions:European chemical compliance is eliminating certain cobalt binder chemistries from carbide die formulations, forcing reformulation costs.
Strategic Opportunities
- India cable manufacturing:PLI scheme incentives for domestic wire and cable production are creating first-mover advantage for die suppliers establishing local service presence.
- Condition-based monitoring:Integration of bore-wear sensors with die reconditioning workflows enables predictive maintenance contracts at wire mills.
- EU Green Deal embodied-carbon tracking:Recycled carbide feedstock certification is opening premium positioning for suppliers with verified circular material flows.
Industry Challenges
- Precision grinding skill scarcity:Conical geometry expertise for sub-0.05 mm wire applications concentrates among retiring European toolmakers, constraining quality replication.
- Dual certification timelines:Simultaneous REACH and EPA compliance documentation extends new product introduction cycles by months.
- Legacy die inventory integration:Wire mills with mixed carbide and diamond die fleets face workflow fragmentation during gradual technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wire Drawing Dies Market |
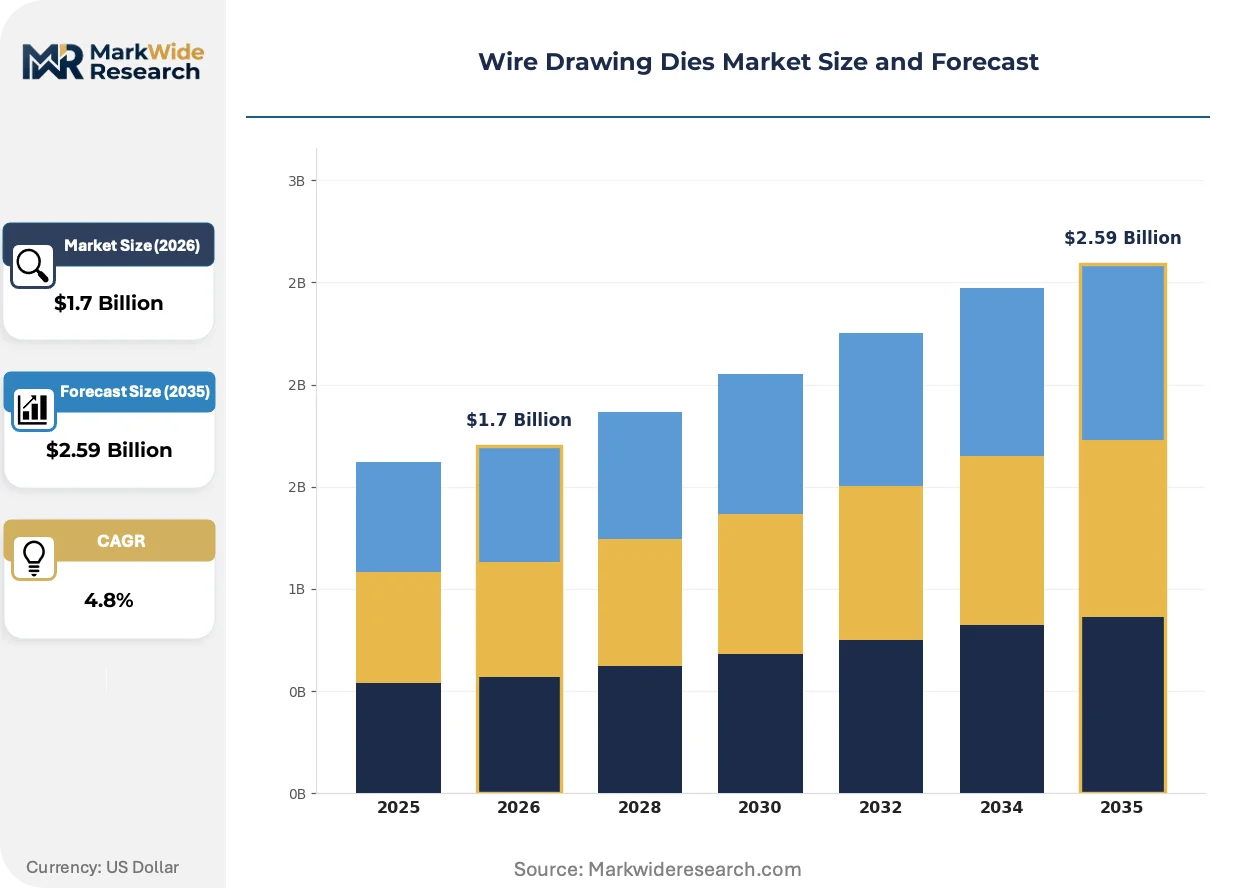
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Die Type: Conical, Reducing, Block, Multi-Point Material: Carbide, Steel, Diamond, Ceramics Application: Electrical Wires, Automotive Cables, Industrial Wires, Copper Alloys End User: Manufacturers, OEMs, Service Providers, Construction |
| Companies Covered | Woodburn Diamond Die, UKO, Esteves Group, Zhengzhou IW Diamond, REDIES, Element Six, SND, Morgan Advanced Materials, Sancliff Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wire Drawing Dies Market Trends and Innovations
Automation of die inspection and reconditioning workflows is compressing turnaround times from weeks to days. This operational acceleration is reshaping buyer expectations for tooling service responsiveness.
Laser bore measurement systems are automating micron-level tolerance verification across bearing and back-relief zones. Tier-one cable producers in Germany and Japan are deploying these systems inline with drawing machines. The technology is automating quality assurance labor while reducing conductor scrap from die wear-induced surface defects.
REACH substance restrictions are eliminating hexavalent chromium surface treatments from European die finishing processes. Die manufacturers are shifting to diamond-like carbon coatings and alternative passivation chemistries. Electrical wire segments with export exposure to EU markets are absorbing reformulation costs fastest to maintain market access.
After-sales service unbundling is separating die sales from reconditioning contracts at major wire producers. Original equipment suppliers now compete with independent refurbishment shops on turnaround speed rather than exclusivity. This pattern is most visible in China's export-oriented cable manufacturing clusters where procurement departments negotiate die supply and maintenance separately.
Wire Drawing Dies Market Segmentation
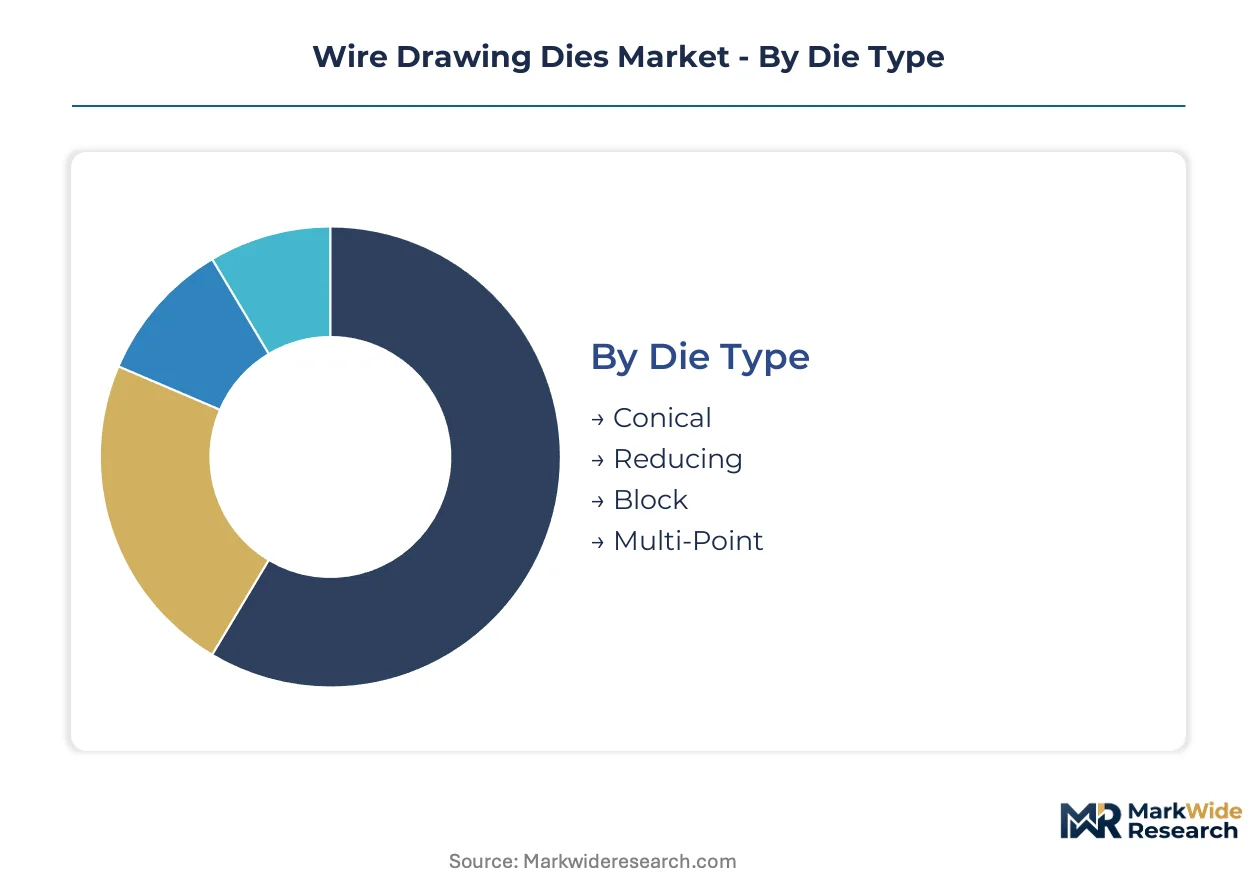
Wire drawing dies serve distinct operational regimes where bore geometry, material hardness, and wear tolerance determine replacement economics. Segmentation reveals how procurement priorities diverge between high-volume ferrous drawing and precision non-ferrous applications.
Die Type:
Upgrade cycles vary by geometry complexity, with multi-point configurations demanding more frequent reconditioning than single-cone designs.
- Conical:The standard entry-bearing-back-relief profile dominates commodity wire production. Chinese cable manufacturers in Jiangsu and Zhejiang provinces deploy conical carbide dies for aluminum conductor drawing where throughput volume outweighs micron-level precision requirements.
- Reducing:Step-down bore configurations enable sequential diameter reduction without intermediate annealing. Demand concentrates in German automotive cable plants producing multi-strand copper bundles for electric vehicle power distribution, where process consolidation cuts energy costs.
- Block:Fixed-diameter finishing dies lock final wire dimensions before spooling. Japanese precision wire mills use block diamond dies for sub-0.1 mm magnet wire serving robotics motor windings.
- Multi-Point:Compound geometry dies integrate drawing and shaping in single pass. US specialty alloy producers deploy these for nickel-chrome heating element wire where bore wear patterns accelerate replacement frequency.
Conical dies sit at the top of the volume ranking, with multi-point configurations climbing the fastest as continuous drawing lines proliferate.
Material:
Cost tier stratification separates captive synthetic diamond supply from commoditized carbide procurement.
- Carbide:Tungsten-cobalt matrices tolerate high-load ferrous drawing. Indian wire rod producers under PLI scheme incentives favor carbide for infrastructure-grade steel cable where die life measured in tons drawn determines tooling economics.
- Diamond:Synthetic polycrystalline variants command premium positioning in fine copper applications. Element Six and ILJIN Diamond supply PCD blanks to European electrical wire specialists where surface finish prevents conductor resistance variation.
- Steel:Tool steel dies serve prototype and low-volume specialty alloy runs. US job shops maintain steel die inventories for titanium and nickel superalloy wire where batch sizes below 500 kg cannot amortize carbide or diamond tooling.
- Ceramics:Silicon nitride and alumina variants handle abrasive ferrous alloys at elevated temperatures. Japanese stainless steel wire producers deploy ceramic dies for 300-series alloys where carbide galling accelerates bore degradation.
Carbide maintains the broadest installed base, though diamond is gaining share fastest as fine-wire electrical applications expand.
Application:
End-use specifications dictate tolerance grades and reconditioning frequency across divergent quality regimes.
- Electrical Wires:Copper and aluminum conductor drawing demands micron-level bore stability. Grid modernization in China pulls diamond die consumption for extra-high-voltage cable where diameter consistency prevents corona discharge losses.
- Automotive Cables:Multi-strand bundling applications prioritize cost-per-ton over absolute precision. German OEM cable suppliers run carbide dies at high speeds for chassis wiring harnesses where surface defects remain within electrical tolerance bands.
- Industrial Wires:General-purpose steel and alloy wire for fasteners, springs, and mesh tolerates wider dimensional variance. US fastener manufacturers in the Midwest operate mixed carbide die fleets with aggressive reconditioning schedules.
- Copper Alloys:Brass and bronze wire for connectors and terminals requires polished bore finishes. Japanese electronics subcontractors specify diamond dies for 0.05 mm phosphor bronze signal wire where oxide-induced resistance spikes trigger rejection.
Electrical wires command the highest die replacement rates, with copper alloy applications expanding most quickly as connector miniaturization advances.
End User:
Procurement sophistication separates integrated manufacturers from fragmented service-dependent buyers.
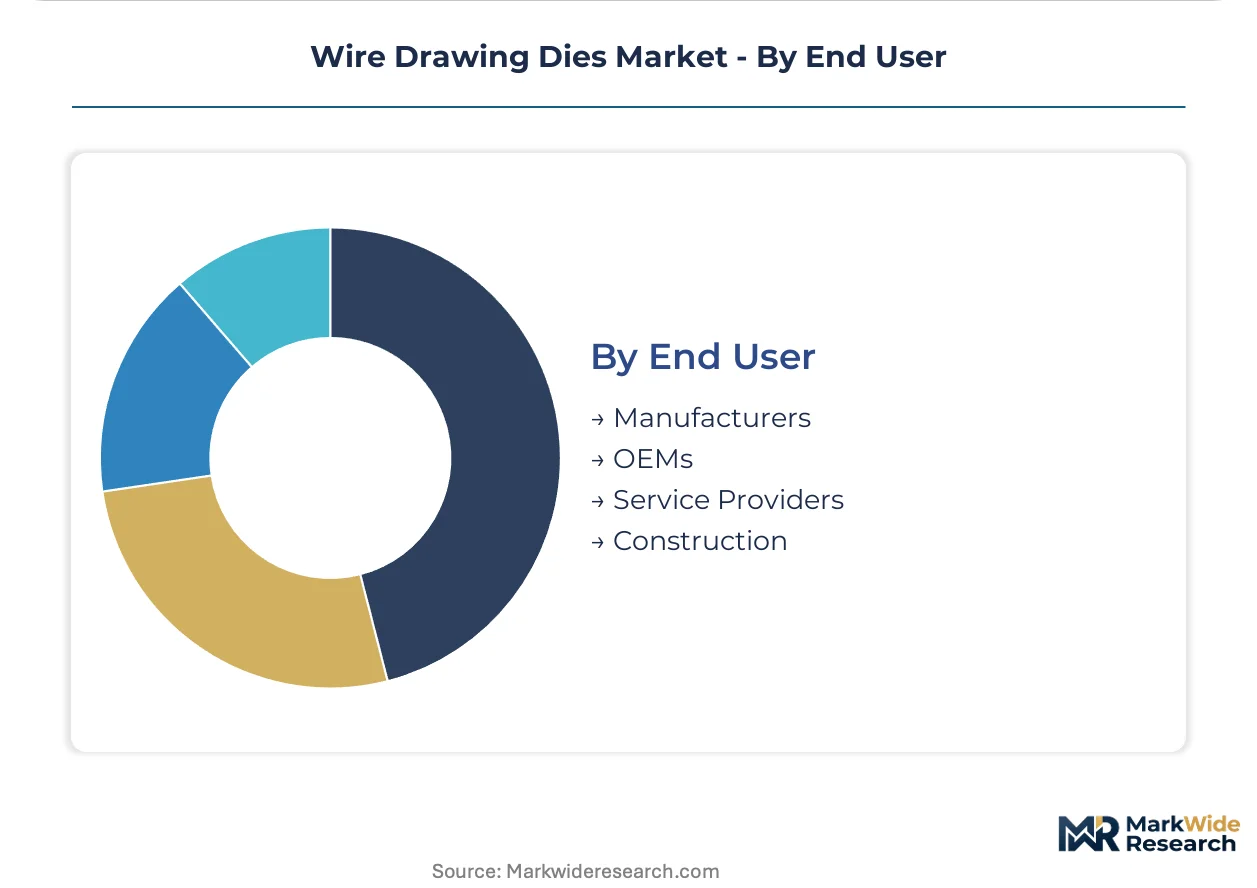
- Manufacturers:Captive wire drawing operations at cable and fastener producers represent the core die demand base. Chinese state-owned cable groups maintain internal die reconditioning workshops to minimize tooling downtime.
- OEMs:Original equipment manufacturers with vertical wire production integrate die specification into equipment procurement. European automotive tier-one suppliers negotiate multi-year die service contracts alongside drawing machine acquisitions.
- Service Providers:Independent die reconditioning specialists capture aftermarket revenue. Esteves Group and Fort Wayne Wire Die operate regional service networks across North America and Europe where wire mills outsource maintenance.
- Construction:Project-specific wire procurement for infrastructure builds drives spot die demand. Indian bridge and power transmission contractors source carbide dies through distributors for temporary on-site wire production facilities.
Manufacturers represent the largest die procurement segment, with service providers climbing fastest as outsourcing of reconditioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed cable production targets pull diamond die consumption volumes that Germany's precision automotive wire sector cannot match ton-for-ton, though German manufacturers maintain tighter tolerance specifications.
United States
Grid modernization under FERC transmission expansion orders drives procurement of synthetic diamond dies for extra-high-voltage cable manufacturing. EPA metalworking effluent guidelines accelerate die replacement cycles among Midwestern wire rod producers seeking compliance through precision tooling upgrades. Drawing operations concentrate in Ohio and Indiana, where fastener manufacturers operate mixed carbide die fleets with aggressive reconditioning schedules.
Germany
Automotive cable plants producing multi-strand copper bundles for electric vehicle power distribution favor step-down bore configurations that eliminate intermediate annealing. REACH substance restrictions eliminate hexavalent chromium surface treatments from die finishing processes, forcing shifts to diamond-like carbon coatings. Industrial activity clusters in Baden-Württemberg and Bavaria, where tier-one cable suppliers negotiate multi-year die service contracts alongside drawing machine acquisitions.
China
State-backed transmission expansion pulls diamond-coated die consumption through cable manufacturing capacity additions in Jiangsu and Zhejiang provinces. GB standards for wire rod quality and MEE environmental enforcement tighten die performance benchmarks for export-oriented manufacturers. Domestic carbide supply chains reinforce local die consumption, with state-owned cable groups maintaining internal reconditioning workshops to minimize tooling downtime.
India
PLI scheme incentives for domestic wire and cable production create first-mover advantage for die suppliers establishing local service presence. BIS certification requirements shape material specifications for infrastructure-grade steel cable procurement. Manufacturing concentrates in Gujarat and Maharashtra, where bridge and power transmission contractors source carbide dies through distributors for temporary on-site wire production facilities.
Japan
Precision wire mills deploy block diamond dies for sub-0.1 mm magnet wire serving robotics motor windings, with METI industrial technology roadmaps pushing micron-level bore stability. JIS standards for conductor quality prevent oxide-induced resistance spikes in 0.05 mm phosphor bronze signal wire. Production gravity sits in Nagoya and Osaka industrial corridors, where electronics subcontractors specify diamond dies for connector miniaturization applications.
Wire Drawing Dies Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with synthetic diamond supply concentrating among advanced materials specialists while carbide fabrication fragments across regional machine shops. Three archetypes dominate: captive synthetic diamond producers insulating margin pools from raw material volatility, precision geometry specialists occupying defensible niches above commodity tiers, and service-network operators capturing recurring maintenance contracts. Consolidation pressure runs through M&A activity targeting regional reconditioning capabilities, while geographic expansion into India's PLI-driven cable manufacturing clusters represents the parallel competitive vector.
Among European-anchored suppliers, Esteves Group exemplifies the service-network archetype through its regional maintenance infrastructure, while Element Six represents captive synthetic diamond production. Woodburn Diamond Die occupies a position within the precision geometry tier. These three entities illustrate how competitive positioning stratifies across material control, geometric specialization, and aftermarket service density rather than scale alone.
| Leading Market Players |
|---|
| Woodburn Diamond Die |
| UKO |
| Esteves Group |
| Zhengzhou IW Diamond |
| REDIES |
| Element Six |
| SND |
| Morgan Advanced Materials |
| Sancliff Inc |
| Others |
Pricing and Supply Chain Analysis
Precision grinding expertise concentrated in Baden-Württemberg and Bavaria toolmaking clusters widens spreads between premium diamond dies and commodity carbide tiers, as labor-cost differentials between European specialists and Chinese fabricators compound raw material tier gaps.
Pricing Analysis
Capacity additions in Jiangsu and Zhejiang are reshaping price floors for standard conical carbide dies, compressing margins for regional fabricators serving infrastructure-grade cable production. Three-tier pricing structure across premium synthetic diamond, certified carbide, and economy tool steel segments reflects certification grade and after-sales service bundling. Cost compression in carbide tiers is intensifying because domestic Chinese supply chains undercut import pricing. Automotive cable manufacturers exhibit highest price sensitivity, while Japanese precision wire mills for sub-0.1 mm magnet wire absorb diamond premiums without volume elasticity.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for die reconditioning services, pressuring foreign suppliers to establish local grinding facilities. Synthetic polycrystalline diamond blanks concentrate supply from Element Six in Ireland and ILJIN in South Korea, while tungsten carbide feedstocks anchor in China's domestic mining and powder metallurgy base. Single-source vulnerability runs through captive PCD production limited to three advanced materials specialists. Distribution runs through regional service networks rather than direct mill relationships, with Esteves Group and Fort Wayne Wire Die operating hub-and-spoke maintenance infrastructure across North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH compliance costs in Europe and EPA effluent-driven replacement demand in the United States, with regulatory divergence creating tiered margin pools.
For Market Incumbents: Deepen captive synthetic diamond production to insulate margin pools from tungsten carbide price volatility threatening commodity die producers. Add reconditioning capacity in Gujarat and Maharashtra to capture PLI-driven cable manufacturing expansion before independent specialists establish local presence. Anchor service contracts to drawing machine OEM partnerships, locking out refurbishment competition through bundled maintenance agreements. For New Entrants and Emerging Players: Enter via precision geometry specialization for sub-0.05 mm copper alloy wire applications, where retiring European toolmaker expertise constrains incumbent replication. Target India's infrastructure cable segment as the most penetrable geography, where BIS certification requirements favor local fabrication over import dependency. Lead with rapid turnaround reconditioning services rather than new die sales, bypassing capital-intensive PCD synthesis barriers. For Investors and Strategic Acquirers: Advanced materials divisions of diversified industrial conglomerates are the most active acquirer in this space, seeking synthetic diamond capabilities to backward-integrate into precision tooling. Long-term viability hinges on circular material flows and verified recycled carbide certification under EU Green Deal tracking. Watch for REACH substance restriction expansions beyond hexavalent chromium as the inflection signal forcing reformulation investment and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Synthesis | Captive PCD production insulates Element Six from raw material volatility affecting competitors. |
| Regional Reconditioning Network Expansion | Esteves Group's European maintenance infrastructure captures recurring contracts from cable producers. |
| Recycled Carbide Feedstock Certification | Verified circular material flows open premium positioning under EU Green Deal embodied-carbon tracking. |
| Condition-Based Monitoring Integration | Bore-wear sensors enable predictive maintenance contracts at German and Japanese wire mills. |
| Precision Geometry Specialization | Woodburn Diamond Die's conical expertise for fine-wire applications occupies defensible niche above commodity tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with die reconditioning service heads, wire mill maintenance directors, synthetic diamond procurement leads, and cable manufacturing operations managers with secondary validation from SEC filings, customs trade data, EPA metalworking effluent guideline dockets, and REACH substance restriction updates. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting approach applied material type, die geometry complexity, end-use application, and regional regulatory cluster as core dimensions. CAGRs derived from trend extrapolation of replacement cycle frequencies, capacity addition announcements, and compliance-driven upgrade patterns. Forecast inputs incorporated wire rod production volumes, grid modernization procurement schedules, and automotive cable electrification content shifts.
Inputs from wire mill operators and die reconditioning specialists were available through the study window; gaps in proprietary cost structures for synthetic diamond synthesis introduce uncertainty bands around margin projections. Forecasts reflect assumptions on regulatory enforcement timelines and technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Air Classifiers Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Powder Processing Service Market
Industrial Materials
Metal Molds Market
Industrial Materials
Cryogenic Insulation Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Isostatic Pressing Market
Industrial Materials
Asia-Pacific Industrial Flooring Market
Industrial Materials
Polyurethane Insulation Board Market