
 Foam Insulation Market | 2026-2036
Foam Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Insulation Market Analysis
Class A fire-rated and low-global-warming-potential specification tiers is redrawing procurement criteria across commercial envelopes. BASF SE leverages its integrated polyol supply chain to control formulation consistency for high-performance spray systems. Owens Corning anchors North American board-stock capacity through mineral-wool-adjacent manufacturing synergies. Covestro AG differentiates in Europe through certified passive-house-compatible polyurethane panels.
Foam insulation comprises cellular polymer matrices—polyurethane, polystyrene, phenolic, or hybrid chemistries—manufactured via continuous lamination, batch molding, or field-applied spraying, with thermal conductivity values typically ranging from 0.020 to 0.035 W/m·K depending on cell-gas composition and density. Its primary purpose is reducing conductive and convective heat transfer in building envelopes, industrial equipment, and transportation shells. Spray foam commands premium positioning in retrofit and complex-geometry applications where air-sealing performance justifies higher installed cost. Polystyrene foam sustains volume leadership in below-grade and cavity-wall board applications due to moisture resistance and established distribution through construction-material channels. Phenolic foam occupies a specialized niche in high-temperature industrial insulation where low smoke toxicity and flame-spread indices override material cost premiums.
The EPA's Significant New Alternatives Policy program and the AIM Act hydrofluorocarbon phasedown are reshaping blowing-agent selection across U.S. foam production, while REACH restrictions on isocyanates and flame-retardant substances constrain formulation flexibility for European manufacturers. China's GB standards for building energy efficiency and MIIT guidelines on low-carbon construction materials are tightening performance thresholds for imported and domestic foam products alike. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains and to align R&D pipelines with region-specific compliance timelines.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon blowing agents under the AIM Act is forcing foam manufacturers to reformulate entire product lines around next-generation cell-gas chemistries, redrawing competitive advantage around R&D velocity and supply-chain integration.
Growth Catalysts
- Residential energy code tightening:Cold-climate builders in the United States and Germany are expanding specification-grade foam adoption as thermal performance mandates intensify envelope requirements.
- REACH restrictions on isocyanates:European manufacturers are accelerating investment in low-toxicity curing systems to maintain formulation flexibility under ECHA substance controls.
- China's MIIT low-carbon construction guidelines:Domestic producers are scaling certified polyurethane panel capacity to capture retrofit incentives tied to building energy efficiency standards.
Market Restraints
- Polyol feedstock volatility:Propylene oxide and MDI price swings compress margin stability for independent foam compounders lacking captive petrochemical supply.
- Concentrated blowing-agent supply:Three chemical conglomerates control 80% of HFO-1234ze and trans-1,1,1,3-tetrafluoropropene global production, creating bottleneck risk during formulation transitions.
- Mineral wool substitution in commercial high-rises:Non-combustible stone wool is capturing specification share where fire-resistance rating overrides thermal performance premiums.
Strategic Opportunities
- Passive house certification tailwinds:Covestro AG and European system houses are positioning certified polyurethane panels to capture Germany and Austria's expanding zero-energy building mandates.
- Spray foam robotics integration:Automated application systems are opening commercial retrofit segments where labor scarcity previously constrained project scalability.
- India's BIS energy efficiency labeling:Imported and domestic foam producers can capture first-mover advantage as the Bureau of Indian Standards implements mandatory thermal conductivity disclosure for building envelope materials.
Industry Challenges
- Certified installer pipeline gaps:Spray foam contractors face 12-18 month training timelines to achieve manufacturer warranty eligibility, throttling capacity expansion in high-demand zones.
- Legacy stock stranding risk:Distributors holding HFC-based inventory must navigate staggered AIM Act phaseout deadlines across U.S. climate zones without write-down exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Insulation Market |
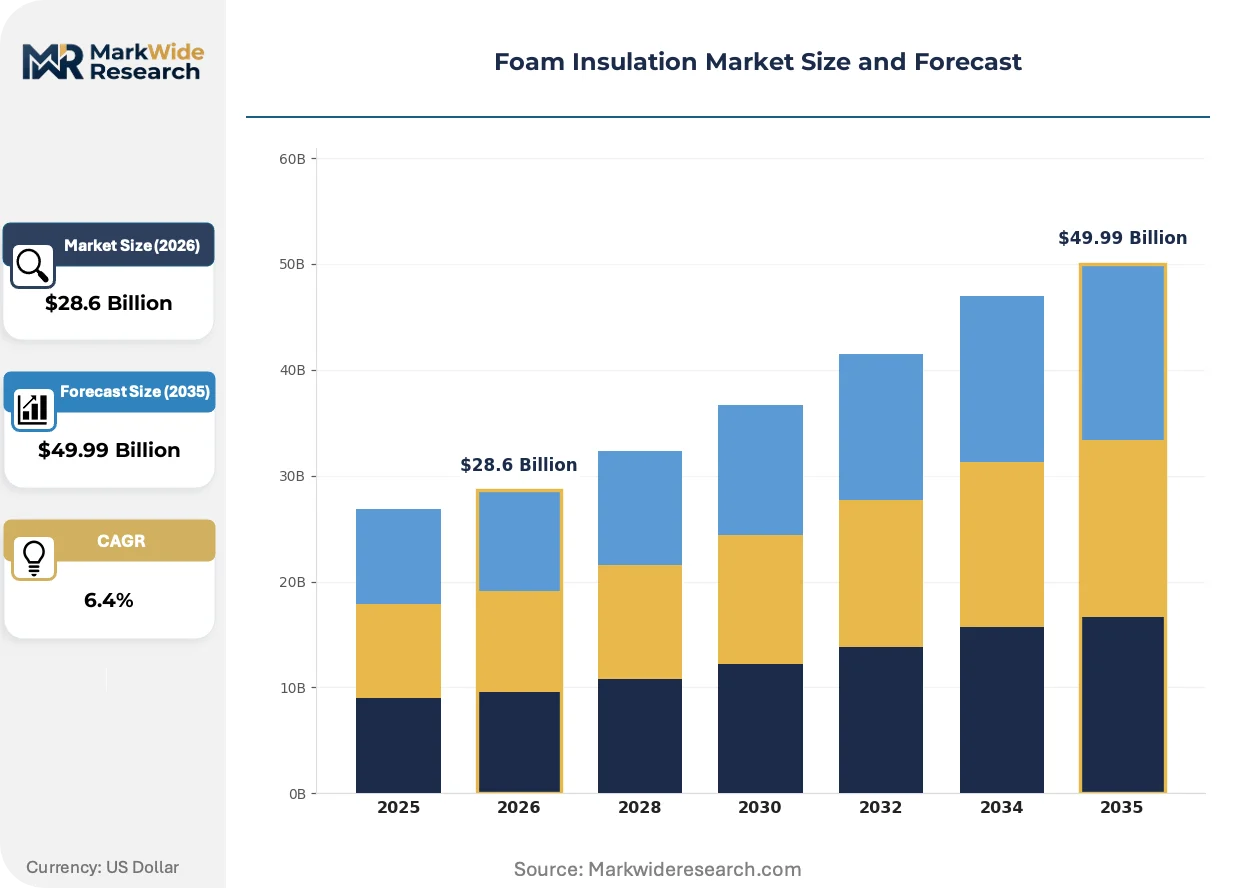
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam, Polystyrene Foam, Phenolic Foam, Spray Foam Application: Thermal Insulation, Soundproofing, Air Sealing, Structural Insulation End User: Residential, Commercial, Industrial, Automotive Form: Board, Spray, Panel, Block |
| Companies Covered | BASF SE, Dow, Owens Corning, Kingspan Group, Covestro AG, Huntsman Corporation, Saint-Gobain, Johns Manville, Armacell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Insulation Market Emerging Trajectories
Formulation chemistry and application methodology are diverging simultaneously, with manufacturers pursuing distinct technical bets on cell-gas composition while deployment technology fragments between site-mixed and pre-fabricated systems.
Water-blown polyurethane systems with hydrofluoroolefin co-blowing are bifurcating performance tiers in commercial roofing applications. Large-scale membrane contractors are specifying HFO-enhanced formulations for 20-year thermal warranty coverage, while economy-tier projects retain legacy HFC blends where code grandfathering permits. This chemistry split is compressing mid-market suppliers unable to fund dual-formulation certification.
The EPA's Significant New Alternatives Policy program is accelerating alternative blowing-agent approvals ahead of AIM Act phaseout deadlines. U.S. spray-foam producers are requalifying entire product portfolios under SNAP listings for trans-1,1,1,3-tetrafluoropropene and hydrocarbon blends. Board-stock manufacturers face tighter compliance timelines than field-applied systems, driving consolidation around integrated chemical producers with in-house toxicology submission capabilities.
Specification-grade procurement is consolidating around certified passive-house performance data rather than nominal R-value claims. German and Austrian envelope designers are demanding blower-door-tested assembly performance guarantees from foam suppliers, displacing commodity board-stock distributors. This verification-driven buying pattern is most visible in Central European residential construction, where energy-plus building standards now dominate new permitting.
Foam Insulation Market Segmentation
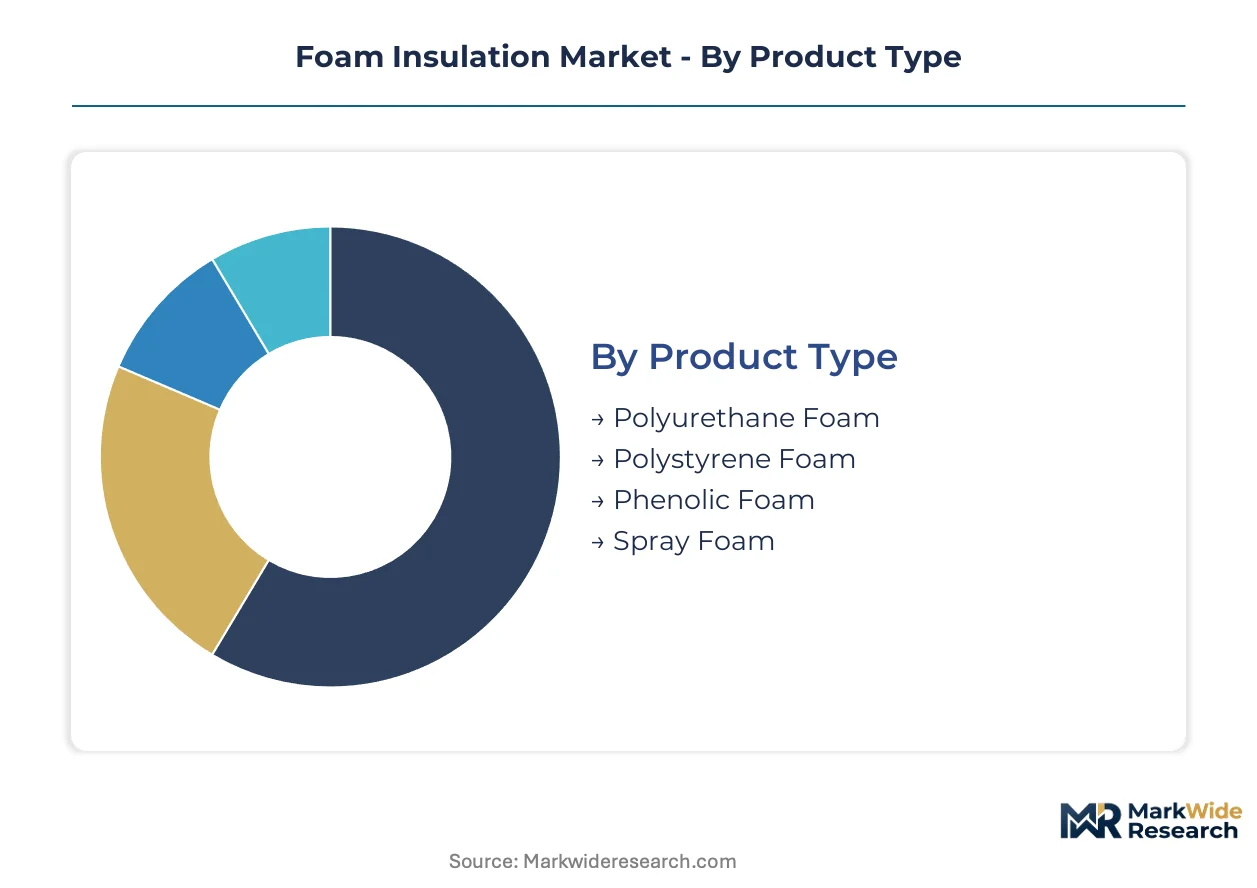
Foam insulation procurement fragments across material chemistry, deployment method, and end-use performance requirements. Specification-grade buyers prioritize certified thermal conductivity and fire-resistance ratings over commodity pricing, while retrofit contractors optimize for application speed and geometry adaptability.
Product Type:
Polyurethane and polystyrene formulations dominate domestic production in the United States, Germany, and China, while phenolic systems remain concentrated in European export channels serving high-temperature industrial applications.
- Polyurethane Foam:Closed-cell matrices manufactured from MDI and polyol reactions achieve thermal conductivity values near 0.022 W/m·K. Demand concentrates in German and Austrian passive-house construction where blower-door-tested assembly guarantees override nominal R-value claims. The EPA's AIM Act HFC phasedown is forcing reformulation toward HFO-1234ze co-blowing systems.
- Polystyrene Foam:Expanded and extruded variants offer moisture resistance and established distribution through construction-material channels. Below-grade and cavity-wall applications in U.S. residential construction sustain volume leadership, though REACH restrictions on flame retardants constrain European formulation flexibility.
- Phenolic Foam:High-temperature industrial insulation where low smoke toxicity and flame-spread indices override material cost premiums. Exports from European manufacturers serve Middle East petrochemical facilities.
- Spray Foam:Field-applied polyurethane systems command premium positioning in retrofit and complex-geometry applications where air-sealing performance justifies higher installed cost. U.S. contractors face 12-18 month certified installer training timelines.
Polystyrene foam holds the largest share; momentum sits with spray foam as labor scarcity drives robotics integration.
Application:
Cost tier stratification separates warranty-backed commercial roofing from economy-grade residential retrofits, with specification-grade procurement consolidating around verified assembly performance rather than material claims alone.
- Thermal Insulation:Reducing conductive and convective heat transfer in building envelopes, industrial equipment, and transportation shells. China's MIIT low-carbon construction guidelines are tightening performance thresholds for domestic and imported products.
- Soundproofing:Acoustic dampening in commercial interiors and transportation applications. Mineral wool substitution in high-rise construction limits foam penetration where fire-resistance ratings override acoustic performance.
- Air Sealing:Continuous barrier systems eliminating thermal bypass. Spray foam dominates complex geometries in U.S. cold-climate zones as energy codes tighten envelope requirements.
- Structural Insulation:Load-bearing insulated panels for prefabricated construction. Covestro AG and European system houses are positioning certified polyurethane panels to capture Germany's expanding zero-energy building mandates.
Thermal insulation commands the dominant revenue position; air sealing is climbing fastest as retrofit incentives expand.
End User:
Customer-type concentration varies sharply by project scale, with residential retrofits fragmenting across thousands of local contractors while commercial and industrial procurement consolidates around national specification houses.
- Residential:Cold-climate builders in the United States and Germany are expanding specification-grade foam adoption. Single-family new construction and deep energy retrofits drive demand for high-R-value board stock and spray systems.
- Commercial:Membrane roofing and curtain-wall applications specify HFO-enhanced formulations for extended thermal warranty coverage. Three chemical conglomerates control 80% of next-generation blowing-agent production, creating supply bottleneck risk.
- Industrial:High-temperature equipment and process piping insulation. Phenolic foam occupies specialized niches where low smoke toxicity is mandatory.
- Automotive:Lightweight thermal and acoustic management in electric vehicle battery enclosures and cabin systems. OEMs are qualifying water-blown polyurethane systems to meet volatile organic compound restrictions.
Residential end-use maintains volume leadership; automotive applications are expanding most quickly as electrification accelerates thermal management requirements.
Form:
Supply concentration favors integrated chemical producers with in-house lamination and molding capabilities, while independent compounders struggle with polyol feedstock volatility and dual-formulation certification costs.
- Board:Continuous lamination of facer materials to foam cores for wall and roof assemblies. Polystyrene board sustains volume leadership through established distribution channels.
- Spray:Field-mixed two-component systems applied via plural-component equipment. Automated application systems are opening commercial retrofit segments where labor scarcity previously constrained project scalability.
- Panel:Pre-fabricated insulated assemblies for modular and passive-house construction. German and Austrian envelope designers are demanding blower-door-tested performance guarantees.
- Block:Batch-molded billets for fabrication into custom shapes. Industrial equipment insulation and specialized architectural applications sustain niche demand.
Board form retains the largest installed base; panel systems are gaining share fastest as prefabrication penetrates residential construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in foam insulation track regulatory divergence rather than pure cost arbitrage, with formulation-grade products crossing borders while commodity board-stock stays regional. Export competitiveness now hinges on certified low-global-warming-potential chemistries rather than scale economies alone.
United States
Residential builders in Minnesota and Wisconsin are expanding specification-grade spray foam adoption as IECC 2021 energy codes tighten envelope requirements. The EPA's AIM Act hydrofluorocarbon phasedown is forcing reformulation timelines that vary by climate zone, creating inventory management complexity for distributors. Houston and Dallas-Fort Worth anchor commercial roofing demand where membrane contractors specify HFO-enhanced systems for extended thermal warranties.
Germany
Passive-house construction in Bavaria and Baden-Württemberg is driving certified polyurethane panel demand where blower-door-tested assembly guarantees override nominal R-value claims. REACH restrictions on isocyanates and flame-retardant substances are constraining formulation flexibility for domestic manufacturers. The Rhine-Ruhr industrial corridor concentrates board-stock production with integrated polyol supply chains serving Central European export markets.
China
MIIT low-carbon construction guidelines are tightening performance thresholds for domestic and imported foam products in Beijing-Tianjin-Hebei and Yangtze River Delta metro clusters. GB standards for building energy efficiency are accelerating certified polyurethane panel capacity expansion among state-owned chemical producers. Shenzhen and Guangzhou retrofit incentives are concentrating demand for high-R-value board stock in commercial building envelope upgrades.
India
Bureau of Indian Standards energy efficiency labeling implementation is creating first-mover advantage opportunities for imported and domestic foam producers in Maharashtra and Gujarat construction markets. CEA building codes are tightening thermal performance mandates for commercial high-rises in Mumbai and Pune. Delhi-NCR deep energy retrofit programs are driving specification-grade procurement where certified thermal conductivity disclosure is becoming mandatory.
Canada
Cold-climate residential construction in Ontario and Quebec is sustaining demand for high-R-value spray foam systems where air-sealing performance justifies installed cost premiums. Health Canada's alignment with EPA SNAP program timelines is accelerating alternative blowing-agent approvals ahead of provincial phaseout schedules. Toronto and Vancouver green building codes are concentrating specification-grade procurement around verified assembly performance data.
Foam Insulation Market Vendor Landscape
Listed leaders compete with private specialists across formulation chemistry and application methodology, with public chemical conglomerates controlling upstream polyol and isocyanate supply while independent compounders focus on regional installation networks. Market structure tilts toward consolidated upstream supply and fragmented downstream application. Three archetypes dominate: integrated chemical producers with captive feedstock, system houses with certified installer networks, and regional board-stock fabricators with established distribution channels. Competitive moves center on dual-formulation certification costs and strategic partnerships with robotics application developers.
Within the integrated chemical producer tier, BASF SE and Covestro AG exemplify archetypes leveraging captive polyol supply chains to control formulation consistency for high-performance systems. Dow occupies a position spanning both upstream chemical production and downstream building materials distribution. Among specialty system houses, Huntsman Corporation sits within the certified installer network development segment where training pipeline investments create competitive moats.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Owens Corning |
| Kingspan Group |
| Covestro AG |
| Huntsman Corporation |
| Saint-Gobain |
| Johns Manville |
| Armacell |
| Others |
Supply Flow & Price Mechanics
Captive polyol production at integrated chemical conglomerates in Germany and the United States establishes scale floors that independent compounders cannot match, concentrating pricing power among MDI producers while fragmenting margin capture downstream. This asymmetry forces board-stock fabricators and spray-foam contractors to absorb feedstock volatility or cede share to system houses with backward-integrated supply.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing stratification across specification-grade, commercial-standard, and economy tiers. Price differentiation hinges on certified thermal conductivity guarantees and fire-resistance ratings under UL and ASTM protocols. Cost compression in economy-tier board stock intensifies as REACH-compliant European imports displace domestic HFC-based formulations. Residential retrofit contractors exhibit highest price sensitivity, while passive-house developers in Bavaria and Austria accept substantial premiums for blower-door-tested assembly warranties.
Supply Chain Analysis
BASF's Ludwigshafen complex and Covestro's Dormagen facility anchor European polyol supply, creating single-source vulnerability for independent foam compounders lacking captive feedstock. Production draws from propylene oxide, MDI, and next-generation HFO-1234ze blowing agents controlled by three chemical conglomerates. Tariff exposure on Chinese polystyrene board imports into the United States compounds margin pressure for regional fabricators. Distribution runs through construction-material wholesalers and certified installer networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in the foam insulation market rests on accelerating specification-grade adoption as building energy codes tighten across cold-climate jurisdictions. Penetration tailwinds from passive-house certification and robotics-enabled spray application create asymmetric upside for positioned players.
For Market Incumbents: Secure captive supply of HFO-1234ze and trans-1,1,1,3-tetrafluoropropene through long-term offtake agreements with Honeywell and Chemours before AIM Act phaseout deadlines strand legacy inventory. Consolidate certified installer networks in Minnesota, Wisconsin, and Ontario where labor scarcity throttles capacity expansion. Mineral wool substitution in commercial high-rises demands fire-rated formulation investment to defend specification share.
For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat construction corridors where BIS energy efficiency labeling creates first-mover advantage before mandatory thermal conductivity disclosure hardens competitive barriers. Target automotive battery enclosure insulation as electric vehicle OEMs qualify water-blown polyurethane systems to meet volatile organic compound restrictions. Pursue robotics application partnerships to bypass the 12-18 month certified installer training bottleneck constraining spray-foam scalability.
For Investors and Strategic Acquirers: Regional system houses with established passive-house certification pipelines and captive installer networks present the most defensible acquisition profile. Long-term viability over the next decade hinges on successful HFC-to-HFO formulation transition completion and MIIT compliance positioning for Chinese market access. Watch EPA SNAP program approval velocity for alternative blowing-agent candidates as the inflection indicator for stranded inventory risk among legacy distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Supply | BASF and Covestro control formulation consistency through captive MDI production, compressing independent compounder margins. |
| HFO-1234ze Co-Blowing Certification | Dual-formulation portfolios under EPA SNAP listings protect distributors from AIM Act phaseout inventory stranding. |
| Certified Installer Network Expansion | Huntsman Corporation's 12-18 month training pipelines create competitive moats in labor-scarce cold-climate zones. |
| Passive-House Panel Production Scale-Up | Covestro AG captures Germany and Austria's zero-energy building mandates through blower-door-tested assembly guarantees. |
| Robotics Application System Partnerships | Automated spray systems unlock commercial retrofit segments previously constrained by contractor capacity limits. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EPA SNAP program filings, MIIT low-carbon construction guidelines, and REACH substance restriction updates. Plant managers at integrated chemical producers, procurement leads at membrane roofing contractors, distribution channel partners in construction-material wholesale, and technical R&D directors at system houses provided operational validation. Bottom-up demand modeling across polyurethane, polystyrene, phenolic, and spray-foam chemistries triangulates against top-down macroeconomic drivers.
Segmentation dimensions modeled span material chemistry, deployment method, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from volume-price elasticity analysis incorporating polyol feedstock cost trajectories and formulation-grade substitution dynamics. Industry-specific forecast inputs include AIM Act phaseout timelines by U.S. climate zone and BIS labeling implementation velocity in Indian construction markets.
Material uncertainties — EPA alternative blowing-agent approval delays, REACH isocyanate restriction tightening, and MIIT performance threshold acceleration — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory divergence between U.S., European, and Chinese jurisdictions evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Wire Mesh Market
Industrial Materials
Mineral Processing Equipment Market
Industrial Materials
Tension Spring Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Extruders Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Weatherstrip Seal Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Lip Seals Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Argon Knife Market
Industrial Materials
Carbide Inserts Market