
 Industrial Diamond Market | 2026-2036
Industrial Diamond Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Diamond Market Intelligence
China's Henan province is narrowing the synthetic diamond supply gap as domestic furnace capacity expands. De Beers leverages its Element Six subsidiary to anchor high-pressure high-temperature gem-quality output for precision electronics. ALROSA sustains natural diamond extraction from Siberian kimberlite pipes, competing on geological rarity for specialized aerospace bearings. Henan Huanghe Whirlwind Co. Ltd. dominates chemical vapor deposition wafer growth, positioning itself as the low-cost alternative for thermal spreaders in semiconductor packaging.
Industrial diamonds comprise crystalline carbon structures rated at ten on the Mohs hardness scale, synthesized through high-pressure high-temperature or chemical vapor deposition methods to achieve thermal conductivity exceeding copper for heat-dissipating substrates. Synthetic diamonds in the Category dimension command volume leadership due to reproducible lattice structures and tunable impurity profiles for electronics-grade specifications. Cutting Tools within Product Type concentrates margin pools where polycrystalline diamond inserts command premium pricing against tungsten carbide alternatives in automotive powertrain machining. Abrasives occupies mature growth trajectories in construction material processing, while Composite Materials in aerospace radomes represents the fastest-expanding application as ceramic matrix integration advances.
REACH in Europe restricts hexavalent chromium plating alternatives, redirecting demand toward diamond-coated tooling for compliant surface finishing. China's SAMR enforces GB standards on synthetic diamond purity classifications, shaping export eligibility for domestic producers. The EPA in the United States monitors abrasive particulate emissions from grinding operations, influencing wet-cutting system adoption. Stakeholders must track how carbon border adjustments and furnace energy intensity standards reshape cost structures across synthetic production routes.
Market Dynamics
Synthetic diamond production capacity in Henan province is compressing lead times for thermal management substrates, forcing natural diamond suppliers to reposition around geological scarcity in aerospace bearing applications.
Growth Catalysts
- Dual carbon goals in China:GB standards enforcement on furnace energy intensity is accelerating synthetic diamond purity upgrades for export-grade chemical vapor deposition wafers.
- Semiconductor packaging demand:Thermal conductivity specifications exceeding copper are pulling diamond heat spreaders into high-performance computing substrate stacks.
- REACH hexavalent chromium restrictions:European surface finishing regulations are redirecting automotive powertrain machining toward diamond-coated tooling compliance pathways.
Market Restraints
- Energy input cost volatility:High-pressure high-temperature synthesis requires sustained electricity loads, exposing margins to grid pricing fluctuations in furnace-intensive production zones.
- Henan supply concentration:Chemical vapor deposition wafer growth clusters in central China create single-source vulnerability for thermal spreader procurement.
- Cubic boron nitride substitution:Lower-cost superhard materials are capturing mid-tier cutting tool insert applications where thermal conductivity thresholds permit.
Strategic Opportunities
- Composite materials in aerospace radomes:Ceramic matrix integration with diamond reinforcement is opening specification windows in defense and satellite communications structures.
- India's PLI scheme for electronics:Domestic semiconductor packaging incentives are creating captive demand for thermal management substrate fabrication.
- Convergence of chemical vapor deposition and additive manufacturing:Near-net-shape diamond deposition is reducing post-growth machining requirements for complex heat sink geometries.
Industry Challenges
- Plasma physics specialization gap:Chemical vapor deposition reactor operation requires rare cross-training in microwave engineering and crystallography, constraining talent pipelines.
- EPA abrasive particulate compliance:Wet-cutting system retrofits for grinding operations demand capital redeployment without immediate throughput recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Diamond Market |
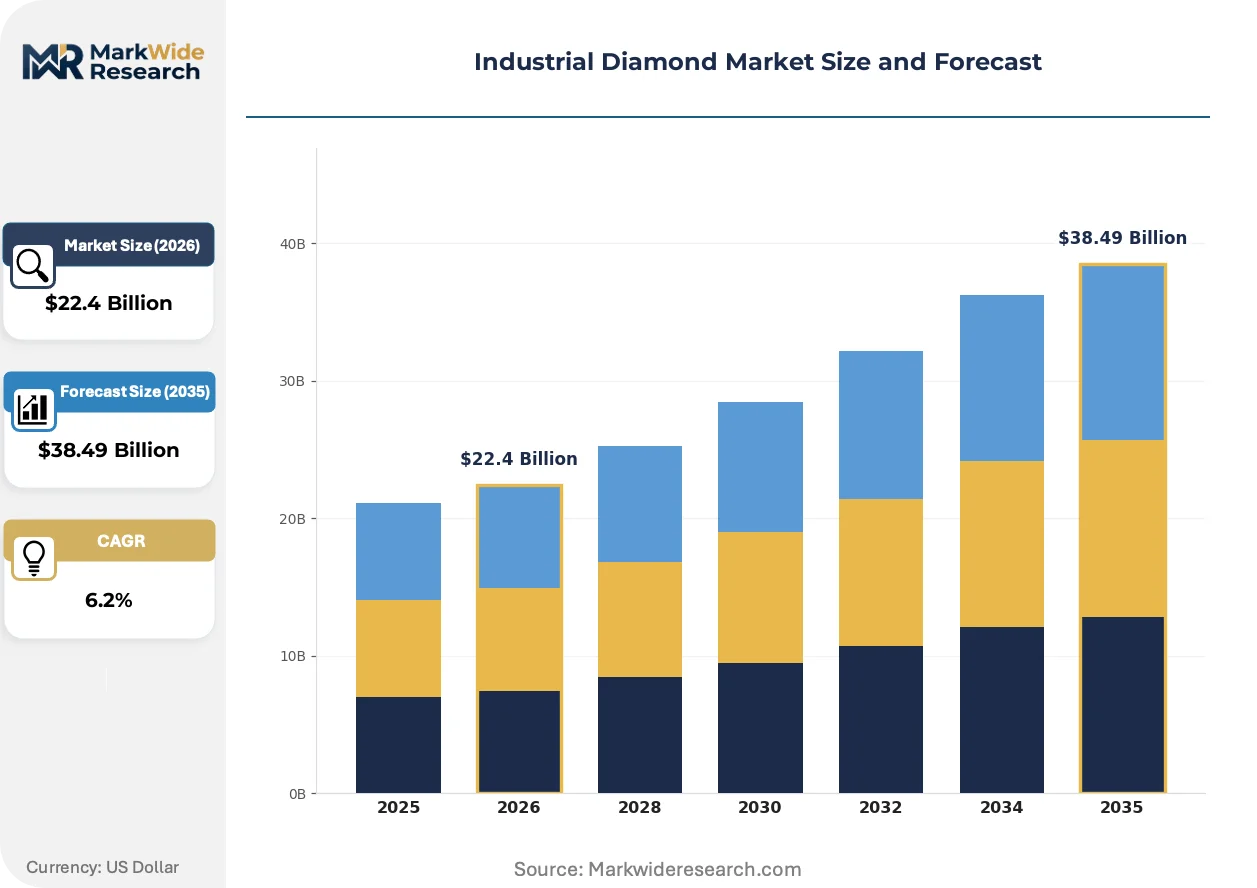
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Tools, Abrasives, Grinders, Composite Materials Category: Synthetic Diamonds, Natural Diamonds, Industrial Grade, Specialized Diamonds End User: Manufacturing, Automotive, Electronics, Aerospace Application: Drilling, Polishing, Grinding, Slicing |
| Companies Covered | De Beers, ALROSA, Applied Diamond, Inc., Industrial Diamond Laboratories, Inc., Morgan Advanced Materials, Scio Diamond Technology Corporation, Element Six UK Ltd., Sumitomo Electric Industries Ltd., Henan Huanghe Whirlwind Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Diamond Market Strategic Shifts & Innovations
Production technology trajectories are splitting between furnace-scale efficiency gains and deposition precision advances, with regulatory compliance acting as the forcing function for capital allocation decisions.
Polycrystalline diamond compact inserts are migrating from mechanical clamping systems to direct brazed interfaces in automotive powertrain machining. Tier-1 suppliers in Germany and Japan are adopting this bonding approach to reduce vibration-induced tool failure. The shift is compressing aftermarket insert replacement cycles while locking buyers into OEM-specific substrate geometries.
REACH authorization requirements for hexavalent chromium plating are eliminating legacy surface finishing options across European automotive supply chains. Diamond-coated cutting edges are capturing redirected demand for compliant powertrain component machining. Tooling distributors in Stuttgart and Turin are restructuring inventory mixes to prioritize superhard material specifications.
Specification-driven procurement now dominates thermal management substrate sourcing for data center semiconductors. Buyers in Taiwan and South Korea are unbundling heat spreader supply from full package assembly, creating direct contracting channels with Henan chemical vapor deposition growers. This disintermediation is compressing margin capture by intermediate substrate fabricators.
Industrial Diamond Market Segmentation
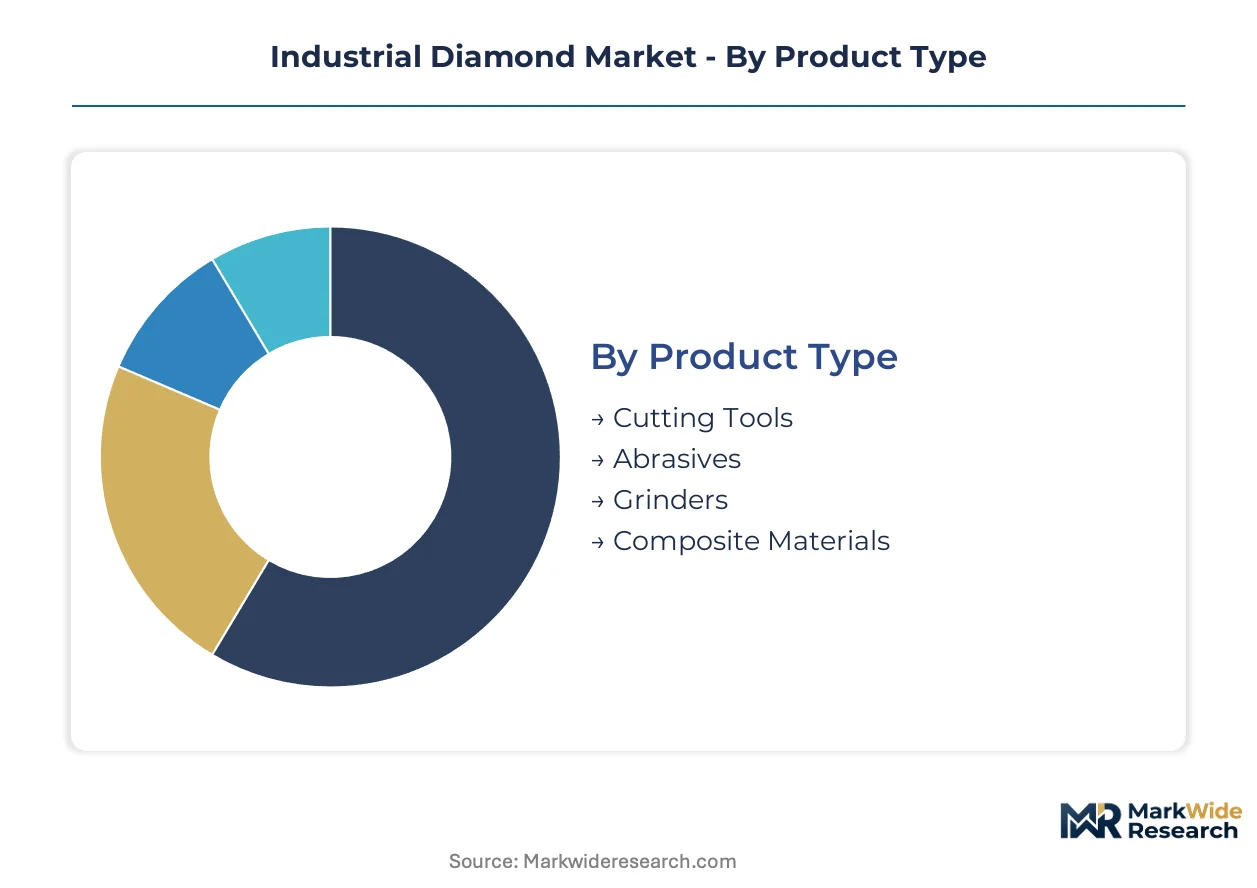
Industrial diamond procurement splits across material origin, tool configuration, and thermal management specification. Buyers in semiconductor packaging and aerospace machining source through distinct qualification pathways that reshape supplier priorities.
Product Type:
Application intensity separates mature consumable segments from precision tooling systems where specification windows tighten.
- Cutting Tools:Polycrystalline diamond compact inserts deliver hardness ratings exceeding tungsten carbide by 3-4x for automotive powertrain machining. German Tier-1 suppliers are migrating from mechanical clamping to direct brazed interfaces, compressing aftermarket replacement cycles while locking geometries to OEM specifications.
- Composite Materials:Ceramic matrix integration with diamond reinforcement achieves dielectric properties for aerospace radomes and satellite communications structures. Defense contractors in the United States and France are qualifying these materials for next-generation radar-transparent housings.
- Abrasives:Bonded and coated grinding wheels serve construction material processing with established supply chains.
- Grinders:Precision finishing systems target optical and medical device manufacturing.
Cutting Tools holds installed capacity. Composite Materials is rotating up the share rankings.
Category:
Volume concentration favors reproducible lattice structures over geological scarcity, though rarity commands premium positioning in specialized bearings.
- Synthetic Diamonds:Chemical vapor deposition wafers from Henan province achieve thermal conductivity specifications exceeding copper for semiconductor heat spreaders. Taiwan and South Korean packaging houses are disintermediating substrate fabricators through direct contracting with Chinese growers.
- Natural Diamonds:Siberian kimberlite extraction supplies aerospace bearing applications where geological certification satisfies traceability requirements. ALROSA sustains output from Arkhangelsk and Yakutia deposits for specialized radial load components.
- Industrial Grade:Standardized grit sizes serve mass-market abrasive applications.
- Specialized Diamonds:Tunable nitrogen-vacancy centers enable quantum sensing and magnetic field detection.
Synthetic Diamonds holds installed capacity. Natural Diamonds is rotating up the share rankings.
End User:
Customer sophistication tiers separate specification-driven procurement from price-sensitive consumable buying.
- Electronics:Data center semiconductor manufacturers unbundle heat spreader supply from full package assembly, creating direct channels with chemical vapor deposition growers. Taiwan Semiconductor Manufacturing Company and Samsung Foundry set thermal conductivity thresholds that exclude legacy substrate materials.
- Aerospace:Radome and bearing applications demand certified provenance for defense and satellite programs. Boeing and Airbus supply chains require material traceability through AS9100-qualified distributors.
- Manufacturing:General machining consumes standardized abrasive products.
- Automotive:Powertrain machining redirects toward REACH-compliant diamond-coated tooling as hexavalent chromium plating faces authorization restrictions.
Manufacturing holds installed capacity. Electronics is rotating up the share rankings.
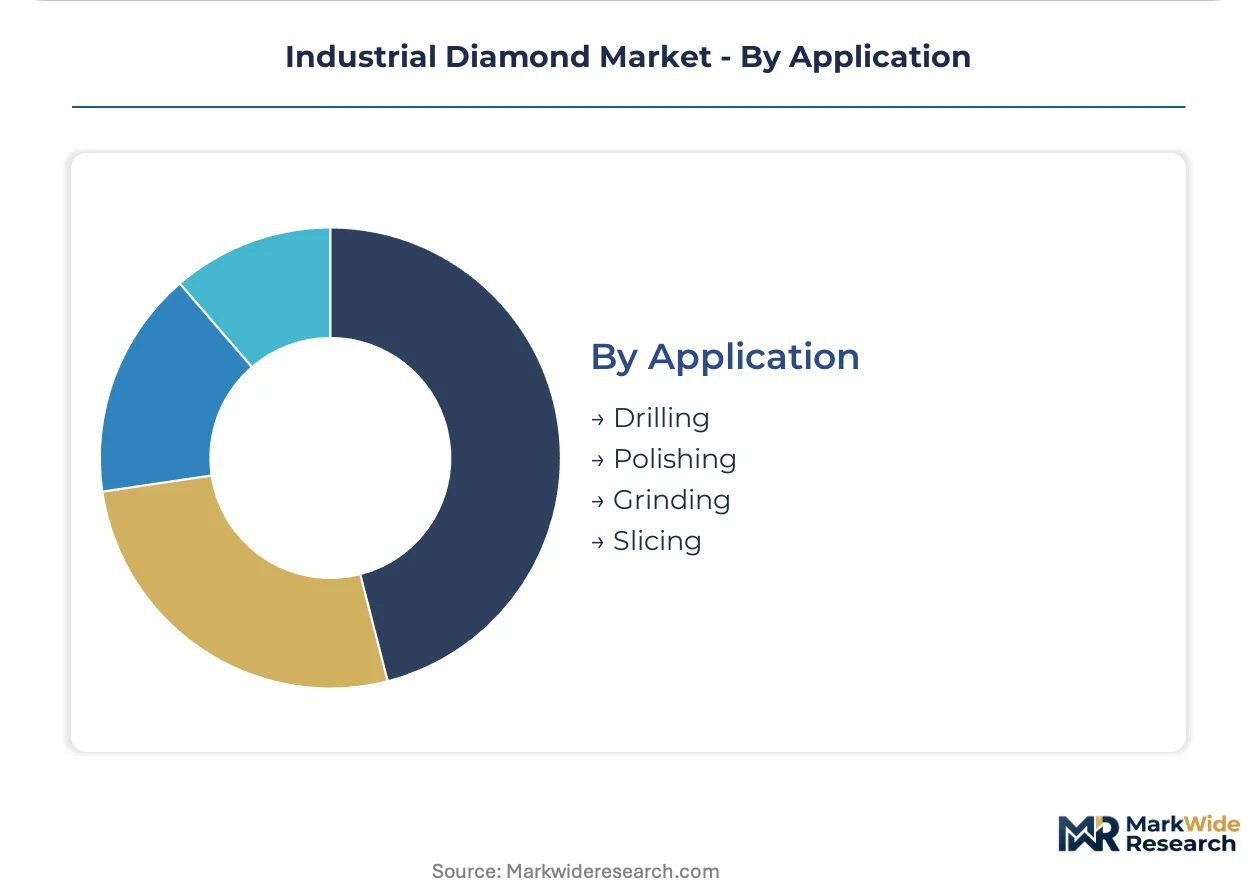
Application:
Process physics determines abrasive selection, with thermal load and surface finish requirements driving superhard material specification.
- Grinding:Wet-cutting system adoption accelerates under EPA abrasive particulate monitoring, requiring capital redeployment without immediate throughput recovery. Detroit-area automotive suppliers retrofit facilities to maintain operating permits.
- Polishing:Optical component finishing achieves sub-nanometer surface roughness for lithography systems and laser optics. Zeiss and Nikon specify synthetic diamond slurries for extreme ultraviolet mirror production.
- Drilling:Oil and gas exploration consumes polycrystalline diamond compact bits.
- Slicing:Silicon wafer dicing and photovoltaic ingot cutting employ fixed-abrasive wire systems.
Drilling holds installed capacity. Polishing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furnace capacity clusters in China's Henan province compress lead times for thermal management substrates, while precision electronics demand in East Asia and aerospace bearing requirements in Siberia create geographically distinct procurement corridors.
United States
Data center semiconductor manufacturers drive diamond heat spreader specifications exceeding copper thermal conductivity. EPA monitoring of abrasive particulate emissions from grinding operations accelerates wet-cutting system retrofits in Detroit-area automotive supplier facilities. Defense contractors in California and Texas qualify diamond-reinforced ceramic matrix composites for next-generation radar-transparent aerospace radomes.
China
GB standards enforcement through SAMR tightens synthetic diamond purity classifications for export-grade chemical vapor deposition wafers. Dual carbon goals elevate furnace energy intensity requirements across Henan province production clusters. Zhengzhou and Luoyang synthetic diamond growers expand direct contracting channels with Taiwan and South Korean semiconductor packaging houses.
Germany
REACH authorization restrictions on hexavalent chromium plating redirect automotive powertrain machining toward diamond-coated tooling compliance pathways. Stuttgart and Turin tooling distributors restructure inventory mixes to prioritize superhard material specifications. Bavaria-based Tier-1 suppliers migrate polycrystalline diamond compact inserts from mechanical clamping to direct brazed interfaces.
Japan
Precision electronics manufacturers specify synthetic diamond substrates for thermal management in high-performance computing stacks. METI guidance shapes domestic procurement standards for semiconductor packaging materials. Osaka and Nagoya industrial clusters develop ceramic matrix integration capabilities for satellite communications radome applications.
India
PLI scheme incentives for domestic electronics manufacturing create captive demand for thermal management substrate fabrication. CDSCO alignment with international purity standards shapes import eligibility for synthetic diamond materials. Gujarat and Karnataka packaging facilities establish qualification pathways for chemical vapor deposition wafer sourcing.
Industrial Diamond Market Key Industry Players
Integrated mining conglomerates and specialized synthetic material producers split the market into distinct capability tiers. Natural diamond extraction from Siberian kimberlite pipes competes with reproducible lattice structures from chemical vapor deposition growth for aerospace bearing and thermal management applications respectively. Three strategic archetypes dominate: diversified mining houses with synthetic subsidiaries, furnace-scale Chinese producers, and precision deposition specialists. Competitive moves concentrate on capacity expansion in Henan province and technology licensing for semiconductor-grade specifications.
Within the diversified mining house tier, De Beers and ALROSA occupy positions anchored by geological scarcity certification for specialized aerospace applications. Element Six UK Ltd. exemplifies the synthetic subsidiary archetype, while Henan Huanghe Whirlwind Co. Ltd. represents furnace-scale Chinese production concentration.
| Leading Market Players |
|---|
| De Beers |
| ALROSA |
| Applied Diamond, Inc. |
| Industrial Diamond Laboratories, Inc. |
| Morgan Advanced Materials |
| Scio Diamond Technology Corporation |
| Element Six UK Ltd. |
| Sumitomo Electric Industries Ltd. |
| Henan Huanghe Whirlwind Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Henan province's furnace capacity expansion is compressing lead times for chemical vapor deposition wafers while eroding pricing power among intermediate substrate fabricators. Taiwan and South Korean semiconductor packaging houses now source thermal spreaders directly from Zhengzhou and Luoyang growers, bypassing traditional distribution layers that once captured margin.
Pricing Analysis
REACH authorization restrictions dictate the pricing tier structure for European automotive tooling, separating diamond-coated inserts from legacy hexavalent chromium alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and thermal conductivity specifications. Cost compression in furnace-scale synthetic production is intensifying because Henan capacity expansion outpaces specification-driven demand growth. Electronics manufacturers show least price sensitivity for semiconductor-grade thermal substrates, while construction abrasives buyers remain highly price-sensitive.
Supply Chain Analysis
Export control regimes on microwave plasma reactor technology limit Western equipment flows into Chinese chemical vapor deposition expansion. Supply concentrates in China, Russia, and Botswana for distinct material categories—synthetic wafers, natural aerospace bearings, and industrial grit respectively. Raw material dependencies include high-purity methane feedstock, tungsten carbide substrate blanks, and rare-earth-doped microwave generators. Single-source vulnerability runs through Henan province for thermal spreader procurement. Distribution runs through AS9100-qualified distributors for aerospace and direct contracting for semiconductor packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized reactor operation skills—combining microwave engineering with crystallography—constrain talent pipelines and create defendable positions for incumbents who secure technical workforces. This scarcity dynamic shapes competitive strategy across the value chain.
For Market Incumbents: Pre-empt cubic boron nitride substitution in mid-tier cutting tools by accelerating direct-brazed polycrystalline diamond compact interface adoption. Lock automotive OEMs into proprietary substrate geometries before REACH enforcement peaks. Backward integration into high-purity methane purification secures feedstock cost advantage against Henan furnace expansions. For New Entrants and Emerging Players: Build out ceramic matrix composite capabilities for aerospace radome applications, where defense qualification timelines protect early movers from rapid commoditization. India's PLI scheme for electronics manufacturing offers the most penetrable entry point for thermal management substrate fabrication. Partner with Gujarat packaging facilities to establish qualification pathways ahead of CDSCO alignment completion. For Investors and Strategic Acquirers: Long-term, this sits as a materials-science consolidation play because furnace-scale efficiency gains and deposition precision advances favor capital-intensive operators with captive technical talent. Target acquisition archetypes: precision chemical vapor deposition specialists with semiconductor-grade certification and established foundry relationships. Watch for inflection in carbon border adjustment implementation across European import channels.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Henan province furnace additions compress lead times for thermal management substrates. |
| Backward Integration | Methane purification capture reduces feedstock cost exposure for synthetic diamond growers. |
| Technology Licensing | Semiconductor-grade chemical vapor deposition specifications transfer through equipment partnerships. |
| Long-term Supply Agreement | Taiwan and South Korean packaging houses lock thermal spreader volumes through direct contracts. |
| Joint Venture | Defense contractors co-develop ceramic matrix composites for radar-transparent aerospace radomes. |
Research Approach
Cross-validation between primary interviews with furnace operators and secondary trade data anchors the qualitative findings. Stakeholder roles engaged include chemical vapor deposition reactor engineers, semiconductor packaging procurement managers, automotive Tier-1 tooling buyers, and aerospace materials qualification specialists. Secondary sources comprise customs records for synthetic diamond wafer flows, SAMR GB standards filings, EPA abrasive particulate monitoring reports, and REACH authorization documentation. Bottom-up capacity modeling triangulates against top-down end-use demand segmentation.
Calibration against historical price trajectories for polycrystalline diamond compact inserts and thermal conductivity specification premiums shapes the analytical framework. Segmentation dimensions span material origin, product type, end-use industry, and application process. CAGRs derive from installed capacity expansion rates cross-referenced with specification-driven demand elasticity. Forecast inputs include furnace energy intensity standards under China's dual carbon goals and semiconductor packaging substrate stack evolution.
Sensitivities concentrate around carbon border adjustment implementation timing and microwave plasma reactor technology transfer restrictions. Forecasts reflect documented assumptions on Henan capacity expansion schedules and REACH enforcement phasing. Material shifts in semiconductor thermal management architecture or aerospace bearing certification requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Industrial Salts Market
Industrial Minerals
Mineral Salt Ingredients Market
Industrial Minerals
Inorganic Salts Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Snowflake Salt Market
Industrial Minerals
Potassium Schoenite Market
Industrial Minerals
Caustic Calcined Magnesite Market
Industrial Minerals
Slate Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Global Cristobalite Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Limestone Mill Market
Industrial Minerals
Pyrophyllite Market
Industrial Minerals
Mineral Enrichment Ingredients Market
Industrial Minerals
Nepheline Market
Industrial Minerals
Asia Pacific Bentonite Market