
 Tooling Board Market | 2026-2036
Tooling Board Market Size, Share, and Industry Trends Forecast 2026-2036
Tooling Board Market Intelligence
Buyer concentration in automotive prototyping is decoupling from traditional tier-one supplier dominance as electric vehicle startups and aerospace contractors fragment procurement across specialized fabricators. Huntsman Corporation leverages its epoxy formulation expertise to anchor European aerospace programs. Coastal Enterprises sustains domestic manufacturing scale for CNC-machinable polyurethane boards serving North American tool shops. RAMPF Group competes through specialized high-temperature tooling board grades for autoclave applications.
Tooling boards are rigid, machinable substrates engineered from polyurethane, epoxy, or phenolic resin systems with densities ranging from 4 lb/ft³ to 50 lb/ft³, serving primarily as master patterns, prototype molds, and checking fixtures in manufacturing development cycles. Polyurethane formulations dominate volume consumption due to their balance of machinability and cost, while epoxy grades command premium positioning in aerospace autoclave tooling where thermal stability exceeds 350°F. CNC Machining remains the prevailing production method, though 3D Printing is displacing subtractive workflows for complex geometries in electronics prototyping.
EPA industrial chemical regulations constrain phenolic resin emissions in U.S. manufacturing facilities, while REACH restricts isocyanate handling across European board production plants. ECHA substance evaluations are forcing reformulation timelines that compress supplier R&D cycles. Stakeholders must monitor regulatory divergence between EPA and REACH chemical frameworks when siting new production capacity or qualifying export grades.
Market Dynamics
REACH chemical restrictions are forcing polyurethane tooling board reformulation across European production plants, compressing supplier R&D timelines while creating first-mover advantages for low-emission formulation specialists.
Growth Catalysts
- Aerospace Prototyping Expansion:Commercial aircraft development programs are consuming higher volumes of high-temperature epoxy tooling boards for autoclave-cured composite molds.
- REACH Compliance Deadlines:ECHA substance evaluations are accelerating substitution toward low-emission polyurethane systems in German automotive tooling clusters.
- Electric Vehicle Tooling Surge:Battery enclosure prototyping and lightweight body panel development are fragmenting procurement across specialized fabricators serving EV startups.
Market Restraints
- Isocyanate Feedstock Volatility:Polyurethane board production faces input cost pressure from methylene diphenyl diisocyanate supply concentration in Northeast Asian chemical complexes.
- Phenolic Resin Emission Controls:EPA industrial chemical regulations constrain U.S. manufacturing facility expansion for high-density phenolic tooling grades.
- Epoxy Thermal Performance Ceiling:Aerospace autoclave tooling demands exceeding 350°F operational limits expose material degradation risks in extended cure cycles.
Strategic Opportunities
- India Automotive Tooling:PLI scheme incentives for domestic electric vehicle manufacturing are creating demand for imported polyurethane master pattern boards.
- 3D Printing Convergence:Fused filament fabrication of soluble support structures is expanding into hybrid workflows combining additive deposition with CNC-machined substrates.
- CSRD-Driven Sustainability Reporting:EU corporate sustainability disclosure requirements are creating procurement preference for bio-based polyurethane formulations with verified carbon footprints.
Industry Challenges
- CNC Programming Talent Scarcity:Complex five-axis machining of low-density polyurethane boards requires specialized CAM expertise concentrated in aging German and Japanese tool shops.
- Autoclave Qualification Timelines:Aerospace OEM certification of new tooling board grades demands 18-24 month thermal cycling validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tooling Board Market |
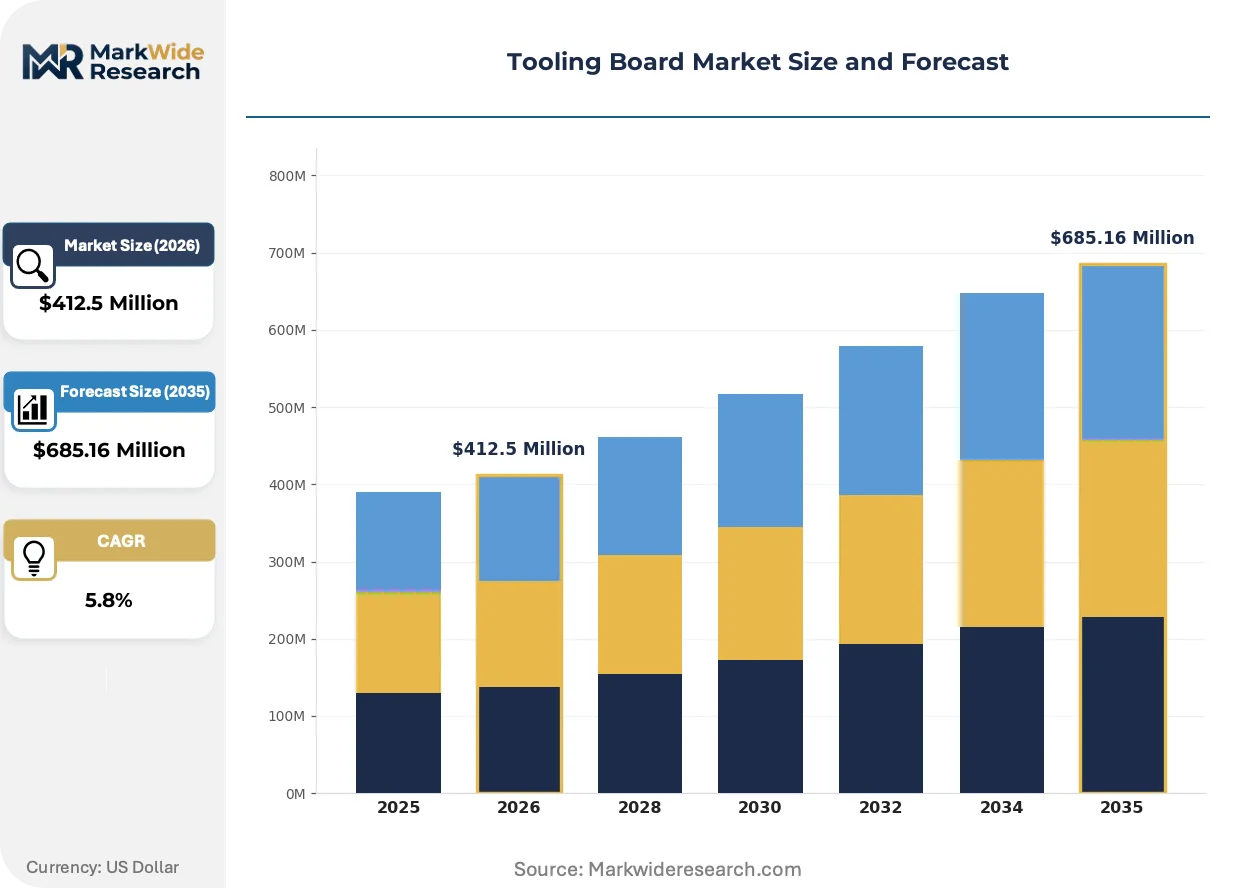
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic, Epoxy, Polyurethane, Acrylic Application: Automotive, Aerospace, Electronics, Construction Production Method: CNC Machining, Injection Molding, Casting, 3D Printing End User: Manufacturers, Suppliers, Fabricators, Engineers |
| Companies Covered | Trelleborg AB, Coastal Enterprises, Huntsman Corporation, BCC Products, Base Group, Sika AG, General Plastics Manufacturing Company, Alro Plastics, RAMPF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tooling Board Market Strategic Shifts & Innovations
Workflow digitization and materials informatics are compressing the traditional master pattern-to-mold development cycle, enabling faster iteration in automotive and aerospace prototyping programs.
High-temperature epoxy tooling boards are expanding into next-generation urban air mobility vehicle development, where electric vertical takeoff aircraft manufacturers require autoclave-stable molds for thermoplastic composite fuselage sections. These programs demand thermal stability beyond standard polyurethane capabilities. The technology is expanding into previously unserved segments of the advanced air mobility supply chain.
REACH restrictions on isocyanate handling are forcing reformulation of polyurethane tooling board production processes across European manufacturing plants. Industrial consequence includes accelerated R&D spending on bio-based polyol alternatives and closed-loop casting systems. German automotive tooling clusters around Stuttgart are responding fastest, with several fabricators already qualifying low-emission grades for series production.
Buyer concentration in automotive prototyping is fragmenting as electric vehicle startups and aerospace contractors bypass traditional tier-one supplier networks. Direct procurement relationships with specialized board fabricators are replacing consolidated purchasing through major mold-making groups. This pattern is most visible in Southern California and Saxony, where EV and urban air mobility engineering centers cluster near specialized machining shops.
Tooling Board Market Segmentation
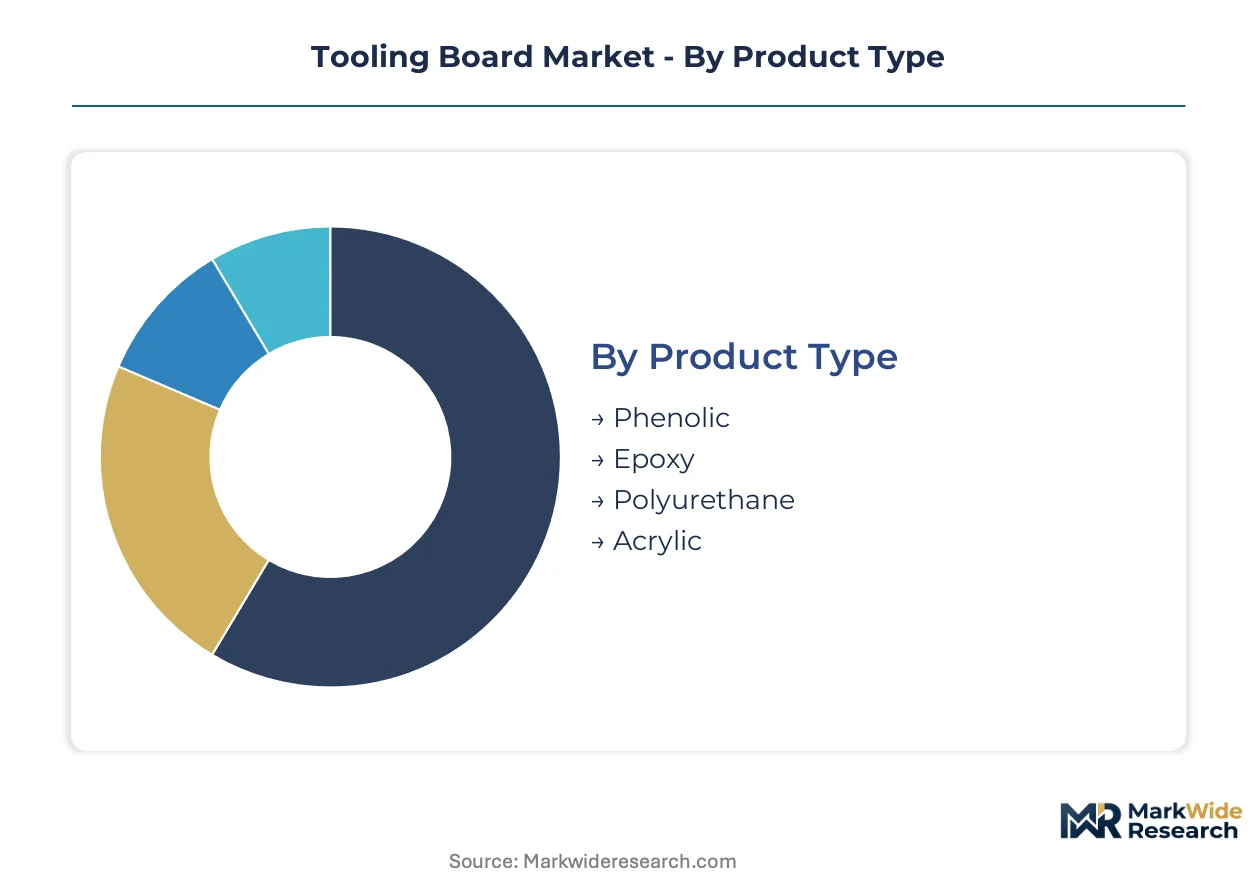
Tooling board procurement patterns diverge sharply across resin chemistry and fabrication workflows. Understanding these splits reveals where capital deployment concentrates and which customer segments drive premium formulation development.
Product Type:
Capital intensity escalates from commodity polyurethane casting systems through aerospace-grade epoxy autoclave tooling requiring extended thermal cycling validation.
- Polyurethane:Low-density cellular structures dominate volume consumption through CNC-machinable master patterns. German automotive clusters around Stuttgart and Wolfsburg concentrate procurement for prototype mold fabrication, with REACH compliance deadlines accelerating reformulation toward low-emission polyol systems.
- Epoxy:High-temperature grades withstand autoclave cure cycles exceeding 350°F for composite aerospace tooling. Commercial aircraft development programs and emerging urban air mobility manufacturers in Southern California specify these formulations for thermoplastic fuselage molds.
- Phenolic:Dense boards serve checking fixtures and metal-forming dies where dimensional stability under mechanical load matters. EPA emission controls constrain U.S. capacity expansion for this chemistry.
- Acrylic:Transparent variants enable optical alignment fixtures and light-transmission testing setups in electronics prototyping workflows.
Most installed capacity flows through polyurethane systems. Expansion is steepest in epoxy grades serving autoclave applications.
Application:
End-use concentration determines margin structure, with aerospace qualification timelines supporting premium pricing against automotive volume plays.
- Automotive:Battery enclosure prototyping and lightweight body panel development for electric vehicle programs fragment procurement across specialized fabricators. India's PLI scheme incentives are creating import demand for polyurethane master pattern boards.
- Aerospace:Autoclave-cured composite molds require thermal stability beyond standard polyurethane capabilities. OEM certification protocols demand 18-24 month validation cycles that lock in supplier relationships.
- Electronics:Complex geometries in device prototyping are displacing subtractive workflows toward hybrid additive-CNC approaches using soluble support structures.
- Construction:Architectural formwork and decorative mold reproduction utilize lower-density grades where surface finish tolerance relaxes.
Procurement volume concentrates in automotive prototyping. Climbing the fastest are aerospace programs with extended tooling qualification horizons.
Production Method:
Workflow digitization is compressing traditional master pattern-to-mold development cycles across subtractive and additive platforms.
- CNC Machining:Five-axis milling of low-density polyurethane boards demands specialized CAM expertise concentrated in aging German and Japanese tool shops. Talent scarcity constrains throughput expansion.
- 3D Printing:Fused filament fabrication of soluble support structures is expanding into hybrid workflows combining additive deposition with machined substrates for electronics prototyping.
- Injection Molding:Limited to high-volume standardized inserts where tooling board serves as prototype validation before steel mold commitment.
- Casting:Open-pour and closed-loop systems produce near-net-shape blocks requiring finish machining, with European plants reformulating for REACH-compliant isocyanate handling.
Capacity utilization peaks in CNC machining. Gaining share fastest are hybrid additive-subtractive workflows.
End User:
Buyer concentration is fragmenting as electric vehicle startups and aerospace contractors bypass traditional tier-one supplier networks.
- Manufacturers:OEM in-house tool shops maintain captive machining capacity for sensitive prototype programs, particularly in German automotive and U.S. urban air mobility clusters.
- Fabricators:Specialized board machining shops in Southern California and Saxony are capturing direct procurement relationships from EV and advanced air mobility engineering centers.
- Suppliers:Consolidated mold-making groups face margin pressure as procurement decentralizes toward specialized machining shops with formulation expertise.
- Engineers:Design validation teams specify checking fixtures and dimensional control tooling with tight tolerance requirements.
Transaction volume flows through fabricators. Steepest expansion trajectory belongs to direct manufacturer procurement bypassing intermediary tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates automotive tooling board procurement while the United States fragments demand across aerospace and electric vehicle startups. Chemical regulatory divergence between REACH and EPA frameworks reshapes supplier positioning across both markets.
United States
Urban air mobility manufacturers in Southern California and aerospace contractors in the Pacific Northwest drive epoxy tooling board consumption for autoclave-cured composite molds. EPA industrial chemical regulations constrain phenolic resin emissions in domestic manufacturing facilities. Specialized machining shops in Greater Los Angeles capture direct procurement relationships from advanced air mobility engineering centers.
Germany
Automotive prototyping programs around Stuttgart and Wolfsburg consume polyurethane master pattern boards for electric vehicle battery enclosures and lightweight body panels. REACH compliance deadlines accelerate reformulation toward low-emission polyol systems across Baden-Württemberg fabrication plants. ECHA substance evaluations compress supplier R&D timelines while creating first-mover advantages for compliant formulation specialists.
China
Commercial aircraft development programs and domestic EV tooling expansion sustain demand for high-temperature epoxy grades and CNC-machinable polyurethane substrates. MIIT industrial standards govern chemical emissions in board production facilities across the Yangtze River Delta. Tooling fabricators in Shanghai and Jiangsu province scale hybrid additive-subtractive workflows for electronics prototyping applications.
India
PLI scheme incentives for domestic electric vehicle manufacturing create import demand for polyurethane master pattern boards in prototype mold fabrication. BIS quality standards regulate tooling material specifications for automotive supplier qualification. Specialized fabricators in Maharashtra and Tamil Nadu establish direct procurement channels with EV startup engineering teams bypassing traditional tier-one networks.
Japan
Aerospace subcontractor networks and precision electronics manufacturers sustain demand for high-density phenolic checking fixtures and dimensional control tooling. METI industrial policy supports advanced materials development in tooling applications. Aging CNC programming expertise concentrates in Nagoya and Osaka tool shops, constraining throughput expansion for complex five-axis machining operations.
Tooling Board Market Key Industry Players
German producers anchor one tier; North American specialists hold differentiated positions in aerospace-grade formulations. The vendor base stratifies across three structural tiers: integrated resin compounders with captive board production, independent fabrication shops with formulation expertise, and regional distributors serving prototype-driven demand. Two strategic archetypes dominate competitive positioning: low-emission polyurethane specialists capturing REACH compliance premiums, and high-temperature epoxy formulators locking in aerospace qualification timelines. Capacity expansion and geographic licensing agreements represent the dominant competitive moves across both tiers.
Within the integrated compounder tier, Huntsman Corporation and Sika AG exemplify resin-to-board vertical positioning, while Coastal Enterprises occupies a distinct geography-focused fabrication role. RAMPF Group represents the specialized high-temperature grade archetype serving autoclave applications. These three anchors illustrate how supplier positioning diverges between chemical formulation depth and machining proximity to end-use clusters.
| Leading Market Players |
|---|
| Trelleborg AB |
| Coastal Enterprises |
| Huntsman Corporation |
| BCC Products |
| Base Group |
| Sika AG |
| General Plastics Manufacturing Company |
| Alro Plastics |
| RAMPF Group |
| Others |
Cost & Logistics Intelligence
CNC programming expertise concentrated in aging German and Japanese tool shops widens labor-cost differentials between premium aerospace-grade epoxy boards and economy polyurethane master patterns.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for CNC-machinable polyurethane substrates. Three-tier pricing structure across premium aerospace epoxy, standard automotive polyurethane, and economy construction-grade phenolic separates thermal stability certification tiers. Cost compression in commodity polyurethane runs through methylene diphenyl diisocyanate feedstock volatility from Northeast Asian chemical complexes. Electric vehicle startups exhibit highest price sensitivity, while aerospace OEMs prioritize thermal cycling qualification over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with isocyanate supply concentration in Northeast Asian chemical complexes feeding European and North American board production. Manufacturing gravity centers on Germany, China, and the United States for finished board fabrication. Raw material flows draw from petrochemical feedstocks, specialized polyol formulations, and high-purity epoxy resin systems. Tariff exposure on isocyanate imports threatens margin stability for European polyurethane casters. Distribution runs through specialized fabrication shops capturing direct procurement from advanced air mobility engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical restrictions function as a regulatory compounder, with ECHA substance evaluation deadlines forcing accelerated R&D investment in low-emission polyurethane systems.
For Market Incumbents: To counter feedstock volatility from Northeast Asian isocyanate supply concentration, deepen backward integration into captive polyol blending capacity and secure long-term offtake agreements with German automotive tooling clusters. Anchor customer relationships through 18-24 month autoclave qualification partnerships that lock out substitute suppliers. For New Entrants and Emerging Players: The price-point gap between premium aerospace epoxy and economy construction phenolic creates entry space for mid-tier polyurethane specialists serving India's PLI-scheme EV tooling demand. Target Maharashtra and Tamil Nadu fabrication markets with REACH-compliant low-emission formulations. Establish direct procurement channels with EV startup engineering teams bypassing tier-one mold-making groups. For Investors and Strategic Acquirers: Resin compounders with captive board production are the most active acquirer in this space, seeking machining proximity to Southern California urban air mobility clusters. Five-to-ten year viability hinges on regulatory compliance capabilities rather than scale alone. Monitor ECHA substance evaluation timelines as the critical inflection signal for formulation obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | Low-emission polyurethane R&D captures first-mover premiums in Stuttgart automotive clusters. |
| Autoclave Qualification Partnership | Extended thermal cycling validation locks supplier relationships with Boeing and Airbus tier networks. |
| Hybrid Additive-Subtractive Workflow | Fused filament fabrication integration serves electronics prototyping demand in Shanghai and Jiangsu. |
| India Distribution Expansion | Direct channels to Maharashtra EV startups bypass consolidated mold-maker procurement layers. |
| Bio-Based Polyol Development | CSRD-driven sustainability reporting creates procurement preference for verified carbon footprint boards. |
Research Approach
Bottom-up automotive and aerospace prototyping modeling reconciled against top-down resin compounding capacity tracking forms the analytical core. Primary interviews with tooling board plant managers, procurement leads at German automotive OEMs, specialized fabrication shop owners, and technical R&D directors at resin suppliers combined with secondary validation from ECHA substance evaluation databases, EPA industrial chemical filings, and customs trade data. Triangulation across these sources anchors volume estimates.
Historical trendline analysis of polyurethane and epoxy grade consumption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include resin chemistry tier, end-use industry application, production method workflow, and regional regulatory cluster. CAGRs derived from weighted average of demand elasticity coefficients and capacity expansion announcements. Forecast inputs incorporated REACH compliance deadline impacts and PLI scheme incentive effects on import demand.
Caveats apply where ECHA evaluation timeline accelerations or isocyanate supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and aerospace program continuation without specific contract visibility. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Powder Processing Service Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Japan Engineering Plastics Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Flat Enameled Wires Market
Industrial Materials
Middle-East and Africa Engineering Plastics Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Fiberglass Tanks Market
Industrial Materials
HV Glass Insulator Market
Industrial Materials
Cork Material Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Industrial Standoff and Spacer Market
Industrial Materials
Couplings Market