
 Global Ophthalmic Viscoelastic Devices Market | 2026-2036
Global Ophthalmic Viscoelastic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ophthalmic Viscoelastic Devices Market Foresight
Modular packaging of viscoelastic agents with pre-loaded injector systems is hardening as the dominant procurement format for ambulatory surgical centers. Alcon leverages its integrated cataract platform to bundle cohesive and dispersive agents with phacoemulsification consoles. Johnson & Johnson Vision anchors its position through proprietary viscoadaptive formulations optimized for microincisional techniques. Haohai Biological Technology competes on manufacturing scale, supplying sodium hyaluronate raw material to multiple finished-device labels across Asia-Pacific markets.
Ophthalmic viscoelastic devices comprise sterile, injectable formulations of hyaluronic acid, chondroitin sulfate, or hydroxypropyl methylcellulose with molecular weights ranging from 500 kDa to 4 MDa, engineered to maintain anterior chamber depth and protect corneal endothelium during intraocular manipulation. Cohesive agents dominate value capture due to their higher unit pricing and essential role in phacoemulsification, while dispersive segments sustain volume leadership in complex cases requiring endothelial coating. Pre-filled syringes are displacing single-use vials as the fastest-growing delivery mode, driven by OR efficiency protocols and reduced contamination risk.
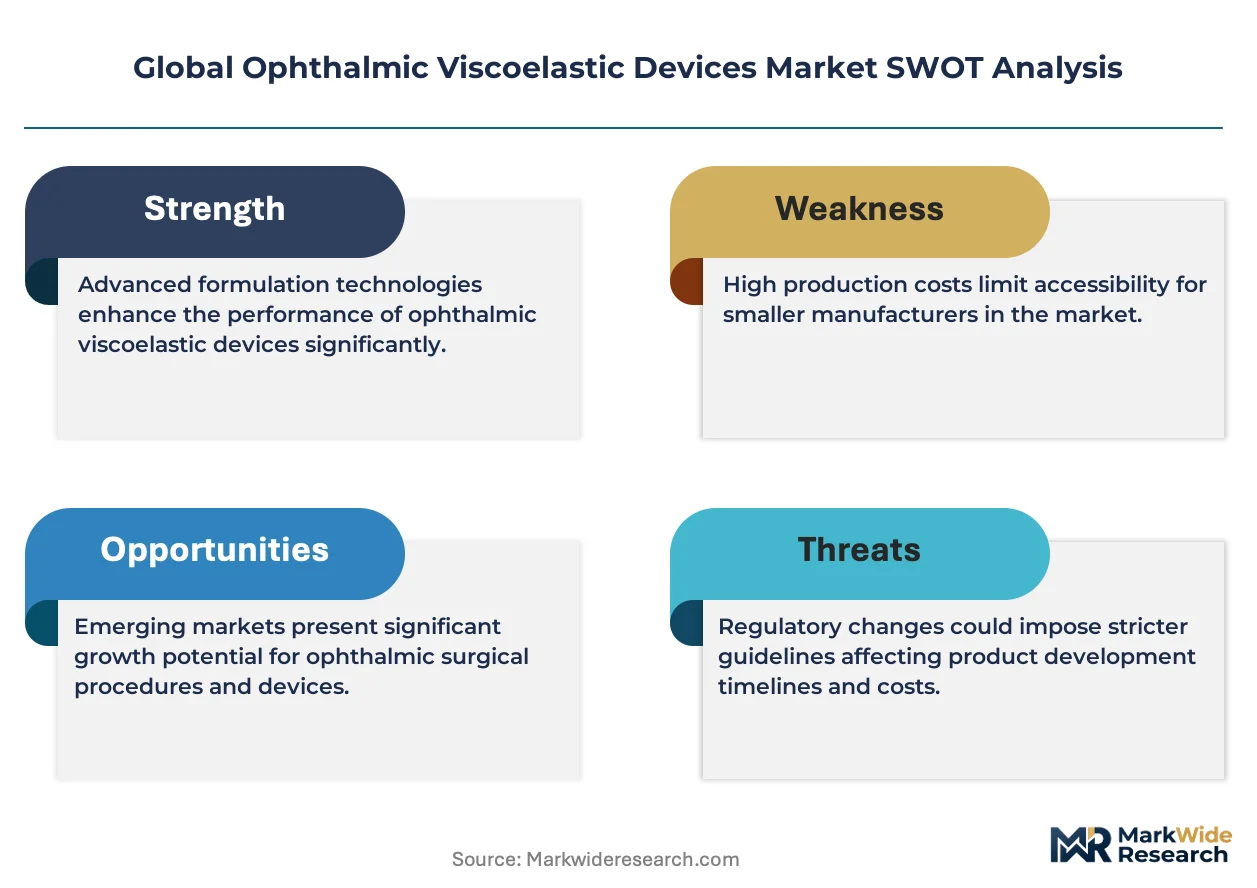
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and sterilization validation burdens for manufacturers seeking transatlantic market access. Japan's PMDA imposes additional lot-release testing for biological origin materials, creating a differentiated compliance threshold for hyaluronate-based devices. Stakeholders must monitor evolving reimbursement banding for premium viscoadaptive formulations versus standard cohesive products, as payer categorization will determine margin sustainability independent of clinical differentiation.
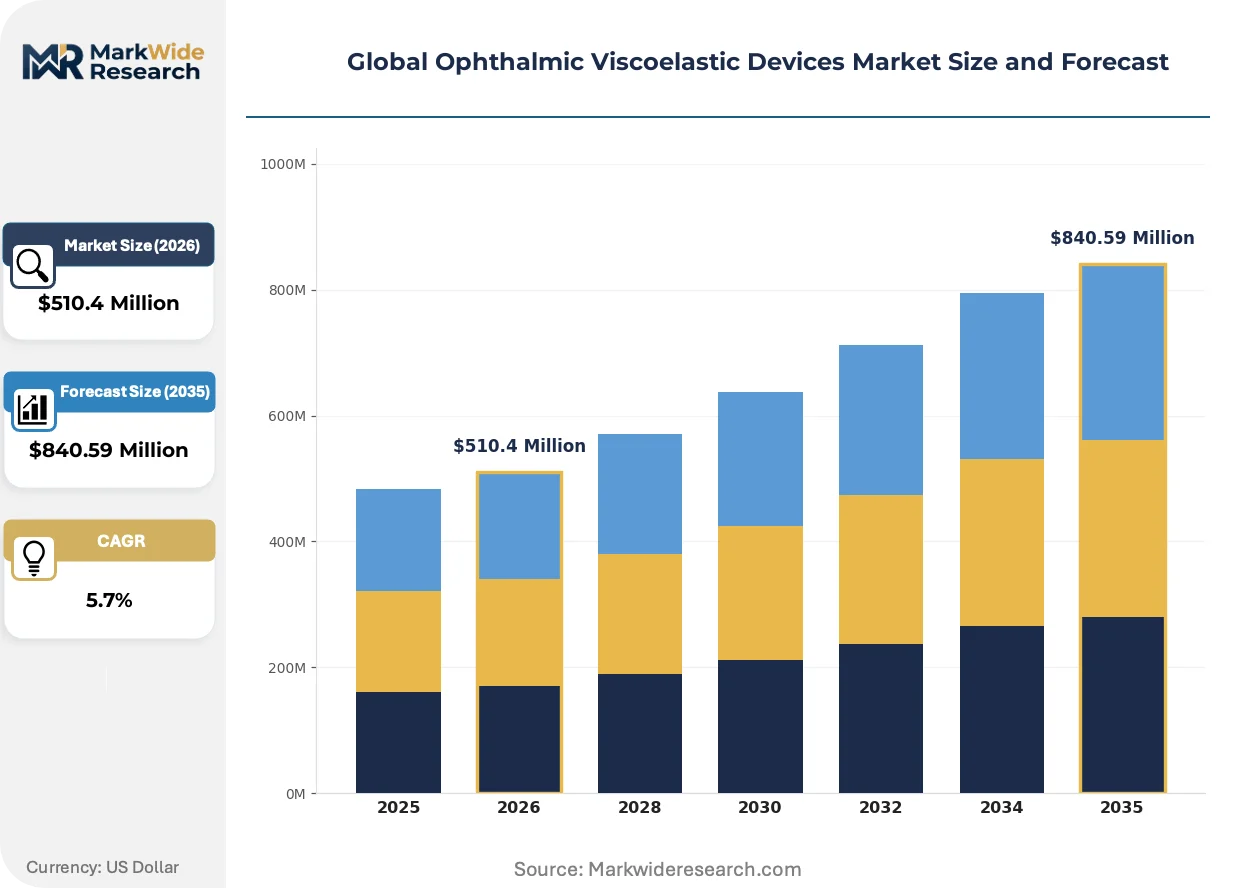
Market Dynamics
Pre-loaded injector systems are consolidating procurement decisions around integrated surgical platforms, forcing standalone viscoelastic suppliers to demonstrate compatibility with dominant phacoemulsification consoles or risk channel exclusion.
Growth Catalysts
- Aging demographics:Cataract surgery volumes in Germany, Japan, and the United States expand the addressable patient pool for anterior chamber maintenance products.
- EU MDR implementation:Stricter biocompatibility documentation requirements for hyaluronic acid formulations favor manufacturers with established sterilization validation capabilities.
- Microincisional techniques:Adoption of sub-2.2 mm phacoemulsification incisions drives demand for viscoadaptive formulations with dual cohesive-dispersive properties.
Market Restraints
- Raw material concentration:Sodium hyaluronate supply chains cluster in specific Asia-Pacific manufacturing zones, creating single-source vulnerability for finished-device labels.
- Rooster bio-origin constraints:Japan's PMDA imposes additional lot-release testing timelines for avian-derived hyaluronate, extending market entry cycles by 8-14 months.
- Balanced salt solution substitution:Cost-conscious ambulatory centers in select markets deploy irrigating solutions for uncomplicated cases, compressing viscoelastic utilization per procedure.
Strategic Opportunities
- Brazil's ANVISA pathway:Streamlined registration for CE-marked devices creates expedited access to Latin America's largest ophthalmic surgical volume.
- Femtosecond laser integration:Convergence of laser capsulotomy systems with cohesive viscoelastic delivery opens premium positioning for automated injection modules.
- Direct-to-ASC distribution:Bypassing traditional distributor networks in the United States captures margin previously allocated to intermediaries.
Industry Challenges
- Sterilization validation capacity:Gamma and e-beam irradiation expertise for high-molecular-weight hyaluronate concentrates among limited contract manufacturers.
- Legacy phaco console compatibility:Ensuring syringe luer-lock dimensions match proprietary injector interfaces across Alcon, Johnson & Johnson Vision, and Bausch + Lomb platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ophthalmic Viscoelastic Devices Market |
| Market Size in 2026 | $510.4 Million |
| Market Size in 2035 | $840.59 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersive, Cohesive, Combined, Viscoadaptive Therapy Area: Cataract Surgery, Glaucoma Treatment, Corneal Transplant, Retinal Procedures End User: Ophthalmic Clinics, Specialty Surgery Centers, Eye Hospitals, Ambulatory Surgical Centers Delivery Mode: Pre-filled Syringes, Single-use Vials, Multi-dose Containers, Sterile Kits |
| Companies Covered | Carl Zeiss Meditec, Bohus Biotech, Alcon, Abbott Medical Optics, Rumex International, Johnson & Johnson Vision, Rayner, Haohai Biological Technology, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ophthalmic Viscoelastic Devices Market Shifts & Advancements
Viscoelastic formulation engineering is converging with surgical automation, creating demand for devices that communicate fill volume and injection pressure data directly to phacoemulsification system dashboards.
Dual-chamber syringe designs are unifying cohesive and dispersive agents in a single delivery system, enabling intraoperative viscosity switching without instrument exchange. Ambulatory surgical centers in the United States and Germany are standardizing these configurations to reduce OR turnover time. The technology is unifying previously separate SKUs into bundled procedure kits, compressing supplier negotiation leverage for standalone cohesive or dispersive products.
EU MDR Annex I general safety and performance requirements are extending clinical evidence obligations to legacy hyaluronic acid devices previously cleared under the Medical Devices Directive. Manufacturers must generate post-market clinical follow-up data or risk certificate suspension. High-viscosity cohesive segments face the heaviest documentation burden, prompting some labels to narrow product ranges ahead of notified body audits.
Surgeon preference data is driving purchasing committee decisions at multi-site ophthalmology platforms, displacing traditional materials management-led procurement. Integrated delivery networks in the United States now mandate viscoelastic compatibility with their captive phacoemulsification fleets. This concentration is most visible in metropolitan surgical markets where three to five platforms control over half of cataract procedure volume.
Global Ophthalmic Viscoelastic Devices Market Segmentation
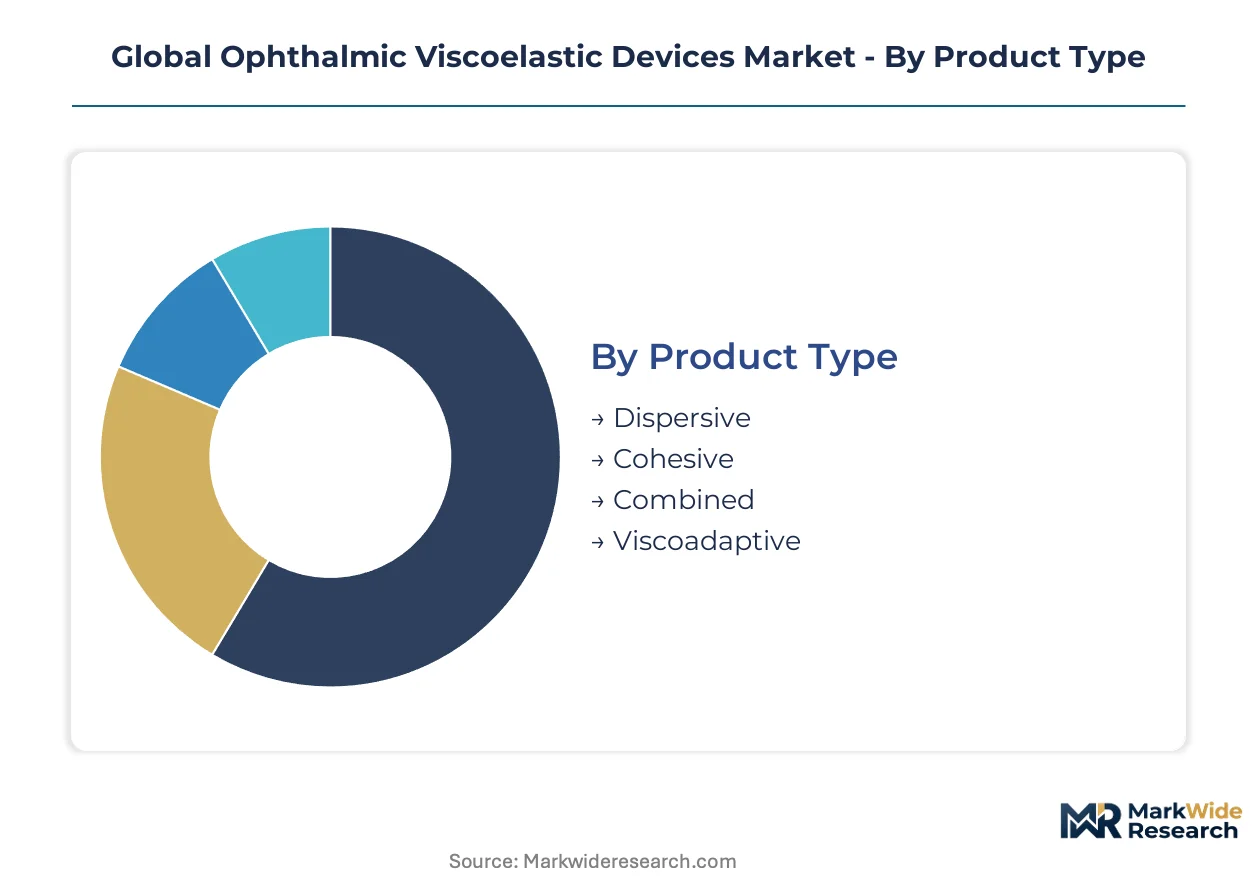
Viscoelastic device segmentation reveals how formulation chemistry, surgical application, and delivery format intersect to determine procurement patterns. Manufacturers configure product portfolios across these dimensions to secure shelf space in integrated surgical platforms.
Product Type:
Supply concentration for high-molecular-weight hyaluronate raw material shapes competitive positioning across formulation categories.
- Cohesive:High-viscosity hyaluronic acid formulations above 2 MDa molecular weight maintain anterior chamber depth during phacoemulsification. Demand clusters in the United States and Germany where premium cataract surgery volumes sustain higher unit pricing for these essential agents.
- Dispersive:Lower-viscosity formulations coat corneal endothelium during complex procedures requiring extended protection. Adoption concentrates in Japan's academic medical centers where PMDA lot-release protocols for avian-derived materials create differentiated supply timelines.
- Combined:Dual-chamber systems unify cohesive and dispersive properties in single delivery configurations.
- Viscoadaptive:Shear-thinning formulations engineered for sub-2.2 mm microincisional techniques.
Today's leader: Cohesive. Tomorrow's challenger: Viscoadaptive.
Therapy Area:
Procedure reimbursement banding determines margin sustainability across clinical applications.
- Cataract Surgery:Phacoemulsification procedures consume the majority of anterior chamber maintenance products globally. Volume concentrates in aging populations across the United States, Japan, and Germany where surgical conversion rates exceed thresholds for sustained device utilization.
- Corneal Transplant:Penetrating keratoplasty and endothelial keratoplasty procedures require specialized endothelial protection protocols. Demand localizes in tertiary eye hospitals across France and the United Kingdom where corneal subspecialization supports premium formulation uptake.
- Glaucoma Treatment:Trabeculectomy and minimally invasive glaucoma surgery applications.
- Retinal Procedures:Vitrectomy and membrane peeling applications requiring tamponade adjuncts.
Cataract Surgery commands current volume. Corneal Transplant offers steepest expansion trajectory.
End User:
Procurement centralization intensity varies dramatically across facility types.
- Ambulatory Surgical Centers:United States-based ASCs consolidate purchasing through integrated delivery networks that mandate phacoemulsification console compatibility. OR efficiency protocols favor pre-loaded injector systems with standardized luer-lock dimensions.
- Eye Hospitals:Tertiary academic centers across Japan and Germany maintain captive sterilization validation capabilities supporting broader supplier qualification.
- Ophthalmic Clinics:Office-based surgical suites with limited procedure volumes.
- Specialty Surgery Centers:Multi-specialty facilities with ophthalmic service lines.
Ambulatory Surgical Centers dominate procurement leverage. Eye Hospitals preserve supplier diversification.
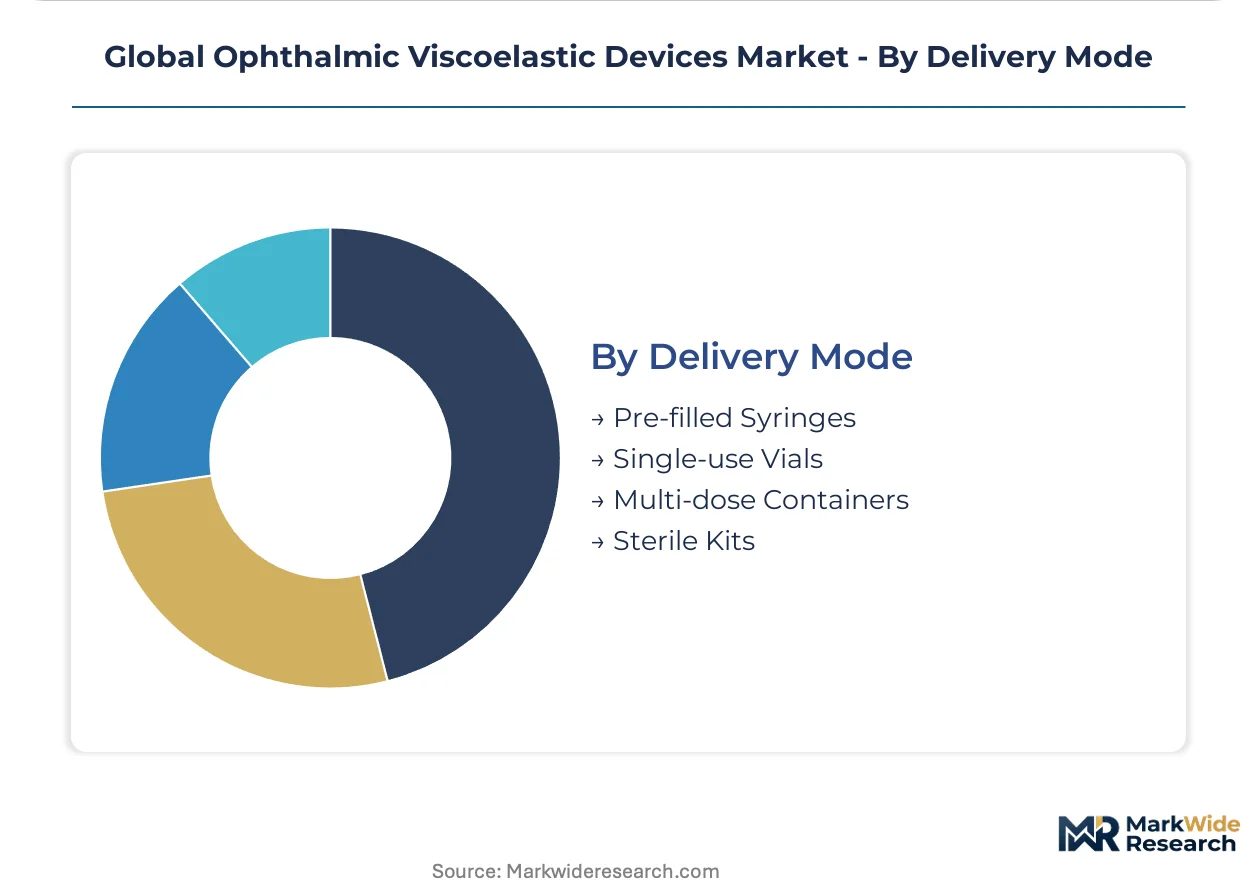
Delivery Mode:
Packaging format selection directly impacts contamination risk profiles and OR turnover metrics.
- Pre-filled Syringes:Sterile, ready-to-inject configurations displace traditional vials in efficiency-focused settings. Adoption accelerates in German and United States ASCs where reduced preparation time translates to measurable throughput gains.
- Single-use Vials:Legacy format retains presence in cost-sensitive markets and complex cases requiring custom aspiration.
- Multi-dose Containers:Institutional formats for high-volume surgical suites with validated aseptic technique.
- Sterile Kits:Bundled configurations with irrigation solutions and surgical accessories.
Pre-filled Syringes gain share fastest. Single-use Vials defend residual niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ophthalmic viscoelastic devices industry traces its commercial origins to European pharmaceutical chemistry and Japanese fermentation biotechnology, with subsequent scale-up occurring across North American surgical supply chains. Manufacturing of sodium hyaluronate raw material now clusters in specific Asia-Pacific zones, while finished-device formulation and sterilization concentrate in Germany, the United States, and Japan.
United States
Ambulatory surgical centers in metropolitan markets drive procurement volume for cohesive formulations. FDA 510(k) clearance pathways govern market entry timelines for hyaluronic acid devices. The Dallas-Fort Worth and Phoenix surgical corridors host concentrated cataract procedure volumes that sustain premium viscoelastic utilization.
Germany
Academic medical centers in Bavaria and Baden-Württemberg maintain high surgical conversion rates for aging populations. EU MDR Annex I requirements impose biocompatibility documentation burdens that favor established sterilization validation capabilities. The Tübingen-Stuttgart ophthalmic cluster anchors research translation for viscoadaptive formulations.
Japan
PMDA lot-release testing protocols for avian-derived hyaluronate extend market entry cycles for foreign suppliers. Tokyo and Osaka tertiary eye hospitals sustain demand for dispersive agents in complex endothelial protection scenarios. The Chubu region hosts fermentation-based sodium hyaluronate production for regional device labels.
China
Domestic manufacturers in Shandong and Jiangsu provinces supply raw material hyaluronate to multiple finished-device assemblers across Asia-Pacific. NMPA registration requirements for Class III medical devices shape local production investment patterns. The Yangtze River Delta concentration supports cost-competitive dispersive formulation output for export markets.
Brazil
ANVISA streamlined registration for CE-marked devices accelerates access to Latin America's largest cataract surgical volume. São Paulo and Rio de Janeiro ophthalmology platforms consolidate procurement for cohesive agents. Southeastern Brazil's private hospital networks sustain premium pricing for pre-loaded injector configurations.
Global Ophthalmic Viscoelastic Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and sterilization validation depth. The vendor base stratifies between integrated surgical platform owners, standalone viscoelastic specialists, and raw material suppliers. Three archetypes dominate: phacoemulsification console bundlers, dual-chamber delivery innovators, and fermentation-scale hyaluronate producers. Competitive moves center on pre-loaded injector compatibility certification and direct-to-ASC distribution channel development.
Among integrated platform owners, Alcon and Johnson & Johnson Vision occupy positions as archetypal console bundlers. Haohai Biological Technology exemplifies the fermentation-scale supplier archetype. These three entities represent distinct strategic vectors—surgical system integration, proprietary formulation engineering, and upstream raw material control—that collectively define competitive tension in procurement decisions.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Bohus Biotech |
| Alcon |
| Abbott Medical Optics |
| Rumex International |
| Johnson & Johnson Vision |
| Rayner |
| Haohai Biological Technology |
| Bausch + Lomb |
| Others |
Supply & Pricing Matrix
EU MDR Annex I biocompatibility documentation requirements gate qualified supply access and premium-tier pricing power for hyaluronic acid device manufacturers, compressing margins for labels lacking sterilization validation capabilities while rewarding compliant incumbents with sustained pricing leverage in German and United States surgical corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates viscoadaptive formulations from cohesive agents and commodity dispersive products, with price differentiation anchored in FDA 510(k) clearance tier and phacoemulsification console compatibility certification. Pricing pressure stems from balanced salt solution substitution in cost-conscious ambulatory surgical centers, eroding utilization per uncomplicated cataract procedure. Academic medical centers in Japan exhibit lowest price sensitivity due to PMDA-mandated lot-release protocols that constrain supplier switching, while Brazilian private hospital networks demonstrate highest sensitivity to pre-loaded injector premium positioning.
Supply Chain Analysis
Regional distribution centers in Frankfurt, Chicago, and Singapore orchestrate hub-and-spoke patterns for finished-device deployment, with geographic supply concentration in China's Shandong and Jiangsu provinces for sodium hyaluronate raw material, Germany's Tübingen-Stuttgart corridor for viscoadaptive formulation R&D, and Japan's Chubu region for fermentation-based biological production. Raw material dependencies center on avian-derived hyaluronate, high-molecular-weight concentrates above 2 MDa, and proprietary shear-thinning polymer additives. Single-source vulnerability in Asia-Pacific manufacturing zones for biological-origin sodium hyaluronate concentrates threatens supply continuity for finished-device labels without captive fermentation capacity. Distribution runs through GPO contracts in United States integrated delivery networks and direct-to-ASC channels displacing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's extended PMDA lot-release timelines and Brazil's ANVISA streamlined CE-mark recognition, enabling faster payback on regulatory investment for entrants targeting Latin American surgical volumes.
For Market Incumbents: Acquire sterilization validation assets and gamma irradiation expertise to defend against EU MDR certificate suspension risk and consolidate procurement leverage through pre-loaded injector compatibility certification across Alcon, Johnson & Johnson Vision, and Bausch + Lomb phacoemulsification platforms. Backward integration into sodium hyaluronate fermentation capacity insulates against single-source raw material vulnerability in Shandong manufacturing zones. For New Entrants and Emerging Players: Enter via dual-chamber delivery system white space in German and United States ambulatory surgical centers, where OR efficiency protocols drive fastest adoption of unified cohesive-dispersive configurations without instrument exchange. Brazil's private hospital networks in São Paulo and Rio de Janeiro offer the most penetrable geography given ANVISA expedited registration pathways for CE-marked devices. Pursue direct-to-ASC distribution bypassing traditional intermediaries to capture margin compression from GPO concentration. For Investors and Strategic Acquirers: Roll-up economics work for standalone viscoelastic specialists with captive sterilization validation because EU MDR Annex I clinical evidence obligations are forcing portfolio narrowing among labels lacking notified body audit readiness. Long-term viability across the analysis window favors targets with demonstrated phacoemulsification console compatibility and established direct-to-ASC channel relationships. Watch PMDA regulatory harmonization discussions as the signal indicating accelerated Japan market entry timelines for foreign suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Notified body audit readiness secures premium-tier pricing access in German surgical corridors. |
| Pre-loaded Injector Compatibility Program | Alcon and Johnson & Johnson Vision console certification prevents ASC procurement exclusion. |
| Direct-to-ASC Distribution Buildout | Bypassing GPO intermediaries captures margin previously allocated to distributor networks. |
| Dual-chamber Delivery System Launch | Unified cohesive-dispersive configurations reduce OR turnover time in efficiency-focused settings. |
| Fermentation Capacity Expansion | Captive sodium hyaluronate production insulates against Asia-Pacific single-source supply risk. |
Research Methodology
Multiple input streams — surgeon interviews at Tokyo and Osaka tertiary eye hospitals, procurement manager discussions at United States integrated delivery networks, and regulatory affairs consultations with EU MDR notified bodies — were reconciled against FDA 510(k) clearance databases, PMDA lot-release protocol documentation, and ANVISA registration filings to construct bottom-up procedure volume estimates and top-down market sizing for cohesive, dispersive, and viscoadaptive formulation segments.
Historical surgical volume trajectories in Germany, Japan, and the United States were cross-referenced against expert panel inputs from phacoemulsification console manufacturers and viscoelastic formulation specialists to derive expansion rates across the projection horizon, with segmentation modeling incorporating molecular weight tier, delivery mode configuration, end-user facility type, and regional regulatory cluster as primary dimensions. Cataract surgery conversion rates for aging populations and microincisional technique adoption curves served as procedure-volume drivers, while reimbursement banding differentials between premium viscoadaptive and standard cohesive products informed pricing elasticity assumptions.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time ASC inventory turnover data introduce uncertainty bands around quarterly demand fluctuation estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Global Proliferative Vitreoretinopathy Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Corneal Edema Treatment Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Macular Edema Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Global Ophthalmic Knives Market
Ophthalmology
Epidemic Keratoconjunctivitis Treatment Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Synoptophore Market