
 Global Medical Footwear Market | 2026-2036
Global Medical Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Footwear Market Foresight
Aftermarket service revenue from custom orthotic fitting and gait analysis is tilting toward specialized medical channels and away from general retail. Orthofeet Inc. leverages direct-to-patient digital foot scanning to sustain repeat purchase rates. DJO LLC anchors its position through rehabilitation center partnerships. New Balance Athletics Inc. competes by extending its sports biomechanics expertise into post-injury recovery footwear.
Medical footwear encompasses engineered footwear systems designed with specific pressure redistribution properties, adjustable closure mechanisms, and depth-inlay construction to accommodate orthotic devices, manufactured through thermoforming, injection molding, or custom CAD-CAM processes. Its primary purpose is to prevent or manage pathological foot conditions including diabetic neuropathy, post-operative edema, and pressure ulcer formation. Diabetic footwear commands the largest revenue pool due to reimbursable prescription pathways in mature healthcare systems, while post-surgical recovery applications demonstrate the fastest volume expansion as ambulatory surgery protocols shorten hospital stays. Distribution through medical supply stores captures higher per-unit margins than online retail because of required professional fitting services.
The FDA classifies diabetic and orthopedic footwear as Class I or II medical devices depending on structural claims, while the EU Medical Device Regulation mandates clinical evidence for pressure ulcer prevention claims. Health Canada and the TGA enforce comparable biocompatibility testing for materials contacting broken skin. Stakeholders must monitor reimbursement code consolidation and evolving telehealth fitting regulations that could reshape channel economics.
Market Dynamics
Post-surgical recovery departments in German hospitals are expanding procurement of therapeutic footwear as ambulatory surgery protocols shorten hospital stays and shift rehabilitation to outpatient settings. This demand rotation is compressing traditional retail channels while elevating medical supply stores and direct-to-patient digital fitting platforms.
Growth Catalysts
- Diabetes prevalence expansion:India's tier-2 cities are registering rising diabetic neuropathy cases, creating concentrated demand for prescription-grade footwear with pressure redistribution properties.
- EU MDR compliance pathways:The EU Medical Device Regulation's tightening material safety requirements for orthopedic products is accelerating certified manufacturer consolidation and premium product substitution.
- CAD-CAM manufacturing scale:Thermoforming and injection molding automation is reducing custom orthotic production lead times from weeks to days in specialized medical channels.
Market Restraints
- Biocompatibility testing costs:Health Canada and TGA requirements for materials contacting broken skin impose six-figure certification burdens on mid-tier manufacturers.
- Professional fitting dependency:Required gait analysis and custom orthotic fitting services limit e-commerce penetration compared to standard footwear categories.
- Reimbursement code fragmentation:Prescription pathway consolidation across Medicare, Medicaid, and private insurers creates administrative complexity for distributors.
Strategic Opportunities
- Telehealth fitting regulation evolution:Emerging FDA guidance on remote digital foot scanning is opening regulatory pathways for direct-to-patient distribution models.
- Sports biomechanics convergence:Rehabilitation center partnerships are fusing athletic recovery expertise with post-surgical footwear design, creating hybrid product categories.
- Aftermarket service unbundling:Gait analysis and orthotic adjustment subscriptions represent recurring revenue streams distinct from unit sales.
Industry Challenges
- Orthopedic technician shortage:Certified pedorthist training programs in the US and EU are failing to match clinic expansion rates, creating fitting bottleneck risks.
- Legacy ERP integration:Medical supply distributors are struggling to merge prescription verification systems with e-commerce inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Footwear Market |
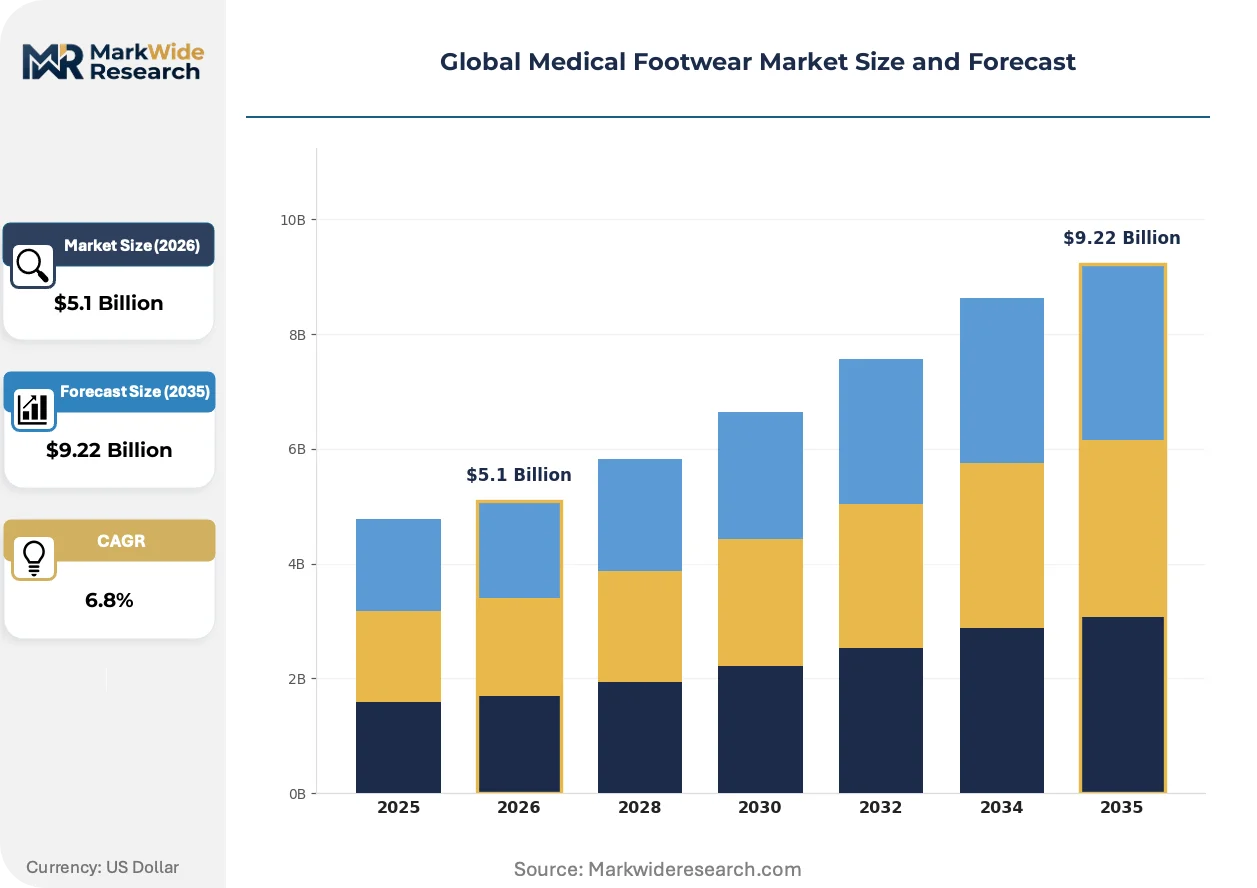
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.22 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Shoes, Orthopedic Shoes, Diabetic Footwear, Surgical Shoes, Slip-Resistant Shoes Application: Diabetes Care, Post-Surgical Recovery, Geriatric Care, Injury Prevention, Pressure Ulcer Management End User: Hospitals, Rehabilitation Centers, Clinics, Home Care Settings, Nursing Homes Distribution Channel: Specialty Stores, Online Retailers, Medical Supply Stores, Pharmacies, Direct Sales |
| Companies Covered | Aetrex Worldwide Inc., Orthofeet Inc., New Balance Athletics Inc., DARCO International Inc., Gravity Defyer Corp., Drew Shoe Corporation, DJO LLC, Dr. Comfort, Apex Foot Health Industries LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Footwear Market Shifts & Advancements
Digital foot scanning technology is virtualizing the traditional custom fitting workflow, compressing the distance between patient measurement and manufacturing execution. Three convergent developments are restructuring how therapeutic footwear reaches end users.
Pressure-sensor insole arrays combined with smartphone-based 3D scanning is virtualizing the clinical gait analysis experience. Podiatry clinics in the US and Germany are adopting these systems to reduce appointment duration while maintaining prescription accuracy. This virtualization is enabling manufacturers to bypass medical supply stores and capture patient data directly.
The EU Medical Device Regulation's clinical evidence requirements for pressure ulcer prevention claims are forcing manufacturers to invest in prospective studies rather than retrospective case files. German orthopedic producers are responding by partnering with university hospitals to generate compliant data packages. Diabetic footwear with explicit prevention claims now faces higher documentation barriers than general therapeutic categories.
Hospital procurement departments are consolidating vendor lists around suppliers offering both footwear and digital fitting infrastructure. Post-surgical recovery units in Mumbai and São Paulo are selecting vendors based on telehealth integration capabilities rather than product catalogs alone. This vendor consolidation is most visible in markets where ambulatory surgery volumes are expanding fastest.
Global Medical Footwear Market Segmentation
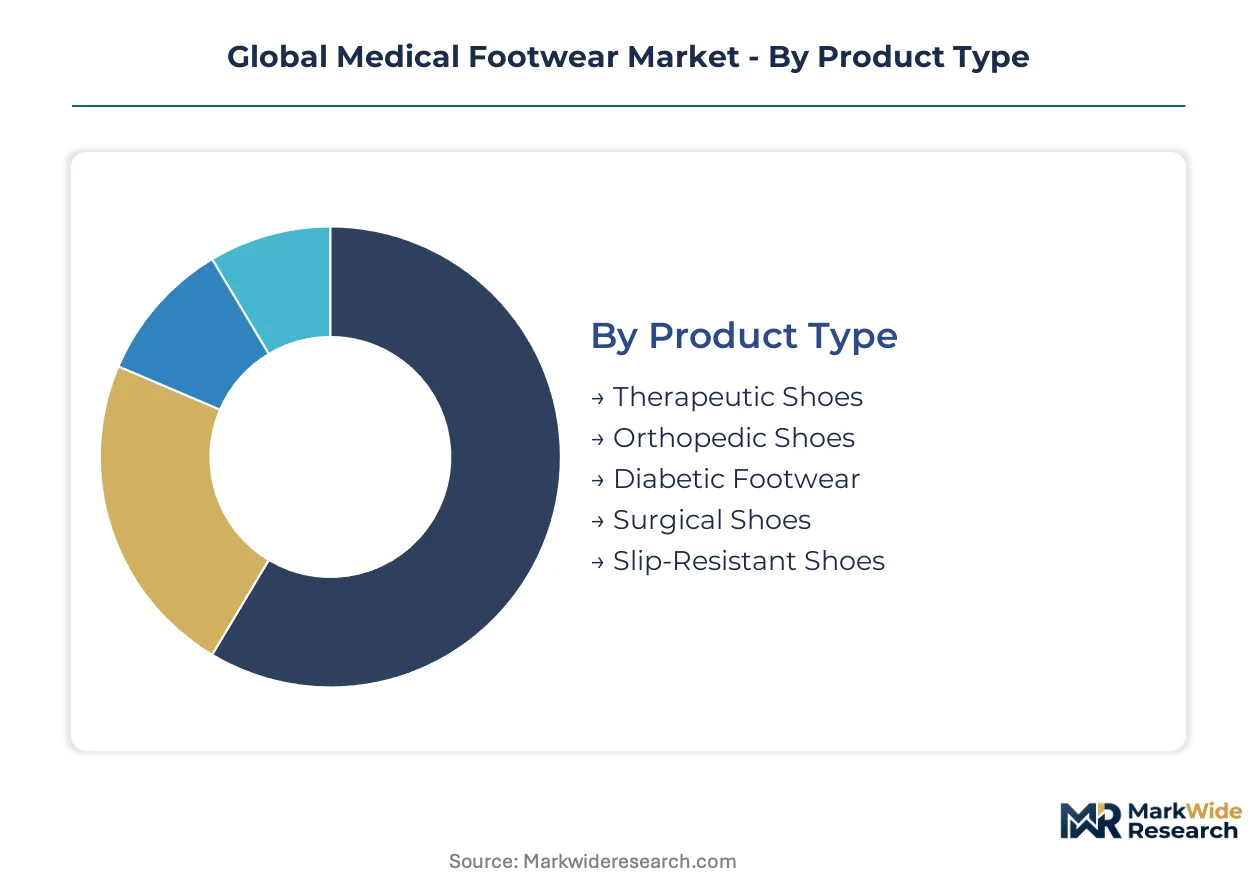
Medical footwear segmentation reveals divergent service intensity requirements across product categories, with custom fitting and gait analysis creating aftermarket revenue pools that vary dramatically by segment. Distribution economics shift based on prescription verification complexity and reimbursement pathway structures.
Product Type:
After-sales service intensity peaks with products requiring ongoing orthotic adjustment and pressure monitoring protocols.
- Diabetic Footwear:Engineered with pressure redistribution insoles and seamless interior construction to prevent neuropathic ulcer formation. Demand concentrates in India's tier-2 cities where diabetes prevalence is climbing fastest, though reimbursement code fragmentation across US Medicare and Medicaid creates administrative friction for distributors.
- Orthopedic Shoes:Features adjustable closure mechanisms and depth-inlay construction accommodating custom orthotic devices. German hospital procurement departments are expanding volume commitments as ambulatory surgery protocols accelerate post-surgical recovery applications.
- Therapeutic Shoes:General-purpose pressure-relief footwear with modular inlay systems.
- Surgical Shoes:Post-operative footwear with open-toe designs and edema-accommodating stretch uppers.
- Slip-Resistant Shoes:Occupational safety footwear with certified traction outsoles for healthcare worker protection.
Diabetic footwear holds the largest share; momentum sits with orthopedic shoes as CAD-CAM manufacturing compresses custom production lead times.
Application:
Cost tier stratification separates reimbursable prescription pathways from direct-pay consumer segments.
- Diabetes Care:Preventive footwear systems targeting neuropathy progression and ulcer avoidance through pressure offloading. The EU Medical Device Regulation's clinical evidence requirements for pressure ulcer prevention claims are forcing manufacturers into prospective study investments.
- Post-Surgical Recovery:Edema management and protected ambulation footwear for shortened hospital stay protocols. Mumbai and São Paulo hospital systems are selecting vendors based on telehealth integration capabilities rather than product catalogs alone.
- Geriatric Care:Fall-risk reduction footwear with stability enhancements for aging populations.
- Injury Prevention:Prophylactic biomechanical support for high-risk occupational and athletic populations.
- Pressure Ulcer Management:Therapeutic systems for existing wound care and offloading protocols.
Diabetes care commands premium pricing through prescription channels; post-surgical recovery is climbing the fastest as ambulatory surgery volumes expand.
End User:
Customer type determines fitting infrastructure requirements and reimbursement complexity.
- Hospitals:Centralized procurement of post-surgical footwear with vendor consolidation around digital fitting infrastructure. German hospital systems are compressing traditional retail channels while elevating direct-to-patient platforms.
- Rehabilitation Centers:Gait analysis-intensive fitting services with recurring orthotic adjustment subscriptions. DJO LLC anchors market position through exclusive partnership networks in this channel.
- Clinics:Podiatry and orthopedic practices with pressure-sensor insole arrays and smartphone-based 3D scanning virtualization.
- Home Care Settings:Remote digital foot scanning adoption driven by FDA guidance evolution on telehealth fitting.
- Nursing Homes:Institutional volume procurement with standardized sizing protocols and reduced customization requirements.
Hospitals represent the highest volume channel; home care settings are gaining share fastest as remote fitting regulations mature.
Distribution Channel:
Margin structures diverge based on professional fitting service bundling requirements.
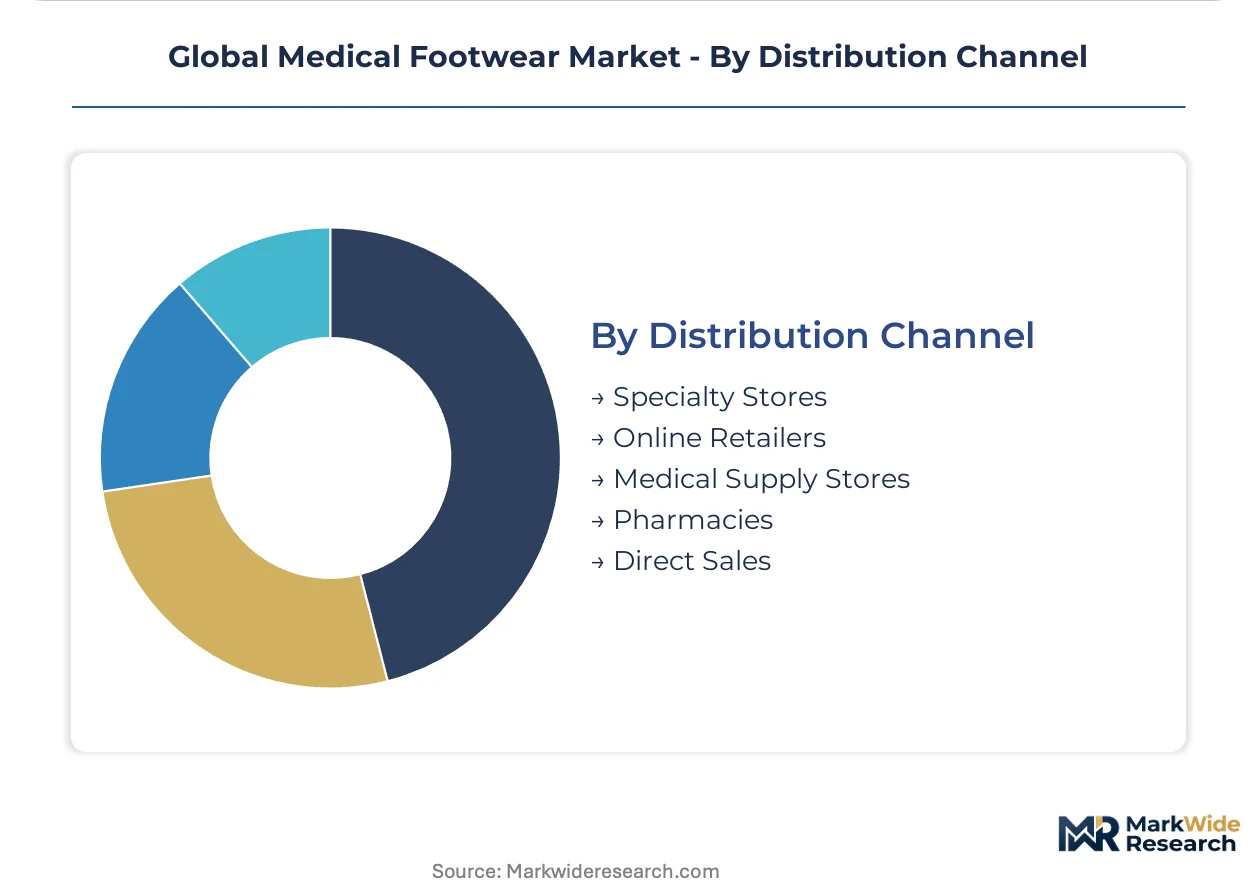
- Medical Supply Stores:Professional fitting services with gait analysis and prescription verification capturing higher per-unit margins than online alternatives. Certified pedorthist shortages in the US and EU are creating fitting bottleneck risks.
- Direct Sales:Manufacturer-controlled digital foot scanning platforms enabling patient data capture and repeat purchase rate optimization. Orthofeet Inc. leverages this channel to sustain direct-to-patient relationships.
- Specialty Stores:Retail environments with trained fitting staff and orthotic device integration capabilities.
- Online Retailers:Limited penetration due to professional fitting dependency, though emerging FDA guidance on remote scanning is opening regulatory pathways.
- Pharmacies:Prescription fulfillment nodes with basic therapeutic footwear access and limited customization services.
Medical supply stores retain margin leadership; direct sales channels are expanding most quickly as telehealth infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in medical footwear concentrates sharply in India's tier-2 cities, where out-of-pocket diabetes care spending dominates, while German hospital procurement departments show minimal elasticity as bundled reimbursement pathways absorb device costs.
United States
Medicare's therapeutic shoe program drives prescription-grade demand through certified pedorthist networks, with FDA telehealth guidance evolution enabling remote digital fitting pilots. The Southeast corridor from Florida to Georgia hosts expanding podiatry clinic chains adopting pressure-sensor insole virtualization systems.
Germany
Ambulatory surgery protocol expansion is compressing hospital stays and rotating procurement toward outpatient therapeutic footwear with digital infrastructure. EU MDR clinical evidence requirements for pressure ulcer prevention claims are forcing orthopedic producers into university hospital partnership investments. The North Rhine-Westphalia cluster anchors manufacturing scale for CAD-CAM custom production systems.
India
Diabetes prevalence acceleration in tier-2 cities like Pune and Lucknow is creating concentrated demand for prescription footwear with pressure redistribution properties. CDSCO's tightening biocompatibility documentation for materials contacting broken skin is elevating import certification burdens on mid-tier distributors. The Maharashtra-Gujarat pharmaceutical corridor is absorbing contract manufacturing overflow from European MDR-compliant producers.
Brazil
Post-surgical recovery unit expansion in São Paulo hospital systems is selecting vendors based on telehealth integration capabilities rather than product catalogs alone. ANVISA's medical device registration pathways for orthopedic footwear are lengthening approval timelines for non-ASEAN imports. The São Paulo-Minas Gerais axis concentrates rehabilitation center partnerships driving gait analysis service bundling.
Japan
Aging-population fall-risk reduction programs are institutionalizing geriatric footwear procurement through municipal health insurance riders. PMDA's biocompatibility testing harmonization with ISO standards is streamlining material certification for domestic manufacturers. The Kansai region around Osaka maintains specialized pedorthist training density unmatched elsewhere in Asia-Pacific.
Global Medical Footwear Market Competitive Landscape
Capability concentration sits with specialized orthopedic fabricators possessing CAD-CAM manufacturing depth; scale advantage sits with athletic footwear multinationals leveraging sports biomechanics expertise. The market structures around three archetypes: certified medical device specialists with prescription channel dominance, sports-performance brands extending into post-injury recovery, and direct-to-patient digital platforms capturing gait data. Competitive moves center on rehabilitation center exclusivity partnerships and telehealth infrastructure acquisitions that bypass traditional medical supply stores.
Among direct-to-patient specialists, Orthofeet Inc. exemplifies the digital foot scanning archetype, while DJO LLC anchors the rehabilitation center partnership model. New Balance Athletics Inc. represents the athletic-to-medical crossover tier, extending sports biomechanics capabilities into post-surgical recovery applications.
| Leading Market Players |
|---|
| Aetrex Worldwide Inc. |
| Orthofeet Inc. |
| New Balance Athletics Inc. |
| DARCO International Inc. |
| Gravity Defyer Corp. |
| Drew Shoe Corporation |
| DJO LLC |
| Dr. Comfort |
| Apex Foot Health Industries LLC |
| Others |
Supply & Pricing Matrix
Biocompatibility certification chokepoints under EU MDR and Health Canada requirements determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic consolidation of manufacturing toward MDR-compliant production clusters. Mid-tier manufacturers face six-figure testing burdens that compress their pricing flexibility while elevating premium substitution rates in prescription channels.
Pricing Analysis
Aftermarket service revenue from gait analysis subscriptions and orthotic adjustment contracts drives lifetime value beyond unit sales in medical footwear. Pricing stratifies across premium, standard, and economy tiers based on CAD-CAM customization depth and FDA Class II certification status. Cost compression in the standard tier is intensifying because of Indian and Brazilian import certification burdens. Home care settings show highest price sensitivity due to direct-pay exposure, while German hospital procurement demonstrates minimal elasticity under bundled reimbursement.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for injection-molded sole components and pressure-sensor arrays. Manufacturing concentrates in Germany, China, and India, with thermoforming equipment and medical-grade EVA foam as critical inputs. Single-source vulnerability sits with Taiwanese semiconductor suppliers for insole sensor arrays. Distribution runs through medical supply stores with certified pedorthist fitting services, though direct-to-patient platforms are capturing growing share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical footwear functions as a service-attach opportunity where recurring gait analysis subscriptions and remote fitting platform fees expand faster than hardware unit sales. The aftermarket revenue layer now determines enterprise valuation multiples.
For Market Incumbents: Insulate prescription channel dominance by acquiring telehealth infrastructure capabilities before FDA guidance on remote digital scanning finalizes. Lock in rehabilitation center exclusivity partnerships in São Paulo and Mumbai where ambulatory surgery volumes are climbing fastest. Backward integration into CAD-CAM manufacturing reduces custom production lead times from weeks to days. For New Entrants and Emerging Players: Pursue white-space opportunity in India's tier-2 cities where diabetes prevalence is accelerating and reimbursement infrastructure remains underdeveloped. Target direct-to-patient digital platforms with smartphone-based 3D scanning as the most penetrable entry vector. Partner with Maharashtra-Gujarat contract manufacturers to bypass European MDR compliance timelines. For Investors and Strategic Acquirers: EU MDR clinical evidence requirements for pressure ulcer prevention claims reshapes the acquisition landscape toward manufacturers with prospective study capabilities and university hospital partnerships. Long-term viability centers on platforms combining hardware with recurring gait data services. Watch FDA telehealth fitting guidance finalization as the signal for direct-to-patient channel inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Infrastructure Acquisition | Captures patient gait data directly, bypassing medical supply store intermediaries. |
| University Hospital Partnership Investment | Generates EU MDR-compliant clinical evidence packages for pressure ulcer prevention claims. |
| CAD-CAM Manufacturing Scale-Up | Compresses custom orthotic lead times from weeks to days in specialized channels. |
| Rehabilitation Center Exclusivity Agreement | Locks in recurring gait analysis subscription revenue with institutional volume commitments. |
| Remote Digital Scanning Platform Launch | Positions for FDA telehealth guidance evolution enabling direct-to-patient distribution. |
Research Methodology
Operator-level perspectives from hospital procurement managers, certified pedorthists, rehabilitation center directors, and biomedical engineers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital GPO contracts, and CMS Medicare reimbursement code records. Bottom-up unit demand modeling and top-down healthcare expenditure allocation triangulated market sizing across product categories.
Scenario-bracketing around regulatory approval timelines and reimbursement code consolidation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and distribution channel complexity. CAGRs derived from healthcare infrastructure investment trajectories, diabetes prevalence curves, and ambulatory surgery volume projections in target geographies.
Sensitivities concentrate around EU MDR enforcement intensity, FDA telehealth guidance finalization, and certified pedorthist training program expansion rates. Forecasts reflect documented assumptions on regulatory pathway evolution and reimbursement structure stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electric Handpiece Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Urology Guidewires Market
Medical Devices
Indian Laparoscopy Devices Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Non-Destructive Medical Technologies Market
Medical Devices
Radiotherapy Patient Positioning Accessories Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Global Structural Heart Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Inversion Table Market
Medical Devices
Breathing Circuits Market
Medical Devices
Elderly and Disabled Assistive Devices Market