
 France Diabetes Devices Market | 2026-2036
France Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Diabetes Devices Market Foresight
France is fragmenting its diabetes devices supply base across regional manufacturing hubs and specialized distributors. Abbott Laboratories leverages integrated sensor production to sustain its position in continuous glucose monitoring. Dexcom competes through algorithm-intensive platforms that anchor real-time data delivery to French endocrinology networks.
France diabetes devices encompass electrochemical biosensors, micro-needle arrays, and closed-loop algorithm controllers designed to measure interstitial glucose and automate insulin delivery for glycemic regulation. Continuous glucose monitors and insulin pumps lead structural growth, with sensor technology capturing expanding margin pools as hardware commoditizes. Bluetooth connectivity and mobile integration represent the fastest-advancing technology layer, though data analytics services remain nascent in reimbursement frameworks.
ANSM enforces pre-market conformity assessments aligned with EU MDR requirements, while CE marking mandates clinical evidence thresholds that filter market entrants by validation capacity. The EU AI Act introduces additional scrutiny for algorithm-driven dosing recommendations, reshaping development timelines for closed-loop systems. Stakeholders must monitor reimbursement negotiations between HAS and manufacturers, as coverage decisions for connected devices will determine which technology tiers achieve scalable adoption across French diabetes clinics and home care channels.
Market Dynamics
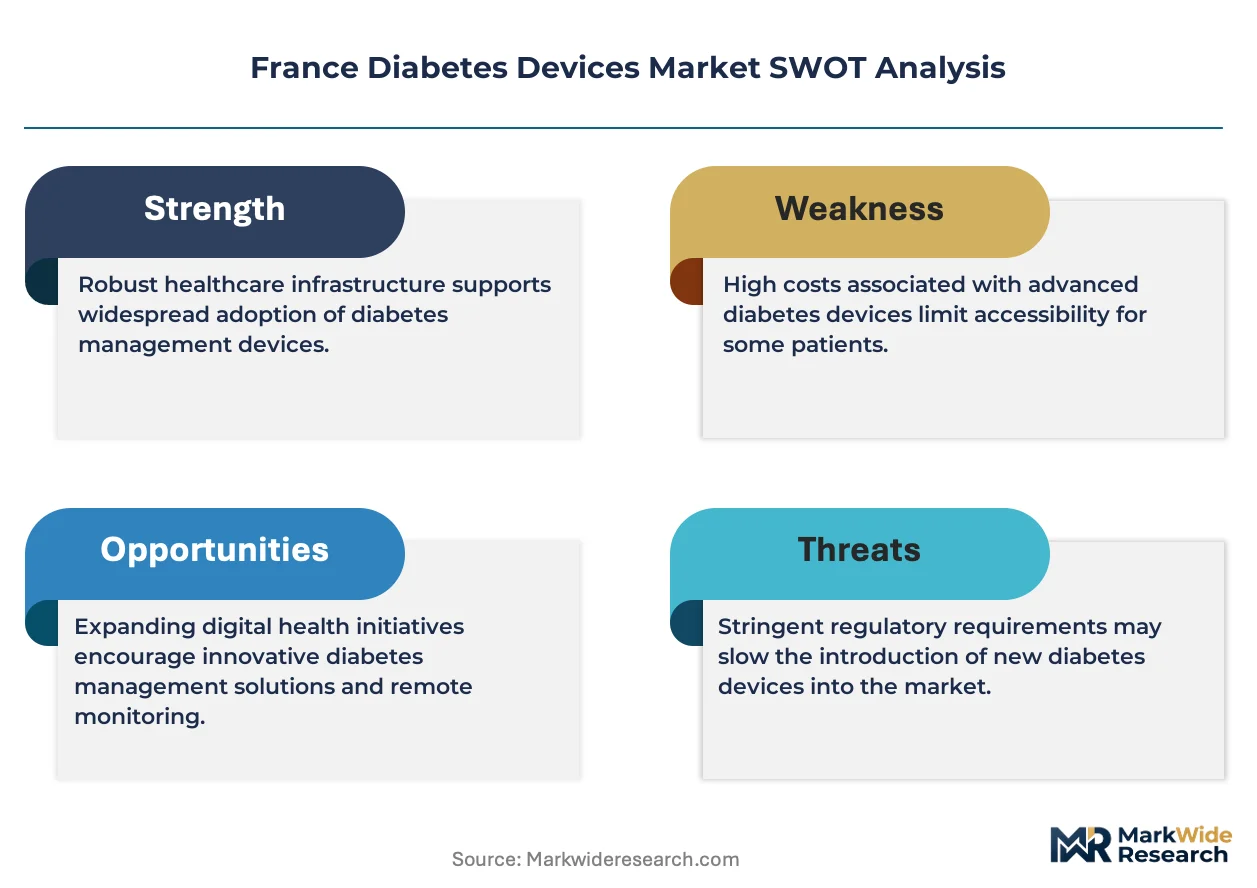
The France diabetes devices sector pivots on ANSM's enforcement of EU MDR conformity assessments, which filters market entry by clinical validation capacity and reshapes competitive positioning among sensor manufacturers and algorithm developers.
Growth Catalysts
- EU MDR Clinical Evidence Thresholds:CE marking mandates under the EU MDR elevate product credibility, accelerating hospital procurement of validated continuous glucose monitoring systems in Paris-area endocrinology networks.
- Home Care Channel Expansion:HAS reimbursement negotiations increasingly cover connected devices for remote glycemic management, pulling sensor adoption beyond clinical settings into patient residences.
- Bluetooth-Enabled Sensor Platforms:Wireless glucose data transmission to mobile applications is hybridizing patient self-monitoring workflows, reducing clinic visit dependency in Île-de-France healthcare clusters.
Market Restraints
- Algorithm Validation Costs:The EU AI Act imposes additional scrutiny on closed-loop insulin dosing systems, extending development timelines and compressing margins for automated delivery platforms.
- Regional Supply Concentration:Sensor manufacturing concentrates in a limited corridor of European contract manufacturers, exposing French distributors to single-source vulnerability for electrochemical biosensor components.
- Interstitial Measurement Limitations:Lag time between blood glucose and interstitial fluid readings creates clinical skepticism among pediatric endocrinologists, constraining pediatric segment penetration.
Strategic Opportunities
- Provincial Clinic Networks:Underpenetrated diabetes care centers in Lyon, Marseille, and Toulouse present white-space expansion for remote monitoring platforms outside the Paris metropolitan concentration.
- Data Analytics Service Layer:Reimbursement frameworks for predictive glycemic pattern analysis remain nascent, creating first-mover advantage for platforms integrating AI-driven patient coaching.
- Micro-Needle Array Convergence:Painless glucose sampling technology combined with wearable form factors is opening pediatric and geriatric segments previously resistant to conventional lancet-based monitoring.
Industry Challenges
- Embedded Software Certification:ANSM pre-market assessments for algorithm-intensive devices require specialized regulatory affairs talent scarce in French medical device consulting pools.
- Legacy Hospital IT Integration:Closed-loop systems face interoperability friction with established electronic health record architectures in public hospital networks, delaying pilot-to-scale transitions.
- Sensor Calibration Complexity:Patient adherence to factory calibration protocols varies widely, undermining clinical outcomes and triggering reimbursement disputes with regional health authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Diabetes Devices Market |
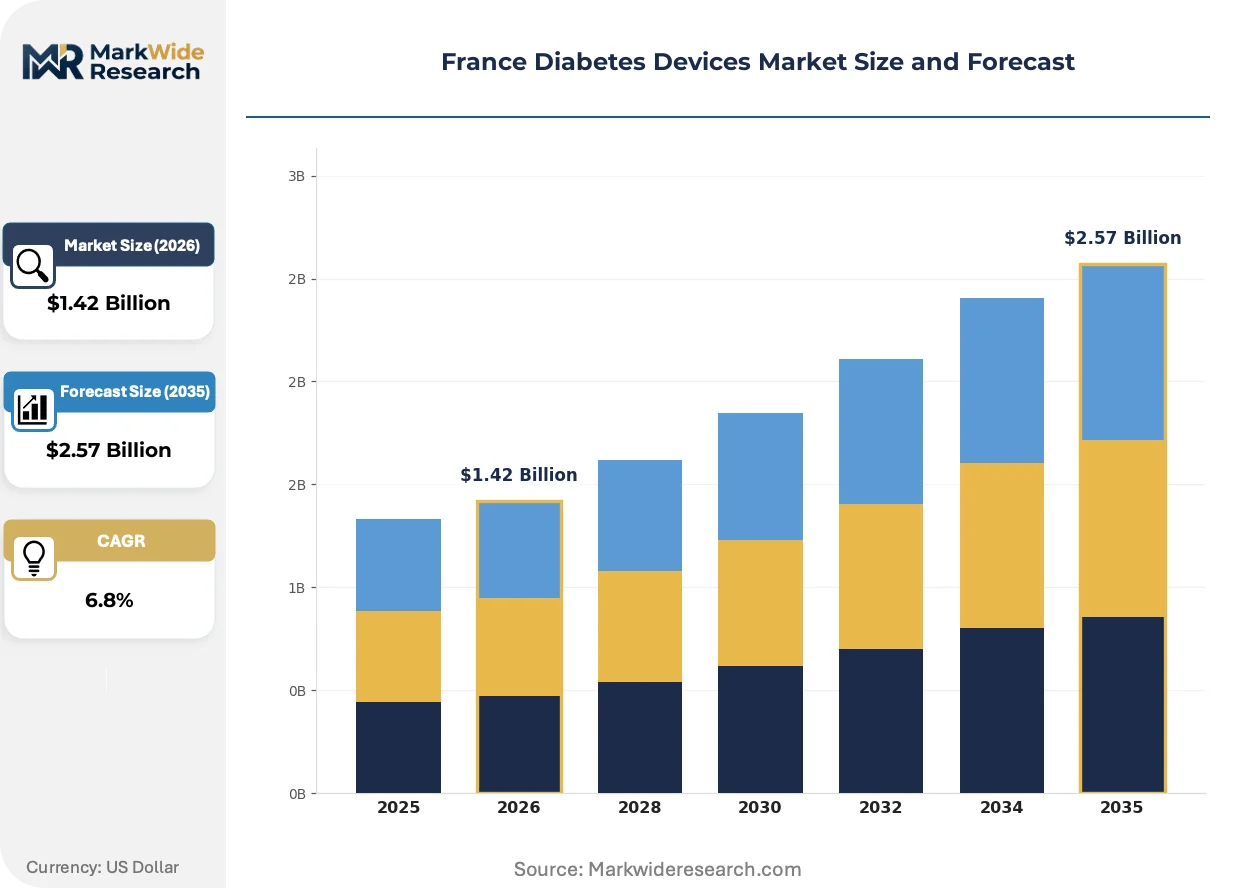
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pumps, Glucose Meters, Continuous Glucose Monitors, Insulin Pens, Lancets, Test Strips Technology: Bluetooth Connectivity, Near Field Communication, Cloud-Based Monitoring, Sensor Technology, Data Analytics, Mobile Integration Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pre-Diabetes, Hypoglycemia Management, Hyperglycemia Control End User: Hospitals, Diabetes Clinics, Home Care, Specialized Laboratories, Pharmacies, Research Institutions |
| Companies Covered | Abbott Laboratories, Dexcom, F. Hoffmann-La Roche Ltd, Medtronic, Novo Nordisk, Sanofi, Johnson & Johnson, Ascensia Diabetes Care Holdings AG, DIABELOOP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Diabetes Devices Market Shifts & Advancements
Sensor hardware commoditization is redirecting value capture toward software layers and data services, with French reimbursement negotiations determining which technology tiers achieve scalable adoption across diabetes care channels.
Continuous glucose monitoring platforms are hybridizing electrochemical sensing with machine learning inference at the edge. French endocrinology clinics in the Île-de-France cluster are adopting these systems faster than provincial networks. The technology is compressing margins on standalone hardware while expanding addressable revenue through subscription-based analytics.
EU AI Act algorithmic risk classification is reshaping development roadmaps for automated insulin delivery. Manufacturers must now document clinical evidence for dosing recommendation engines before CE marking approval. Closed-loop systems targeting pediatric populations face the steepest compliance burden, with some developers pivoting toward adult-only indications to accelerate market entry.
French diabetes patients are consolidating device purchasing decisions through specialized pharmacy networks rather than hospital procurement channels. Regional pharmacy chains in Lyon and Bordeaux are building in-house educator staff to support sensor onboarding. This shift is most visible in urban centers where home care reimbursement coverage has expanded fastest, displacing traditional durable medical equipment distributors from the patient relationship.
France Diabetes Devices Market Segmentation
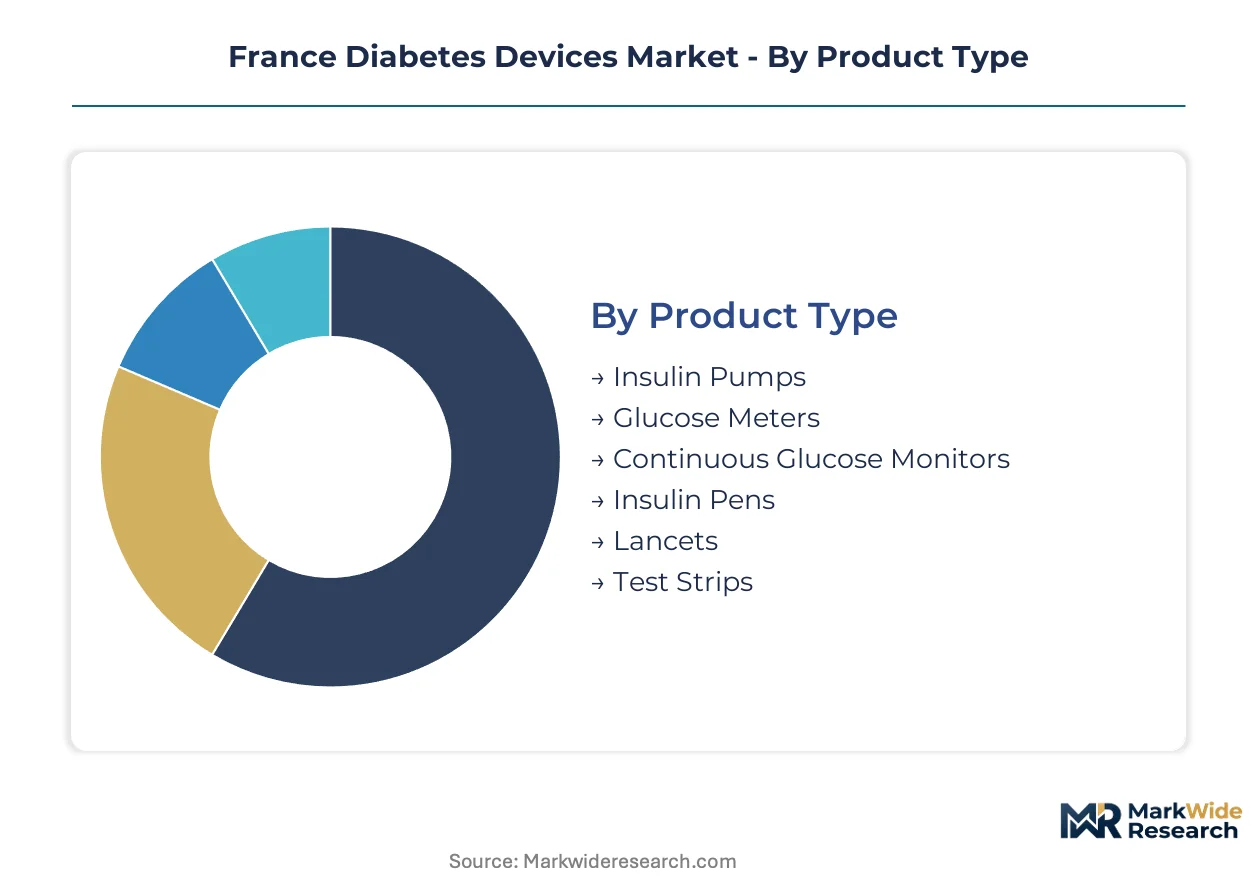
France's diabetes devices market fragments across four intersecting dimensions that determine reimbursement pathways and procurement channels. Product type and technology layers define margin capture, while application and end-user categories shape clinical validation requirements under ANSM oversight.
Product Type:
Mature electrochemical hardware segments anchor volume, while emerging closed-loop systems command premium positioning.
- Continuous Glucose Monitors:Electrochemical biosensors measure interstitial glucose via subcutaneous filament arrays. Paris-area endocrinology networks in Île-de-France drive hospital procurement of factory-calibrated systems, though patient adherence to sensor replacement protocols varies by regional pharmacy support density.
- Insulin Pumps:Motor-driven reservoir systems deliver basal-bolus dosing through subcutaneous infusion sets. HAS reimbursement negotiations increasingly cover Bluetooth-enabled pumps for home care channels, displacing traditional syringe-based management in urban diabetes clinics.
- Glucose Meters:Portable electrochemical readers using capillary blood samples remain the entry-tier standard for provincial healthcare networks with limited connected device coverage.
- Insulin Pens:Disposable and reusable injection devices dominate Type 2 diabetes management where pump therapy remains economically restricted.
- Lancets:Single-use micro-needles for capillary blood sampling face margin compression as continuous monitoring reduces fingerstick dependency.
- Test Strips:Consumable electrochemical strips tied to meter hardware see volume concentration in retail pharmacy chains across Lyon and Marseille.
Test strips retain volume leadership; continuous glucose monitors hold the steepest expansion curve.
Technology:
Cost tier stratification separates validated clinical platforms from consumer-accessible monitoring layers.
- Sensor Technology:Electrochemical transduction layers convert glucose-enzyme reactions into electrical signals. French manufacturing concentrates electrochemical biosensor production in contract facilities serving Abbott and Dexcom supply chains, exposing distributors to single-source component vulnerability.
- Bluetooth Connectivity:Wireless data transmission protocols enable real-time glucose streaming to mobile applications. Home care reimbursement expansion in Bordeaux and Toulouse accelerates patient adoption of smartphone-integrated monitoring outside hospital settings.
- Data Analytics:Cloud-based pattern recognition for glycemic prediction remains nascent in HAS coverage frameworks, creating first-mover positioning for AI-driven coaching platforms.
- Mobile Integration:Native application ecosystems for iOS and Android consolidate patient data visualization and caregiver alert functions.
- Cloud-Based Monitoring:Centralized data repositories enable remote clinician oversight of patient glucose trends across dispersed regional networks.
- Near Field Communication:Short-range contactless data transfer supports quick clinic downloads without full smartphone pairing.
Sensor technology captures the highest margin tier; data analytics is climbing the fastest toward reimbursable service status.
Application:
Customer type differentiation separates intensive insulin users from lifestyle-managed populations with diverging device complexity needs.
- Type 1 Diabetes:Autoimmune insulin deficiency requiring exogenous replacement therapy. Pediatric endocrinologists in Paris academic hospitals drive adoption of closed-loop systems, though interstitial measurement lag times constrain penetration in younger patient segments.
- Type 2 Diabetes:Progressive insulin resistance managed through oral agents and eventual insulin supplementation. Provincial clinic networks in Lyon and Marseille present white-space expansion for connected monitoring platforms beyond the Île-de-France concentration.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring temporary monitoring interventions with strict glycemic targets.
- Pre-Diabetes:Elevated glucose levels below diagnostic thresholds create preventive monitoring opportunities in employer wellness programs.
- Hypoglycemia Management:Acute low glucose event prevention drives demand for predictive alert algorithms in insulin-intensive populations.
- Hyperglycemia Control:Chronic elevation management focuses on trend visualization for behavioral modification rather than automated intervention.
Type 2 diabetes dominates patient volume; Type 1 diabetes commands the highest per-patient technology expenditure trajectory.
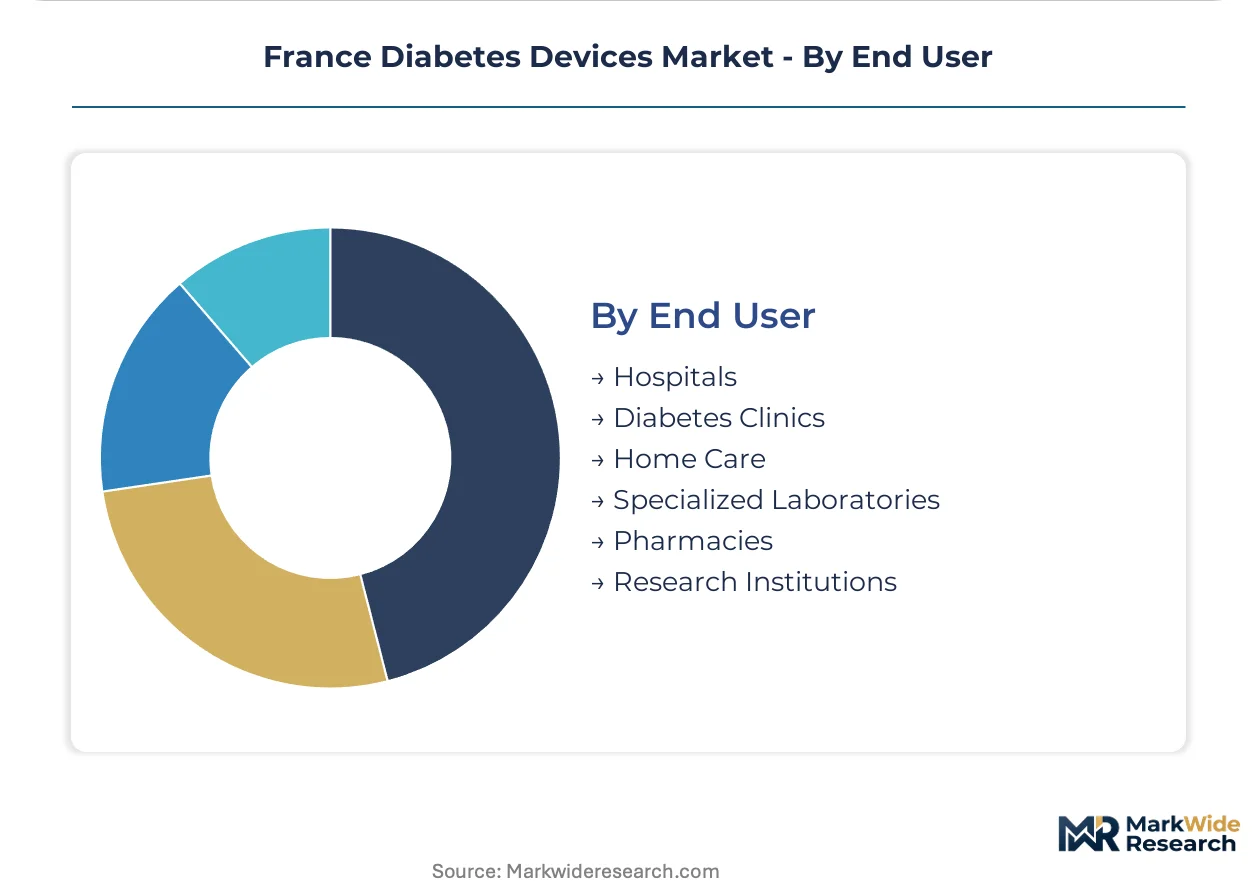
End User:
Supply concentration in specialized distribution channels determines patient access pathways and margin retention.
- Home Care:Patient-resident monitoring and self-management supported by remote clinical oversight. HAS reimbursement negotiations for connected devices pull sensor adoption beyond hospital walls into residences across urban French centers.
- Diabetes Clinics:Specialized endocrinology practices in Paris metropolitan networks anchor algorithm-intensive platform validation and prescriber education.
- Hospitals:Acute care settings require interoperable glucose data integration with electronic health record architectures in public hospital networks.
- Pharmacies:Regional chains in Lyon and Bordeaux build in-house educator staff to support sensor onboarding, displacing durable medical equipment distributors.
- Specialized Laboratories:Reference testing facilities validate continuous monitor accuracy against laboratory glucose measurements.
- Research Institutions:Academic medical centers conduct clinical trials for EU MDR conformity assessments and EU AI Act algorithm validation.
Home care channels are gaining share fastest; diabetes clinics retain the highest-margin prescriber influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM's enforcement of EU MDR conformity assessments anchors France's regulatory framework, filtering market entry by clinical validation capacity and concentrating sensor manufacturing partnerships in the Île-de-France healthcare cluster.
Île-de-France
Paris metropolitan endocrinology networks drive adoption of algorithm-intensive continuous glucose monitoring platforms. HAS reimbursement negotiations for connected devices accelerate fastest in this region, pulling sensor procurement beyond hospital walls into specialized pharmacy channels. The concentration of academic medical centers here anchors EU AI Act algorithm validation trials for closed-loop insulin delivery systems.
Auvergne-Rhône-Alpes
Lyon's provincial diabetes care centers present white-space expansion for remote monitoring platforms outside the Paris concentration. The region's medical device distributors are building educator staff to support sensor onboarding, displacing traditional durable medical equipment suppliers. Bluetooth-enabled pump adoption is climbing here as home care reimbursement coverage expands through regional health authority agreements.
Provence-Alpes-Côte d'Azur
Marseille's underpenetrated clinic networks create demand for factory-calibrated continuous monitoring systems with reduced calibration complexity. The region's pharmacy chains are consolidating device purchasing decisions through in-house diabetes educator programs. ANSM pre-market assessments for algorithm-driven devices face longer review queues here due to limited specialized regulatory affairs consulting capacity.
Nouvelle-Aquitaine
Bordeaux's regional pharmacy networks are capturing patient relationships from hospital procurement channels for connected glucose monitoring. The city's healthcare cluster is piloting cloud-based remote oversight systems for dispersed rural diabetes populations. Interstitial measurement limitations constrain pediatric segment penetration despite expanding home care reimbursement frameworks.
Occitanie
Toulouse's aerospace engineering heritage is spilling into medical device manufacturing, with contract facilities producing electrochemical biosensor components for Abbott and Dexcom supply chains. The region's diabetes clinics are adopting Bluetooth-integrated platforms slower than Île-de-France due to legacy electronic health record interoperability friction. Single-source vulnerability for sensor components exposes French distributors to supply concentration risk.
France Diabetes Devices Market Competitive Landscape
Capability concentration sits with algorithm developers and sensor specialists; scale advantage sits with diversified medtech conglomerates with established hospital procurement relationships. The market structure tiering separates premium-tier integrated platform providers from mid-tier component suppliers and regional distributors. Two strategic archetypes dominate: vertically integrated sensor manufacturers controlling electrochemical production and algorithm-intensive platform developers monetizing through data services. Competitive moves center on M&A targeting specialized regulatory affairs talent and strategic partnerships with French pharmacy chains for patient onboarding capacity.
Within the integrated platform tier, Abbott Laboratories and Dexcom exemplify divergent approaches to value capture. Abbott's position reflects captive sensor production capacity and factory-calibrated system architectures. Dexcom represents algorithm-intensive real-time data delivery anchored to French endocrinology networks. Among European-headquartered specialists, F. Hoffmann-La Roche Ltd occupies a position bridging diagnostic heritage with connected care transitions. Medtronic sits within the diversified medtech conglomerate archetype, leveraging established hospital procurement relationships for pump therapy platforms. The competitive dynamic between these players turns on reimbursement negotiation outcomes with HAS and pharmacy channel capture rates outside Paris metropolitan concentration.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| F. Hoffmann-La Roche Ltd |
| Medtronic |
| Novo Nordisk |
| Sanofi |
| Johnson & Johnson |
| Ascensia Diabetes Care Holdings AG |
| DIABELOOP |
| Others |
Supply & Pricing Matrix
Undercapacity in European electrochemical biosensor contract manufacturing is concentrating pricing power among sensor specialists while forcing French distributors into long-term offtake commitments. This utilization squeeze elevates input costs for continuous glucose monitoring hardware while compressing margins on commoditized glucose meters.
Pricing Analysis
Paris-area procurement premiums run 15-20 percent above Lyon and Marseille for identical factory-calibrated sensor platforms due to specialized pharmacy educator density and faster HAS reimbursement processing. Three-tier pricing structure across premium closed-loop systems, standard Bluetooth-enabled monitors, and economy capillary meters dominates the market. Cost compression in the meter segment is intensifying as continuous monitoring reduces fingerstick dependency among Type 2 populations. Provincial clinic networks exhibit the highest price sensitivity, while Paris academic hospitals prioritize algorithm validation over unit economics.
Supply Chain Analysis
Electrochemical transduction membranes and enzymatic glucose oxidase layers draw from specialized chemical synthesis facilities in Germany, Switzerland, and the Netherlands. Subcutaneous filament arrays, Bluetooth module chipsets, and mobile application middleware constitute critical component dependencies. Single-source vulnerability for electrochemical biosensor substrates exposes French distributors to supply interruption when contract manufacturers prioritize Abbott and Dexcom volume commitments. Distribution runs through regional pharmacy chains building in-house educator capacity, displacing traditional durable medical equipment wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's diabetes devices sector sits in early-cycle expansion as HAS reimbursement negotiations for home care connected devices accelerate patient-resident monitoring penetration beyond hospital walls.
For Market Incumbents: Build regulatory affairs talent moats by acquiring specialized EU MDR consulting capabilities scarce in French medical device advisory pools. Anchor sensor production partnerships with Occitanie contract manufacturers to reduce single-source exposure. Defend against algorithm-intensive platform entrants by deepening clinical validation relationships with Paris-area endocrinology networks. For New Entrants and Emerging Players: Pursue white-space expansion in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur provincial clinic networks where connected device penetration lags Île-de-France by 30-40 percent. Target Type 2 diabetes management platforms with simplified calibration protocols suited to pharmacy educator support models. Deploy direct-to-patient onboarding through Lyon and Bordeaux pharmacy chain partnerships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across closed-loop algorithm development as EU AI Act compliance extends validation timelines and talent costs. Five-to-ten year viability favors platforms with captive sensor supply or established HAS reimbursement pathways. Acquisition targets should demonstrate pharmacy channel capture rates outside Paris metropolitan concentration. Monitor HAS coverage decisions for predictive analytics services as the inflection signal for scalable data revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway Acceleration | CE marking timelines determine competitive entry sequencing for algorithm-driven dosing platforms under ANSM oversight. |
| Pharmacy Chain Educator Program Partnership | Lyon and Bordeaux pharmacy networks are consolidating patient relationships from hospital procurement channels. |
| Cloud-Based Remote Monitoring Deployment | Bordeaux healthcare clusters pilot oversight systems for dispersed rural diabetes populations in Nouvelle-Aquitaine. |
| Micro-Needle Array Form Factor Development | Painless sampling technology opens pediatric and geriatric segments resistant to conventional lancet-based monitoring. |
| EU AI Act Algorithm Validation Investment | Clinical evidence requirements for dosing recommendation engines reshape development roadmaps before market entry. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinologists, hospital biomedical engineers, regional pharmacy chain procurement directors, and ANSM regulatory affairs specialists. Secondary validation drew from ANSM pre-market assessment databases, HAS reimbursement coverage decisions, EU MDR notified body filings, and hospital procurement contract registries. Bottom-up patient population modeling and top-down manufacturer shipment analysis were triangulated to anchor volume estimates.
Calibration against historical adoption curves for continuous glucose monitoring in comparable European markets refined growth rate assumptions across the projection horizon. Segmentation dimensions modeled include product type, technology layer, diabetes application, and end-user channel. CAGRs were derived from fitted adoption curves incorporating HAS reimbursement expansion timelines and EU AI Act implementation phases. Forecast inputs included sensor replacement protocol adherence rates and pharmacy educator density by region.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure growth or HAS budget allocation priorities would shift the trajectory of connected device penetration. Forecasts reflect documented assumptions regarding reimbursement pathway evolution and regulatory timeline adherence. Cross-checking against EMA parallel assessment trends and comparable EU member state adoption benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market