
 Middle East and Africa Diabetes Pen Market | 2026-2036
Middle East and Africa Diabetes Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Diabetes Pen Market Analytics
Aftermarket service revenue for pen needle compatibility and patient training programs is tilting toward manufacturers with direct distribution networks. Novo Nordisk A/S leverages its Gulf-based logistics hubs to sustain replenishment contracts with hospital chains across Saudi Arabia and the UAE. Julphar anchors regional manufacturing through its Ras Al Khaimah facility, producing disposable pens for Gulf Cooperation Council markets. Eli Lilly and Company competes on biologic pen portfolios, positioning its glucagon-like peptide-1 delivery devices for expanding clinic networks in Egypt and Nigeria.
A diabetes pen is a handheld, spring-loaded or electronic injection device designed to deliver precise insulin or biologic doses through disposable or reusable cartridges, typically featuring dose-adjustment dials in one-unit increments and subcutaneous needle attachment systems. Its primary commercial purpose is to enable accurate, patient-controlled glycemic management outside clinical settings. Insulin pens dominate value pools across the Middle East and Africa, while reusable pens capture accelerating share as Saudi Arabia and the UAE impose medical waste reduction targets. Homecare channels now generate the fastest-growing demand segment, driven by reimbursement shifts favoring outpatient diabetes management in South Africa and Morocco.
SFDA in Saudi Arabia, SAHPRA in South Africa, and the UAE's Ministry of Health and Prevention enforce device registration, sterility validation, and patient-labeling standards that determine market access for imported and locally assembled pens. These frameworks elevate compliance costs for new entrants while rewarding manufacturers with established quality management systems and regional regulatory dossiers. Stakeholders must monitor evolving Gulf harmonization initiatives and national health insurance expansion timelines that will reshape procurement centralization and pricing negotiations.
Market Dynamics
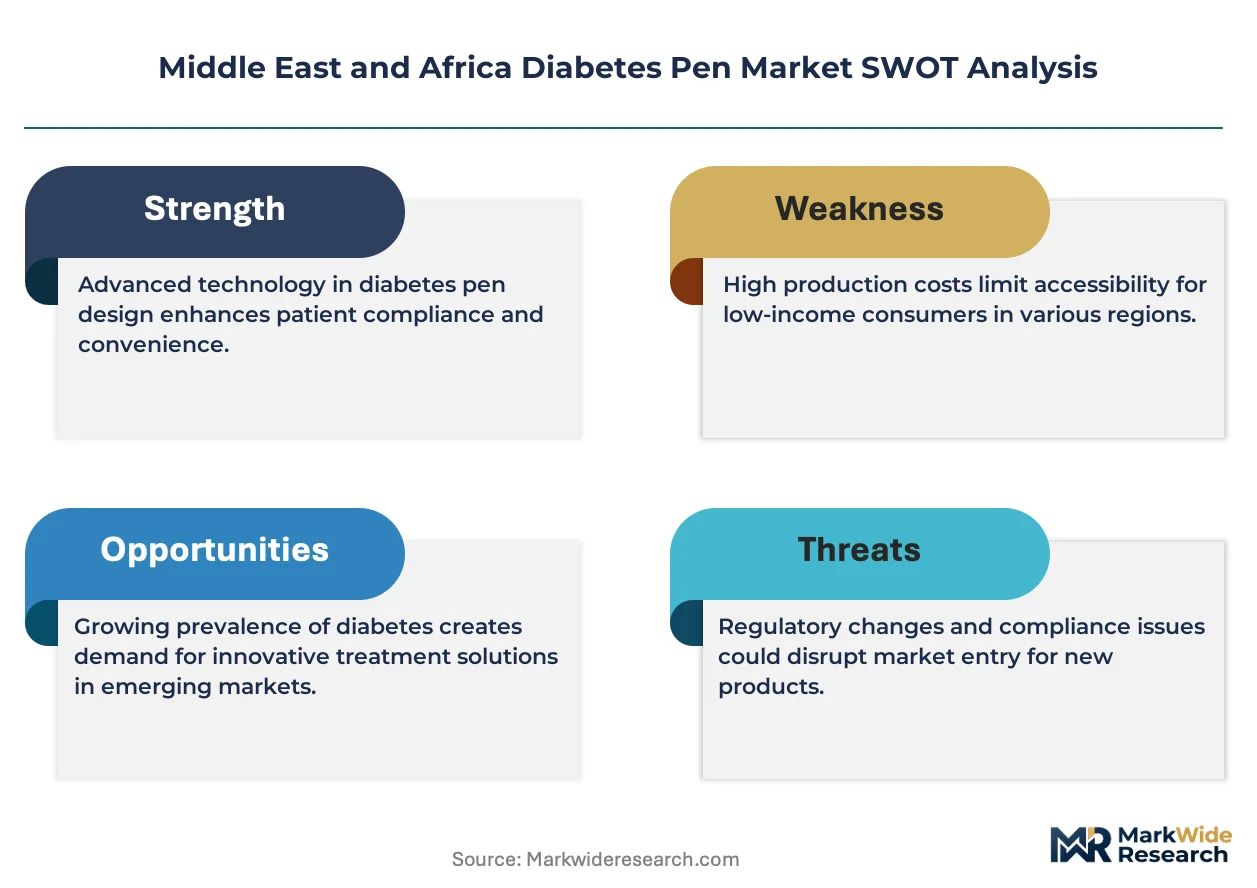
Reimbursement centralization across Gulf health authorities is compressing procurement cycles and elevating compliance thresholds for device registration, forcing manufacturers to consolidate distribution partnerships or exit secondary markets entirely.
Growth Catalysts
- SFDA Device Registration Mandates:Saudi Arabia's sterility validation and patient-labeling standards are filtering out uncertified imports, expanding addressable share for compliant reusable pen suppliers.
- Homecare Channel Expansion:Outpatient diabetes management reimbursement in South Africa and Morocco is redirecting volume from hospital pharmacies to direct-to-patient fulfillment models.
- Biologic Delivery Convergence:Glucagon-like peptide-1 therapies requiring pen-based administration are creating incremental demand pools beyond traditional insulin users.
Market Restraints
- Import Duty Volatility:Fluctuating tariffs on stainless steel pen needles and polymer cartridges elevate landed cost unpredictability for distributors serving Egypt and Nigeria.
- Single-Source Concentration:Gulf logistics corridors depend heavily on Dubai Jebel Ali port capacity, creating bottleneck exposure during peak pharmaceutical shipping seasons.
- Substitution by Vial-Syringe:Price-sensitive public hospital systems in Sudan and Ethiopia continue defaulting to conventional insulin delivery, capping pen penetration rates.
Strategic Opportunities
- Underpenetrated East African Markets:Kenya and Tanzania diabetes prevalence is climbing faster than pen supply infrastructure, opening first-mover positioning for localized assembly partnerships.
- Smart Pen Connectivity:Bluetooth-enabled dose logging is converging with telemedicine platforms, enabling remote glycemic monitoring subscriptions for UAE expatriate populations.
- South Africa National Health Insurance:NHI rollout timelines are reshaping tender specifications toward reusable devices with multi-year maintenance contracts.
Industry Challenges
- Regulatory Dossier Compilation:Divergent sterility testing protocols between SAHPRA and MOHAP extend product launch timelines by twelve to eighteen months for multi-market entrants.
- Specialized Field Service Networks:Patient training and device calibration requirements demand dedicated diabetes educator deployment, straining human resource availability in secondary Moroccan cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Diabetes Pen Market |
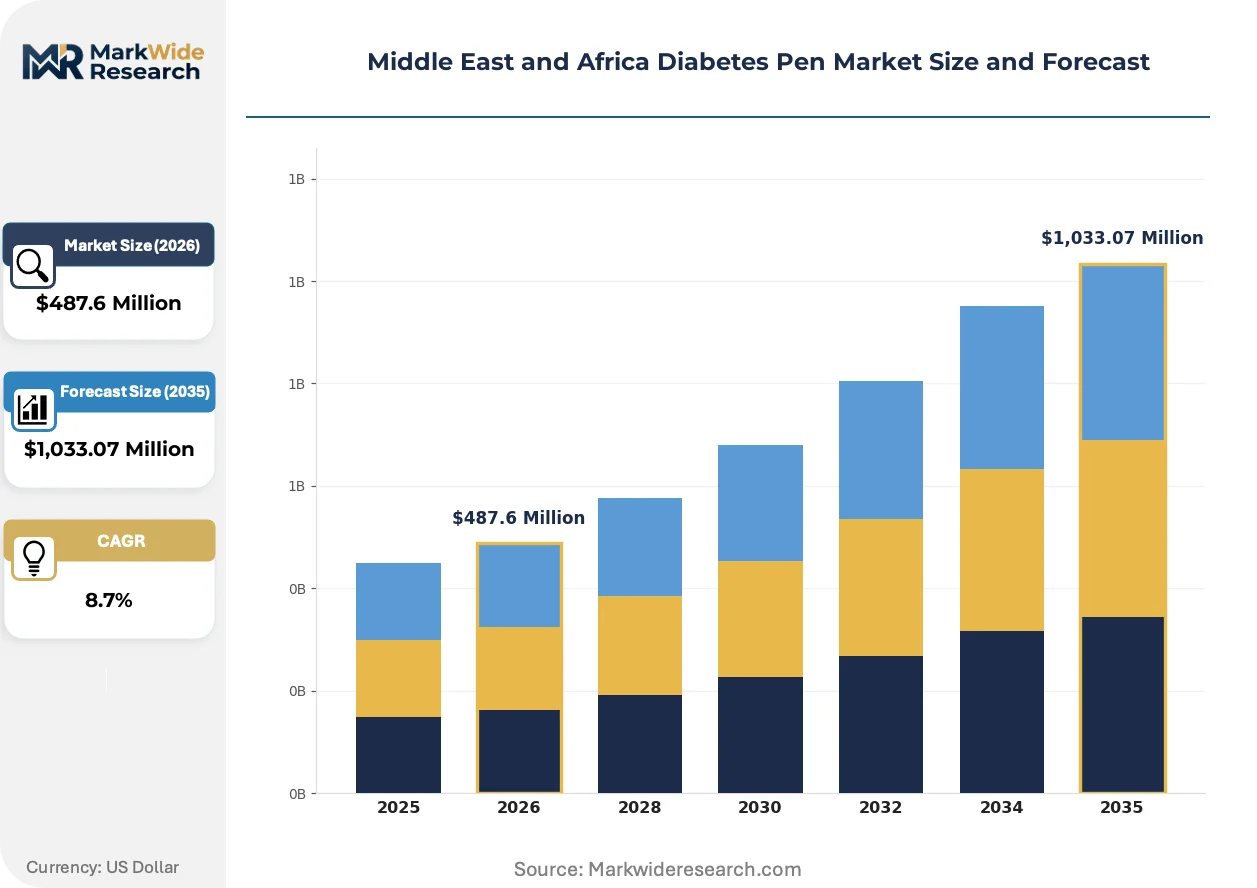
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Biologic Pens, Disposable Pens, Reusable Pens End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Subcutaneous Injection, Intramuscular Injection, Intravenous Injection, Oral Delivery Intervention Type: Preventive Therapy, Symptomatic Treatment, Patient Education, Health Monitoring |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Julphar, Biocon, Becton Dickinson and Company, Medtronic PLC, Roche Diabetes Care, Ypsomed AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Diabetes Pen Market Evolving Landscape
Device intelligence and sustainability mandates are restructuring competitive advantage around data integration and waste reduction rather than unit economics alone.
Connected dose-tracking technology is migrating from premium European markets to Gulf healthcare systems. Saudi hospital chains are piloting Bluetooth-enabled pens that transmit injection data to centralized electronic health records. This migration from standalone mechanical devices to networked delivery systems is compressing service contract margins while locking in multi-year platform subscriptions.
SFDA and UAE MOHAP are harmonizing medical device registration pathways through Gulf Cooperation Council mutual recognition protocols. This regulatory convergence reduces redundant testing costs for manufacturers with regional headquarters in Riyadh or Dubai. Disposable pen categories face accelerated scrutiny under these frameworks, prompting portfolio rebalancing toward reusable platforms with documented lifecycle assessments.
Patients across South Africa and Morocco are consolidating pharmacy relationships around chains offering integrated pen needle subscription programs. Independent community pharmacies are losing chronic disease foot traffic to retail health networks bundling device replenishment with glucose strip co-purchases. This channel consolidation is most visible in Johannesburg and Casablanca metropolitan zones where health insurer preferred provider networks steer reimbursement flows.
Middle East and Africa Diabetes Pen Market Segmentation
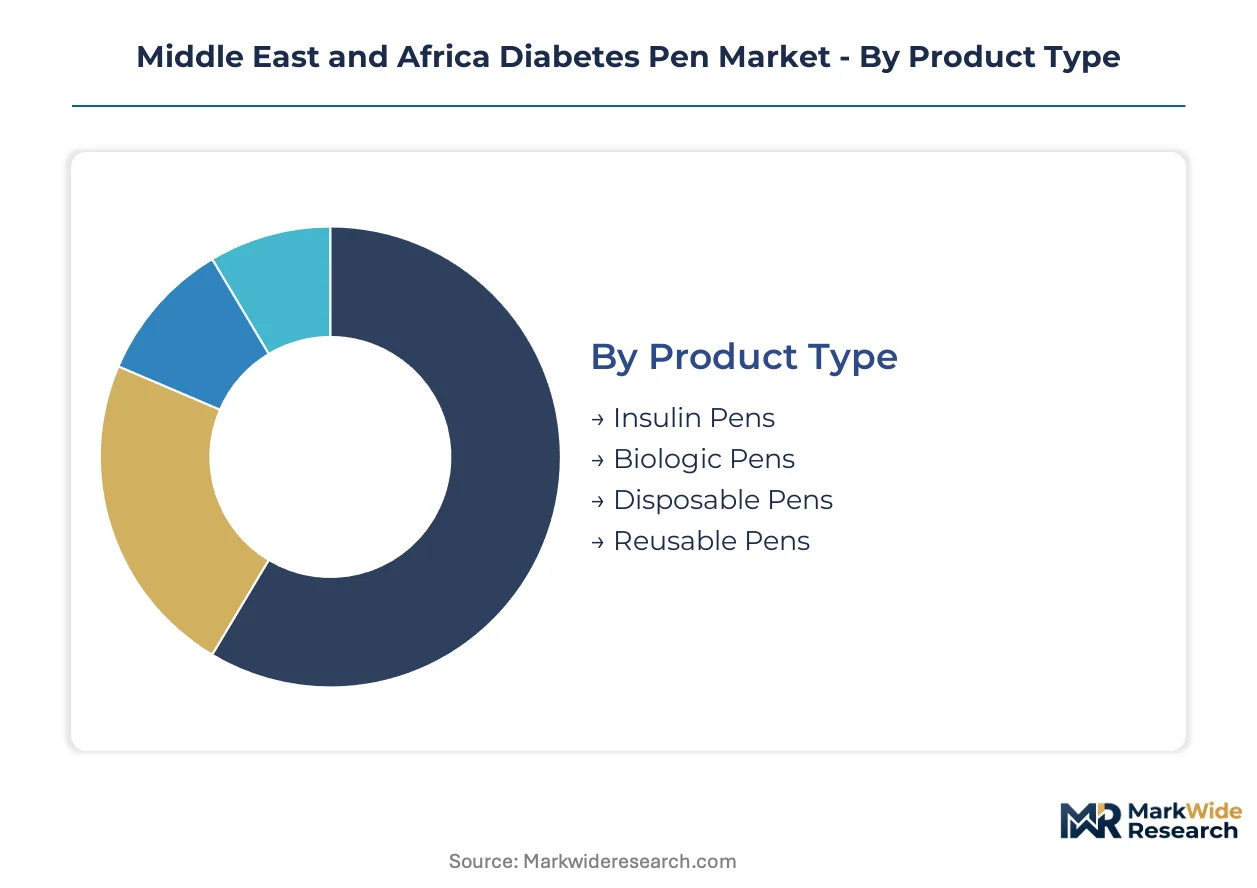
Diabetes pen segmentation in the Middle East and Africa reflects divergent reimbursement pathways, regulatory maturity, and patient self-management readiness across Gulf and sub-Saharan markets. Understanding how product configuration, care setting, delivery mechanism, and intervention philosophy partition demand enables manufacturers to align portfolio investments with procurement centralization trends and homecare expansion timelines.
Product Type:
Cost tier differentiation separates premium biologic-compatible systems from mass-market insulin delivery platforms, with sustainability mandates increasingly filtering procurement specifications.
- Insulin Pens:Spring-loaded mechanical devices with one-unit dose adjustment dials designed for U-100 insulin cartridge compatibility. Demand concentrates in Saudi hospital tenders and South African public sector contracts where volume procurement favors established needle attachment standards.
- Biologic Pens:Precision-engineered delivery systems for heat-sensitive peptide therapies requiring cold-chain integrity through injection. The steepest expansion runs through UAE specialist clinic networks and Egyptian private diabetes centers where glucagon-like peptide-1 adoption is accelerating.
- Disposable Pens:Pre-filled, single-use devices eliminating cartridge replacement and maintenance protocols. Preferred by Moroccan homecare programs and Nigerian retail pharmacy chains with limited field service infrastructure.
- Reusable Pens:Durable metal or polymer chassis accepting replaceable insulin cartridges across multi-year lifecycles. SFDA waste reduction directives and UAE medical device sustainability guidelines are elevating tender preferences for documented lifecycle assessment submissions.
Insulin pens command the established base. The steepest expansion runs through biologic pens.
End User:
Application setting determines service intensity, with reimbursement centralization redirecting volume from acute facilities toward ambulatory and direct-to-patient channels.
- Hospitals:Acute care facilities managing inpatient glycemic crises and perioperative insulin protocols. Procurement concentrates in Saudi Arabia's Ministry of Health central purchasing and South Africa's provincial health department tenders.
- Clinics:Outpatient specialty centers providing diabetes educator staffing and device training programs. Expansion accelerates in Casablanca and Lagos where insurer preferred provider networks are consolidating chronic disease management.
- Homecare:Patient-directed administration outside clinical supervision with telephone or telemedicine backup support. Fastest-growing trajectory across Johannesburg metropolitan zones and Moroccan urban corridors where reimbursement shifts favor outpatient management.
- Pharmacies:Retail and community dispensing points bundling device replenishment with glucose monitoring consumables. Chains in Dubai and Riyadh are capturing chronic disease foot traffic through integrated pen needle subscription models.
Hospitals command the established base. The steepest expansion runs through homecare.
Delivery Mode:
Volume concentration in subcutaneous platforms reflects diabetes pharmacology requirements, with alternative routes serving niche therapeutic categories.
- Subcutaneous Injection:Abdominal, thigh, or upper arm tissue deposition using 4-6mm pen needles optimized for insulin and peptide absorption kinetics. Dominates across all product categories and geographies within the regional scope.
- Intramuscular Injection:Deeper tissue penetration for rapid-acting insulin analogues in acute hyperglycemic episodes. Limited to hospital emergency departments and specialized diabetes centers in Cairo and Nairobi.
- Intravenous Injection:Direct vascular delivery reserved for perioperative and intensive care glycemic management. Restricted to tertiary hospital pharmacy compounding units with sterile preparation capabilities.
- Oral Delivery:Non-injectable alternatives including fixed-dose combination tablets and emerging peptide permeation technologies. Captures price-sensitive segments in Sudan and Ethiopia where pen penetration faces vial-syringe substitution pressure.
Subcutaneous injection commands the established base. The steepest expansion runs through intramuscular injection in acute care settings.
Intervention Type:
Customer type orientation distinguishes acute therapeutic response from longitudinal disease management, with education and monitoring services emerging as platform differentiation vectors.
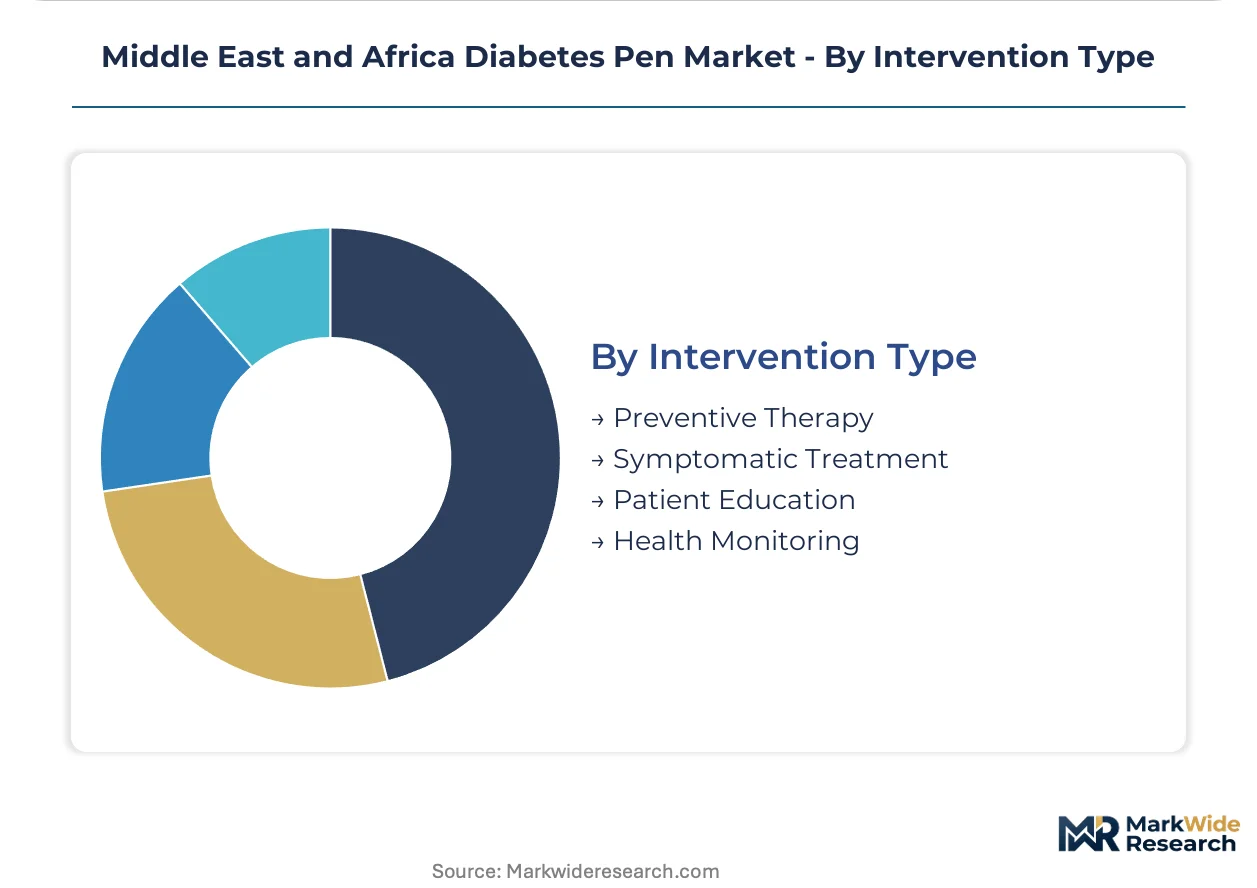
- Preventive Therapy:Early insulin initiation and lifestyle modification protocols targeting prediabetes progression. Expanding through UAE employer-sponsored screening programs and South African health insurer wellness incentives.
- Symptomatic Treatment:Glycemic crisis intervention and complication management in established diabetes populations. Concentrates in Egyptian public hospitals and Nigerian federal medical centers with high patient acuity.
- Patient Education:Structured training on dose calculation, injection technique, and hypoglycemia recognition. Required by SFDA and SAHPRA device registration frameworks, creating dedicated educator deployment demand.
- Health Monitoring:Integrated glucose logging, dose tracking, and telemedicine connectivity. Bluetooth-enabled pens are piloting in Saudi hospital chains with electronic health record integration mandates.
Symptomatic treatment commands the established base. The steepest expansion runs through health monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Middle East and Africa diabetes pen market. Gulf Cooperation Council buyers prioritize device certification and connectivity features over unit cost. Sub-Saharan public health systems remain acutely sensitive to landed price, driving vial-syringe substitution in lower-tier facilities.
Saudi Arabia
SFDA sterility validation mandates and medical waste reduction targets are elevating tender preferences for reusable pen platforms. The Riyadh-based central procurement authority compresses contract cycles while demanding documented lifecycle assessments. Eastern Province hospital clusters are piloting Bluetooth-enabled dose tracking integrated with national electronic health record systems.
United Arab Emirates
MOHAP device registration harmonization with Gulf Cooperation Council protocols is reducing redundant testing costs for manufacturers with Dubai headquarters. Expatriate populations in Abu Dhabi are driving demand for smart pen connectivity bundled with telemedicine subscriptions. Jebel Ali logistics corridors handle peak pharmaceutical shipping volumes, creating concentrated distribution dependency.
South Africa
SAHPRA quality protocols and National Health Insurance rollout timelines are reshaping specifications toward reusable devices with multi-year maintenance contracts. Johannesburg metropolitan pharmacy chains are consolidating chronic disease foot traffic through integrated pen needle subscription models. Provincial health department tenders dominate public sector volume procurement.
Egypt
Private diabetes center expansion in Cairo is accelerating glucagon-like peptide-1 delivery device adoption beyond traditional insulin populations. The national pharmaceutical regulator maintains sterility validation requirements that extend product launch timelines for imported platforms. Nile Delta clinic networks are capturing outpatient volume as reimbursement shifts favor ambulatory management.
Nigeria
Federal medical center procurement concentrates symptomatic treatment demand for acute glycemic crisis intervention. Import duty volatility on polymer cartridges elevates landed cost unpredictability for distributors serving Lagos retail pharmacy chains. Price-sensitive public hospital systems continue defaulting to conventional insulin delivery, capping pen penetration rates.
Middle East and Africa Diabetes Pen Market Competitive Landscape
Capability concentration sits with manufacturers holding Gulf-based logistics infrastructure and direct hospital chain relationships; scale advantage sits with multinational pharmaceutical groups with biologic pen portfolios. The market structure tiers into three archetypes: integrated diabetes care platforms with educator networks, regional manufacturing specialists with Gulf Cooperation Council market access, and disposable pen suppliers serving price-sensitive sub-Saharan channels. Dominant competitive moves include distribution partnership consolidation to meet tightening procurement centralization, and portfolio rebalancing toward reusable platforms with documented lifecycle assessments.
Among European-headquartered integrated diabetes care platforms, Novo Nordisk A/S and Sanofi occupy positions exemplifying the capability-concentrated tier with established Gulf logistics hubs and direct hospital chain replenishment contracts. Eli Lilly and Company represents the biologic pen portfolio archetype, while Julphar anchors regional manufacturing specialization through its Ras Al Khaimah facility serving Gulf Cooperation Council markets. These three named entities collectively illustrate the competitive segmentation between multinational scale advantages and regional manufacturing proximity.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Julphar |
| Biocon |
| Becton Dickinson and Company |
| Medtronic PLC |
| Roche Diabetes Care |
| Ypsomed AG |
| Others |
Value Network & Pricing Analysis
Stainless steel pen needle manufacturing concentrates in East Asian fabrication hubs, anchoring margin capture downstream with distributors serving Gulf hospital chains and South African retail pharmacy networks. This upstream concentration forces procurement managers to absorb landed cost volatility through inventory hedging or contract renegotiation cycles.
Pricing Analysis
Aftermarket service revenue from patient training programs and multi-year maintenance contracts drives lifetime value differentiation. Three-tier pricing structure across premium connected devices, standard reusable platforms, and economy disposable pens separates Novo Nordisk's Bluetooth-enabled systems from Julphar's GCC-manufactured alternatives. Cost compression in the economy tier intensifies because import duty volatility on polymer cartridges elevates landed cost unpredictability for Nigerian distributors. Public hospital systems in Sudan and Ethiopia exhibit acute price sensitivity, while UAE specialist clinics demonstrate low sensitivity to unit cost when connectivity features are bundled.
Supply Chain Analysis
Medical device export-control regimes limiting smart pen technology flows constrain Bluetooth-enabled platform availability in sub-Saharan markets. Component sourcing draws from Chinese polymer cartridge suppliers, German precision spring manufacturers, and Indian stainless steel needle fabricators. Single-source vulnerability concentrates at Dubai Jebel Ali port capacity, creating bottleneck exposure during peak pharmaceutical shipping seasons. Distribution runs through Gulf-based logistics hubs serving Saudi hospital chains, direct-to-patient fulfillment models in South Africa, and retail pharmacy networks in Morocco.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa diabetes pen market is entering a cyclical recovery phase. Homecare reimbursement expansion across South Africa and Morocco is rebuilding volume growth after procurement centralization compressed contract cycles.
For Market Incumbents: Build regulatory dossier depth as a moat against SAHPRA-SFDA protocol divergence. Consolidate distribution partnerships to meet Gulf health authority tender centralization requirements. Defend against vial-syringe substitution pressure in Sudan and Ethiopia by embedding educator networks within provincial health departments. Deepen backward integration into polymer cartridge production to offset import duty volatility exposure. For New Entrants and Emerging Players: Pursue localized assembly partnerships in Kenya and Tanzania where diabetes prevalence climbs faster than pen supply infrastructure. Target East African clinic networks as the most penetrable geography given first-mover positioning availability. Enter through smart pen connectivity pilots bundled with telemedicine platforms serving UAE expatriate populations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected dose-tracking device manufacturing due to Bluetooth module integration and software validation requirements. Long-term viability favors manufacturers with Gulf-based logistics infrastructure and direct hospital chain replenishment contracts. Acquisition target archetype: regional manufacturing specialists with GCC market access and established MOHAP registration dossiers. Signal to watch: Gulf Cooperation Council mutual recognition protocol implementation timelines accelerating product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Dossier Investment | Accelerates market access for reusable pen platforms in Saudi hospital tenders. |
| Gulf Logistics Hub Consolidation | Compresses replenishment cycles for Dubai-serving manufacturers with Jebel Ali capacity. |
| Bluetooth-Enabled Pen Pilot Programs | Locks in multi-year platform subscriptions with Saudi electronic health record mandates. |
| East African Localized Assembly Partnership | Reduces landed cost exposure for Kenya and Tanzania clinic network penetration. |
| Patient Educator Network Deployment | Meets SAHPRA device registration requirements while capturing Moroccan homecare volume. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, diabetes educators, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary interviews with Saudi Ministry of Health central purchasing authorities, UAE MOHAP regulatory affairs leads, and South African provincial health department formulary directors supplied ground-level procurement intelligence. Secondary sources included SFDA device registration databases, SAHPRA quality protocol filings, Gulf Cooperation Council trade statistics, and hospital procurement tender records. Bottom-up volume estimates from individual country demand profiles were triangulated against top-down market sizing from regional healthcare expenditure trends.
Demand-supply balance modeling anchored forecast outputs across the analysis window. Segmentation dimensions encompassed product type tiers, end-user settings, delivery mechanisms, and intervention philosophies alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis against diabetes prevalence trajectories, reimbursement policy timelines, and medical device import growth patterns. Industry-specific inputs included SFDA waste reduction directive implementation schedules and South Africa National Health Insurance rollout phasing assumptions.
Sensitivities concentrate around Gulf harmonization initiative acceleration, NHI procurement specification shifts, and smart pen connectivity adoption curves. Forecasts reflect documented assumptions regarding sterility validation protocol convergence and homecare channel reimbursement expansion. Material shifts in import duty regimes or Jebel Ali port capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Gestational Diabetes Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Diabetic Gastroparesis Treatment Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Global Non-Invasive Glucose Meter Market