
 South Africa Oral Antidiabetic Drug Market | 2026-2036
South Africa Oral Antidiabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Oral Antidiabetic Drug Market Insights
Public sector buyer concentration is rebalancing as provincial health departments consolidate tender awards into fewer, larger-volume contracts. Novo Nordisk leverages its insulin portfolio to sustain institutional supply relationships across South Africa's academic hospital complexes. Sanofi anchors its position through broad-spectrum sulfonylurea availability in both public and private channels. Aspen Pharmacare competes on localized manufacturing scale, producing finished dosage forms at its Gqeberha facility for regional distribution.
Oral antidiabetic drugs comprise pharmacological agents administered by mouth to lower blood glucose through mechanisms including hepatic glucose suppression, insulin secretion enhancement, or renal glucose excretion inhibition; these formulations typically contain active pharmaceutical ingredients such as metformin hydrochloride, glimepiride, or empagliflozin combined with excipients for tablet compression or coating stability. SGLT2 inhibitors represent the fastest-expanding drug class as nephroprotective labeling expands prescriber preference beyond glycemic control alone. Retail pharmacies capture the dominant distribution channel margin pool due to direct patient co-payment collection and chronic medication dispensing frequency. Tablet formulations maintain volume leadership while coated variants command premium positioning in private insurance reimbursement tiers.
SAHPRA governs product registration and post-market surveillance, requiring bioequivalence documentation for generic substitutions that shapes competitive entry timelines. The National Essential Medicines List Committee determines public sector reimbursement inclusion, directly constraining which drug classes penetrate township clinics and district hospitals. Stakeholders must monitor SAHPRA's evolving biosimilar guidance and provincial tender consolidation to align portfolio investments with shifting access pathways.
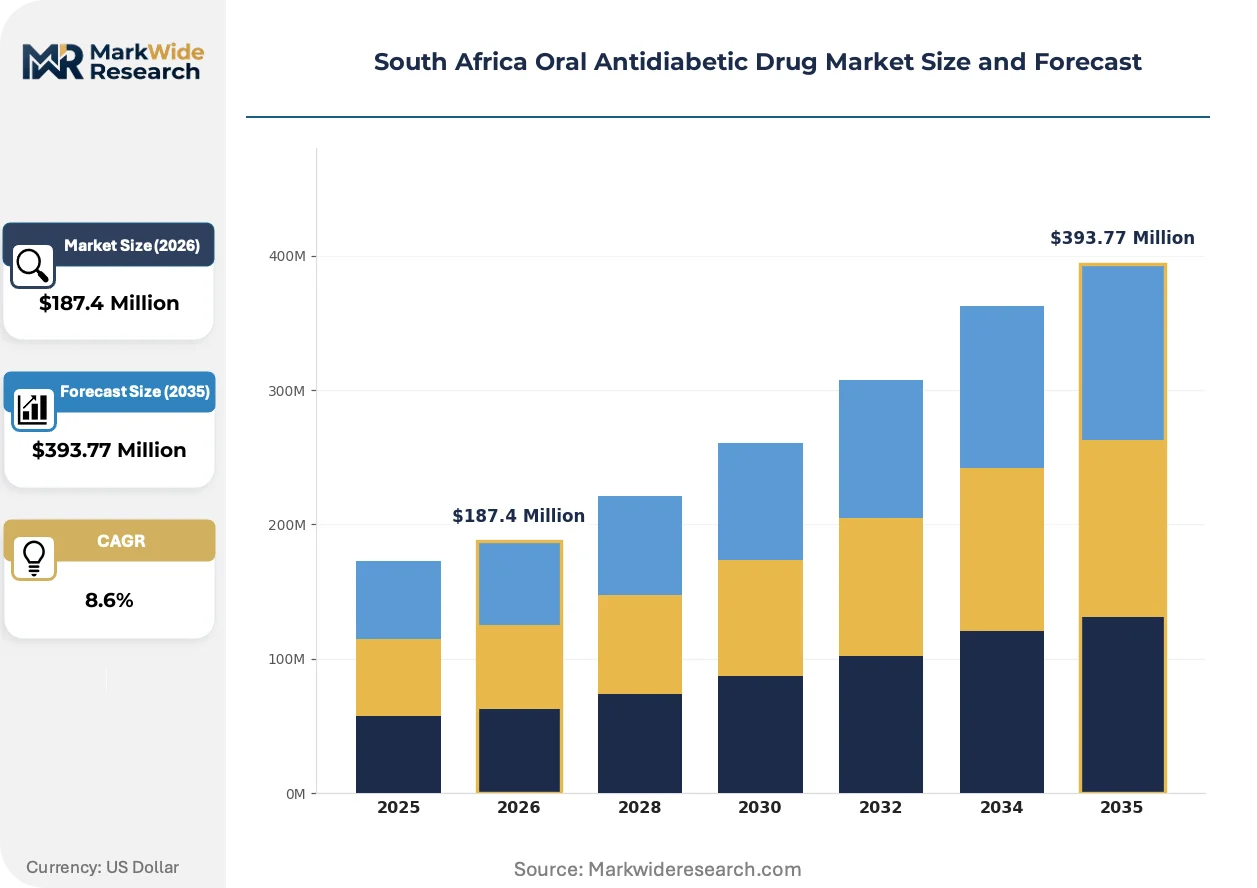
Market Dynamics
Provincial tender consolidation across Gauteng and KwaZulu-Natal is compressing supplier margins while amplifying volume commitments for winning bidders in South Africa's public hospital networks.
Growth Catalysts
- SAHPRA Biosimilar Pathways:Streamlined registration for insulin analogues accelerates competitive entry and expands therapeutic access in public sector formularies.
- Urban Township Demand Density:Type 2 diabetes prevalence concentrates in peri-urban corridors, creating predictable chronic medication dispensing volumes for retail pharmacy networks.
- SGLT2 Nephroprotective Labeling:Expanded prescriber indications beyond glycemic control alone drive therapeutic class switching in private insurance tiers.
Market Restraints
- Active Pharmaceutical Ingredient Import Dependency:South African manufacturers rely on imported metformin hydrochloride and empagliflozin intermediates, exposing margins to currency volatility.
- Public Sector Reimbursement Caps:National Essential Medicines List Committee exclusions constrain which drug classes penetrate district hospitals and township clinics.
- Biologic Cold Chain Infrastructure Gaps:Temperature-controlled distribution limitations outside major metros restrict insulin analogue penetration into rural provinces.
Strategic Opportunities
- Eastern Cape Manufacturing Localization:Aspen Pharmacare's Gqeberha facility offers regional finished dosage production scale for SADC export qualification.
- Retail Pharmacy Chronic Dispensing:Direct patient co-payment collection at community pharmacies captures margin pools unavailable in public tender channels.
- Coated Tablet Premium Positioning:Modified-release formulations command differential reimbursement tiers within private health insurance formularies.
Industry Challenges
- Bioequivalence Documentation Burden:Generic substitution requirements demand costly clinical validation timelines that delay market entry for new entrants.
- Provincial Tender Coordination Complexity:Consolidated award mechanisms require simultaneous compliance with divergent procurement specifications across Gauteng and KwaZulu-Natal health departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Oral Antidiabetic Drug Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Biguanides, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Formulation Type: Tablets, Granules, Oral Solutions, Coated Tablets Patient Demographics: Type 2 Diabetes, Gestational Diabetes, Elderly Patients, Obese Patients Distribution Channel: Retail Pharmacies, Hospitals, Online Pharmacies, Wholesalers |
| Companies Covered | Novo Nordisk, Sanofi, AstraZeneca, Eli Lilly and Company, Merck & Co., Boehringer Ingelheim, Takeda Pharmaceutical, Aspen Pharmacare, Novartis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Oral Antidiabetic Drug Market Trends and Innovations
Fixed-dose combination therapies are compressing pill burden while renal protective prescribing protocols expand addressable patient populations beyond traditional glycemic targets.
Single-tablet combinations of metformin with SGLT2 inhibitors are unifying previously separate therapeutic categories into unified daily regimens. Private specialists in Johannesburg and Cape Town academic complexes are adopting these formulations at accelerating rates. This convergence is unifying prescriber preference around simplified adherence protocols while compressing standalone sulfonylurea volumes.
SAHPRA's evolving biosimilar guidance is tightening bioequivalence documentation requirements for insulin analogue substitutions. The regulatory tightening extends clinical validation timelines for new market entrants. Local manufacturers are responding by prioritizing portfolio investments toward small-molecule oral agents with established generic pathways.
Direct-to-patient chronic medication delivery is fragmenting traditional wholesale pharmacy dependencies. Retail chains in urban townships are deploying subscription-based dispensing models that bypass hospital pharmacy queues. This channel innovation is most visible in Gauteng peri-urban corridors where patient transport costs to centralized facilities remain prohibitive.
South Africa Oral Antidiabetic Drug Market Segmentation
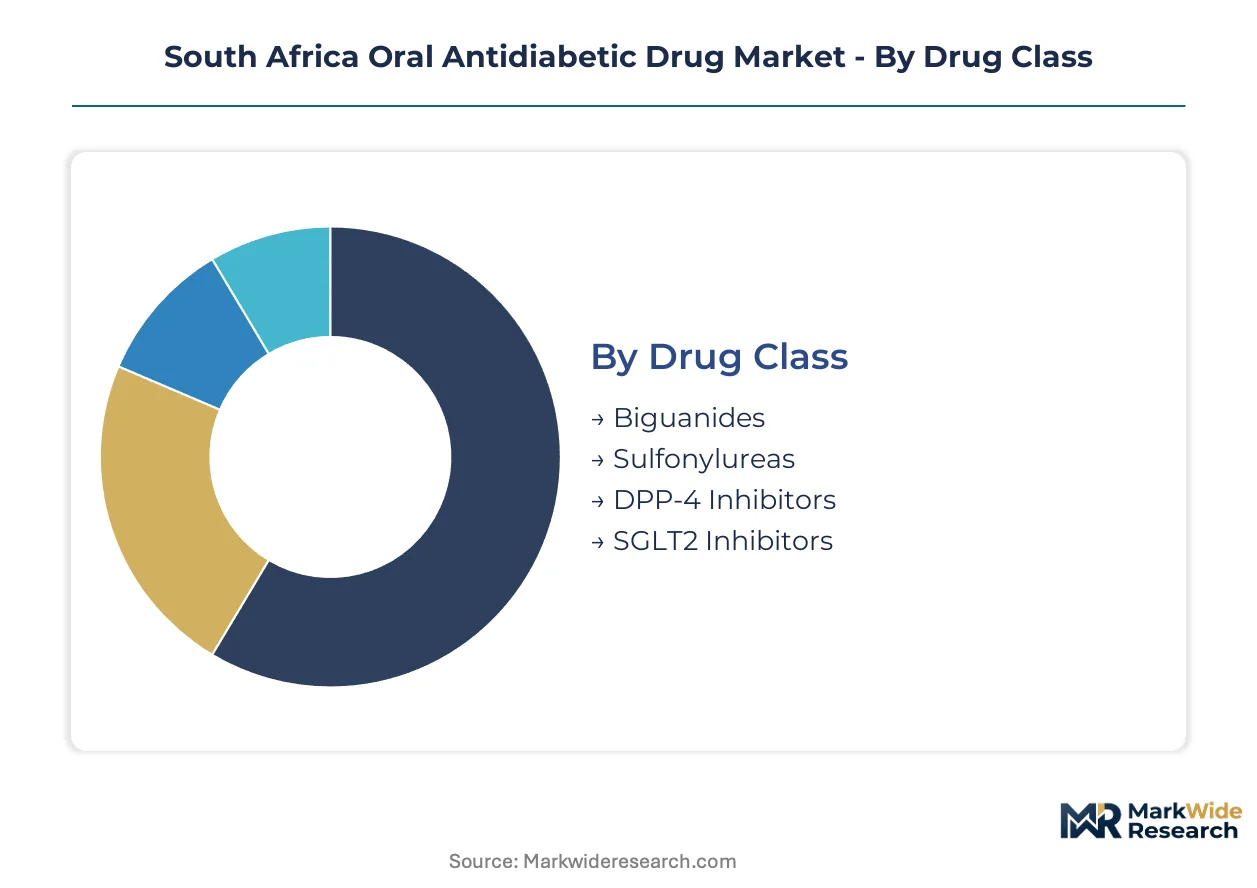
Drug class distinctions determine SAHPRA registration pathways and provincial tender eligibility, while formulation choices shape reimbursement tier placement and patient adherence economics. Each segmentation axis carries distinct regulatory, commercial, and clinical implications for portfolio positioning.
Drug Class:
Biguanides and SGLT2 inhibitors carry the heaviest bioequivalence documentation burdens under SAHPRA's tightened generic substitution protocols, whereas sulfonylureas navigate established abbreviated pathways.
- Biguanides:Metformin hydrochloride formulations dominate public sector procurement volumes through National Essential Medicines List inclusion. Demand concentrates in Gauteng and KwaZulu-Natal township clinics where first-line therapy protocols drive predictable dispensing frequency.
- SGLT2 Inhibitors:Empagliflozin and dapagliflozin analogues command premium private insurance reimbursement following nephroprotective label expansion. Prescriber adoption accelerates in Johannesburg academic hospital complexes where renal protective protocols extend beyond glycemic targets.
- Sulfonylureas:Glimepiride maintains broad availability across both public tender and private retail channels with streamlined generic substitution.
- DPP-4 Inhibitors:Sitagliptin formulations occupy intermediate reimbursement tiers with restricted access in district hospital formularies.
Biguanides sit at the top of the volume ranking, with SGLT2 inhibitors climbing the fastest.
Formulation Type:
Cost tiers separate commodity tablet production from modified-release coated variants that capture differential private insurance margins.
- Tablets:Immediate-release metformin and glimepiride tablets constitute the procurement backbone for public hospital networks. Manufacturing concentrates at Aspen Pharmacare's Gqeberha facility with SADC export qualification potential.
- Coated Tablets:Enteric-coated and sustained-release formulations reduce gastrointestinal adverse events while qualifying for premium reimbursement tiers. Private specialists in Cape Town academic complexes prescribe these variants at accelerating rates for patient adherence optimization.
- Granules:Pediatric and geriatric dosing flexibility supports niche positioning where swallowing difficulties limit standard tablet use.
- Oral Solutions:Liquid formulations serve institutional settings and patients with dysphagia, though cold chain requirements constrain rural distribution.
Standard tablets generate the highest absolute volumes, while coated variants deliver the steepest margin expansion trajectory.
Patient Demographics:
Application-driven segmentation aligns therapeutic selection with comorbidity profiles and age-specific metabolic considerations.
- Type 2 Diabetes:The predominant addressable population concentrates in peri-urban corridors across Gauteng and Eastern Cape provinces. Urban township density creates predictable chronic medication dispensing patterns for retail pharmacy networks.
- Obese Patients:SGLT2 inhibitor preference intensifies among this cohort due to concurrent weight reduction benefits. Endocrinology practices in Johannesburg and Cape Town academic complexes prioritize these agents for metabolic syndrome management.
- Elderly Patients:Hypoglycemia risk considerations drive sulfonylurea avoidance and DPP-4 inhibitor selection in geriatric protocols.
- Gestational Diabetes:Insulin-first protocols limit oral agent penetration, though metformin retains restricted off-label utilization in select private settings.
Type 2 diabetes accounts for the dominant patient volume base, with obese patient targeting gaining share fastest as SGLT2 protocols expand.
Distribution Channel:
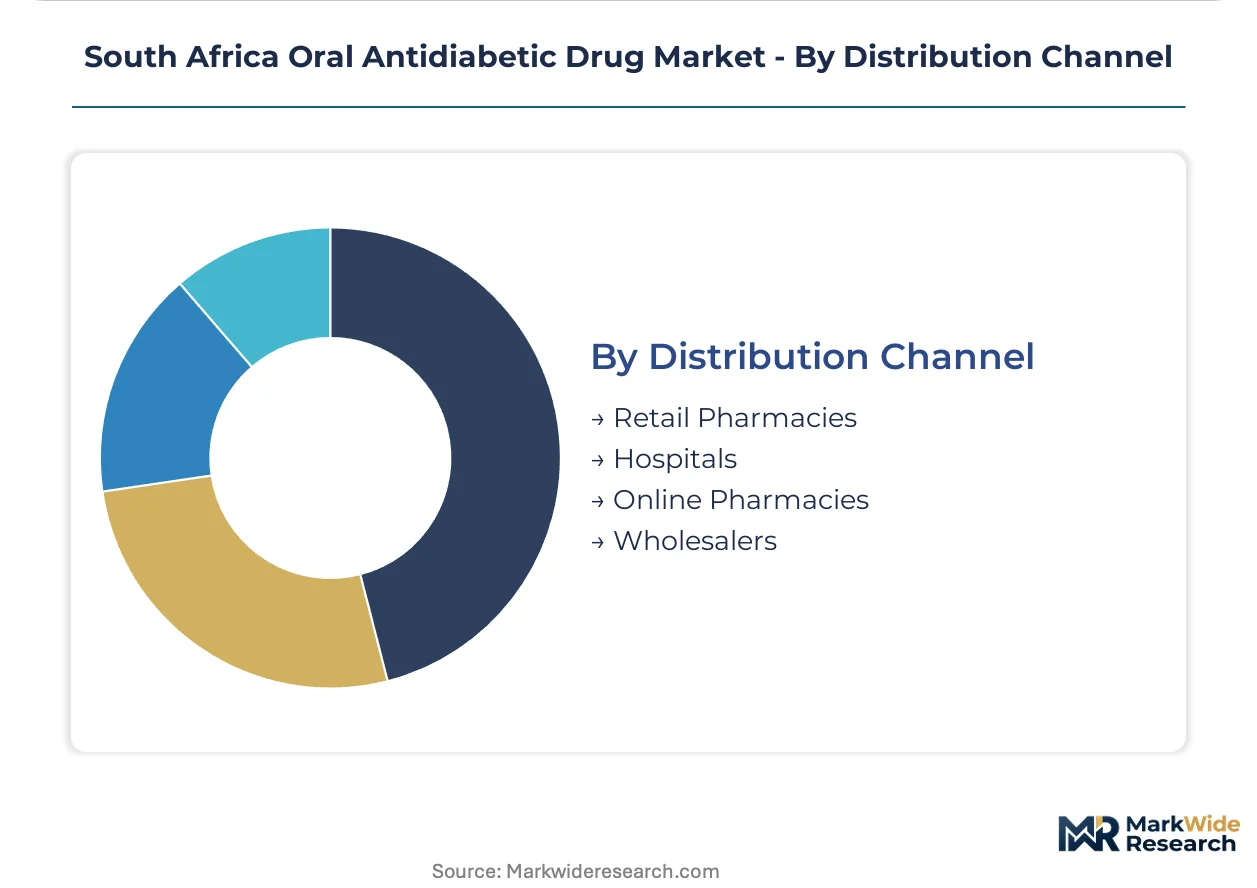
Customer type differentiation separates institutional procurement from direct-to-patient retail economics and emerging subscription-based delivery models.
- Retail Pharmacies:Community pharmacies in urban townships capture margin pools through direct patient co-payment collection. Chronic medication dispensing frequency supports subscription-based models that bypass hospital pharmacy queues in Gauteng peri-urban corridors.
- Hospitals:Academic hospital complexes anchor institutional prescribing influence that shapes downstream retail demand. Provincial tender consolidation across Gauteng and KwaZulu-Natal compresses supplier margins while amplifying volume commitments.
- Online Pharmacies:Direct-to-patient delivery fragments traditional wholesale dependencies, though regulatory clarity on prescription verification remains evolving.
- Wholesalers:Regional distribution networks service rural provinces where temperature-controlled infrastructure gaps restrict insulin analogue penetration.
Retail pharmacies command the highest margin capture, with hospital procurement driving the greatest volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's oral antidiabetic market diverges sharply from Nigeria's fragmented procurement landscape, where federal-state coordination failures delay formulary harmonization. Provincial consolidation in Gauteng and KwaZulu-Natal creates concentrated demand nodes that multinational suppliers target with volume-tiered contracting.
Gauteng Province
Urban township corridors around Johannesburg and Pretoria generate the highest Type 2 diabetes patient density in sub-Saharan Africa. The National Essential Medicines List Committee mandates metformin-first protocols in public clinics, restricting newer drug class penetration. Academic hospital complexes in Johannesburg anchor prescriber influence that shapes downstream retail pharmacy demand across the province.
KwaZulu-Natal
Peri-urban corridors between Durban and Pietermaritzburg concentrate chronic medication dispensing volumes for retail networks. Provincial tender consolidation compresses supplier margins while amplifying volume commitments for winning bidders. The eThekwini metropolitan distribution hub struggles with temperature-controlled infrastructure gaps that limit insulin analogue rural penetration.
Eastern Cape
Aspen Pharmacare's Gqeberha facility anchors localized finished dosage production for regional SADC export qualification. District hospitals in former Transkei regions face procurement delays due to transport infrastructure deficits. The Port Elizabeth-Gqeberha corridor attracts logistics investment targeting pharmacy-led chronic dispensing models.
Western Cape
Private insurance reimbursement tiers in Cape Town academic complexes drive premium-coated tablet adoption for patient adherence optimization. The provincial health department maintains stricter formulary controls than Gauteng, limiting SGLT2 inhibitor access in public clinics. Stellenbosch University medical research partnerships influence nephroprotective prescribing protocol development.
South Africa Oral Antidiabetic Drug Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Africa's oral antidiabetic market. The supplier base organizes around three strategic archetypes: multinational pharmaceutical corporations with insulin-to-oral portfolios, regional African manufacturers leveraging localized production scale, and generic specialists navigating SAHPRA bioequivalence pathways. Consolidation pressures intensify as provincial tender mechanisms favor fewer, larger-volume contract awards. Competitive positioning hinges on regulatory navigation speed and cold chain distribution reach into peri-urban corridors.
Among multinational developers, Novo Nordisk and Sanofi occupy positions exemplifying portfolio breadth strategies that span insulin analogues through oral agent categories. Aspen Pharmacare represents the regional manufacturing archetype, with its Gqeberha facility anchoring SADC export-oriented production scale. These three entities illustrate divergent pathways for market access: regulatory sophistication, localized manufacturing leverage, and therapeutic category span.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| AstraZeneca |
| Eli Lilly and Company |
| Merck & Co. |
| Boehringer Ingelheim |
| Takeda Pharmaceutical |
| Aspen Pharmacare |
| Novartis |
| Others |
Pricing and Supply Chain Analysis
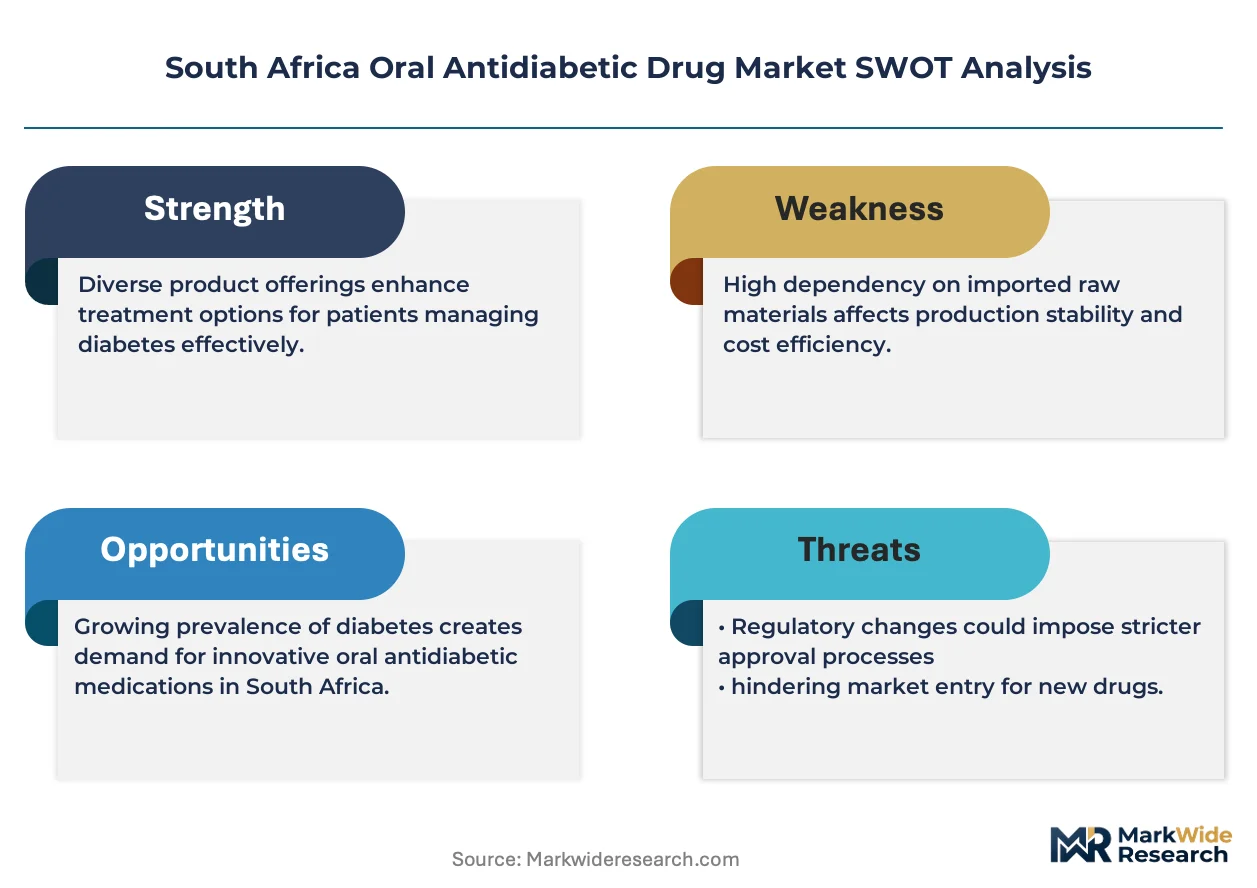
Metformin hydrochloride API price indices from Indian and Chinese bulk chemical markets cascade through South Africa's oral antidiabetic supply chain, compressing margin structures for finished dosage manufacturers while amplifying cost pass-through pressures into public tender pricing tiers.
Pricing Analysis
Capacity additions in India's API manufacturing corridors are reshaping price floors for biguanide intermediates, forcing South African formulators into three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SAHPRA bioequivalence certification tier and volume scale commitments to provincial health departments. Pricing pressure stems from consolidated Gauteng and KwaZulu-Natal tender awards that amplify buyer leverage. Public sector procurement managers exhibit highest price sensitivity, while private insurance formularies absorb premium-coated tablet markups.
Supply Chain Analysis
Pharmaceutical chemistry expertise concentration in Hyderabad and Shanghai shapes South Africa's API sourcing patterns, with local Gqeberha facilities dependent on imported metformin hydrochloride, empagliflozin intermediates, and glimepiride precursors. Raw material feeds from these geographies face tariff exposure under evolving SADC-EU trade protocols. Distribution runs through Johannesburg cold storage hubs before radiating to peri-urban township pharmacies, with temperature-controlled gaps beyond eThekwini limiting insulin analogue rural reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's oral antidiabetic market offers margin expansion through SGLT2 nephroprotective tier migration and API import cost compression, with coated tablet premiums widening as private insurance formularies reward adherence-optimized formulations.
For Market Incumbents: To counter provincial tender consolidation squeezing supplier margins, Novo Nordisk and Sanofi should deepen backward integration into API sourcing through Indian partnership structures, while accelerating SAHPRA biosimilar documentation investments to defend formulary positioning against emerging generic entrants. For New Entrants and Emerging Players: Launch via direct-to-patient subscription dispensing models in Gauteng peri-urban corridors where hospital pharmacy queue avoidance commands patient willingness-to-pay. Target Eastern Cape district hospitals with SADC-export-qualified Gqeberha manufacturing partnerships, exploiting underpenetrated rural chronic medication channels outside temperature-controlled infrastructure constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where provincial tender mechanisms favor fewer, larger-volume contract awards across Gauteng and KwaZulu-Natal health departments. Mid-scale generic manufacturers with established SAHPRA bioequivalence pathways represent priority acquisition archetypes over the coming decade. Watch SAHPRA's evolving biosimilar guidance tightening as the critical inflection signal for portfolio repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Biosimilar Pathway Advancement | Accelerates competitive entry timelines for insulin analogues into public sector formularies. |
| Provincial Tender Volume Consolidation | Compresses supplier margins while amplifying commitment security for winning bidders in Gauteng. |
| Coated Tablet Premium Tier Introduction | Captures differential private insurance reimbursement through adherence-optimized formulation positioning. |
| Direct-to-Patient Subscription Launch | Bypasses hospital pharmacy queues in peri-urban corridors with prohibitive patient transport costs. |
| Eastern Cape Manufacturing Scale-Up | Qualifies regional SADC export access through Aspen Pharmacare's Gqeberha finished dosage facility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulary directors at Gauteng and KwaZulu-Natal health departments, procurement managers at academic hospital complexes, retail pharmacy chain operators, and SAHPRA regulatory affairs specialists with secondary validation against National Essential Medicines List Committee publications, SAHPRA registration databases, provincial tender award records, and SADC pharmaceutical trade statistics. Bottom-up patient volume modeling and top-down market sizing triangulated around manufacturer shipment data.
Segment-weighting applied drug class, formulation type, and distribution channel dimensions across the analysis window, with patient demographic overlays for comorbidity targeting. CAGRs derived from trend extrapolation of dispensing frequency patterns and therapeutic class switching rates calibrated against provincial health expenditure forecasts. Forecast inputs incorporated SAHPRA regulatory timeline assumptions and API price index volatility from Indian bulk chemical markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained currency depreciation or abrupt SAHPRA bioequivalence requirement shifts. Projections reflect documented assumptions regarding tender consolidation pace and SGLT2 nephroprotective protocol adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
India Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
France Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Mexico Diabetes Medication Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Blood Glucose Monitoring Devices Market