
 Digital Diabetes Management Market | 2026-2036
Digital Diabetes Management Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Diabetes Management Market Analysis
The EU Green Deal is rebalancing procurement criteria across European healthcare systems toward connected care platforms with lower carbon footprints in manufacturing and disposal. Dexcom leverages its vertically integrated sensor production to sustain margin control across European distribution channels. Abbott anchors its competitive position through Libre platform scale, while Medtronic competes in automated insulin delivery with its MiniMed ecosystem.
Digital diabetes management encompasses software-enabled devices and platforms that collect, transmit, and analyze glycemic data to guide therapeutic decisions, typically incorporating Bluetooth-enabled sensors, algorithm-driven mobile interfaces, and cloud-based analytics operating at measurement intervals of one to five minutes. Continuous glucose monitoring systems command the largest revenue share within product type segmentation due to recurring sensor replacement cycles and premium reimbursement tiers. Wearable devices within the technology dimension are expanding fastest as form factors shrink and battery life extends, while patient education applications remain underdeveloped relative to monitoring and insulin delivery functions.
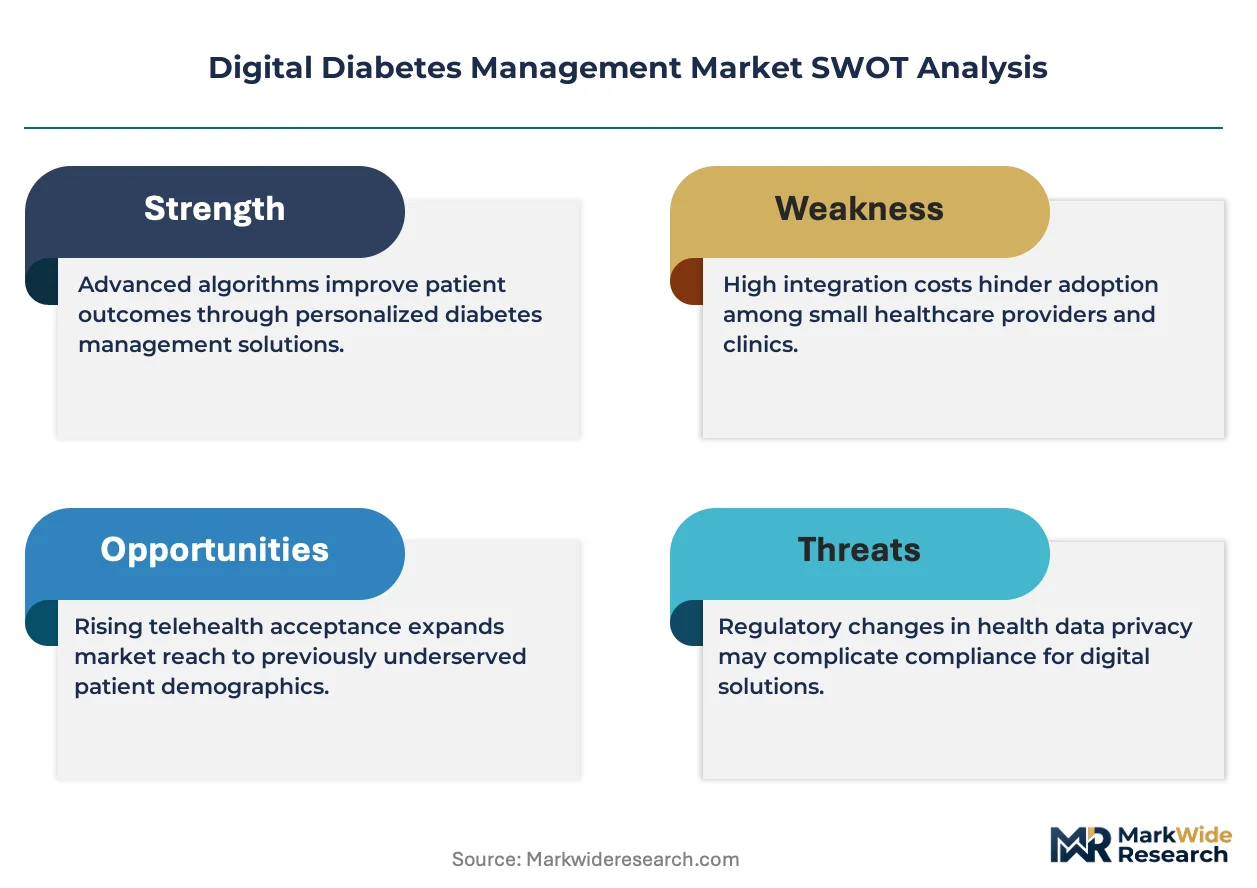
FDA digital health pre-certification, EU MDR Class IIa/IIb device requirements, and HIPAA data security standards collectively elevate barriers for new entrants while mandating interoperability protocols that shape platform architecture. EMA guidance on software-as-medical-device classification further constrains how algorithm updates deploy across European markets. Stakeholders must weigh regulatory compliance investment against the pace of AI-driven predictive analytics integration.
Market Dynamics
Statutory health insurance reimbursement expansion in Germany is compressing sensor replacement cycles and pulling automated insulin delivery platforms into standard-of-care protocols across European hospital systems.
Growth Catalysts
- CGM reimbursement broadening:Germany's statutory health insurance now covers continuous glucose monitoring for Type 2 diabetes patients on intensive insulin therapy, expanding addressable patient populations beyond Type 1.
- FDA digital health pre-certification:The program accelerates software-as-medical-device approvals, compressing time-to-market for algorithm-driven insulin dosing applications.
- Bluetooth Low Energy 5.3:Extended range and reduced power consumption enable smaller wearable form factors with multi-day battery life, supporting patient adherence.
Market Restraints
- Palladium supply concentration:Electrochemical sensor electrodes depend on palladium, with Russian and South African mines supplying over 70% of global refined output, exposing manufacturers to price volatility and sanctions risk.
- EU MDR Class IIb certification timelines:Software-as-medical-device reclassifications under the Medical Device Regulation extend conformity assessment durations to 18-24 months for algorithm updates.
- Non-invasive optical substitutes:Spectroscopic glucose monitoring approaches from consumer electronics manufacturers threaten to commoditize peripheral segments of the monitoring market.
Strategic Opportunities
- Underpenetrated Japan:Reimbursement for real-time CGM remains limited to specific patient subgroups, creating whitespace for platform entrants as METI evaluates expanded coverage criteria.
- AI-driven hypoglycemia prediction:Machine learning models trained on multi-parameter physiological data are converging with CGM streams to enable anticipatory insulin suspension.
- EU Green Deal procurement criteria:Healthcare systems are rebalancing vendor selection toward connected care platforms with verified lower carbon footprints in manufacturing and end-of-life disposal.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers with combined expertise in electrochemical sensing, wireless protocols, and FDA-quality system design extends development timelines.
- Legacy EHR integration complexity:Hospital procurement committees demand seamless data flow into Epic and Cerner environments, requiring costly interoperability certification.
- Sensor calibration drift management:Factory calibration protocols must account for enzymatic degradation across temperature and humidity variations during global distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Diabetes Management Market |
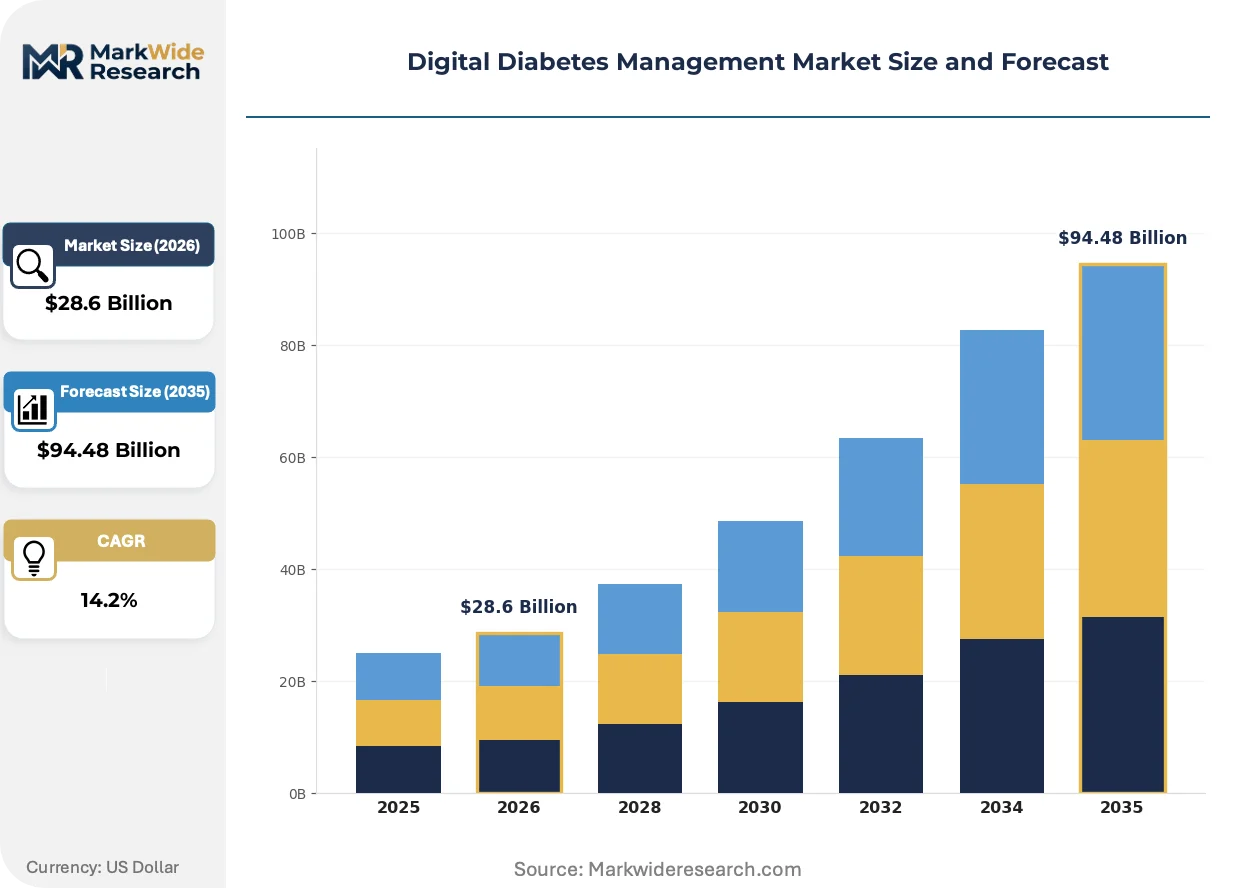
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Monitors, Insulin Pumps, Mobile Apps, Continuous Glucose Monitoring Systems End User: Clinics, Hospitals, Patients, Caregivers Technology: Mobile Health, Telehealth, Wearable Devices, Cloud Computing Application: Monitoring, Insulin Delivery, Data Management, Patient Education |
| Companies Covered | Dexcom, Tandem Diabetes Care, Abbott, Novo Nordisk A/S, Embecta, F. Hoffmann-La Roche Ltd., Medtronic, Bayer AG, Insulet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Diabetes Management Market Emerging Trajectories
Algorithmic automation is displacing manual insulin dosing decisions, while regulatory frameworks race to keep pace with software update velocity and data security requirements.
Multi-sensor fusion is electrifying glucose prediction accuracy. Platforms now combine interstitial glucose readings with accelerometer, heart rate variability, and meal logging data through edge computing architectures. Endocrinology practices in the United States are piloting these systems for closed-loop insulin delivery. The structural consequence is compression of hypoglycemic event rates and reduced clinical burden on diabetes educators.
The EU AI Act risk classification framework is reshaping software deployment protocols. Algorithmic features qualifying as high-risk AI systems face mandatory conformity assessments, quality management systems, and human oversight requirements. CGM platforms with predictive dosing recommendations fall under this classification. European manufacturers are responding by segregating AI-enabled features into modular software architectures that can be validated independently.
Subscription-based platform access is displacing device-centric purchasing in employer-sponsored health plans. Large self-insured employers in the United States are contracting directly with CGM manufacturers for population health management, bundling hardware, software, and clinical coaching. This model is most visible among technology sector employers with younger, digitally-native workforces where diabetes prevalence is rising fastest.
Digital Diabetes Management Market Segmentation
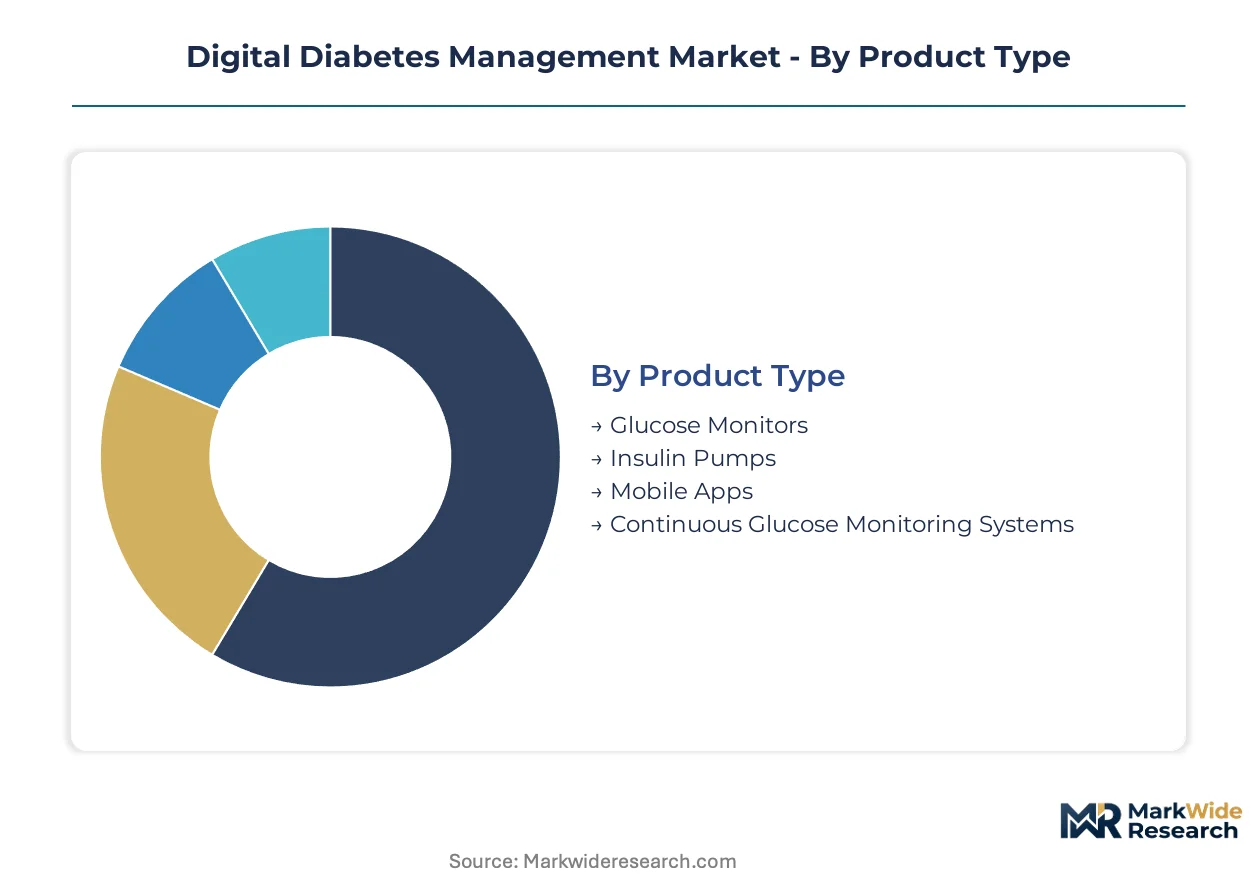
Segmentation in digital diabetes management reveals how procurement power, reimbursement tiers, and technology readiness diverge across patient populations and care settings. Understanding these fault lines exposes where platform economics concentrate and where new entrants face structural barriers.
Product Type:
Supply concentration in electrochemical sensor manufacturing and insulin delivery mechanics shapes competitive moats across hardware categories, with recurring consumable revenue driving platform valuations.
- Continuous Glucose Monitoring Systems:Factory-calibrated electrochemical sensors measure interstitial glucose via subcutaneous filaments, transmitting data via Bluetooth Low Energy to paired receivers. Hospital systems in Germany and the United States anchor procurement volume, pulled by statutory reimbursement expansion for Type 2 intensive insulin patients and FDA pre-certification pathways that accelerate software updates.
- Insulin Pumps:Motor-driven reservoir systems deliver basal and bolus dosing through infusion sets, with automated insulin delivery algorithms closing the loop with CGM inputs. Pediatric endocrinology practices and academic medical centers concentrate demand, constrained by EMA MDR Class IIb certification timelines that extend conformity assessments for algorithm modifications.
- Glucose Monitors:Fingerstick-based electrochemical test strips provide point-in-time glucose readings with lower per-test cost than CGM.
- Mobile Apps:Software interfaces for manual glucose logging, meal tracking, and dose calculation operate on consumer hardware without hardware attachment.
Today's leader: Continuous Glucose Monitoring Systems. Tomorrow's challenger: Insulin Pumps.
End User:
Reimbursement authority and clinical workflow integration requirements fragment purchasing power across care settings, with hospital procurement committees demanding EHR interoperability that smaller clinics cannot enforce.
- Hospitals:Integrated delivery networks with Epic and Cerner deployments require seamless data flow into electronic health records, driving vendor selection toward platforms with costly interoperability certification. United States health systems lead procurement scale, though German statutory insurance expansion is pulling comparable volume into European hospital systems.
- Patients:Direct-to-consumer and pharmacy channel purchases dominate, with subscription models displacing device-centric purchasing among employer-sponsored populations. Technology sector employers with younger, digitally-native workforces are contracting directly with manufacturers for population health management bundles.
- Clinics:Independent endocrinology practices pilot multi-sensor fusion systems for closed-loop insulin delivery, though capital constraints limit platform switching frequency.
- Caregivers:Remote monitoring access for family members and home health aides expands addressable user base beyond the diagnosed patient.
Hospitals command procurement volume today. Patients represent the steepest expansion trajectory as subscription access democratizes.
Technology:
Form factor miniaturization and power efficiency gains are redrawing competitive boundaries, with wearable architectures capturing investment as mobile health commoditizes.
- Wearable Devices:Shrinking sensor form factors and multi-day battery life enabled by Bluetooth Low Energy 5.3 improve patient adherence and expand addressable populations beyond early adopters. United States and German markets concentrate demand, with EU Green Deal procurement criteria rebalancing vendor selection toward lower-carbon manufacturing footprints.
- Telehealth:Remote consultation platforms integrate CGM data streams for virtual endocrinology visits, with reimbursement parity expanding post-pandemic.
- Mobile Health:Smartphone-native applications for glucose logging and dose calculation face downward pricing pressure from platform bundling.
- Cloud Computing:Scalable analytics infrastructure supports population-level glycemic pattern analysis for payers and employers.
Wearable Devices anchor technology investment. Telehealth gains share fastest as virtual care reimbursement stabilizes.
Application:
Clinical value capture concentrates in acute event prevention and therapeutic automation, while patient education remains underdeveloped relative to monitoring and delivery functions.
- Monitoring:Real-time and retrospective glucose data collection commands the largest revenue share, with recurring sensor replacement cycles generating predictable consumable revenue. German statutory health insurance reimbursement expansion and United States hospital procurement growth concentrate demand.
- Insulin Delivery:Algorithm-driven dosing automation compresses hypoglycemic event rates and reduces clinical burden on diabetes educators, with endocrinology practices in the United States piloting closed-loop systems.
- Data Management:Cloud-based analytics and EHR integration address payer and provider reporting requirements.
- Patient Education:Digital coaching and behavioral intervention modules lag in development investment and reimbursement recognition.
Monitoring dominates revenue capture today. Insulin Delivery is climbing the fastest as algorithmic automation displaces manual dosing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital diabetes management industry traces its commercial roots to Silicon Valley electrochemical sensor development in the early 2000s, with subsequent scaling through German precision manufacturing and Japanese miniaturization expertise. Today procurement patterns concentrate in five national markets where reimbursement frameworks and industrial capabilities have converged.
United States
Hospital systems with Epic and Cerner deployments drive procurement volume for connected glucose monitoring platforms. FDA digital health pre-certification accelerates software-as-medical-device approvals, compressing time-to-market for algorithm-driven applications. The San Francisco Bay Area anchors sensor development clusters where Bluetooth Low Energy integration expertise concentrates.
Germany
Statutory health insurance reimbursement expansion now covers continuous glucose monitoring for Type 2 diabetes patients on intensive insulin therapy. EU MDR Class IIa/IIb device requirements under the Medical Device Regulation shape conformity assessment protocols for algorithm updates. The Munich-Stuttgart corridor hosts manufacturing facilities serving European distribution channels.
Japan
Reimbursement for real-time CGM remains limited to specific patient subgroups, creating whitespace for platform entrants. METI evaluates expanded coverage criteria that would broaden addressable populations. The Tokyo-Osaka industrial belt concentrates electrochemical sensor fabrication capabilities for Asian markets.
United Kingdom
NHS procurement frameworks prioritize interoperability with electronic health record systems, favoring vendors with costly certification investments. MHRA alignment with EU MDR post-Brexit maintains regulatory continuity for device approvals. The Cambridge-London corridor attracts digital health venture capital for algorithm development.
China
NMPA regulatory pathways for software-as-medical-device classification are evolving to accommodate AI-driven glucose prediction features. Domestic manufacturers compete on cost-positioning for hospital procurement tenders. The Yangtze River Delta cluster concentrates electrochemical sensor electrode production.
Digital Diabetes Management Market Vendor Landscape
Premium-margin players sit above commodity-margin players across reimbursement tier access and regulatory certification depth. The market structure consolidates around vertically integrated sensor manufacturers and modular platform assemblers, with mid-tier specialists occupying narrow application niches. Three archetypes dominate: full-stack ecosystem builders, component-focused suppliers, and algorithm-centric software vendors. Competitive moves concentrate on backward integration into palladium supply chains and strategic partnerships with hospital procurement committees.
Among full-stack ecosystem builders, Dexcom, Abbott, and Medtronic occupy positions that exemplify contrasting approaches to platform architecture. Dexcom represents the vertically integrated archetype with captive sensor production. Abbott anchors the scale-driven positioning through broad distribution reach. Medtronic sits within the automated insulin delivery specialization where hardware-software integration requirements create defensive moats.
| Leading Market Players |
|---|
| Dexcom |
| Tandem Diabetes Care |
| Abbott |
| Novo Nordisk A/S |
| Embecta |
| F. Hoffmann-La Roche Ltd. |
| Medtronic |
| Bayer AG |
| Insulet Corporation |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committees in the United States and German statutory health insurance funds concentrate purchasing power for connected glucose monitoring platforms, locking in subscription-based pricing models that bundle hardware, consumables, and clinical coaching services.
Pricing Analysis
Subscription-based platform access dominates pricing architecture across employer-sponsored health plans and hospital system contracts, with three-tier pricing structure across premium, standard, and economy levels separating FDA pre-certified ecosystems from MDR Class IIb certified devices and unbundled sensor-only offerings. Price differentiation rests on certification depth and EHR interoperability grade, with Epic and Cerner integration commanding material premiums. Cost compression in the standard tier is intensifying because Bluetooth Low Energy commoditization erodes hardware margins. Self-insured employers show lowest price sensitivity, while independent clinics face acute budget constraints.
Supply Chain Analysis
Freight cost volatility from Russian and South African palladium shipments to electrochemical sensor fabrication facilities in the United States, Germany, and Japan elevates working capital requirements for manufacturers. Raw material dependencies center on palladium electrodes, enzymatic glucose oxidase formulations, and Bluetooth Low Energy chipsets. Single-source vulnerability in Russian palladium refining exposes producers to sanctions-driven supply interruption. Distribution runs through hospital GPO contracts, pharmacy channels, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in algorithm-driven insulin delivery automation, where software update velocity and predictive analytics integration justify premium pricing tiers above commoditized sensor hardware.
For Market Incumbents: Anticipate non-invasive optical glucose monitoring threats from consumer electronics manufacturers by accelerating FDA pre-certification for multi-sensor fusion platforms. Backward integration into palladium supply chains through offtake agreements with South African and Australian miners reduces raw material volatility exposure. Prioritize embedded firmware talent acquisition in the San Francisco Bay Area and Munich-Stuttgart corridor to compress development timelines for closed-loop algorithm updates.
For New Entrants and Emerging Players: Begin with Japan's underpenetrated reimbursement environment, where METI evaluation of expanded CGM coverage criteria creates whitespace before domestic incumbents consolidate position. Target employer-sponsored population health management bundles in United States technology sector firms, where subscription model familiarity and rising diabetes prevalence lower adoption friction. Lead with AI-driven hypoglycemia prediction modules that integrate with existing CGM data streams rather than competing on hardware.
For Investors and Strategic Acquirers: Large pharmaceutical manufacturers with diabetes therapeutic portfolios are the most active acquirer in this space, seeking closed-loop ecosystem control. Five-to-ten year viability favors vertically integrated sensor producers with captive manufacturing and algorithm development capabilities. Watch FDA digital health pre-certification program expansion as the signal indicating accelerated software-as-medical-device consolidation timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | German statutory health insurance expansion for Type 2 intensive insulin patients unlocks volume. |
| Hospital System Partnership | Epic and Cerner interoperability certification secures procurement committee placement. |
| Software Companion Development | AI-driven hypoglycemia prediction modules qualify for FDA pre-certification acceleration. |
| CE Marking Pathway | EU MDR Class IIb segregation enables modular algorithm validation independent of hardware. |
| Backward Integration | Palladium offtake agreements with Australian and South African miners reduce supply volatility. |
Methodological Framework
Multiple input streams — structured interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; regulatory filings with FDA and EMA; and CMS Medicare reimbursement databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from hospital procurement databases, continuous glucose monitor registration records, and statutory health insurance claims data. Cross-referencing manufacturer sensor shipment disclosures against payer reimbursement volumes tested internal consistency.
Historical revenue trajectories were cross-referenced against panel input from endocrinology practice administrators and diabetes educator networks to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology architecture, and application function. CAGRs were derived from curve-fitting observed adoption patterns against reimbursement expansion timelines and algorithm automation penetration rates. Forecast inputs incorporated Bluetooth Low Energy adoption curves and EU Green Deal procurement criteria implementation.
Several conditions sit outside the modeled scope, including palladium price shock scenarios beyond historical volatility bands and non-invasive optical glucose monitoring technology breakthroughs. Forecasts reflect documented assumptions about reimbursement parity expansion and regulatory pre-certification program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Philippines Diabetes Care Devices Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Global Implantable Insulin Pump Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Canada Diabetes Care Drugs and Devices Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
South Korea Insulin Infusion Pump Market