
 Type 2 Diabetes Mellitus Treatment Market | 2026-2036
Type 2 Diabetes Mellitus Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Type 2 Diabetes Mellitus Treatment Market Outlook
The EU Green Deal is decoupling pharmaceutical manufacturing from carbon-intensive supply chains, pressuring diabetes drug producers to reformulate and reshore active pharmaceutical ingredient production. Novo Nordisk AS leverages its integrated fermentation capacity in Denmark to sustain cost leadership in insulin and GLP-1 manufacturing. Eli Lilly and Co. anchors its position through deep R&D investment in oral incretin mimetics, while Sanofi SA competes via broad geographic distribution across European and emerging markets.
Type 2 Diabetes Mellitus Treatment encompasses pharmacological interventions that modulate insulin secretion, peripheral glucose uptake, or hepatic glucose output to achieve glycemic targets in patients with insulin resistance and progressive beta-cell dysfunction. These therapies range from synthetic human insulin and insulin analogs to small-molecule oral agents and peptide-based injectables, with manufacturing processes spanning recombinant DNA fermentation, chemical synthesis, and lyophilization for stability. The injectable delivery mode dominates value capture due to the biological nature of GLP-1 receptor agonists and insulin, though oral formulations are gaining structural importance as patient preference shifts toward non-invasive administration. Among product types, GLP-1 receptor agonists represent the fastest-expanding margin pool, while SGLT-2 inhibitors occupy a mature but defensible position in cardiovascular risk reduction protocols.
The FDA enforces stringent chemistry, manufacturing, and controls requirements for biosimilar insulins, while the EMA's MDR framework imposes heightened clinical evidence standards on glucose-monitoring combination devices. The EPA regulates pharmaceutical manufacturing effluent under its industrial wastewater guidelines, affecting production location decisions for API synthesis. Stakeholders must monitor evolving reimbursement parity between oral and injectable agents as pharmacy benefit managers recalibrate tier placement for weight-management indications.
Market Dynamics
GLP-1 receptor agonist manufacturing concentration in Denmark and Indiana is restructuring competitive economics, as fermentation capacity scarcity forces late entrants into costly contract manufacturing arrangements or decade-long facility buildouts.
Growth Catalysts
- Medicare coverage expansion:CMS reimbursement decisions for obesity-linked diabetes indications are pulling GLP-1 prescribing into primary care settings across the United States.
- EU MDR glucose-monitoring integration:The European framework is accelerating approval of combination drug-device products that pair SGLT-2 inhibitors with continuous glucose monitors.
- Peptide synthesis automation:Solid-phase manufacturing advances are compressing batch cycle times for injectable incretin mimetics at contract development facilities.
Market Restraints
- API supply concentration:Fermentation-derived peptide production clusters in Denmark and the United States, exposing formulations to single-source geographic risk.
- FDA bioequivalence stringency:The agency's evolving standards for peptide drugs are extending approval timelines for biosimilar GLP-1 entrants by 24-36 months.
- Lyophilization capacity scarcity:Sterile fill-finish infrastructure for biologic stability is bottlenecking launch volumes for new molecular entities.
Strategic Opportunities
- Oral peptide delivery:Permeation enhancer technologies are opening non-injective administration routes for GLP-1 drugs, capturing patient segments refusing pen-based therapy.
- India CDMO expansion:The country's PLI scheme for active pharmaceutical ingredients is attracting fermentation investment for insulin and peptide manufacturing.
- Cardiovascular outcome bundling:Payer contracts linking SGLT-2 inhibitor reimbursement to heart failure hospitalization reduction are creating indication expansion pathways.
Industry Challenges
- Bioprocess engineering talent scarcity:Large-scale mammalian cell culture expertise for GLP-1 production is concentrated among a narrow cohort of Danish and American specialists.
- Legacy insulin manufacturing retooling:Recombinant human insulin facilities face stranded asset risk as prescribing shifts toward analogs and incretin mimetics.
- Combination device software validation:FDA digital health pre-certification requirements for glucose-sensing injection systems are extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Type 2 Diabetes Mellitus Treatment Market |
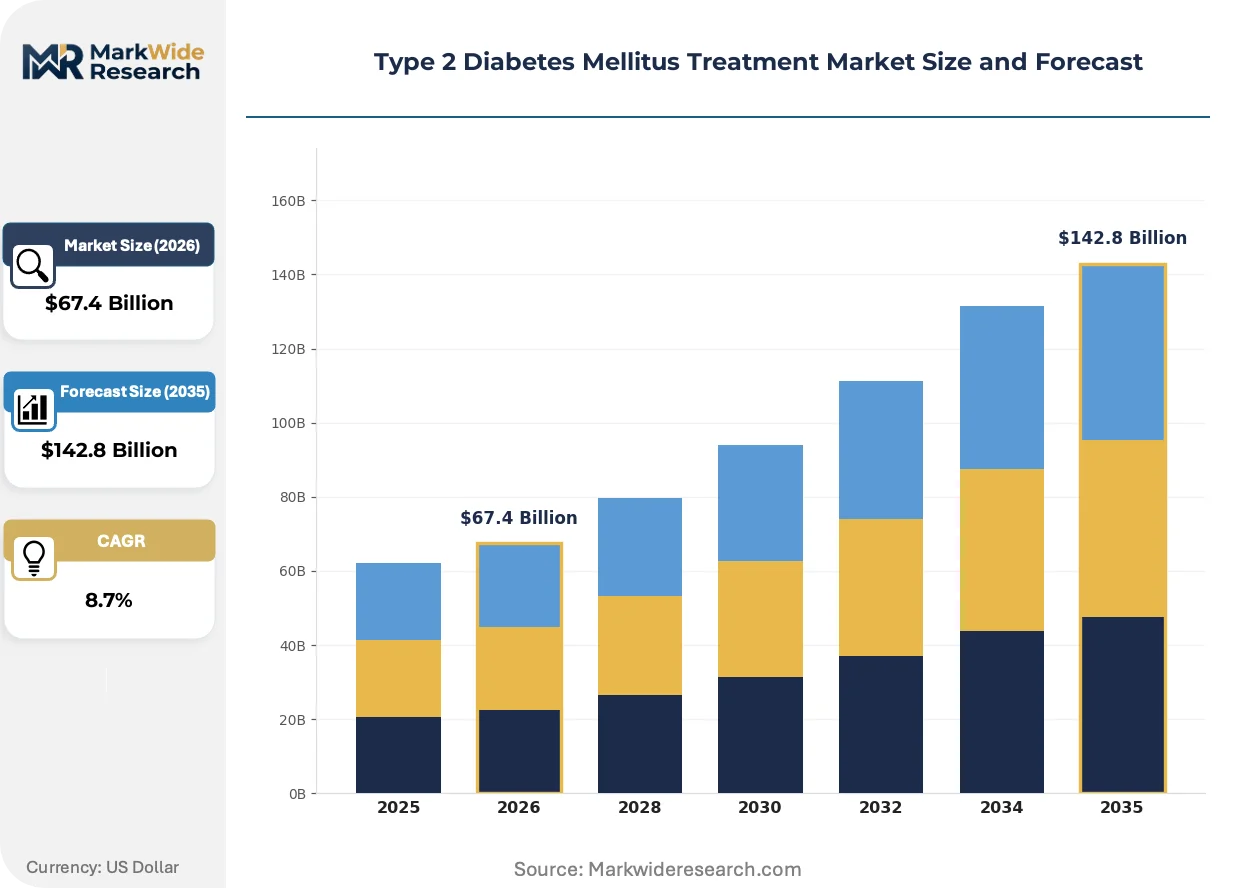
| Market Size in 2026 | $67.4 Billion |
| Market Size in 2035 | $142.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Receptor Agonists, SGLT-2 Inhibitors, DPP-4 Inhibitors End User: Hospitals, Clinics, Homecare, Pharmacies Delivery Mode: Injectable, Oral, Continuous Infusion, Inhaled Application: Weight Management, Glycemic Control, Cardiovascular Risk Reduction, Long-term Care |
| Companies Covered | Novo Nordisk AS, Sanofi SA, Eli Lilly and Co., AstraZeneca PLC, Merck & Co. Inc, Boehringer Ingelheim International GmbH, Takeda Pharmaceutical Co. Ltd, Novartis AG, Daiichi Sankyo Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Type 2 Diabetes Mellitus Treatment Market Strategic Shifts
Continuous manufacturing and real-time release testing are displacing batch processing in peptide drug production, while dual-hormone agonist engineering expands the pharmacological target space beyond single-pathway modulation.
Dual glucose-dependent insulinotropic polypeptide (GIP) and GLP-1 receptor agonists are integrating metabolic and appetite-regulating mechanisms into single molecular entities. Hospital systems in the United States are accelerating formulary placement of these agents for patients with obesity-driven insulin resistance. This convergence is compressing market share for standalone GLP-1 drugs by offering superior glycemic control and weight reduction in head-to-head outcomes data.
The EU Green Deal's pharmaceutical manufacturing decarbonization mandates are forcing reformulation of solvent-intensive chemical synthesis routes for small-molecule oral diabetes agents. Active pharmaceutical ingredient producers in Germany and Switzerland are retrofitting facilities to reduce carbon dioxide emissions from peptide coupling reactions. SGLT-2 inhibitor manufacturers with European supply chains face the steepest compliance costs, reshaping location decisions toward renewable-energy-powered fermentation sites.
Pharmacy benefit managers are unbundling weight-management indications from diabetes-only reimbursement tiers, creating distinct contracting pathways for GLP-1 drugs. Employers and commercial payers in the United States are negotiating separate value-based contracts for cardiometabolic risk reduction versus glycemic control. This bifurcation is most visible in large self-insured employer plans, where obesity coverage expansion is outpacing traditional diabetes formulary management.
Type 2 Diabetes Mellitus Treatment Market Segmentation
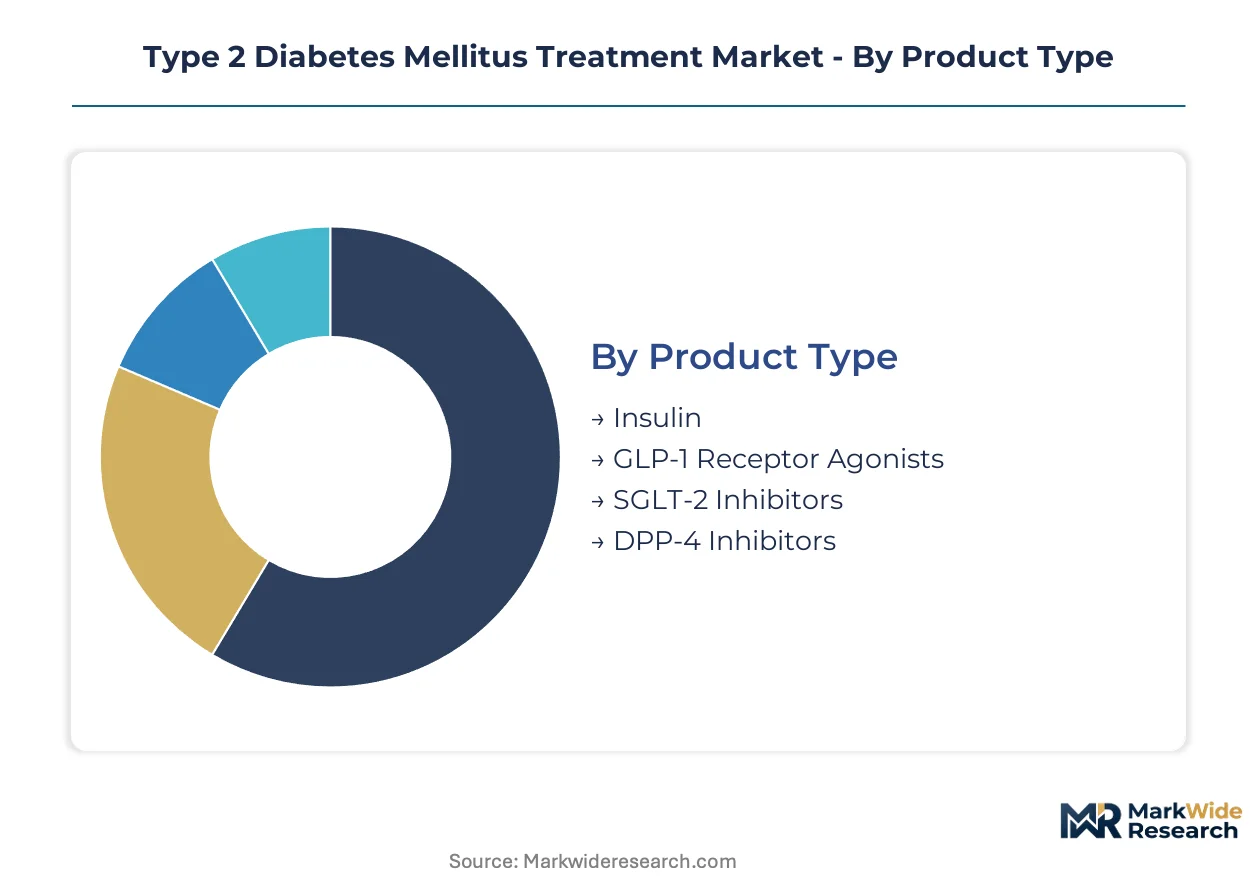
Segmentation in Type 2 diabetes treatment reveals how prescribing economics diverge across clinical settings and patient risk profiles. Manufacturers calibrate formulation investments, pricing architecture, and channel strategy against these distinct demand pockets.
Product Type:
Biologic versus small-molecule chemistry distinguishes manufacturing complexity, margin structure, and regulatory pathway intensity across therapeutic classes.
- Insulin:Recombinant human insulin and analogs require large-scale fermentation infrastructure with lyophilization stability protocols. Demand concentrates in Medicare-reimbursed long-term care settings across the United States, constrained by biosimilar substitution hesitancy and cold-chain distribution requirements.
- GLP-1 Receptor Agonists:Peptide-based incretin mimetics modulate glucose-dependent insulin secretion through subcutaneous or oral delivery. Hospital systems in Denmark and Indiana are expanding formulary placement for obesity-driven diabetes, pulled by cardiovascular outcome data and Medicare coverage expansion for weight-linked indications.
- SGLT-2 Inhibitors:Small-molecule oral agents reduce renal glucose reabsorption with established heart failure hospitalization benefits.
- DPP-4 Inhibitors:Oral gliptins extend endogenous incretin half-life through enzymatic inhibition, occupying a mature position in step-therapy protocols.
Mature deployment sits with Insulin. Newer deployment is concentrated in GLP-1 Receptor Agonists.
End User:
Site-of-care economics and reimbursement mechanics fragment prescribing authority across institutional and ambulatory channels.
- Hospitals:Inpatient glycemic management protocols drive concentrated purchasing of rapid-acting insulin analogs and combination drug-device systems. Formulary committees in United States health systems are accelerating GLP-1 placement for cardiometabolic risk reduction, constrained by pharmacy budget impact thresholds.
- Clinics:Outpatient endocrinology practices manage dose titration and therapeutic switching for complex patients. Patient volume concentrates in urban specialty centers across Germany and the United States, where prior authorization requirements for GLP-1 drugs create administrative friction.
- Homecare:Self-administered injectable and oral therapies shift monitoring burden to patients and caregivers.
- Pharmacies:Retail dispensing captures prescription volume for maintenance oral agents and refill insulin supplies.
Revenue concentration favors Hospitals. Volume expansion is accelerating fastest in Homecare.
Delivery Mode:
Administration route determines patient adherence economics, manufacturing process requirements, and competitive differentiation potential.
- Injectable:Pen-based and syringe delivery dominates biologic administration, requiring aseptic fill-finish capacity and stability validation. United States Medicare reimbursement for pen devices drives preference over vial-and-syringe alternatives, though cold-chain logistics add distribution cost.
- Oral:Tablet and capsule formulations eliminate injection burden for small-molecule agents. Permeation enhancer technologies are opening non-invasive routes for peptide drugs in Denmark and Switzerland development pipelines, capturing patient segments refusing pen-based therapy.
- Continuous Infusion:Pump-based insulin delivery enables precise basal-bolus modulation for intensive management.
- Inhaled:Pulmonary insulin delivery offers rapid onset without injection, constrained by lung function screening requirements.
Injectable delivery commands current value capture. Oral peptide formulations represent the steepest expansion trajectory.
Application:
Indication breadth and outcome-based contracting reshape how payers evaluate therapeutic value beyond glycemic endpoints.
- Weight Management:Anti-obesity prescribing for diabetes patients is unbundling from traditional glycemic-only reimbursement tiers. Large self-insured employers in the United States are negotiating separate value-based contracts for cardiometabolic risk reduction, outpacing standard diabetes formulary management.
- Glycemic Control:HbA1c reduction remains the foundational regulatory endpoint for approval and step-therapy positioning. Clinics in Germany prioritize DPP-4 inhibitors and basal insulin for elderly patients with hypoglycemia risk, constrained by renal function monitoring requirements.
- Cardiovascular Risk Reduction:SGLT-2 inhibitors and GLP-1 drugs with heart failure outcome data command premium positioning.
- Long-term Care:Nursing facility protocols emphasize hypoglycemia avoidance and simplified dosing regimens.
Glycemic Control anchors established utilization. Weight Management is gaining share fastest as indication boundaries blur.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide fermentation capacity concentrates in Denmark and the United States while consumption spreads across aging populations in Western Europe and East Asia. This geographic asymmetry forces supply chain managers to balance cold-chain logistics costs against manufacturing scale economies.
United States
Medicare coverage decisions for GLP-1 receptor agonists are pulling prescribing into primary care settings across the Southeast and Midwest. The FDA enforces stringent chemistry, manufacturing, and controls requirements for biosimilar insulins, extending approval timelines for peptide drug entrants. Indianapolis anchors Eli Lilly and Co.'s manufacturing footprint for oral incretin mimetics development.
Germany
Hospital formulary committees in Bavaria and North Rhine-Westphalia are accelerating SGLT-2 inhibitor placement for cardiovascular risk reduction protocols. The EU MDR framework imposes heightened clinical evidence standards on glucose-monitoring combination devices, reshaping approval pathways for drug-device products. Boehringer Ingelheim International GmbH maintains its headquarters and R&D operations in Ingelheim am Rhein.
Denmark
Novo Nordisk AS leverages integrated fermentation capacity in Bagsværd to sustain cost leadership in insulin and GLP-1 manufacturing. The EPA's industrial wastewater guidelines affect production location decisions for API synthesis, though Danish facilities benefit from renewable energy integration. Copenhagen's bioprocess engineering talent pool supports large-scale mammalian cell culture expertise for peptide production.
Japan
PMDA regulatory pathways for oral peptide delivery technologies are attracting permeation enhancer development from domestic and multinational sponsors. Takeda Pharmaceutical Co. Ltd and Daiichi Sankyo Co. Ltd compete through broad geographic distribution and cardiovascular outcome trial investments. Osaka and Tokyo metropolitan areas concentrate endocrinology practice volume for complex patient management.
India
The PLI scheme for active pharmaceutical ingredients is attracting fermentation investment for insulin and peptide manufacturing in Gujarat and Maharashtra. CDSCO approval timelines for biosimilar insulins remain shorter than FDA equivalents, enabling faster market entry for domestic producers. Hyderabad's contract development and manufacturing organizations are expanding sterile fill-finish capacity for biologic stability protocols.
Type 2 Diabetes Mellitus Treatment Market Competitive Environment
The competitive structure tilts toward integrated fermentation specialists with captive API supply and deep R&D pipelines. Market concentration is pronounced in peptide-based therapeutics, where manufacturing scale and regulatory expertise create defensive moats. Two strategic archetypes dominate: vertically integrated biologics manufacturers with fermentation assets, and diversified pharmaceutical conglomerates with broad geographic distribution networks. Dominant competitive moves include capacity expansion in Denmark and Indiana fermentation clusters, and strategic partnerships for oral peptide delivery technology access.
Among integrated biologics specialists, Novo Nordisk AS and Eli Lilly and Co. exemplify the fermentation-anchored archetype with concentrated manufacturing footprints. Sanofi SA occupies a position within the diversified multinational tier, leveraging broad European and emerging market distribution. These three entities represent distinct strategic postures: the Danish incumbent with captive supply chain control, the American innovator with oral formulation R&D emphasis, and the French conglomerate with geographic reach advantages.
| Leading Market Players |
|---|
| Novo Nordisk AS |
| Sanofi SA |
| Eli Lilly and Co. |
| AstraZeneca PLC |
| Merck & Co. Inc |
| Boehringer Ingelheim International GmbH |
| Takeda Pharmaceutical Co. Ltd |
| Novartis AG |
| Daiichi Sankyo Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Hospital formulary committees in the United States and Germany concentrate purchasing authority for GLP-1 receptor agonists and SGLT-2 inhibitors, driving value-based contracting that ties reimbursement to cardiovascular outcome metrics rather than unit price alone.
Pricing Analysis
Margin tightening in Medicare-reimbursed insulin tiers reflects biosimilar substitution hesitancy and cold-chain distribution cost burdens. Pricing stratifies across originator biologics, authorized generics, and emerging biosimilars, with brand premium sustained by outcome data differentiation. Cost-down pressure on oral incretin mimetics accelerates because pharmacy benefit managers unbundle weight-management indications from diabetes-only tiers. Self-insured employers exhibit highest price sensitivity; integrated delivery networks with captive specialty pharmacies demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with fermentation-derived peptide API production in Denmark and Indiana, where mammalian cell culture capacity anchors global GLP-1 supply. Manufacturing draws from recombinant DNA fermentation, solid-phase peptide synthesis, and lyophilization stability protocols. Tariff exposure on Chinese-sourced chemical intermediates for small-molecule oral agents compounds geographic concentration risk. Distribution runs through cold-chain logistics networks serving hospital systems, specialty pharmacies, and homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
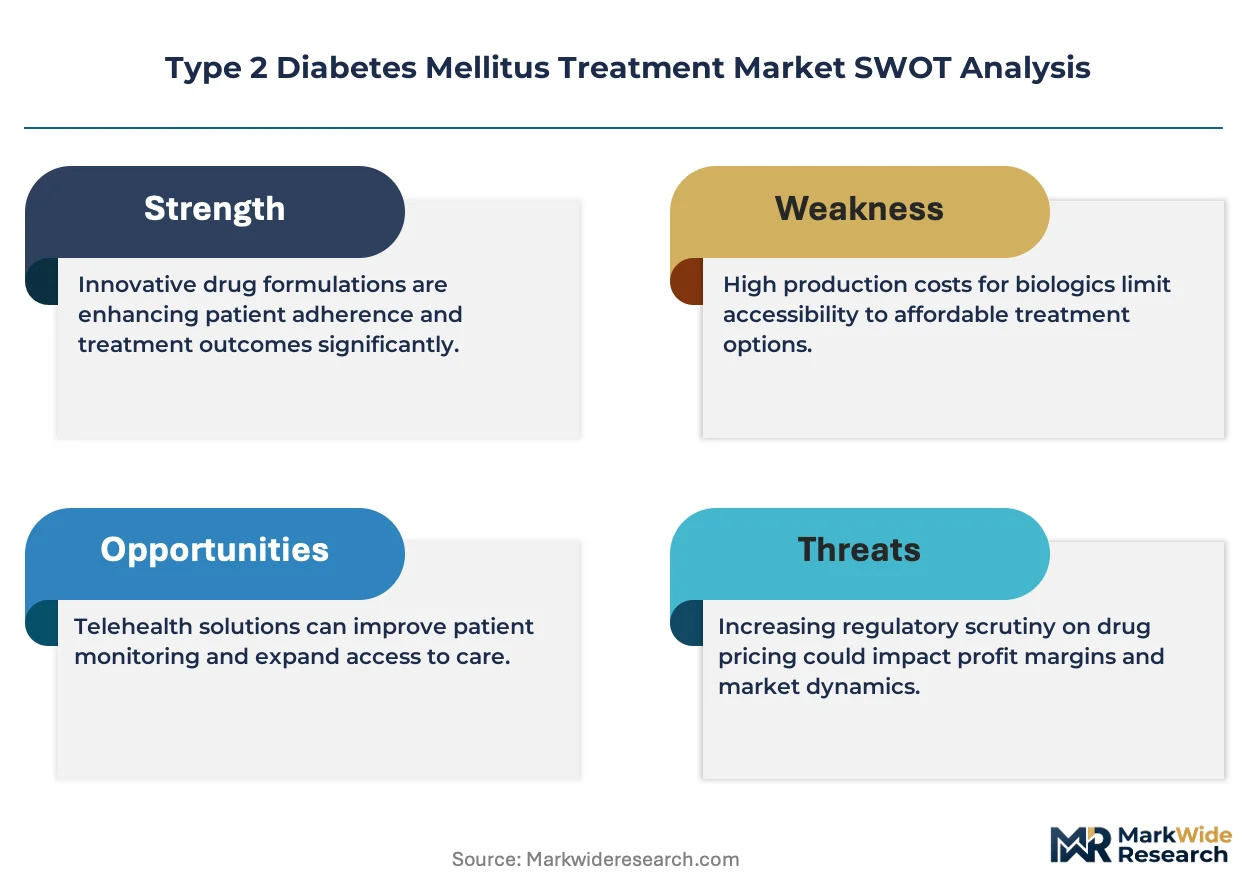
Type 2 diabetes treatment is consolidating around fermentation-anchored incumbents with captive API supply, as capacity scarcity and FDA bioequivalence stringency force subscale players toward contract manufacturing or exit.
For Market Incumbents: Anchor cost leadership through backward integration into peptide fermentation capacity in Denmark or Indiana, while capturing formulary placement via cardiovascular outcome data generation. Defend against oral peptide delivery disruptors by accelerating permeation enhancer partnerships. Prioritize sterile fill-finish capacity additions to resolve lyophilization bottlenecks. For New Entrants and Emerging Players: Contract development and manufacturing organizations in India offer the most penetrable entry vector, leveraging CDSCO's shorter biosimilar approval timelines and PLI scheme fermentation incentives. Target oral peptide delivery technologies for patient segments refusing pen-based therapy. Pursue strategic licensing with European hospital systems seeking SGLT-2 inhibitor and continuous glucose monitor combination products. For Investors and Strategic Acquirers: The window for entry favors CDMOs with sterile biologic fill-finish capabilities and Indian fermentation assets with peptide synthesis expertise. Long-term viability hinges on regulatory navigation capacity and payer contracting relationships. Watch for Medicare coverage expansion signals for obesity-linked diabetes indications as inflection triggers for GLP-1 demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Fermentation capacity expansion in Denmark and Indiana secures peptide API supply dominance against late entrants. |
| Regulatory Approval Pathway | FDA bioequivalence strategy acceleration for biosimilar insulins compresses approval timelines by 24-36 months. |
| Strategic Partnership | Permeation enhancer technology licensing opens non-invasive oral routes for GLP-1 receptor agonists. |
| Reimbursement Strategy | Value-based contracts with self-insured employers unbundle weight-management from diabetes-only tiers. |
| Pipeline Diversification | Dual GIP-GLP-1 agonist development integrates metabolic and appetite-regulating mechanisms. |
Study Parameters
Multi-period observation of formulary placement decisions, Medicare coverage determinations, and fermentation capacity utilization anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down therapeutic class value aggregation enabled triangulation.
Segment-weighting across product type, delivery mode, end user, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from historical prescription growth rates, patent expiry schedules, and biosimilar entry probability assessments. Forecast inputs incorporated EU MDR implementation timelines for combination drug-device products and PLI scheme capacity buildout trajectories in India.
Caveats apply where FDA bioequivalence standard evolution, Medicare coverage expansion decisions, or EU Green Deal manufacturing decarbonization mandates could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
Middle East and Africa Continuous Glucose Monitoring Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Italy Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market