
 Dental Orthotic Devices Market | 2026-2036
Dental Orthotic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Orthotic Devices Market Outlook
Equipment leasing and pay-per-aligner subscription models are tilting competitive dynamics toward asset-light entrants that bypass capital-intensive manufacturing. Align Technology leverages its end-to-end digital workflow to sustain margin advantages across scanning, planning, and fabrication. Dentsply Sirona anchors its position through integrated chairside systems that control the intraoral capture segment. Straumann Group differentiates via specialty-grade materials and premium positioning in the orthodontic specialist channel.
Dental orthotic devices are custom-fabricated removable or fixed appliances engineered from medical-grade polymers, cobalt-chromium alloys, or nickel-titanium wires to exert controlled mechanical force on dentition and maxillofacial structures. These devices serve therapeutic functions spanning occlusal correction, arch expansion, mandibular repositioning, and post-treatment retention through precise force delivery calibrated in gram-millimeters. The aligner segment leads volume as plastic-based clear alternatives displace fixed brackets among adult patients seeking aesthetic treatment. Retainers occupy a mature, high-margin aftermarket position driven by mandatory post-orthodontic compliance protocols. Splint applications for temporomandibular joint management represent a faster-growing clinical subset as diagnostic criteria for jaw disorders standardize across practices.
FDA 510(k) clearance pathways and EU MDR Class IIa device requirements shape product development timelines and clinical evidence obligations for manufacturers seeking market access. The FDA's evolving stance on direct-to-consumer orthodontic models is forcing channel participants to reassess patient-prescriber relationships and informed consent frameworks. Stakeholders must monitor how regulator scrutiny of artificial intelligence-driven treatment planning algorithms reshapes competitive moats around digital orthodontics platforms.
Market Dynamics
The dental orthotic devices sector is undergoing a fundamental reconfiguration as direct-to-consumer distribution models dismantle traditional prescriber-patient intermediaries, compressing margin structures across conventional orthodontic channels while forcing incumbent manufacturers to defend their clinical relationships.
Growth Catalysts
- Clear Aligner Aesthetics:Adult patients are rejecting fixed metal brackets in favor of removable transparent appliances, pulling volume toward plastic-based alternatives that address cosmetic concerns during professional and social interactions.
- EU MDR Compliance Framework:Stricter biocompatibility documentation requirements for Class IIa custom medical devices are raising barriers for low-quality entrants, concentrating market share among manufacturers with robust clinical evidence portfolios.
- Employer-Sponsored Dental Benefits:United States corporations are expanding orthodontic coverage as a talent retention tool, accelerating patient acquisition timelines and reducing out-of-pocket cost sensitivity for elective treatments.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Specialized thermoplastic polyurethane supply chains exhibit price instability tied to petrochemical feedstock fluctuations, squeezing fabrication margins for clear aligner producers.
- Intraoral Scanner Supply Concentration:Chairside digital capture hardware depends on a narrow supplier base concentrated in East Asian manufacturing clusters, exposing practices to equipment availability risk and service backlogs.
- FDA 510(k) Pathway Friction:Evolving agency scrutiny of algorithm-driven treatment planning is extending clearance timelines and increasing clinical evidence burdens for artificial intelligence-enabled orthodontic platforms.
Strategic Opportunities
- Temporomandibular Joint Splint Expansion:Diagnostic criteria standardization for jaw disorders is opening clinical pathways for mandibular repositioning appliances in pain management practices beyond traditional orthodontic settings.
- Pay-Per-Aligner Subscription Models:Asset-light financing structures are enabling independent practices to offer competitive clear aligner services without capital-intensive in-house fabrication equipment.
- Indian Market Penetration:Rising disposable incomes and expanding private dental clinic networks in metropolitan centers are creating addressable demand for mid-priced aesthetic orthodontic solutions.
Industry Challenges
- Digital Workflow Integration Complexity:Orthodontic practices face steep learning curves when connecting third-party intraoral scanners with proprietary treatment planning software, generating workflow friction and training costs.
- Biocompatibility Certification Timelines:Nickel-titanium wire suppliers must navigate extended material testing protocols to satisfy EU MDR substance documentation requirements, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Orthotic Devices Market |
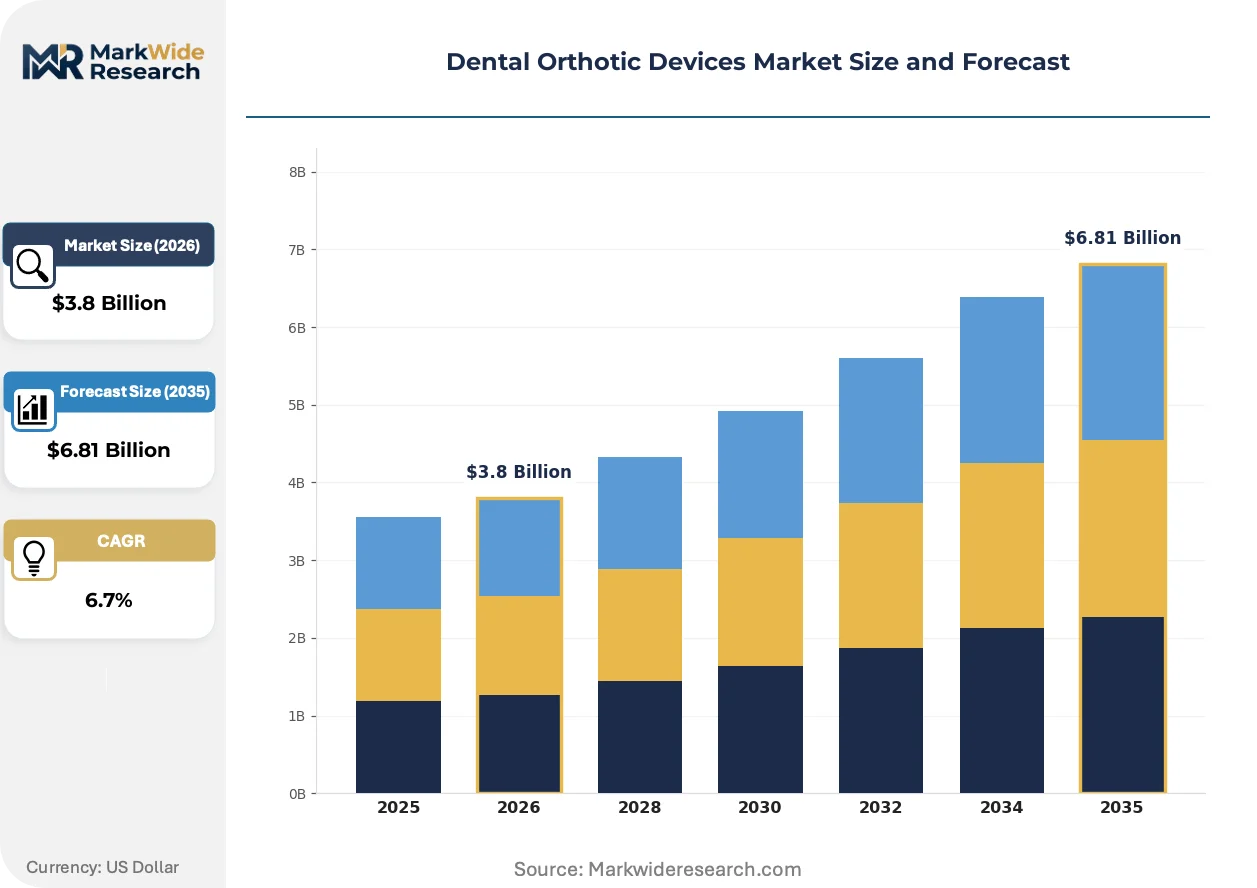
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aligners, Retainers, Splints, Palatal Expanders Application: Orthodontics, Jaw Disorders, Sleep Apnea, Tooth Movement End User: Dental Clinics, Hospitals, Orthodontic Practices, Home Care Material: Plastic, Metal, Composite, Silicone |
| Companies Covered | Align Technology, Dentsply Sirona, Straumann Group, Danaher Corporation, Ormco, ClearCorrect, Angelalign, 3M, Scheu Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Orthotic Devices Market Strategic Shifts
Artificial intelligence and cloud-based manufacturing architectures are compressing the traditional orthodontic value chain, enabling same-day treatment planning and decentralized production that challenges centralized fabrication economics.
Intraoral scanning hardware paired with machine learning algorithms is digitizing the patient acquisition funnel, allowing general dental practices to capture digital impressions without specialist referrals. Solo practitioners and small group practices are deploying these systems at accelerating rates to retain patient volume. This capability is digitizing the traditional gatekeeper role of orthodontic specialists, redistributing diagnostic and planning authority across broader dental networks.
The EU MDR's enhanced clinical evidence requirements for custom medical devices are forcing manufacturers to rebuild quality management systems around patient-specific device traceability. Compliance investments are diverting R&D resources toward documentation infrastructure rather than product innovation. Clear aligner and retainer segments face the steepest adaptation costs as notified bodies apply stricter scrutiny to polymer biocompatibility claims.
Patients are initiating treatment journeys through direct-to-consumer digital channels that bypass traditional prescriber relationships, fragmenting the historical referral-based patient flow. Employer-sponsored benefits administrators are responding by tightening network requirements to preserve plan cost controls. This behavioral shift is most pronounced in United States metropolitan markets where marketing spend concentrates and consumer brand awareness drives initial provider selection.
Dental Orthotic Devices Market Segmentation
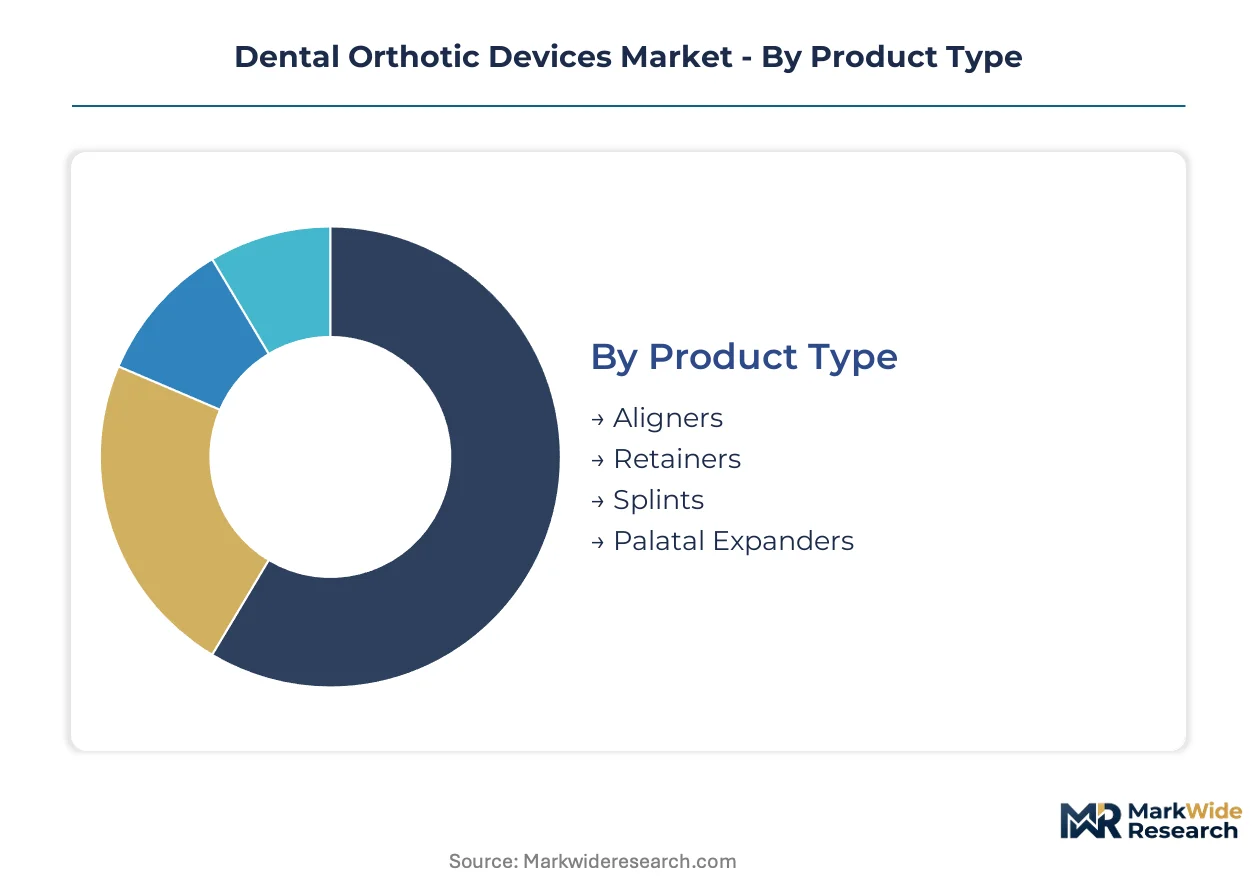
Segmentation in dental orthotics reveals how material science, clinical setting, and patient acuity reshape procurement priorities across the value chain. Manufacturers calibrate fabrication workflows and regulatory documentation to match the technical demands of each product category and end-use environment.
Product Type:
Volume concentration across product categories reflects shifting patient preferences toward removable aesthetic solutions and expanding diagnostic recognition of jaw dysfunction.
- Aligners:Thermoplastic polyurethane shells apply calibrated orthodontic force through sequential appliance replacement. Demand concentrates in United States metropolitan markets where employer-sponsored benefits reduce out-of-pocket barriers for adult patients seeking cosmetic alternatives to fixed brackets.
- Retainers:Post-tention appliances fabricated from polypropylene or nickel-titanium wires maintain arch stability after active orthodontic correction. United States orthodontic practices drive aftermarket volume through mandatory compliance protocols that extend device lifecycles.
- Splints:Mandibular repositioning appliances for temporomandibular joint management.
- Palatal Expanders:Fixed or removable devices for maxillary arch development in pediatric cases.
Aligners hold installed capacity. Splints are rotating up the share rankings.
Application:
Clinical application segmentation tracks how diagnostic criteria expansion and specialty referral patterns redirect device procurement across dental medicine disciplines.
- Orthodontics:Arch correction and malocclusion treatment through fixed or removable mechanical force delivery. United States general dental practices are capturing digital planning authority through intraoral scanner deployment, fragmenting traditional specialist referral channels.
- Jaw Disorders:Temporomandibular joint dysfunction management via repositioning splints and stabilization appliances. Diagnostic standardization across United States pain management and orofacial specialty clinics is expanding addressable patient populations beyond conventional orthodontic settings.
- Sleep Apnea:Mandibular advancement devices for obstructive sleep-disordered breathing.
- Tooth Movement:Limited orthodontic correction for minor alignment issues.
Orthodontics anchors revenue concentration. Jaw Disorders is climbing the fastest as diagnostic protocols mature.
End User:
End-user segmentation exposes how channel economics and clinical workflow integration determine procurement authority and device specification requirements.
- Dental Clinics:General practice settings deploying chairside digital capture systems to retain orthodontic volume. United States solo and small-group practices are accelerating scanner adoption to bypass specialist referrals and capture aligner revenue directly.
- Orthodontic Practices:Specialty settings with dedicated treatment planning expertise and patient volume concentration. These practices command premium positioning through complex case management and integrated digital workflows spanning scanning to fabrication coordination.
- Hospitals:Academic medical centers and integrated delivery networks with multidisciplinary craniofacial programs.
- Home Care:Direct-to-consumer models bypassing traditional prescriber relationships.
Dental Clinics are gaining procurement share through digital workflow adoption. Orthodontic Practices defend margin position through case complexity.
Material:
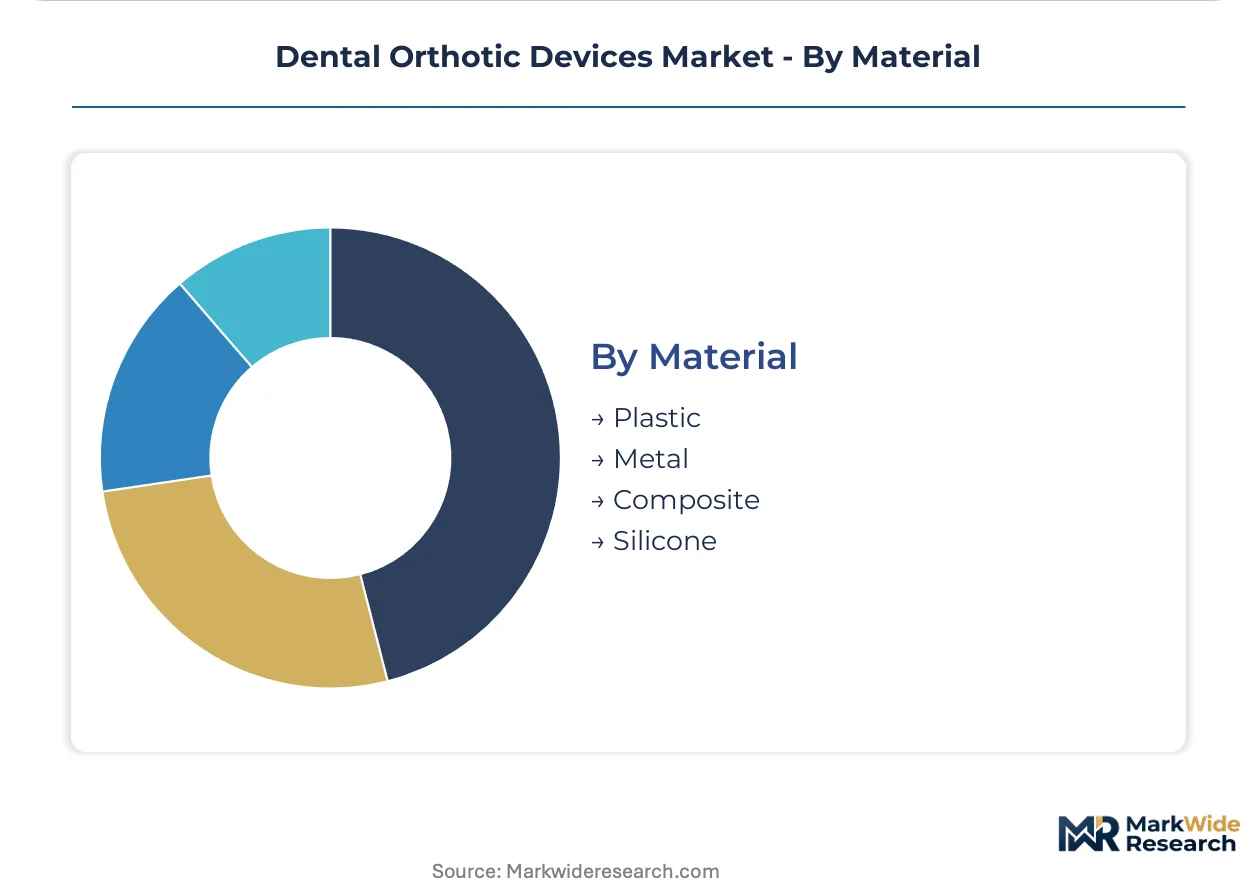
Material segmentation tracks how biocompatibility certification burdens and supply chain concentration reshape fabrication economics and competitive positioning.
- Plastic:Medical-grade thermoplastic polyurethanes and polyethylene terephthalate glycol formulations for clear aligners and retainers. EU MDR substance documentation requirements are extending quality system investments and delaying market access for polymer suppliers lacking robust clinical evidence portfolios.
- Metal:Nickel-titanium shape-memory alloys and cobalt-chromium compositions for fixed appliances and wire components. United States and European orthodontic specialists specify these materials for complex torque and anchorage requirements where polymer alternatives lack mechanical performance.
- Composite:Fiber-reinforced polymers for aesthetic fixed appliances.
- Silicone:Soft elastomeric materials for protective mouthguards and cushioning appliances.
Plastic dominates volume throughput. Metal retains premium positioning in specialist channel specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored dental benefit expansion across multiple jurisdictions is redirecting patient acquisition patterns toward regions with mature commercial insurance infrastructure. FDA and EU MDR regulatory frameworks are simultaneously reshaping market access timelines for device manufacturers seeking multi-territory presence.
United States
Direct-to-consumer marketing channels and employer-sponsored orthodontic benefits are compressing patient acquisition timelines in metropolitan markets. FDA scrutiny of algorithm-driven treatment planning is extending 510(k) clearance pathways for AI-enabled platforms. The Boston-Cambridge corridor hosts concentrated digital orthodontics development activity alongside established specialty practice networks.
Germany
EU MDR Class IIa device requirements are elevating clinical evidence burdens for custom-fabricated appliances entering European markets. The country's national pharmaceutical regulator enforces stringent biocompatibility documentation for polymer-based clear aligners. The Baden-Württemberg industrial cluster supports precision manufacturing capabilities serving both domestic orthodontic practices and export markets.
China
Rising disposable incomes in metropolitan centers are creating addressable demand for mid-priced aesthetic orthodontic solutions outside traditional specialist channels. The country's national medical products administration maintains oversight of custom medical device manufacturing licensing. The Yangtze River Delta concentration of dental equipment suppliers is enabling localized production scale for domestic clear aligner brands.
India
Expanding private dental clinic networks in metropolitan centers are democratizing access to orthodontic treatment beyond historical tier-1 city concentration. The Central Drugs Standard Control Organization regulates medical device import and manufacturing standards for custom dental appliances. The Maharashtra-Gujarat corridor is emerging as a fabrication hub serving both domestic consumption and regional export demand.
Japan
Aging demographics and aesthetic consciousness among working-age adults are sustaining demand for discreet orthodontic alternatives to fixed appliances. The Pharmaceuticals and Medical Devices Agency maintains rigorous quality management system requirements for custom device traceability. The Osaka-Kobe manufacturing belt retains specialized metal alloy processing capabilities for nickel-titanium wire components.
Dental Orthotic Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority. The vendor base clusters around three strategic archetypes: end-to-end digital workflow integrators, chairside system anchors, and specialty-grade material suppliers. Consolidation pressure concentrates among manufacturers seeking backward integration into intraoral capture hardware. Geographic expansion and technology licensing represent dominant competitive moves for market access acceleration.
Within the digital workflow tier, Align Technology exemplifies end-to-end platform control spanning patient acquisition through fabrication coordination. Dentsply Sirona anchors chairside system integration, leveraging its position across intraoral scanning and treatment planning software. Straumann Group occupies the specialty-grade materials vector, with its Swiss-based structure supporting premium positioning in orthodontic specialist channels.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Straumann Group |
| Danaher Corporation |
| Ormco |
| ClearCorrect |
| Angelalign |
| 3M |
| Scheu Dental |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing cluster anchors clear aligner thermoplastic polyurethane supply, concentrating fabrication capacity among a handful of polymer compounders who command pricing power over downstream appliance producers. This geographic concentration translates directly into margin pressure for mid-tier manufacturers lacking long-term offtake agreements or captive resin supply.
Pricing Analysis
Certification level creates the primary spread across the market, with FDA 510(k)-cleared and EU MDR Class IIa-certified devices commanding substantial premiums over uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on material grade and clinical evidence depth. Cost compression in the standard tier is intensifying because direct-to-consumer entrants are bypassing traditional markup structures. Employer-sponsored benefit administrators exhibit the lowest price sensitivity, while uninsured direct-pay patients in emerging markets drive volume toward economy-tier alternatives.
Supply Chain Analysis
Medical-grade thermoplastic polyurethane feedstock draws from petrochemical complexes concentrated in China, Germany, and the United States, with specialized polymer grades requiring proprietary additive packages from Swiss and Japanese specialty chemical suppliers. Nickel-titanium shape-memory alloy wire hinges on vacuum arc remelting capabilities concentrated in Japan, Germany, and the United States. Single-source vulnerability persists for EU MDR-compliant polymer masterbatch formulations, where notified body certification creates switching costs. Distribution runs through orthodontic specialist distributors in developed markets and direct manufacturer-to-clinic relationships in cost-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from direct-to-consumer aligner platforms that dismantle traditional prescriber-patient intermediaries, requiring defensive repositioning around clinical relationship control and regulatory compliance moats.
For Market Incumbents: Build clinical workflow integration moats by embedding proprietary treatment planning software within chairside scanning hardware, locking general dental practices into captive ecosystems. Deepen backward integration into thermoplastic polyurethane compounding to insulate margins from petrochemical feedstock volatility. Prioritize EU MDR quality system investments ahead of smaller competitors to capture market share as certification barriers rise.
For New Entrants and Emerging Players: India's metropolitan private dental clinic networks offer the most penetrable white-space opportunity, with rising disposable incomes and limited incumbent digital workflow penetration. Target temporomandibular joint splint applications as a faster-growing clinical subset where diagnostic criteria standardization is expanding addressable patient populations beyond traditional orthodontic settings. Deploy pay-per-aligner subscription financing to bypass capital-intensive fabrication equipment requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among end-to-end digital workflow platforms with integrated patient acquisition and fabrication coordination capabilities. Across the analysis window, vertically integrated platforms with proprietary intraoral scanning hardware and treatment planning software demonstrate superior cash flow durability. Monitor FDA enforcement actions against direct-to-consumer orthodontic models as an inflection signal for regulatory risk repricing across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Quality System Investment | Accelerates market access timelines by satisfying notified body substance documentation requirements ahead of competitors. |
| Chairside Digital Workflow Integration | Captures general dental practice volume by embedding proprietary scanning and planning software within hardware ecosystems. |
| Backward Integration into Polymer Compounding | Insulates fabrication margins from thermoplastic polyurethane feedstock price volatility tied to petrochemical cycles. |
| Temporomandibular Joint Splint Portfolio Expansion | Opens clinical pathways in pain management and orofacial specialty settings beyond traditional orthodontic channels. |
| Direct-to-Consumer Regulatory Compliance Framework | Preempts FDA enforcement risk by establishing patient-prescriber relationship protocols and informed consent infrastructure. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body guidance documents, and orthodontic practice management surveys. Orthodontic specialists, general dental practitioners, biomedical engineers at clear aligner manufacturers, and procurement managers at dental group purchasing organizations provided structured input. Trade data from customs authorities, SEC filings from publicly traded device manufacturers, and patent filings covering thermoplastic polyurethane formulations supplied quantitative anchors. Bottom-up demand modeling triangulated against top-down market sizing from dental insurance claims databases.
Forecast inputs span product type segmentation across aligners, retainers, splints, and palatal expanders; application segmentation across orthodontics, jaw disorders, sleep apnea, and limited tooth movement; end-user segmentation across dental clinics, orthodontic practices, hospitals, and home care; and material segmentation across plastic, metal, composite, and silicone formulations. CAGRs were derived from regression analysis against historical orthodontic procedure volumes and employer-sponsored benefit expansion trajectories. Modeled variables include intraoral scanner adoption rates, EU MDR compliance cost pass-through, and direct-to-consumer channel penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by well-capitalized direct-to-consumer platforms or accelerated FDA enforcement actions would shift outcomes beyond modeled ranges. Cross-checking against orthodontic procedure volume data from national dental associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Europe Kyphoplasty Market
Orthopedic Devices
Brazil Spinal Surgery Devices Market
Orthopedic Devices
Chondroplasty Market
Orthopedic Devices
Veterinary Prosthetics and Orthotics Market
Orthopedic Devices
Kyphoplasty Market
Orthopedic Devices
Spinal Surgery Devices Market
Orthopedic Devices
Animal External Fixation Market
Orthopedic Devices
Global Artificial Joints Market
Orthopedic Devices
USA Spinal Surgery Devices Market
Orthopedic Devices
South Africa Spinal Surgery Devices Market
Orthopedic Devices
Orthopedic Fracture Repairing Implants for Osteoporosis Market
Orthopedic Devices
Spinal Pumps Market
Orthopedic Devices
Keyhole Orthopaedic Surgery Market
Orthopedic Devices
Global Personalized 3D Printed Orthopedic Implants Market
Orthopedic Devices
Unicompartmental Knee Prosthesis Market
Orthopedic Devices
Vertebroplasty and Kyphoplasty Market