
 Canada Diabetes Care Drugs and Devices Market | 2026-2036
Canada Diabetes Care Drugs and Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Diabetes Care Drugs and Devices Market Outlook
The manufacturing capability gap between large-scale biologics producers and emerging device specialists is collapsing as automated fill-finish lines and modular pump assembly platforms democratize production scale. Novo Nordisk A/S leverages its integrated insulin active pharmaceutical ingredient supply chain to dominate Canadian GLP-1 agonist distribution. Dexcom differentiates through proprietary factory-calibration algorithms that eliminate fingerstick requirements for glucose trending data. Abbott Laboratories anchors its market position with Libre sensor manufacturing capacity that sustains aggressive provincial tender pricing.
Canada diabetes care drugs and devices encompass pharmacologic agents for glycemic control and instrument-based systems for glucose surveillance and insulin administration, with drug products requiring cold-chain distribution at two to eight degrees Celsius and devices incorporating electrochemical sensors with measurement ranges of forty to five hundred milligrams per deciliter. These products serve to reduce hemoglobin A1c levels, prevent microvascular complications, and enable patient self-management outside clinical settings. Insulin and GLP-1 agonists command the largest revenue pools within drug categories as biologic therapies displace older oral agents in provincial formularies. Continuous glucose monitors represent the fastest-expanding device segment as Health Canada clears next-generation integrated systems that pair directly with smartphone applications and automated insulin delivery platforms.
Health Canada, the Patented Medicine Prices Review Board, and provincial public drug programs including Ontario's OHIP+ and British Columbia's Pharmacare collectively shape market access through cost-effectiveness thresholds and reimbursement listing decisions. The Patented Medicine Prices Review Board's revised pricing guidelines reference international benchmarks that constrain launch prices for novel diabetes therapies entering Canadian distribution channels. Stakeholders must monitor evolving interoperability standards between continuous glucose monitors and insulin pumps as Health Canada aligns its digital health device framework with FDA breakthrough device pathways.
Market Dynamics
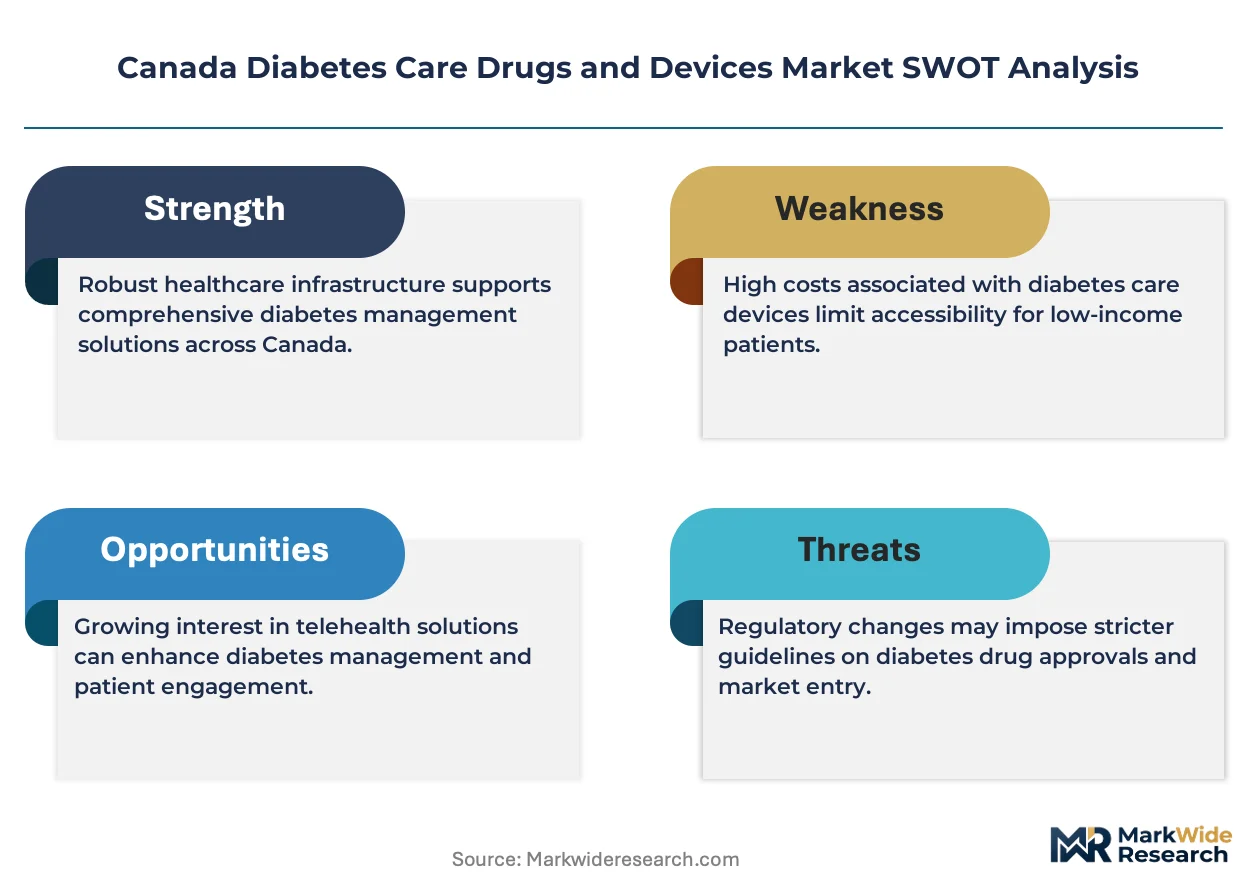
Provincial formulary expansions for continuous glucose monitors are compressing hospital-based diabetes management into home care settings, restructuring reimbursement flows and patient touchpoint economics across Ontario, British Columbia, and Alberta.
Growth Catalysts
- OHIP+ and Pharmacare expansions:Ontario and British Columbia are extending public reimbursement for real-time glucose monitoring systems, removing out-of-pocket barriers for Type 1 and insulin-dependent Type 2 patients.
- Automated insulin delivery convergence:Algorithm-enabled pump-CGM integration is pulling patients from multiple daily injection regimens toward closed-loop systems that reduce hypoglycemic events.
- Home care migration:Provincial health authorities are redirecting chronic disease management budgets from acute care facilities to community-based patient self-monitoring programs.
Market Restraints
- Biologics cold-chain infrastructure:Insulin and GLP-1 agonists require uninterrupted two-to-eight-degree Celsius distribution, constraining pharmacy dispensing radius and rural access.
- Health Canada device licensing timelines:Novel interoperable pump-sensor systems face extended pre-market review periods that delay commercialization versus FDA-cleared equivalents.
- Provincial tender concentration:Bulk purchasing by Ontario and Quebec public drug programs compresses manufacturer margins and limits pricing flexibility for innovative entrants.
Strategic Opportunities
- Remote patient monitoring integration:Telemedicine platforms are embedding CGM data streams into virtual endocrinology consultations, creating subscription revenue models beyond device sales.
- Atlantic Canada formulary gaps:New Brunswick and Nova Scotia maintain narrower public coverage for continuous glucose monitors, presenting first-mover listing advantages.
- Interoperability standards alignment:Health Canada's digital health framework is converging with FDA breakthrough pathways, enabling simultaneous North American market entry for integrated delivery systems.
Industry Challenges
- Specialized diabetes educator workforce scarcity:Certified diabetes educator training programs are not scaling to match device adoption rates, creating patient onboarding bottlenecks in community settings.
- Legacy EMR integration complexity:CGM and pump data formats lack standardized APIs with provincial electronic medical record systems, forcing manual data entry or proprietary middleware investments.
- Patent cliff biosimilar transition:Insulin analog patent expiries are triggering formulary switches that require pharmacovigilance infrastructure and patient education investments from provincial payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Diabetes Care Drugs and Devices Market |
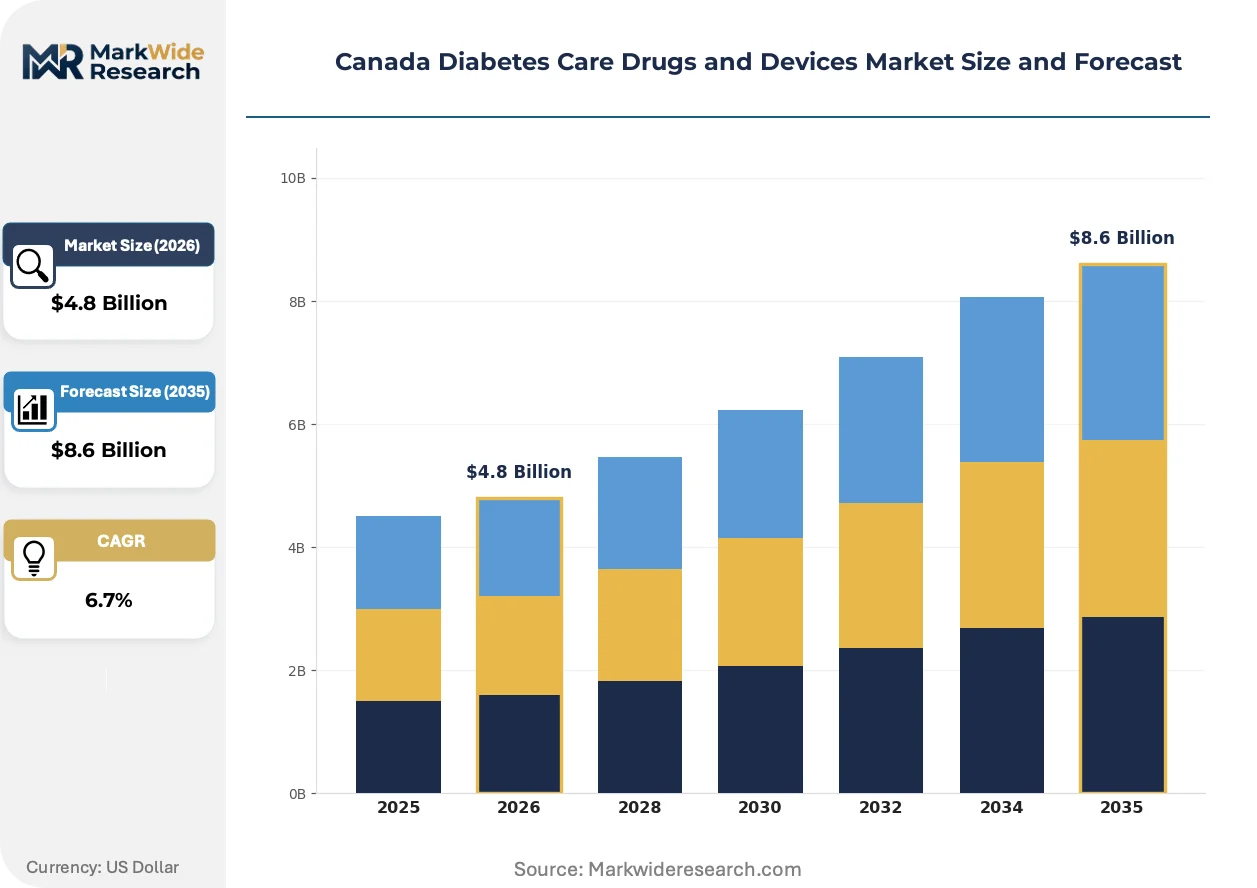
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Metformin, GLP-1 Agonists, DPP-4 Inhibitors Device Type: Smart Glucometers, Continuous Glucose Monitors, Insulin Pumps, Lancets End User: Hospitals, Clinics, Home Care, Pharmacies Application: Blood Glucose Monitoring, Insulin Delivery, Patient Management, Education |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly & Co., Abbott Laboratories, Medtronic, Dexcom, Roche, AstraZeneca, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Diabetes Care Drugs and Devices Market Strategic Shifts
Factory-calibrated glucose sensors are eliminating calibration burdens while artificial pancreas algorithms compress the gap between monitoring and automated insulin response, restructuring competitive advantage around software integration rather than hardware performance alone.
Non-adjunctive continuous glucose monitoring is decomposing the traditional fingerstick confirmation requirement for insulin dosing decisions. Patients with Type 1 diabetes are adopting factory-calibrated sensors at accelerating rates across Ontario and British Columbia. This capability compression is collapsing the separate markets for blood glucose meters and test strips into integrated sensor-platform ecosystems.
Health Canada's evolving medical device licensing framework is accelerating approvals for interoperable insulin delivery systems that pair directly with smartphone applications. The regulatory pathway now recognizes FDA breakthrough device designations, reducing redundant clinical evidence requirements. Pump manufacturers with existing US clearances are prioritizing Canadian submissions to capture provincial tender windows.
Patient data ownership preferences are shifting toward direct-to-consumer CGM purchasing outside provincial formularies. Younger, digitally native diabetes patients in urban centers are bypassing traditional pharmacy channels for subscription-based sensor delivery. British Columbia and Alberta demonstrate the highest concentration of this behavior, where out-of-pocket sensor costs are offset by workplace health spending accounts.
Canada Diabetes Care Drugs and Devices Market Segmentation
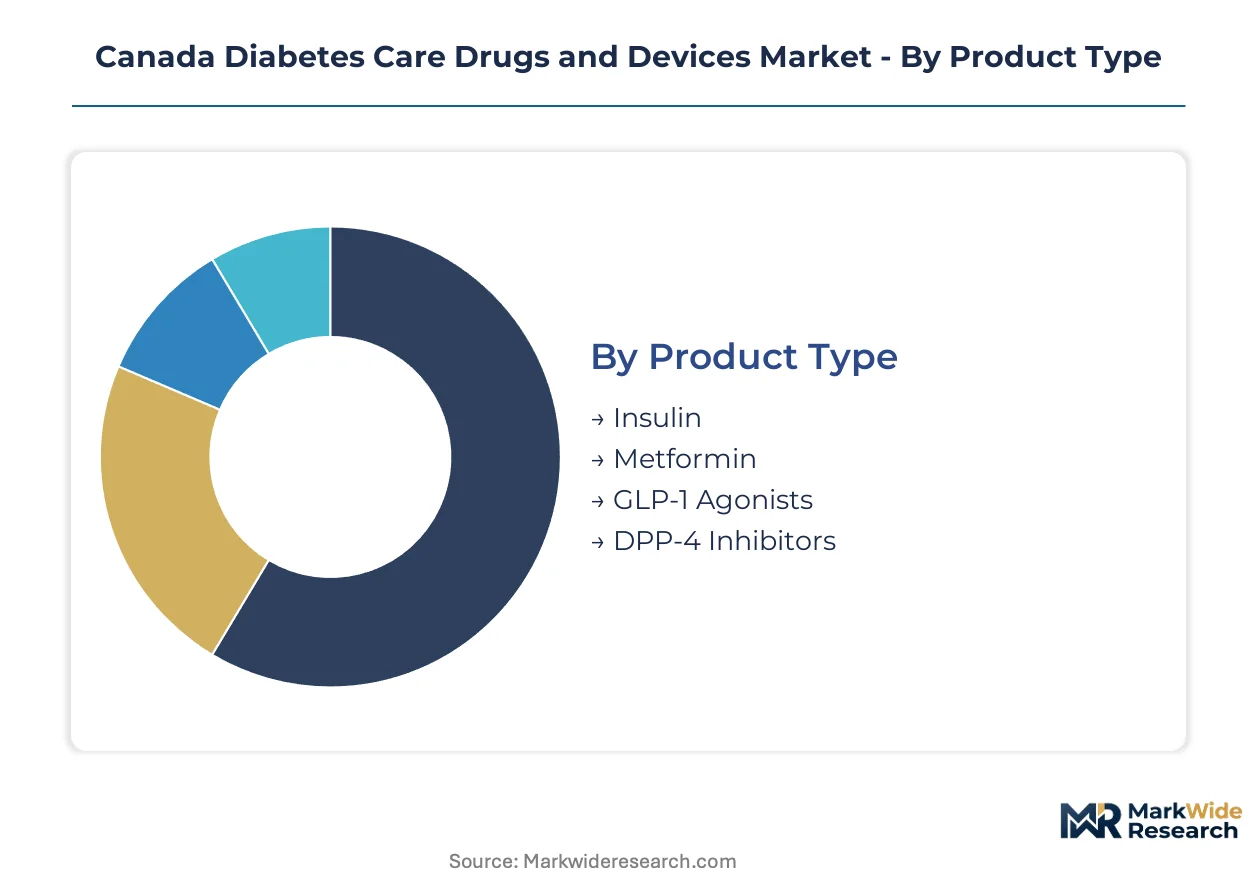
Provincial formulary decisions and reimbursement tiers fragment the Canadian diabetes market into distinct commercial battlegrounds. Product and device categories face divergent margin pressures as public drug plans favor generics while private spending concentrates on premium monitoring technologies.
Product Type:
Margin pools concentrate in biologic therapies where cold-chain infrastructure and manufacturing complexity sustain pricing power against provincial tender pressure.
- Insulin:Biosynthetic human and analog formulations require uninterrupted two-to-eight-degree Celsius distribution through pharmacy networks. Ontario and Quebec public drug programs drive volume through bulk tender arrangements, compressing margins for rapid-acting and long-acting basal variants alike.
- GLP-1 Agonists:Weekly injectable therapies for Type 2 diabetes command premium formulary positioning through demonstrated cardiovascular outcome benefits. British Columbia's Pharmacare expansion for obesity-related indications is redirecting endocrinology prescribing patterns toward this class.
- Metformin:First-line oral therapy dominates prescription volume through generic substitution mandates across all ten provinces.
- DPP-4 Inhibitors:Oral incretin enhancers face formulary delisting pressure as GLP-1 agonists displace second-line therapy positioning.
The dominant share belongs to Insulin, while GLP-1 Agonists is closing the gap fastest.
Device Type:
Revenue concentration tracks patient migration from acute care to self-directed home monitoring, elevating subscription-based sensor platforms over capital equipment.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors with smartphone pairing eliminate fingerstick requirements. OHIP+ reimbursement expansion in Ontario and direct-to-consumer subscription channels in Alberta are accelerating patient adoption curves.
- Insulin Pumps:Tethered and patch pump systems with algorithm-enabled basal rate adjustment reduce hypoglycemic event frequency. Health Canada's streamlined licensing for FDA-cleared interoperable systems is shortening commercialization timelines for closed-loop configurations.
- Smart Glucometers:Bluetooth-enabled meters with cloud data synchronization retain relevance for non-insulin-dependent Type 2 patients outside provincial CGM coverage.
- Lancets:Disposable penetration devices for capillary blood sampling face demand erosion as non-adjunctive CGM protocols eliminate confirmatory testing requirements.
Continuous Glucose Monitors capture the steepest expansion trajectory, with Insulin Pumps following as automated delivery convergence accelerates.
End User:
Patient touchpoint economics are restructuring as provincial budgets shift chronic disease management from institutional settings to community-based care.
- Home Care:Self-directed glucose monitoring and insulin administration outside clinical facilities. Ontario's community care access centers and British Columbia's home health nursing programs are expanding device dispensing authority to reduce hospital readmission rates.
- Hospitals:Inpatient glycemic management for acute metabolic decompensation and perioperative glucose control. Tertiary centers in Toronto, Vancouver, and Montreal concentrate specialized diabetes educator staffing for complex case management.
- Clinics:Outpatient endocrinology and primary care prescribing for therapy initiation and dose titration.
- Pharmacies:Dispensing nodes for insulin, oral agents, and point-of-care glucose testing supplies.
Home Care now commands the dominant patient volume share, while Clinics retain the highest prescriber influence density.
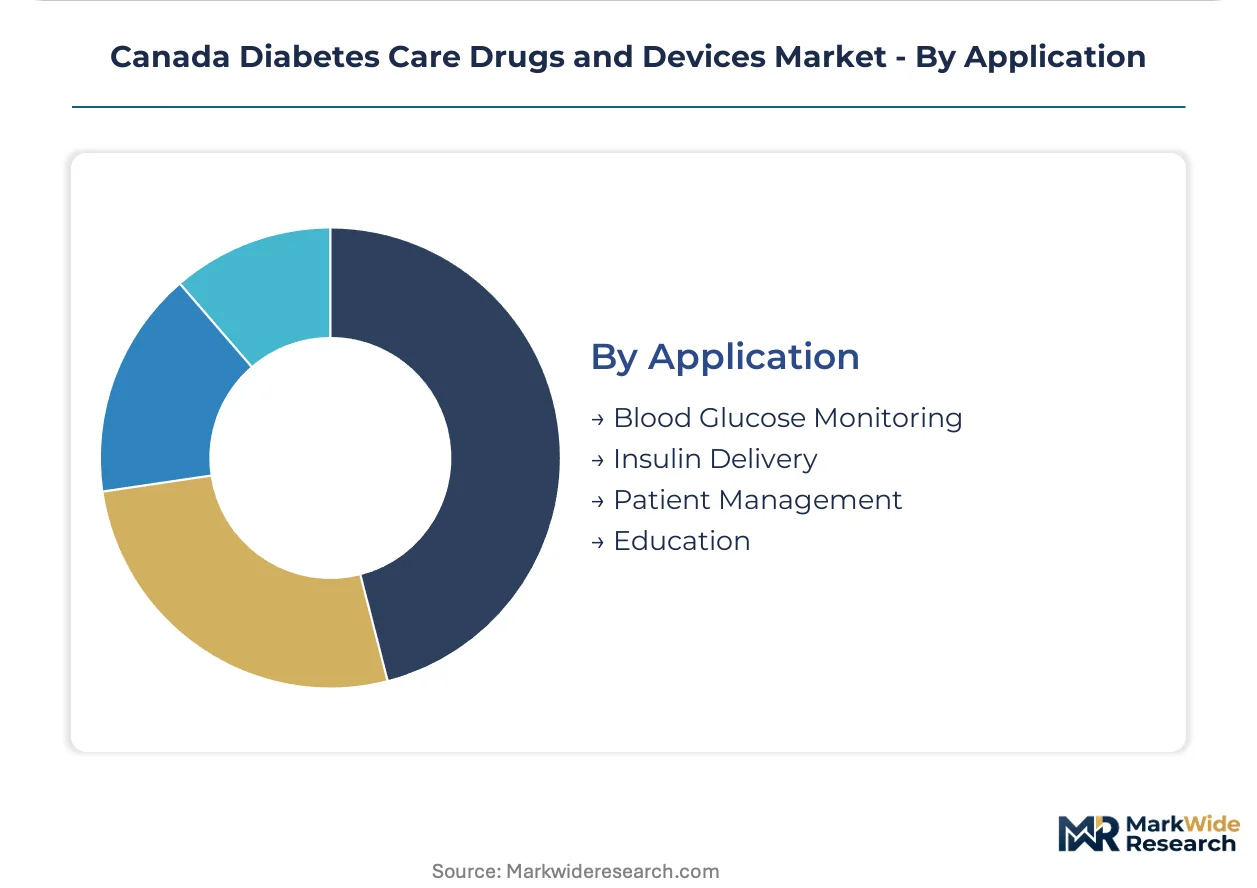
Application:
Software integration and data interoperability are creating new revenue layers beyond hardware and pharmaceutical sales.
- Blood Glucose Monitoring:Real-time and retrospective glucose trend analysis through sensor-derived data streams. Provincial electronic medical record integration gaps in Alberta and Saskatchewan are forcing middleware investments by device manufacturers.
- Insulin Delivery:Subcutaneous bolus and basal administration via syringe, pen, or pump mechanisms. Atlantic Canada formulary restrictions on pump coverage are maintaining multiple daily injection prevalence in New Brunswick and Nova Scotia.
- Patient Management:Remote monitoring platforms embedding CGM data into virtual endocrinology consultations.
- Education:Certified diabetes educator programs for device onboarding and therapy adherence support.
Blood Glucose Monitoring holds the dominant application share, with Patient Management expanding most quickly through telemedicine platform embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands premium pricing power through OHIP+ formulary expansions while Atlantic provinces operate under narrower reimbursement tiers, creating a two-speed market dynamic across provincial health systems.
Ontario
OHIP+ reimbursement for continuous glucose monitors drives patient migration toward factory-calibrated sensor platforms. Health Canada streamlined licensing recognizes FDA breakthrough designations for interoperable insulin delivery systems. Toronto's concentration of tertiary diabetes centers anchors specialized educator staffing for complex case management.
British Columbia
Pharmacare expansions for obesity-related GLP-1 indications redirect endocrinology prescribing patterns toward weekly injectable therapies. The Patented Medicine Prices Review Board's international benchmark pricing constrains launch premiums for novel biologics entering provincial distribution. Vancouver's digital health cluster supports direct-to-consumer CGM subscription channels among younger, digitally native patients.
Alberta
Workplace health spending accounts offset out-of-pocket sensor costs, accelerating adoption of premium monitoring technologies outside public formularies. Provincial community care access programs expand device dispensing authority to reduce hospital readmission rates. Calgary's health technology procurement hub concentrates bulk purchasing negotiations for insulin pump tenders.
Quebec
Public drug program bulk tender arrangements compress manufacturer margins for rapid-acting and long-acting insulin analogs. The province's cold-chain distribution infrastructure sustains pharmacy dispensing radius constraints for biologic therapies. Montreal's pharmaceutical manufacturing base anchors regional fill-finish capacity for GLP-1 agonist distribution.
Atlantic Canada
New Brunswick and Nova Scotia maintain narrower public coverage for continuous glucose monitors, preserving multiple daily injection prevalence. Formulary gaps present first-mover listing advantages for manufacturers negotiating provincial tender windows. Halifax's regional health authority concentrates specialized diabetes educator resources for rural patient onboarding.
Canada Diabetes Care Drugs and Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated biologics producers dominating drug categories and sensor specialists capturing device innovation premiums. The market structure concentrates around three strategic tiers: multinational pharmaceutical conglomerates with captive insulin supply chains, dedicated diabetes technology firms with algorithm-enabled platforms, and diversified medical device manufacturers with interoperable system portfolios. Dominant competitive moves include vertical integration into active pharmaceutical ingredient production and strategic partnerships bridging glucose monitoring data streams with automated insulin delivery algorithms.
Among the integrated biologics producers, Novo Nordisk A/S and Sanofi occupy positions anchored by captive insulin manufacturing infrastructure and established provincial formulary relationships. Dexcom and Abbott Laboratories exemplify the sensor-specialist archetype, with their market presence tied to factory-calibration capabilities and aggressive provincial tender pricing strategies. Medtronic represents the diversified device manufacturer tier, sitting within the automated insulin delivery convergence trajectory as Health Canada accelerates licensing for closed-loop system configurations.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly & Co. |
| Abbott Laboratories |
| Medtronic |
| Dexcom |
| Roche |
| AstraZeneca |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Automated fill-finish line utilization at large-scale biologics facilities shapes both supply concentration and price floors for insulin and GLP-1 agonists across Canadian provincial markets. Scale economies in sensor manufacturing similarly compress unit costs for continuous glucose monitors while sustaining margins through software subscription tiers.
Pricing Analysis
The customization-premium spread separates factory-calibrated CGM systems with smartphone integration from basic glucometer configurations. Three-tier pricing structure across premium, standard, and economy levels tracks Health Canada clearance status and interoperability certification. Cost compression in the standard tier stems from Ontario and Quebec bulk tender arrangements. Price sensitivity concentrates among insulin-dependent patients in Atlantic Canada provinces with narrower public formulary coverage.
Supply Chain Analysis
Port congestion at Vancouver and Montreal trade lanes elevates inbound logistics costs for temperature-controlled biologics shipments from Denmark and Germany. Active pharmaceutical ingredient production concentrates in Denmark, France, and the United States. Electrochemical sensor components draw from semiconductor fabrication facilities in Taiwan and South Korea. Single-source vulnerability in factory-calibration algorithm licensing creates supply chain risk. Distribution runs through pharmacy networks with cold-chain certification for biologics and direct-to-consumer subscription channels for premium monitoring devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated provincial drug programs in Ontario and Quebec, fragmenting manufacturer pricing autonomy across reimbursement tiers.
For Market Incumbents: Consolidate formulary positioning through backward integration into active pharmaceutical ingredient production and captive supply of cold-chain distribution infrastructure. Threats from biosimilar insulin analogs and algorithm-enabled pump competitors require defensive certification investment for Health Canada interoperability standards. For New Entrants and Emerging Players: Differentiate on remote patient monitoring software integration rather than hardware performance alone. Atlantic Canada formulary gaps in New Brunswick and Nova Scotia present the most penetrable geography. Direct-to-consumer subscription channels bypass provincial tender concentration. For Investors and Strategic Acquirers: Algorithm-specialist firms with FDA breakthrough designations and pending Health Canada submissions represent the priority acquisition archetype. Long-term viability hinges on software recurring revenue attachment rates rather than device unit sales. Watch for Health Canada alignment with FDA digital health pathways as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Interoperability Certification | Accelerates provincial formulary listing for integrated pump-sensor systems. |
| Provincial Tender Pre-Positioning | Captures volume commitments from Ontario and Quebec bulk purchasing programs. |
| Software Companion Development | Creates subscription revenue layers beyond hardware transaction economics. |
| Cold-Chain Distribution Partnership | Secures two-to-eight-degree Celsius integrity for biologics across rural pharmacy networks. |
| Certified Diabetes Educator Program Scaling | Reduces patient onboarding bottlenecks constraining device adoption curves. |
Study Parameters
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and certified diabetes educators provided ongoing calibration across primary interview cycles. Secondary validation drew from Health Canada medical device licensing records, provincial drug program formulary databases, Patented Medicine Prices Review Board guidelines, and hospital GPO contract filings. Bottom-up patient volume estimates and top-down expenditure flows underwent cross-triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, device category, end-user setting, and provincial regulatory cluster. CAGRs derived from fitted growth curves incorporating reimbursement expansion timelines and technology substitution rates. Forecast inputs captured Health Canada approval velocity and provincial budget allocation shifts toward home care.
The analysis sits within stated boundaries; outcomes outside sustained public formulary expansion or accelerated interoperability licensing would require recalibration. Forecasts reflect assumptions regarding provincial reimbursement continuity and cold-chain infrastructure investment. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Diabetes Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Hyperglycemia Treatment Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
Wearable Glucometers Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Glycated Albumin Market