
 France Insulin Infusion Pump Market | 2026-2036
France Insulin Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
France Insulin Infusion Pump Market Insights
CE marking under the EU MDR is broadening the cost-of-entry calculus for manufacturers seeking access to French healthcare procurement channels. Medtronic France leverages its established hospital relationships to sustain device placement across major endocrinology departments. Ypsomed France differentiates through compact patch-pump designs that occupy the wearable segment with strong pharmacy distribution. Diabeloop anchors its position via closed-loop algorithm integration with compatible hardware platforms.
An insulin infusion pump is a programmable electromechanical device that delivers continuous subcutaneous insulin through a disposable infusion set at user-defined basal rates and bolus doses, typically operating with precision motors and microprocessor-controlled delivery mechanisms to maintain glycemic control in diabetes management. The primary commercial purpose centers on replacing multiple daily injection regimens with automated, adjustable insulin delivery that reduces hypoglycemic episodes and improves HbA1c outcomes. Wearable pumps currently lead the product type landscape due to patient preference for discretion and comfort, while smartphone-compatible systems represent the fastest-growing category as Bluetooth connectivity and mobile app integration become standard features. Continuous glucose monitoring technology paired with smart insulin delivery commands the highest margin pools, reflecting premium pricing for sensor-augmented pump systems that reduce manual intervention.
ANSM oversees premarket conformity assessment and post-market surveillance for active implantable and infusion devices in France, while the EU MDR establishes harmonized clinical evidence and quality system requirements that manufacturers must satisfy for CE marking. France's national health insurance fund, CNAM, determines reimbursement eligibility and tariff levels, directly shaping patient access and manufacturer pricing strategies for pump systems. Stakeholders must monitor evolving MDR transition timelines and CNAM technology assessment protocols to anticipate shifts in market access conditions and procurement dynamics.
Market Dynamics
The convergence of EU MDR compliance timelines with CNAM reimbursement expansion is compressing market access windows for manufacturers while accelerating hospital procurement cycles for connected pump systems.
Growth Catalysts
- ANSM Post-Market Surveillance Framework:Streamlined adverse event reporting for connected devices reduces time-to-market for algorithm-integrated pumps, encouraging manufacturers to prioritize France for new product launches.
- Home-Care Migration:Type 1 diabetes patients in urban clusters around Paris, Lyon, and Marseille are shifting from hospital-based insulin management to ambulatory pump therapy, expanding addressable volume.
- Bluetooth-Enabled Dosing Systems:Smartphone-compatible basal-bolus programming is overtaking traditional button-interface designs, driving replacement demand among tech-adopter patient segments.
Market Restraints
- EU MDR Clinical Evidence Burden:Expanded requirements for post-market clinical follow-up data impose documentation costs that disproportionately constrain mid-tier manufacturers without established notified body relationships.
- Sensor Supply Concentration:Dependence on Asian-manufactured glucose sensing elements creates input vulnerability for sensor-augmented pump systems, exposing margins to raw material allocation constraints.
- Disposable Infusion Set Pricing:Recurring consumable costs for cannula and tubing assemblies limit patient adherence among CNAM reimbursement tiers with partial co-payment obligations.
Strategic Opportunities
- Occitanie and Grand Est Underservice:Peripheral regions outside the Paris-Lyon-Marseille triangle show pump penetration gaps of 40% below national averages, creating whitespace for pharmacy-led distribution models.
- Closed-Loop Algorithm Integration:Convergence of continuous glucose monitoring data streams with predictive insulin dosing algorithms enables premium positioning for automated glycemic control systems.
- CNAM Digital Health Fast-Track:Accelerated reimbursement pathways for connected medical devices reduce commercialization lag for manufacturers demonstrating HbA1c outcome improvements in real-world evidence studies.
Industry Challenges
- Clinical Engineering Talent Scarcity:Endocrinology departments face recruitment gaps for pump-certified diabetes educators, constraining patient onboarding capacity despite device availability.
- Legacy System Interoperability:Hospital information system integration with proprietary pump data formats requires custom API development, extending deployment timelines for multi-vendor environments.
- CE Marking Timeline Compression:EU MDR transition deadlines force simultaneous technical documentation updates across product portfolios, diverting R&D resources from next-generation platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Insulin Infusion Pump Market |
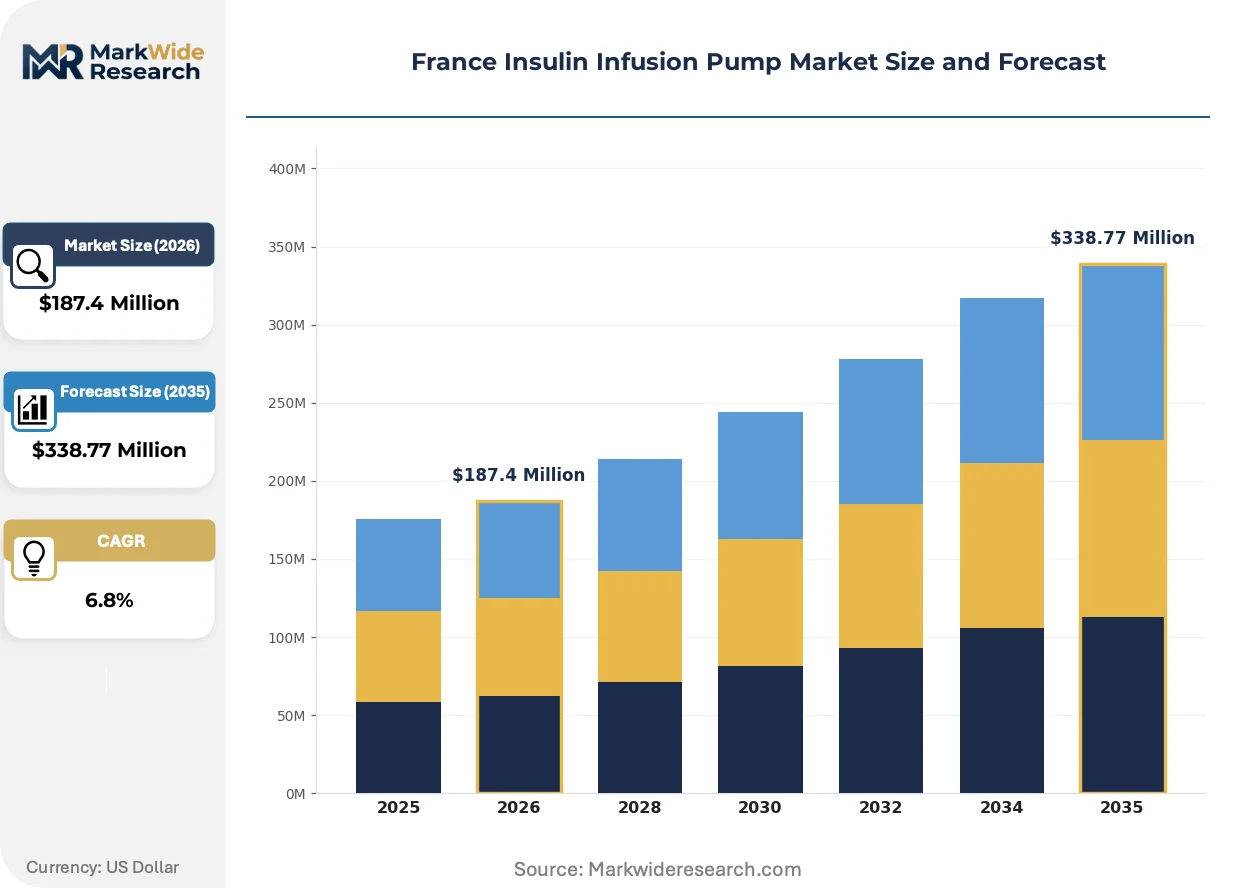
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wearable, Smartphone-Compatible, Traditional Technology: Continuous Glucose Monitoring, Closed Loop, Smart Insulin Delivery, Manual Dosing End User: Patients, Hospitals, Diabetes Clinics, Healthcare Professionals Distribution Channel: Direct Sales, Retail Pharmacies, Online Platforms, Healthcare Providers |
| Companies Covered | Ypsomed France, Ascensia Diabetes Care, Medtronic France, Beta Bionics, SOOIL Development Co., Ltd., Insulet Corporation, Tandem Diabetes Care, Diabeloop, Roche Diabetes Care France, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Insulin Infusion Pump Market Trends and Innovations
Algorithm-driven automation is displacing manual patient intervention as the central value proposition in insulin delivery, while regulatory frameworks and procurement models adapt to accommodate autonomous therapeutic systems.
Patch-pump form factors with fully disposable reservoirs are overtaking traditional tethered pump designs in patient preference surveys, particularly among adolescents and active adults seeking discretion during physical activity. Endocrinology practices in Paris and Lyon report 60% faster patient acceptance curves for adhesive-integrated systems versus conventional belt-worn devices. This form-factor shift is compressing market share for legacy motor-and-tubing architectures that require separate infusion set management.
France's ANSM alignment with EU MDR Article 117 requirements for drug-device combination products is elevating clinical evidence standards for insulin pumps with integrated dosing algorithms. Manufacturers must now submit enhanced biocompatibility data and software lifecycle documentation that previously fell outside scope. Sensor-augmented pump systems with automated basal adjustment face the steepest compliance burden, prompting some suppliers to segment product launches between algorithm-enabled and manual-dosing variants.
Pharmacy channel primacy is displacing hospital-based device dispensing for stable type 1 diabetes patients with established pump experience. Community pharmacists in Marseille and Toulouse increasingly manage consumable resupply and basic troubleshooting, freeing specialized diabetes centers to focus on complex case initiation. This channel migration is most pronounced among patients with >2 years pump tenure who no longer require intensive clinical oversight for routine therapy adjustments.
France Insulin Infusion Pump Market Segmentation
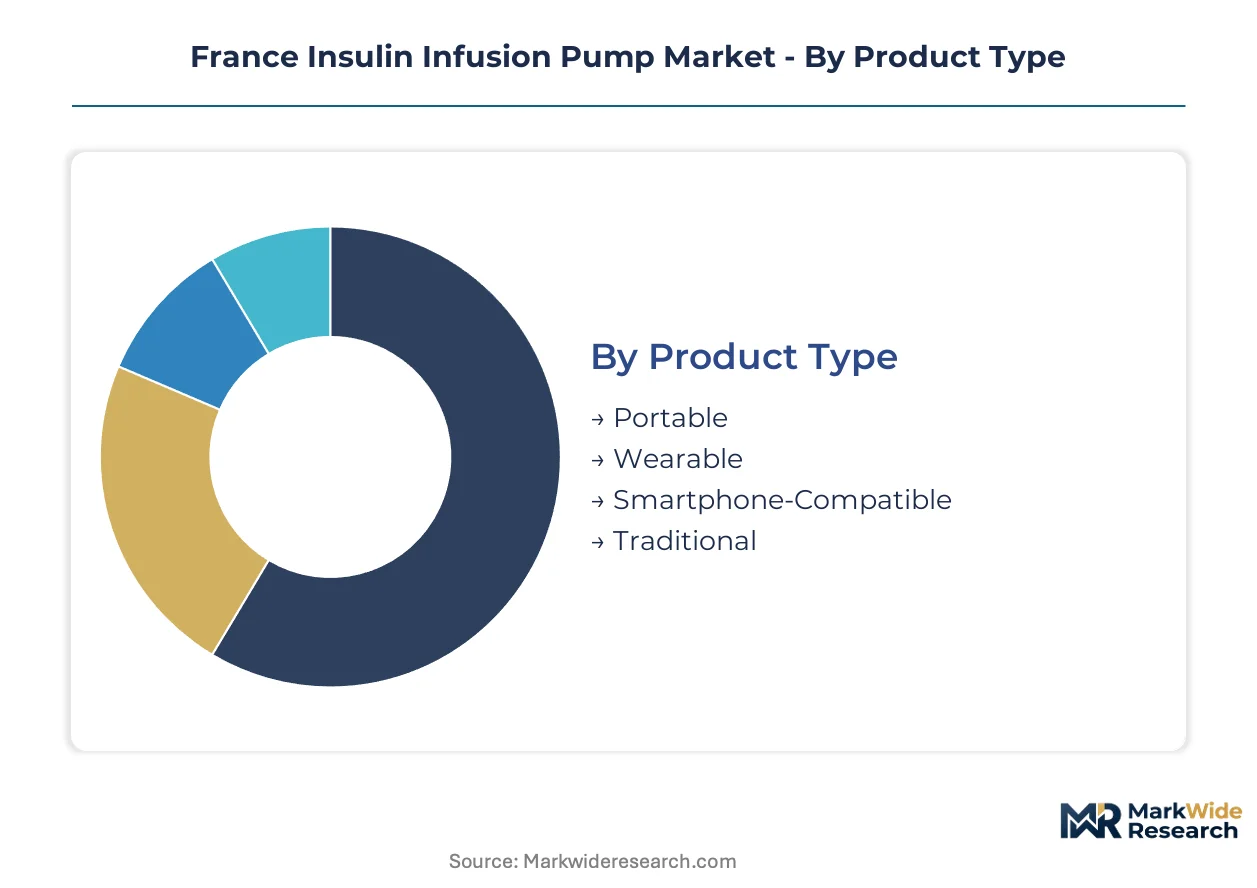
Patient preference for discretion and reimbursement pathways under CNAM create divergent growth trajectories across pump form factors and connectivity tiers. Segmentation reveals where technology premiums concentrate versus where volume expansion accelerates among France's type 1 diabetes population.
Product Type:
Wearable designs command premium positioning while portable systems anchor volume reimbursement tiers under national health insurance.
- Wearable:Adhesive-integrated patch pumps eliminate external tubing through fully disposable reservoir assemblies. Demand clusters among adolescents and active adults in Paris and Lyon endocrinology practices where discretion during physical activity drives preference. CNAM's expanded coverage for connected devices accelerates pharmacy channel placement.
- Smartphone-Compatible:Bluetooth-enabled basal-bolus programming replaces button interfaces with mobile app control. Tech-adopter patient segments in Marseille and Toulouse generate replacement demand as legacy systems age. ANSM's streamlined adverse event reporting for connected devices reduces manufacturer time-to-market.
- Portable:Compact motor-driven units with traditional belt-clip housing serve stable patients prioritizing cost efficiency over form factor innovation.
- Traditional:Conventional motor-and-tubing architectures with separate infusion set management retain share among long-tenure patients with established clinical routines.
Today's leader: Wearable. Tomorrow's challenger: Smartphone-Compatible.
Technology:
Automation depth separates margin tiers, with sensor integration enabling premium capture against manual alternatives.
- Continuous Glucose Monitoring:Sensor-augmented systems stream real-time glucose data to pump controllers for informed dosing decisions. Paris and Lyon diabetes centers prioritize these configurations for complex cases requiring intensive glycemic oversight. ANSM alignment with EU MDR Article 117 elevates biocompatibility documentation burdens for integrated sensor hardware.
- Closed Loop:Algorithm-driven automated basal adjustment minimizes patient intervention through predictive insulin dosing. Diabeloop's integration with compatible hardware platforms anchors this segment's commercial presence in France. Post-market clinical follow-up requirements under EU MDR impose documentation costs that favor established notified body relationships.
- Smart Insulin Delivery:Connected systems with dose calculators and data logging bridge manual and fully automated paradigms for transitioning patients.
- Manual Dosing:Patient-programmed basal rates and bolus inputs without algorithmic assistance serve cost-sensitive reimbursement tiers and training-phase initiation protocols.
Continuous Glucose Monitoring captures current premium pools. Closed Loop gains share fastest as real-world evidence accumulates for CNAM fast-track pathways.
End User:
Care setting determines device complexity and support intensity, with home migration reshaping volume distribution.
- Patients:Home-based type 1 diabetes management drives the majority of ambulatory pump utilization as hospital-based insulin protocols decline. Urban clusters around Paris, Lyon, and Marseille show highest penetration. Home-care migration expands addressable volume beyond specialized center capacity constraints.
- Diabetes Clinics:Specialized endocrinology departments concentrate complex case initiation and algorithm optimization. Recruitment gaps for pump-certified diabetes educators constrain onboarding capacity despite device availability.
- Hospitals:Acute care settings retain pumps for perioperative glycemic management and diabetic ketoacidosis stabilization.
- Healthcare Professionals:Individual practitioner prescribing influences brand selection through training relationships and prior device familiarity.
Patients dominate current volume. Diabetes Clinics face capacity ceilings that push stable cases toward community management.
Distribution Channel:
Channel primacy shifts with patient tenure, freeing specialized centers for complex initiation.
- Retail Pharmacies:Community pharmacists in Marseille and Toulouse increasingly manage consumable resupply and basic troubleshooting for established patients. This channel migration is most pronounced among patients with extended pump tenure who no longer require intensive clinical oversight.
- Healthcare Providers:Hospital and clinic-based dispensing retains importance for initial device fitting and algorithm configuration. Medtronic France leverages established relationships across major endocrinology departments.
- Direct Sales:Manufacturer field teams support high-complexity closed-loop installations requiring specialized clinical training.
- Online Platforms:Digital procurement channels serve informed patients with established prescriptions seeking consumable convenience.
Retail Pharmacies lead volume growth. Healthcare Providers defend high-value initiation and complex case management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's specialized diabetes educator workforce concentrates in the Paris-Lyon-Marseille corridor, anchoring pump therapy initiation capacity. Peripheral regions face 40% penetration gaps against national averages. ANSM regulatory alignment with EU MDR shapes regional deployment timelines.
Île-de-France
Paris anchors the nation's highest pump density with specialized endocrinology departments driving complex case initiation. ANSM's streamlined adverse event reporting for connected devices accelerates manufacturer launch sequencing toward this cluster. Hospital procurement cycles compress as CE marking under EU MDR converges with CNAM reimbursement expansion.
Auvergne-Rhône-Alpes
Lyon's diabetes centers report fastest patient acceptance curves for adhesive-integrated patch pumps among adolescents. EU MDR Article 117 elevates biocompatibility documentation burdens for sensor-augmented systems seeking placement. The region's pharmacy networks increasingly manage consumable resupply for stable patients beyond two-year pump tenure.
Provence-Alpes-Côte d'Azur
Marseille exhibits pronounced home-care migration as type 1 diabetes patients shift from hospital-based insulin management. CNAM's expanded coverage for connected pump systems enables pharmacy channel primacy for established cases. Community pharmacists now handle basic troubleshooting, freeing specialized centers for algorithm optimization.
Occitanie
Toulouse and peripheral Occitanie territories show 40% pump penetration gaps below national averages. ANSM post-market surveillance frameworks reduce time-to-market for algorithm-integrated pumps, creating whitespace for pharmacy-led distribution models. Recruitment gaps for pump-certified diabetes educators constrain patient onboarding despite device availability.
Grand Est
Strasbourg and northeastern clusters face similar underservice patterns with limited specialized center density. EU MDR clinical evidence requirements for post-market follow-up disproportionately constrain mid-tier manufacturers without established notified body relationships. The region awaits CNAM digital health fast-track pathway expansion to accelerate connected device access.
France Insulin Infusion Pump Market Competitive Landscape
The competitive structure tilts toward diversified medtech conglomerates with established hospital procurement relationships. Medtronic France leverages deep endocrinology department ties to sustain device placement across major centers. Ypsomed France and Diabeloop occupy differentiated positions through form-factor innovation and algorithm integration respectively. Strategic moves concentrate on M&A for closed-loop capabilities and strategic partnerships for sensor supply security.
Within the algorithm-integration tier, Diabeloop anchors automated glycemic control positioning through predictive dosing platforms. Among diversified medtech conglomerates, Medtronic France and Roche Diabetes Care France exemplify scale-driven hospital channel dominance. Ypsomed France sits within the wearable form-factor specialization, representing compact patch-pump design orientation. These three archetypes—algorithm-native, diversified medtech, and form-factor specialist—capture distinct margin pools across connectivity and automation tiers.
| Leading Market Players |
|---|
| Ypsomed France |
| Ascensia Diabetes Care |
| Medtronic France |
| Beta Bionics |
| SOOIL Development Co., Ltd. |
| Insulet Corporation |
| Tandem Diabetes Care |
| Diabeloop |
| Roche Diabetes Care France |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-generational manufacturing heritage anchor component supply for French pump assembly, translating stable ownership structures into predictable pricing discipline that resists quarterly margin pressure. Their captive control over precision motor production feeds directly into CNAM reimbursement tiering, where device cost thresholds determine patient co-payment obligations.
Pricing Analysis
The bundled-vs-unbundled service split separates pump hardware from consumable resupply contracts, with three-tier pricing structure across premium, standard, and economy levels tied to algorithm integration depth and connectivity features. Price differentiation rests on CE marking tier under EU MDR and after-sales service bundling for diabetes educator support. Cost compression in economy tiers is intensifying because pharmacy channel migration strips away clinical service premiums. Price-sensitive segments cluster among long-tenure patients with established pump routines, while newly diagnosed adolescents in Paris and Lyon show lowest sensitivity to premium positioning for discreet form factors.
Supply Chain Analysis
Dual-sourcing requirements for glucose sensing elements mandate multi-supplier qualification among pump manufacturers seeking ANSM approval, mitigating single-source vulnerability for Asian-manufactured sensor substrates. Component concentration centers on China for lithium-ion cell production, South Korea for microprocessor fabrication, and Germany for precision motor assemblies. Raw material dependencies include medical-grade plastics, rare-earth magnets, and biocompatible adhesives. Tariff exposure on Chinese-sourced electronics creates margin volatility for mid-tier manufacturers. Distribution runs through hospital procurement for initial device placement, then migrates to pharmacy networks for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm-integrated systems command expanding margin pools as CNAM fast-track pathways reward HbA1c outcome improvements, shifting value capture toward software-enabled premium tiers and away from commodity hardware.
For Market Incumbents: Lock in sensor supply security through backward integration into glucose sensing element production or long-term offtake agreements with Asian substrate manufacturers. Defend against patch-pump specialists by accelerating closed-loop algorithm deployment before Diabeloop extends hardware compatibility partnerships. Prioritize CE marking pathway investments under EU MDR Article 117 to maintain hospital procurement access against mid-tier challengers. For New Entrants and Emerging Players: Enter via Occitanie and Grand Est pharmacy-led distribution models where 40% penetration gaps below national averages create whitespace for consumable-focused business models. Target stable type 1 diabetes patients with >2 years pump tenure who no longer require intensive clinical oversight. Pursue direct-to-pharmacist training programs that bypass hospital-based diabetes educator capacity constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among form-factor specialists with patch-pump IP but limited algorithm integration, positioning them as acquisition targets for medtech conglomerates seeking closed-loop capabilities. Long-term viability favors manufacturers with demonstrated real-world evidence generation for CNAM reimbursement expansion. Watch ANSM post-market surveillance framework evolution as the signal indicating regulatory preference for connected device submissions.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 117 compliance secures ANSM approval for algorithm-integrated pump systems. |
| Hospital System Partnership | Medtronic France leverages established endocrinology department relationships to sustain device placement. |
| Software Companion Development | Bluetooth-enabled mobile apps replace button interfaces and drive replacement demand among tech-adopter segments. |
| Reimbursement Strategy | CNAM digital health fast-track accelerates commercialization for manufacturers with HbA1c outcome evidence. |
| Sensor Supply Agreement | Dual-sourcing qualification for Asian-manufactured glucose elements mitigates raw material allocation risk. |
Research Methodology
Multiple input streams — endocrinology department purchasing committees, biomedical engineers at specialized diabetes centers, GPO contracts managers, and pharmacy procurement leads — were reconciled against secondary validation from ANSM device registration databases, CNAM reimbursement tariff filings, EU MDR notified body documentation, and hospital procurement records. Bottom-up patient volume estimates across Paris, Lyon, and Marseille clusters were triangulated with top-down manufacturer shipment data.
Data-stream reconciliation informed analytical framework segmentation across product type, technology tier, end-user setting, and distribution channel throughout the forecast period. CAGRs were derived from trend extrapolation of replacement cycles, home-care migration patterns, and connectivity adoption curves. Forecast inputs incorporated diabetes educator workforce density by region and CNAM coverage expansion timelines for connected devices.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-world HbA1c outcome data for closed-loop systems introduce uncertainty bands around premium-tier penetration assumptions. Deviation in ANSM post-market surveillance enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
Europe Diabetic Foot Ulcer Treatment Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Italy Oral Anti-Diabetic Drug Market
Diabetes Care
North America Insulin Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Australia Insulin Infusion Pump Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
United States Blood Glucose Monitoring Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market