
 Diabetic Footwear Market | 2026-2036
Diabetic Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetic Footwear Market Intelligence
Production capacity expansion in Southeast Asia, particularly in Vietnam and Indonesia, is realigning the supply chain for therapeutic insoles and orthopedic shoes. Orthofeet Inc. leverages its direct-to-consumer online channel to capture a wider patient base. Aetrex Worldwide Inc. differentiates through its integration of 3D foot scanning technology into retail settings. DJO Global Inc. sustains a strong presence in the clinical channel, supplying rehabilitation centers and orthopedic clinics.
Diabetic footwear comprises specially designed shoes, insoles, and socks engineered to reduce the risk of foot complications in individuals with diabetes. These products often feature a non-binding design, extra depth to accommodate custom orthotics, and a seamless interior to prevent skin irritation. Orthopedic shoes constitute the largest product segment, driven by clinical prescriptions and reimbursement policies. The distribution landscape shows a notable shift towards online retailers, which offer a wider selection and direct patient access.
Regulatory frameworks, such as the U.S. FDA's classification of certain products as medical devices and Europe's CE marking requirements, mandate stringent quality and safety standards. Adherence to standards like ISO 13485 for medical device quality management is critical for market access. Future product development will hinge on integrating smart technologies for pressure monitoring while navigating diverse international reimbursement landscapes.
Market Dynamics
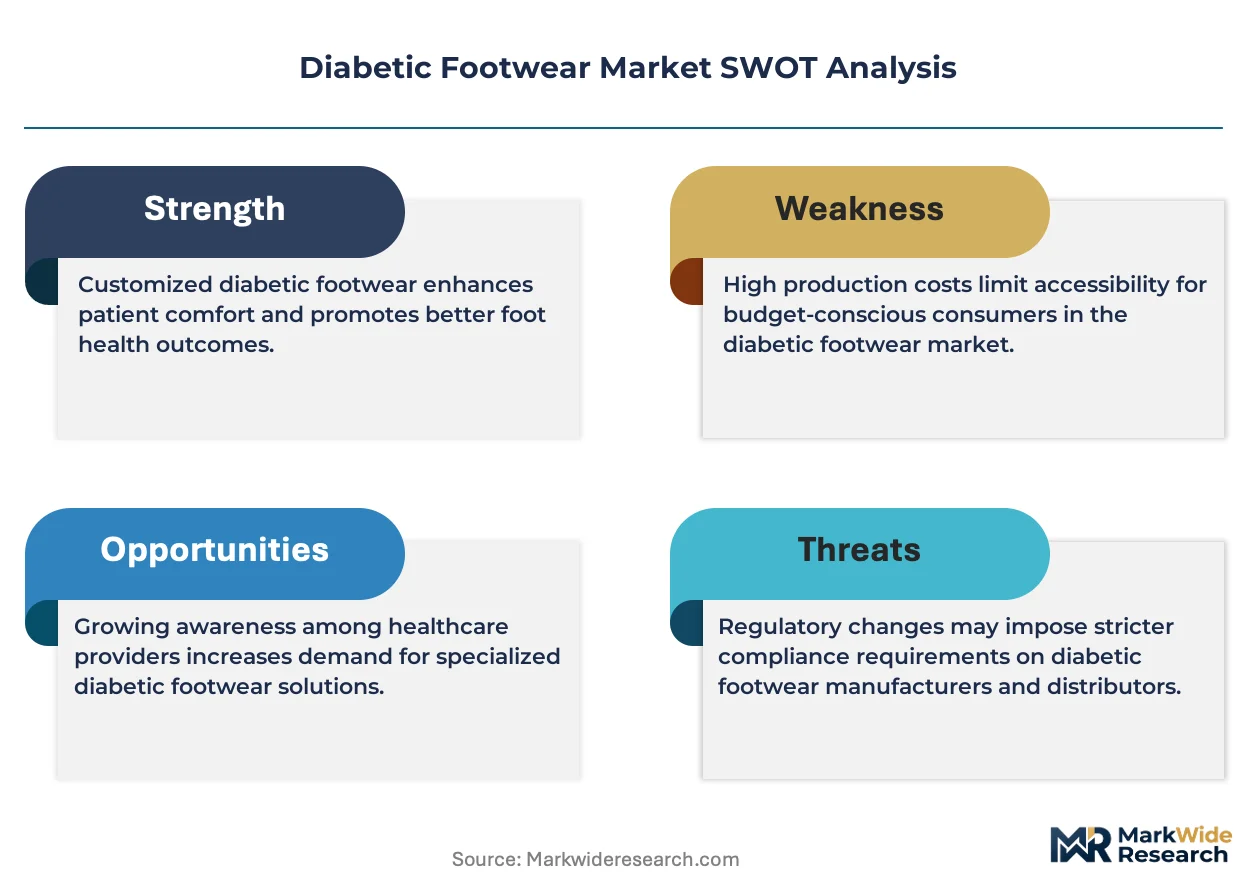
The formalization of the market under medical device frameworks is the central force shaping the diabetic footwear industry. This regulatory tightening, led by bodies like the US FDA and European authorities, is compelling a realignment of global supply chains toward compliant manufacturing hubs.
Growth Catalysts
- Reimbursement Policies:Favorable reimbursement schemes, such as the U.S. Medicare Therapeutic Shoe Bill, directly support patient access and drive clinical demand for prescribed orthopedic shoes and custom insoles.
- Aging Demographics:The rising prevalence of diabetes within aging populations, particularly in developed nations like Japan and Germany, expands the core patient base requiring specialized footwear for preventative care.
- Material Innovation:The adoption of advanced materials, including multi-density foams and moisture-wicking linings, improves therapeutic efficacy and patient comfort, encouraging consistent use and better clinical outcomes.
Market Restraints
- High Product Costs:The expense of custom-molded orthotics and medically-certified footwear creates a significant affordability barrier for patients in regions lacking comprehensive public or private insurance coverage.
- Regulatory Compliance Burden:Adhering to disparate international standards, such as Europe's MDR for CE marking and the FDA's device classifications, increases development costs and time-to-market for manufacturers.
- Substitution from Consumer Brands:Widely available comfort and athletic footwear from mass-market brands acts as a low-cost substitute, diverting potential customers with less severe symptoms from medically-designed products.
Strategic Opportunities
- Smart Technology Integration:Incorporating pressure-sensing smart insoles that provide real-time feedback to a user's smartphone offers a new paradigm for ulcer prevention and remote patient monitoring.
- Direct-to-Consumer Channels:Expanding online DTC sales models enables manufacturers to control the customer experience, gather valuable patient data, and capture higher margins by bypassing traditional distributors.
- Geographic Expansion:Untapped markets in the Gulf Cooperation Council countries, where diabetes rates are high, present significant growth potential for companies able to navigate local healthcare system requirements.
Industry Challenges
- Quality Management System Demands:The stringent documentation, process control, and auditing required to achieve and maintain ISO 13485 certification for medical devices presents a continuous operational challenge.
- Supply Chain Reconfiguration:Shifting manufacturing to lower-cost regions like Vietnam and Indonesia introduces risks related to quality control consistency, logistics management, and intellectual property protection.
- Specialized Skills Scarcity:A lack of certified pedorthists and footwear technicians capable of accurately fitting and modifying therapeutic products can limit market growth and compromise patient outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetic Footwear Market |
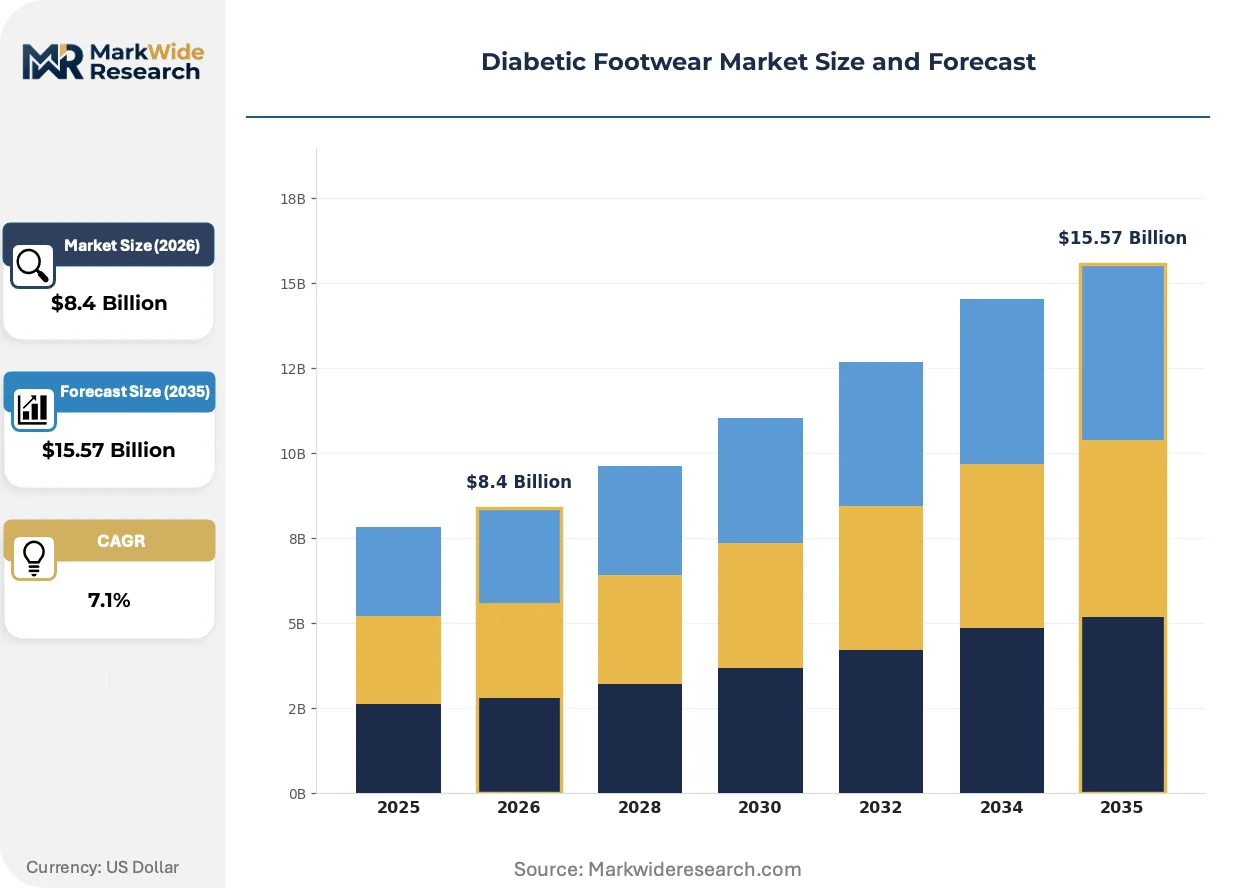
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.57 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Shoes, Therapeutic Insoles, Custom-Made Footwear, Pressure Relief Shoes, Diabetic Socks Technology: Memory Foam, Gel Padding, Breathable Mesh, Antimicrobial Coating, Shock Absorption End User: Adults with Neuropathy, Elderly Patients, Rehabilitation Centers, Sports Injury Clinics, Physical Therapy Facilities Distribution Channel: Specialty Stores, Online Retailers, Medical Supply Distributors, Pharmacies, Orthopedic Clinics |
| Companies Covered | Orthofeet Inc., Aetrex Worldwide Inc., Drew Shoe Corporation, DJO Global Inc., Podartis Srl, DARCO International Inc., Propet USA Inc., Pilgrim Shoes, Finn Comfort USA Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetic Footwear Market Strategic Shifts & Innovations
Material science and digital health technologies are converging to transform diabetic footwear from a passive support product into an active component of preventative care. This evolution focuses on personalization, data-driven feedback loops, and enhanced patient compliance through superior comfort and design.
Three-dimensional printing technology enables the rapid and precise fabrication of custom orthotics directly from digital foot scans. Podiatry clinics and specialized retailers are adopting this process to deliver personalized solutions with significantly shorter lead times than traditional methods. This on-demand manufacturing capability is consolidating the supply chain by reducing the industry's reliance on centralized, slow-turnaround casting and milling facilities.
Europe's Medical Device Regulation (MDR) has elevated the compliance threshold for many diabetic footwear products sold within the EU. The regulation mandates more rigorous clinical evidence, post-market surveillance, and technical documentation for items to receive a CE marking. The orthopedic shoes segment is most impacted, compelling manufacturers to invest heavily in updating their quality management systems and proving product safety and performance claims.
A distinct shift in patient behavior toward online purchasing is disrupting traditional clinical and retail distribution channels. Direct-to-consumer brands leverage virtual fitting tools, lenient return policies, and broader aesthetic choices to attract patients seeking greater convenience and autonomy. This channel disintermediation is most visible in the United States, where a mature e-commerce infrastructure supports direct patient access and brand engagement.
Diabetic Footwear Market Segmentation
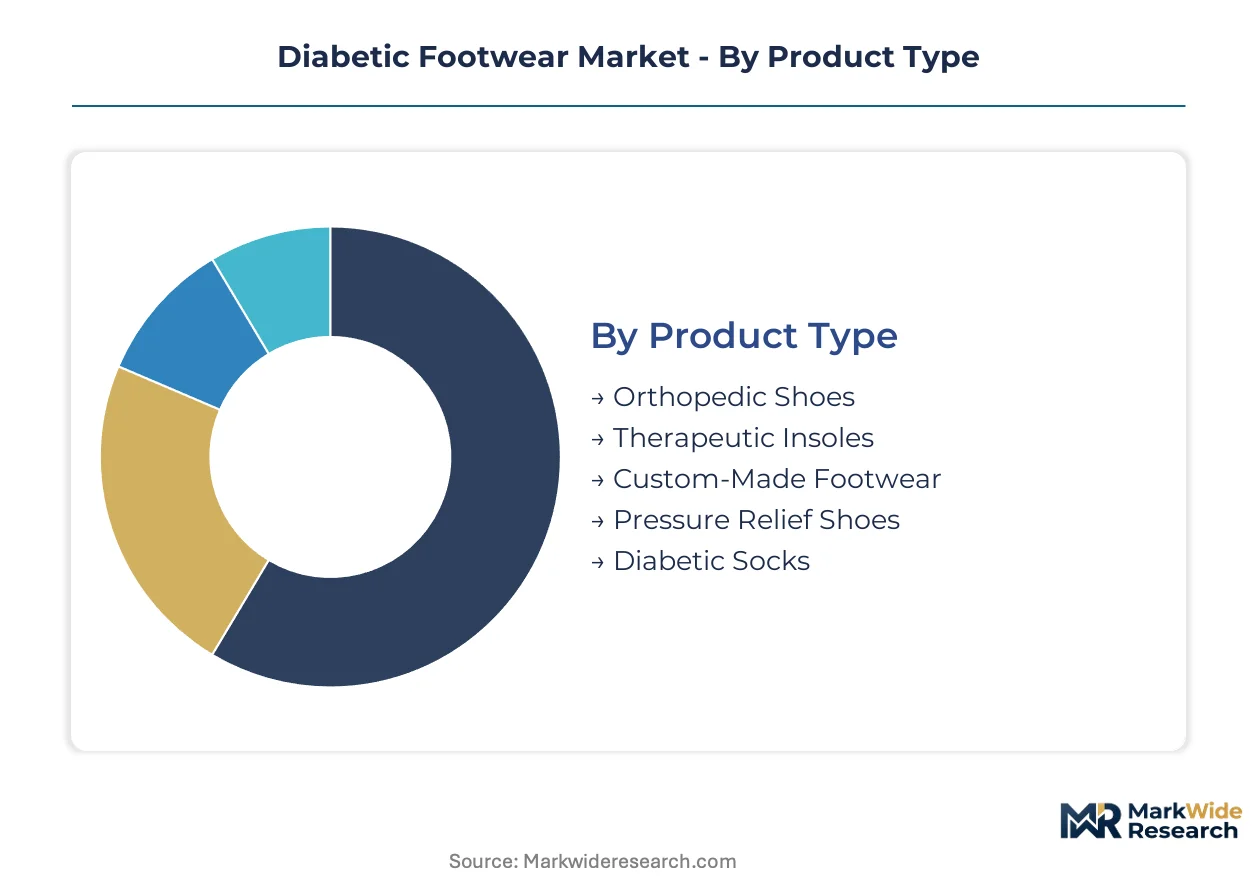
The diabetic footwear market's segmentation highlights the diverse product offerings and specialized needs of its patient base. Understanding these segments is crucial for manufacturers to tailor product development, optimize distribution strategies, and address specific clinical requirements across different end-user groups.
Product Type:
The product type segmentation highlights the specialized design characteristics inherent in diabetic footwear, each addressing distinct aspects of foot health for individuals with diabetes.
- Orthopedic Shoes:These are prescribed medical devices, often custom-fitted, providing critical support and protection for diabetic patients. Demand concentrates in Germany and Japan due to aging populations and strong clinical prescription policies.
- Therapeutic Insoles:Designed to distribute pressure evenly across the foot, these insoles prevent ulcer formation and enhance comfort. Their use expands within rehabilitation centers, driven by patient-specific needs for pressure management.
- Custom-Made Footwear:Tailored to individual foot deformities or severe conditions, this footwear offers precise fit and maximum protection.
- Pressure Relief Shoes:Engineered with specialized soles and interiors, these shoes minimize pressure points to prevent skin breakdown.
- Diabetic Socks:Non-binding and moisture-wicking, these socks improve circulation and reduce friction for daily foot care.
Mature deployment sits with Orthopedic Shoes. Newer deployment is concentrated in Pressure Relief Shoes.
Technology:
Application focus guides the development of specialized technologies in diabetic footwear, enhancing both therapeutic efficacy and patient comfort.
- Breathable Mesh:This material promotes air circulation, reducing moisture and the risk of fungal infections for diabetic patients. Demand is high in regions with warmer climates, such as Southeast Asia, where skin health is a concern.
- Shock Absorption:Components designed to absorb impact reduce stress on the foot, protecting sensitive areas from repetitive trauma. Elderly patients and individuals with active lifestyles require this feature to maintain mobility and prevent injury.
- Memory Foam:This material conforms to the foot's shape, providing personalized cushioning and pressure distribution.
- Gel Padding:Strategically placed gel inserts offer targeted cushioning and reduce impact in high-pressure areas.
- Antimicrobial Coating:Applied to interior materials, these coatings inhibit bacterial and fungal growth, maintaining foot hygiene.
Breathable Mesh technology represents the fastest-growing trajectory. Memory Foam technology also expands quickly.
End User:
Customer type differentiation reveals specific needs and care requirements across the diabetic patient population, influencing product design and market outreach.
- Elderly Patients:This demographic often experiences reduced sensation and impaired circulation, necessitating protective footwear to prevent falls and skin breakdown. Demand is particularly strong in developed nations with high life expectancies, like the U.S. and Germany.
- Rehabilitation Centers:These facilities require a range of specialized footwear for post-operative care and gait training, often integrating custom orthotics. Clinical demand in these settings is supported by medical referrals and insurance coverage.
- Adults with Neuropathy:Individuals with nerve damage require seamless interiors and extra depth to prevent irritation and accommodate swelling.
- Sports Injury Clinics:These clinics cater to patients requiring therapeutic footwear for recovery from foot-related injuries exacerbated by diabetes.
- Physical Therapy Facilities:These facilities utilize diabetic footwear as part of comprehensive treatment plans for mobility improvement and ulcer prevention.
Demand from Elderly Patients remains substantial. Sports Injury Clinics show the steepest expansion trajectory.
Distribution Channel:
Volume dynamics shape the effectiveness of various distribution channels for diabetic footwear, impacting accessibility and market reach for consumers.
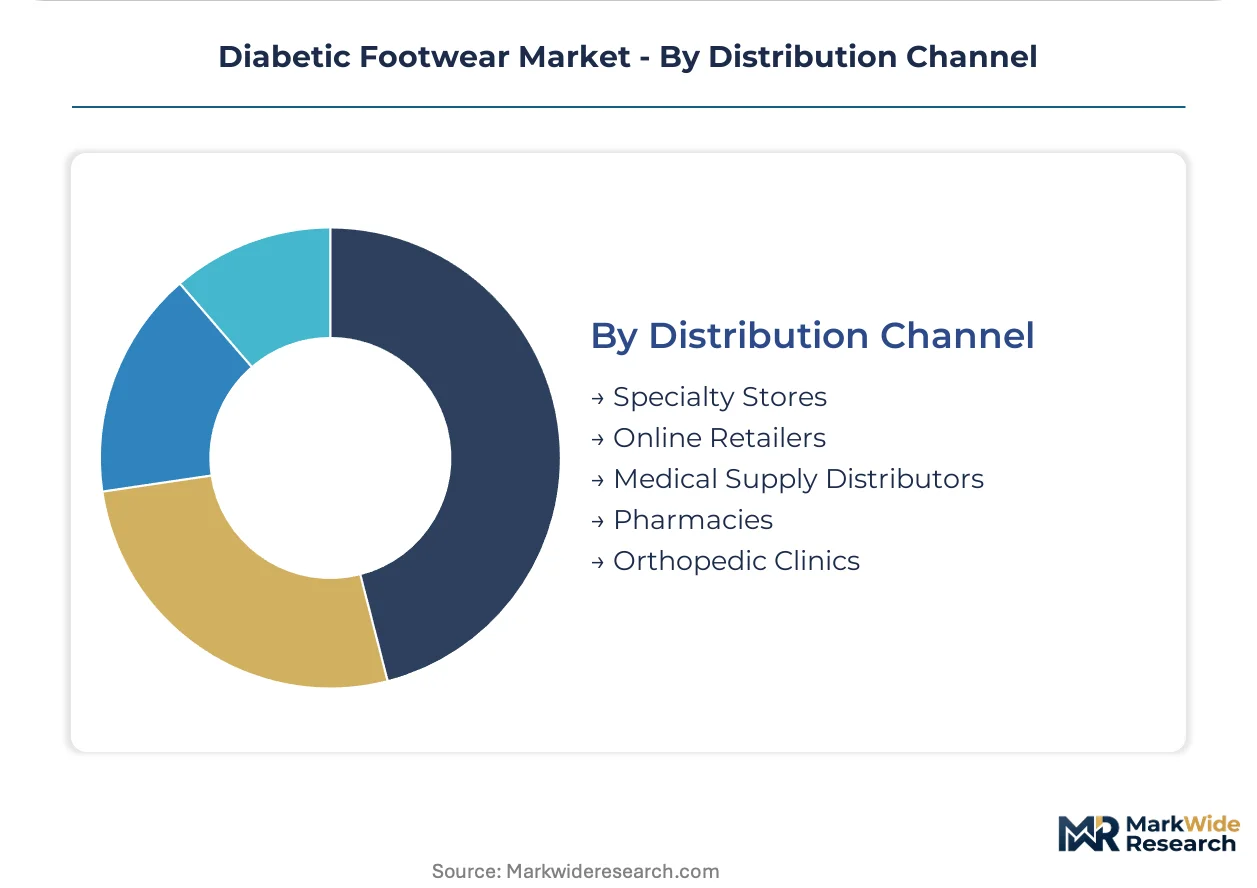
- Online Retailers:These platforms offer extensive product catalogs, comparative pricing, and direct-to-consumer convenience, attracting a broad patient base. The U.S. market leads in online sales due to its mature e-commerce infrastructure.
- Orthopedic Clinics:These specialized medical environments provide expert fitting services and clinical prescriptions, ensuring patients receive appropriate therapeutic footwear. Their presence is strong in countries with established healthcare systems, such as Japan and Germany.
- Specialty Stores:Focused on medical and comfort footwear, these stores offer personalized fitting and product expertise.
- Medical Supply Distributors:These distributors supply a wide range of healthcare products, including diabetic footwear, to hospitals and clinics.
- Pharmacies:Increasingly, pharmacies offer over-the-counter diabetic socks and basic therapeutic insoles for convenient patient access.
Online Retailers are gaining share fastest. Medical Supply Distributors maintain a stable presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced healthcare infrastructure significantly influences the European diabetic footwear market. The nation's robust clinical prescription policies ensure patient access to specialized products. This focus supports innovation and demand for high-quality therapeutic solutions across the region.
United States
An aging population and high diabetes prevalence drive demand for specialized footwear in the United States. The U.S. Medicare Therapeutic Shoe Bill directly supports patient access to prescribed therapeutic shoes. California's tech hubs foster innovation in smart footwear solutions for remote monitoring.
Germany
Aging demographics and a strong preventative care culture characterize the German market for diabetic footwear. CE marking requirements mandate stringent quality and safety standards for medical devices. Bavaria's medical technology sector advances orthopedic footwear development and manufacturing.
Japan
Japan's exceptionally high elderly population sustains a consistent demand for specialized diabetic footwear. National health insurance schemes facilitate access to prescribed medical devices for patients. Tokyo's specialized clinics integrate 3D foot scanning technology for precise custom fittings.
United Arab Emirates
High diabetes rates and rising health awareness contribute to a growing market for diabetic footwear in the UAE. MOHAP regulations guide medical device imports and distribution within the country. Dubai's healthcare free zones attract international manufacturers and specialized retailers.
China
China's vast diabetic population and increasing healthcare expenditure fuel market expansion for therapeutic footwear. NMPA oversight ensures product quality and safety for medical devices sold domestically. The Yangtze River Delta region sees expanding production of therapeutic insoles and orthopedic shoes.
Diabetic Footwear Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution reach in the diabetic footwear market. The industry structure is tiered, featuring specialized therapeutic providers and broad-portfolio firms. Key archetypes include technology integrators, comfort-focused brands, and clinical channel specialists. Strategic partnerships for technology integration and geographic expansion are common competitive moves.
Specialized therapeutic providers like Orthofeet Inc. and DJO Global Inc. focus on clinical channels and direct-to-consumer online sales. Orthofeet Inc. exemplifies leveraging online channels to capture a wider patient base. Aetrex Worldwide Inc. differentiates itself through the integration of 3D foot scanning technology into retail settings, enhancing personalization. These companies represent distinct approaches to market penetration and patient engagement within the diabetic footwear segment.
| Leading Market Players |
|---|
| Orthofeet Inc. |
| Aetrex Worldwide Inc. |
| Drew Shoe Corporation |
| DJO Global Inc. |
| Podartis Srl |
| DARCO International Inc. |
| Propet USA Inc. |
| Pilgrim Shoes |
| Finn Comfort USA Inc. |
| Others |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) implementation gates qualified supply and premium-tier pricing access for diabetic footwear. This regulatory tightening compels manufacturers to invest in compliant production processes and materials.
Pricing Analysis
Warranty bundling and extended service agreements differentiate premium diabetic footwear products from basic offerings. The dominant pricing model remains per-unit transactional, though value-based pricing emerges for highly customized solutions like 3D-printed orthotics. Price differentiation stems from the product's quality grade, its specific medical device certification level (e.g., CE marking, FDA classification), and the level of customization. Pricing softness reflects cost compression in the standard therapeutic insole segment due to competition from mass-market comfort brands. Patients with comprehensive insurance coverage exhibit lower price sensitivity compared to self-paying individuals.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for diabetic footwear. Geographic supply concentration for components and finished goods centers on Vietnam, Indonesia, and China. Raw material dependencies include multi-density foams, moisture-wicking linings, and breathable mesh fabrics. A structural supply chain risk is quality control consistency during the shift of manufacturing to lower-cost regions. The dominant distribution model increasingly favors online retailers for direct patient access, complemented by specialized orthopedic clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diabetic footwear market is in a technology-transition phase, with 3D printing replacing traditional casting methods for custom orthotics.
For Market Incumbents:Anticipate continued pressure from consumer brands offering comfort footwear by investing in advanced material science for superior therapeutic outcomes. Strengthen relationships with clinical channels, particularly rehabilitation centers, by offering comprehensive product portfolios and educational support. Prioritize R&D in smart technology integration, such as pressure-sensing insoles, to maintain a competitive edge against emerging digital health solutions. Ensure continuous investment in ISO 13485 certification to navigate evolving international regulatory landscapes.
For New Entrants and Emerging Players:The U.S. Medicare Therapeutic Shoe Bill in the United States opens a window for specialized manufacturers targeting reimbursed orthopedic shoes and custom insoles. Target untapped markets in the Gulf Cooperation Council countries, where high diabetes rates present significant growth potential. Leverage direct-to-consumer online channels with virtual fitting tools to penetrate the market rapidly. Focus on niche product segments like pressure relief shoes, integrating advanced sensor technologies for preventative care.
For Investors and Strategic Acquirers:Widespread adoption of real-time pressure monitoring in smart insoles is the leading indicator that signals a shift towards active preventative care. Long-term viability rests on the sustained global increase in diabetes prevalence and aging demographics requiring specialized foot protection. Identify acquisition targets among technology integrators specializing in digital health platforms for remote patient monitoring. Evaluate firms with strong intellectual property in advanced materials or established direct-to-consumer distribution networks.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Ensures product safety and efficacy, opening access to the lucrative United States market. |
| CE Marking Pathway | Mandates compliance with European health and safety standards for market entry into the EU. |
| Software Companion Development | Enhances product value through data-driven insights for patient monitoring and adherence. |
| Hospital System Partnership | Secures clinical adoption and expands distribution within established healthcare networks. |
| Reimbursement Strategy | Facilitates patient access and drives demand for prescribed therapeutic footwear products. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary research involved interviews with podiatrists, orthopedic surgeons, footwear manufacturers, and rehabilitation center administrators. This approach combined bottom-up market sizing with top-down validation, ensuring comprehensive data triangulation.
Product type, technology, end user, distribution channel, and regional healthcare system maturity were modeled at a granular level. The analytical framework integrated historical data with projected market dynamics across the modeling period to derive Compound Annual Growth Rates. Key industry-specific forecast inputs included diabetes prevalence rates and global aging population statistics.
Caveats apply where unforeseen changes in reimbursement policies or new medical device classifications could materially shift the outlook. Forecasts reflect documented assumptions regarding technological adoption and patient adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Blood Glucose Monitoring Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
Middle East and Africa Insulin Infusion Pumps Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market
Diabetes Care
Global Diabetes Pen Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Global Proliferative Diabetic Retinopathy Market