
 North America Insulin Infusion Pumps Market | 2026-2036
North America Insulin Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Insulin Infusion Pumps Market Analytics
The capital-intensity divergence between players is bifurcating competitive dynamics across the North America Insulin Infusion Pumps Market. Medtronic leverages its vertically integrated manufacturing footprint to sustain hardware-software bundling advantages. Insulet anchors its position through proprietary patch-pump architecture that eliminates tubing. Tandem Diabetes Care differentiates via algorithm-driven closed-loop systems that integrate with third-party continuous glucose monitors.
An insulin infusion pump is a programmable electromechanical device that delivers rapid-acting insulin through a subcutaneous cannula at programmed basal rates and patient-initiated bolus doses, typically with precision of 0.025 to 0.1 units per hour depending on model specification. Its primary commercial purpose is to replicate physiological pancreatic beta-cell insulin secretion patterns for glycemic management in Type 1 and insulin-dependent Type 2 diabetes patients. Patch pumps are capturing disproportionate growth velocity as tubeless form factors reduce skin-site complications and expand pediatric acceptance. Home care end users represent the deepest margin pool because recurring supply reorder rates exceed institutional procurement cycles, while hospital networks concentrate volume through group purchasing organization contracts that compress unit economics.
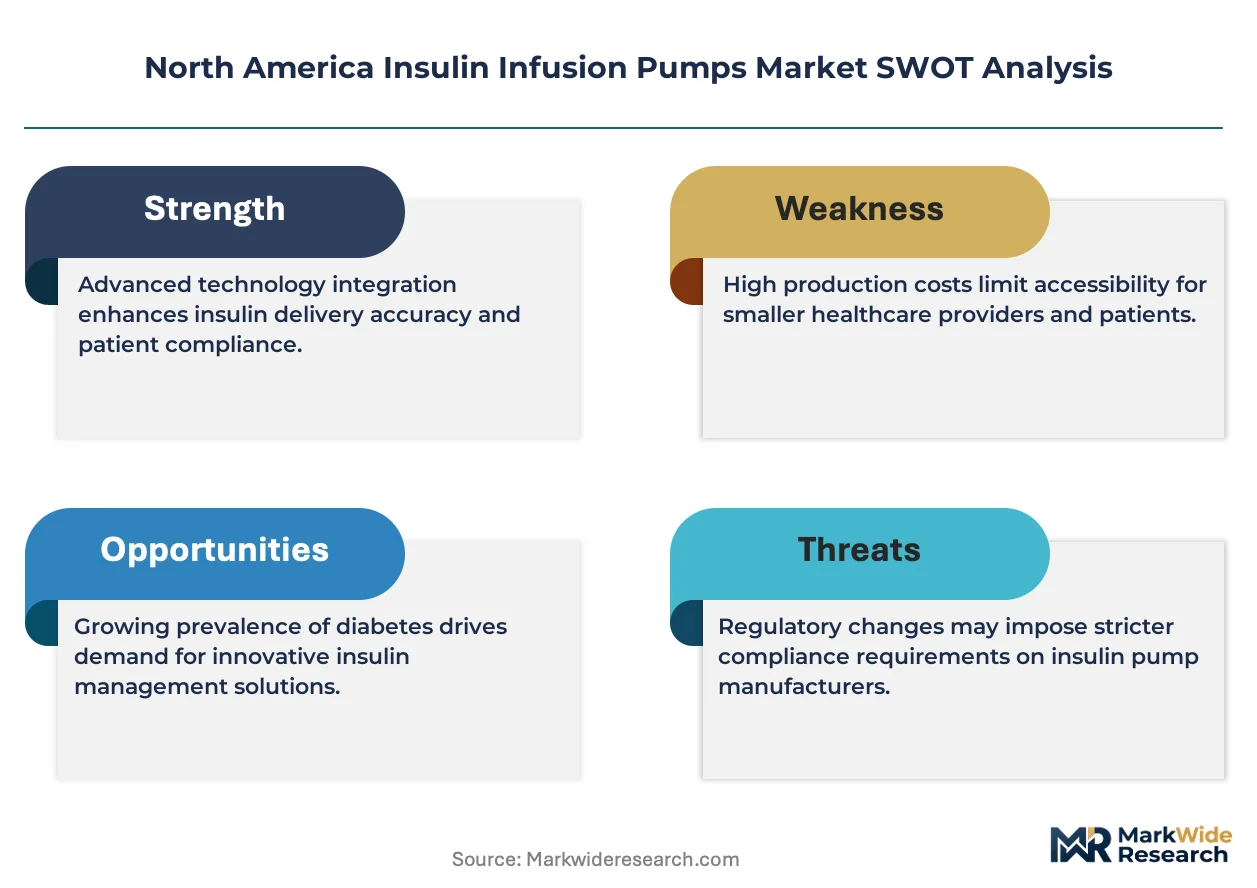
FDA premarket notification and premarket approval pathways govern device commercialization, with the agency's Breakthrough Devices Program accelerating review timelines for closed-loop artificial pancreas configurations. CMS national coverage determinations and state-level Medicaid fee schedules directly shape patient out-of-pocket exposure and manufacturer addressable volume. HIPAA interoperability mandates and ONC certification requirements for connected-device data exchange are tightening software validation burdens. Stakeholders must monitor how FDA software-as-medical-device guidance evolution and prospective CMS remote therapeutic monitoring reimbursement expansion reshape competitive moats around data platform integration.
Market Dynamics
Closed-loop algorithm development is compressing competitive differentiation timelines across the North America Insulin Infusion Pumps Market, forcing hardware manufacturers to deepen software competencies or cede margin to interoperable CGM partners.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated review pathways for artificial pancreas configurations compress commercialization timelines by 12-18 months versus standard PMA routes.
- Pediatric end-use expansion:Tubeless patch-pump form factors eliminate tubing entanglement risks, expanding addressable populations to children under 12 previously excluded from pump therapy.
- CMS remote therapeutic monitoring:Prospective reimbursement expansion for connected-device data transmission creates recurring revenue streams beyond hardware sales.
Market Restraints
- Precision electromechanical component concentration:Sub-miniature motor and sensor supply chains concentrate in East Asian contract manufacturers, exposing lead-time volatility.
- Software validation burden:FDA software-as-medical-device guidance evolution tightens documentation requirements for algorithm updates, extending engineering cycles.
- Substitution by ultra-long-acting analogs:Once-weekly basal insulin formulations under development threaten pump-dependent patient conversion for Type 2 populations.
Strategic Opportunities
- Canada provincial coverage gaps:Uneven insulin pump reimbursement across Ontario, Quebec, and British Columbia provincial formularies creates white-space volume for private-pay models.
- CGM-pump convergence:Integration with Dexcom and Abbott FreeStyle Libre ecosystems enables single-vendor closed-loop control without proprietary sensor development.
- Direct-to-consumer pharmacy channels:CVS and Walgreens specialty pharmacy networks bypass traditional durable medical equipment distributors, capturing margin compression.
Industry Challenges
- Biomedical algorithm talent scarcity:Control systems engineers with glycemic physiology expertise command premium compensation, constraining R&D scaling.
- HIPAA interoperability compliance:ONC certification requirements for connected-device data exchange demand continuous security validation across software update cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Insulin Infusion Pumps Market |
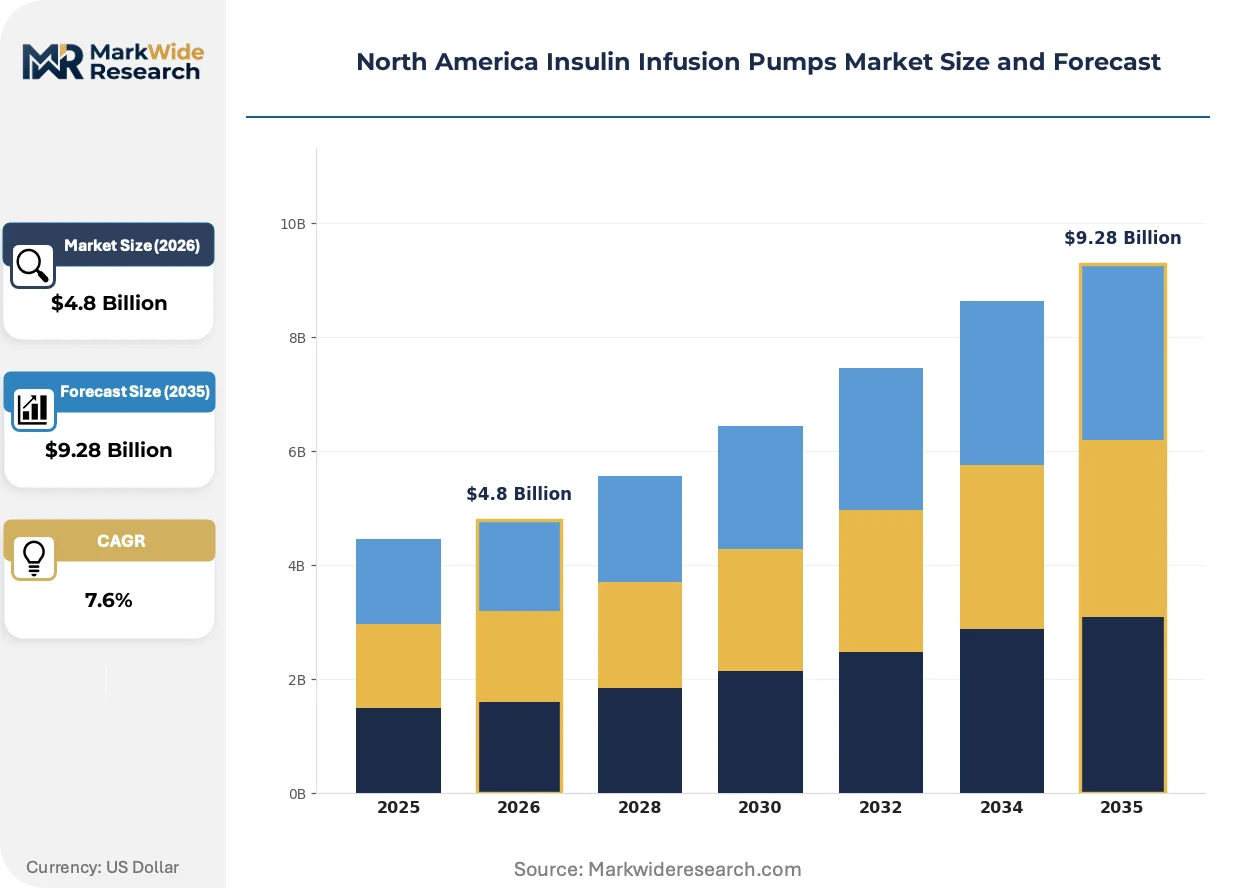
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
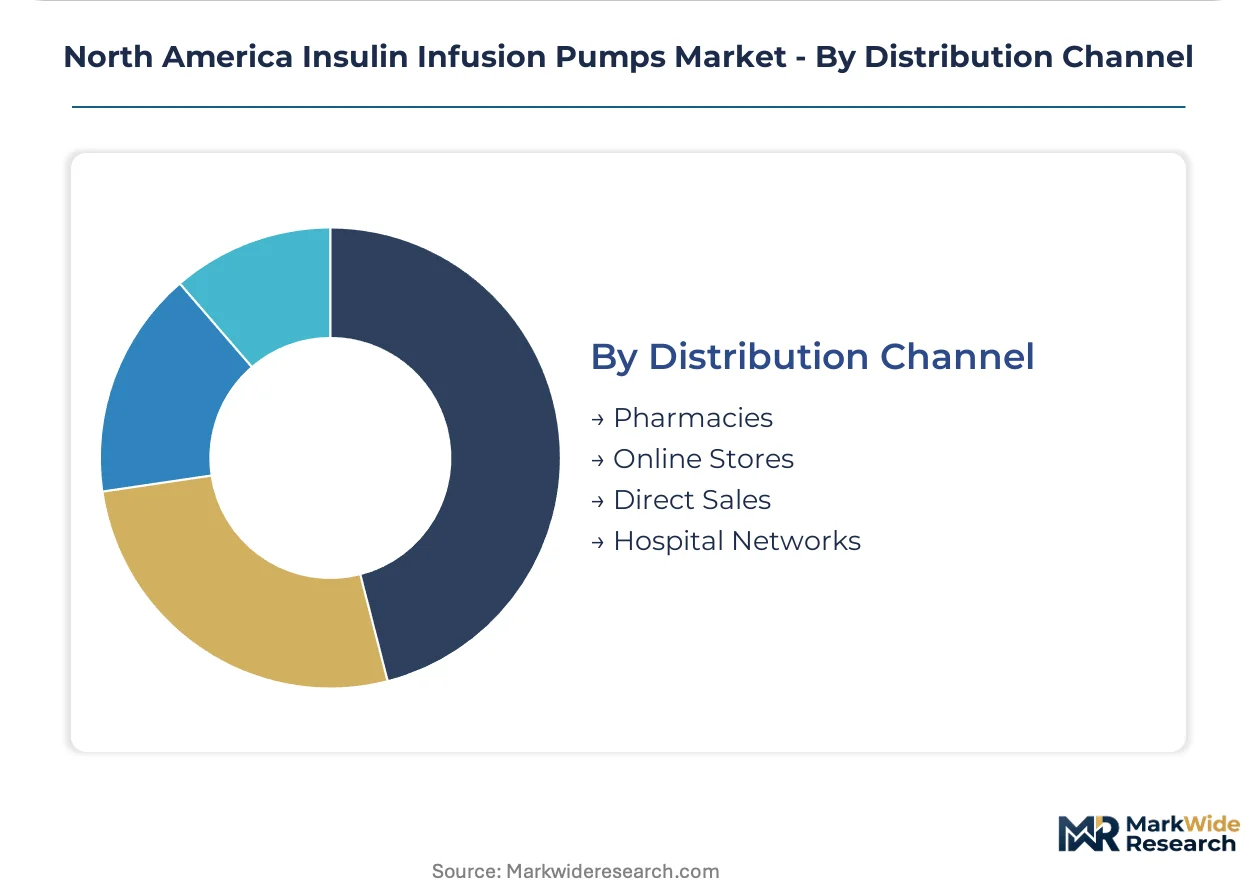
| Segmentation | Product Type: External Pumps, Patch Pumps, Smart Insulin Pens, Wearable Devices End User: Hospitals, Home Care, Diabetes Clinics, Specialty Pharmacies Technology: Continuous Glucose Monitoring, Insulin Delivery Systems, Mobile Apps, Telehealth Integration Distribution Channel: Pharmacies, Online Stores, Direct Sales, Hospital Networks |
| Companies Covered | Medtronic, Insulet, Tandem Diabetes Care, Ypsomed, Roche, Ascensia, Modular Medical, SOOIL Development, AgVa Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Insulin Infusion Pumps Market Evolving Landscape
Algorithmic control systems are displacing manual patient intervention as the primary value driver, shifting competitive advantage from mechanical reliability to predictive glucose forecasting accuracy and seamless third-party sensor integration.
Insulin delivery mechanism design is miniaturizing through MEMS-based micropump architectures that eliminate traditional motor-and-gear assemblies. Pediatric patients and active adult users are adopting these reduced-form-factor devices at twice the rate of conventional pumps. This technology compression is enabling patch-pump wear times to extend from three to seven days, reducing supply reorder friction and deepening patient lock-in.
FDA software-as-medical-device guidance is tightening predicate device pathways for algorithm modifications, requiring new clinical evidence for control-loop parameter adjustments previously cleared as labeling changes. Manufacturers must now submit supplemental PMA applications for machine-learning model updates, extending deployment cycles. Closed-loop systems with adaptive algorithms face the steepest compliance burden, advantaging players with established clinical trial infrastructure.
Patient data ownership preferences are fragmenting traditional device-vendor relationships, with Medicare beneficiaries increasingly demanding portable therapy records across health system migrations. Hospital-owned specialty pharmacies are capturing pump initiation volume from independent DME suppliers, compressing distributor margins. This channel rotation is most visible in United States integrated delivery networks where formulary committees consolidate vendor selection authority.
North America Insulin Infusion Pumps Market Segmentation
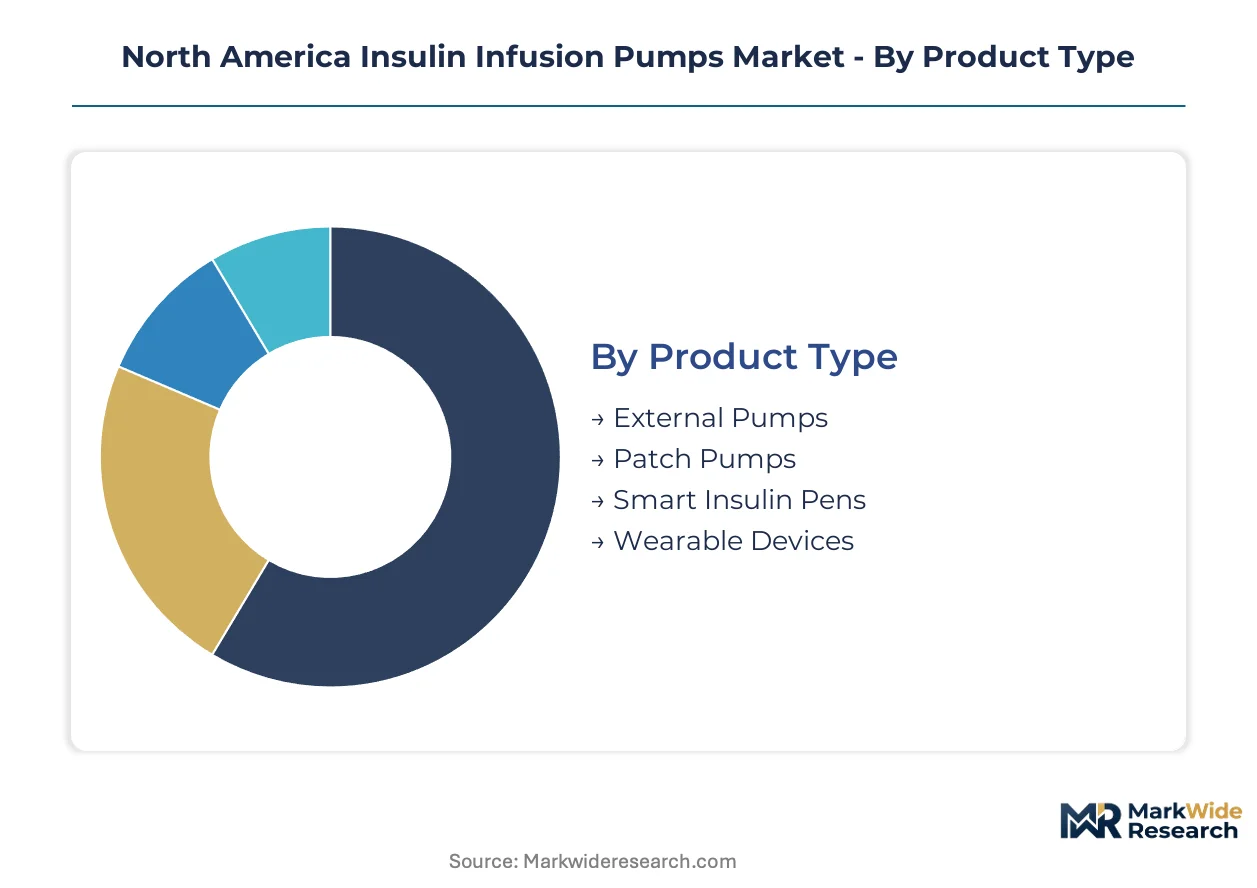
Segmentation in the North America Insulin Infusion Pumps Market reveals divergent margin structures and substitution vulnerabilities across hardware form factors and care delivery settings. Each dimension exposes distinct competitive moats and regulatory exposure profiles that reshape vendor resource allocation.
Product Type:
Substitution pressure from ultra-long-acting basal insulin formulations threatens conventional pump-dependent patient populations most acutely in Type 2 diabetes, compressing addressable volume for traditional hardware categories.
- External Pumps:Traditional tubed electromechanical devices deliver precise basal and bolus insulin through subcutaneous infusion sets with motor-driven syringe mechanisms. United States integrated delivery networks concentrate procurement through group purchasing organization contracts that compress unit economics while locking in multi-year supply agreements.
- Patch Pumps:Tubeless disposable or semi-reusable devices adhere directly to skin, eliminating tubing entanglement risks and expanding pediatric eligibility below age 12. Home care settings in Ontario and Quebec drive disproportionate adoption where provincial coverage gaps force private-pay models with premium pricing tolerance.
- Smart Insulin Pens:Bluetooth-enabled injection devices log dose timing and glucose readings for retrospective pattern analysis without continuous infusion.
- Wearable Devices:Multi-sensor platforms combining insulin delivery with activity tracking and predictive analytics for lifestyle-integrated glycemic management.
External pumps anchor the volume base while patch pumps gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive institutional procurement from recurring revenue-rich home care channels with divergent margin profiles.
- Hospitals:Acute care facilities manage inpatient hyperglycemia and perioperative insulin protocols through institutional-grade infusion systems with EMR integration. United States hospital networks leverage CMS reimbursement frameworks to standardize on vendor-agnostic platforms, ceding margin to group purchasing organization intermediaries.
- Home Care:Self-managing patients drive recurring supply reorder cycles at 2-3x the frequency of institutional procurement, deepening lifetime value and vendor lock-in. CMS remote therapeutic monitoring expansion creates incremental reimbursement streams for connected-device data transmission beyond hardware margins.
- Diabetes Clinics:Outpatient specialty practices provide pump initiation training and ongoing titration support with concentrated endocrinologist influence on device selection.
- Specialty Pharmacies:CVS and Walgreens networks bypass traditional durable medical equipment distributors, capturing margin compression through direct-to-consumer fulfillment.
Home care channels deliver the deepest margin pool while specialty pharmacies expand most quickly through channel consolidation.
Technology:
Application maturity separates FDA-cleared closed-loop algorithms from emerging telehealth integration layers with unproven reimbursement pathways.
- Continuous Glucose Monitoring:Real-time interstitial glucose sensors enable predictive insulin dosing with trend arrow displays and customizable alert thresholds. Dexcom and Abbott FreeStyle Libre ecosystems dominate United States third-party integration, enabling single-vendor closed-loop control without proprietary sensor development.
- Insulin Delivery Systems:MEMS-based micropump architectures and precision motor assemblies execute programmable basal rates with 0.025-unit precision specifications. FDA software-as-medical-device guidance tightens validation burdens for algorithm modifications, advantaging established clinical trial infrastructure.
- Mobile Apps:Smartphone platforms for dose logging, carbohydrate counting, and retrospective pattern visualization with varying FDA classification status.
- Telehealth Integration:Cloud-based data sharing between patients and care teams with prospective CMS reimbursement expansion still pending national coverage determination.
Continuous glucose monitoring anchors interoperability value while telehealth integration climbs the fastest toward reimbursable status.
Distribution Channel:
Customer type concentration in Medicare populations fragments traditional device-vendor relationships around portable therapy record demands.
- Pharmacies:Brick-and-mortar retail and specialty pharmacy counters provide immediate supply access with insurance prior authorization support. British Columbia and Alberta provincial formularies create uneven coverage landscapes that pharmacy benefit managers navigate through tiered co-pay structures.
- Online Stores:Direct-to-consumer platforms and Amazon marketplace listings expand geographic reach with compressed fulfillment timelines for supply reorders. United States Medicare beneficiaries increasingly demand portable therapy records across health system migrations, fragmenting traditional loyalty patterns.
- Direct Sales:Manufacturer field representatives provide in-person pump initiation training and ongoing clinical support with highest touch service intensity.
- Hospital Networks:Integrated delivery network formularies consolidate vendor selection authority through value-based procurement committees.
Pharmacies anchor the volume base while online stores gain share at the steepest rate through convenience-driven reorder migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American jurisdictions. United States patients face substantial out-of-pocket exposure despite CMS coverage, while Canadian provincial formularies create patchwork access that forces private-pay premiums. Mexican patients remain predominantly price-sensitive, driving informal import channels and generic device adoption.
United States
Integrated delivery networks concentrate procurement through group purchasing organization contracts that compress unit economics. FDA premarket approval pathways and Breakthrough Devices Program designations shape commercialization velocity for closed-loop systems. The Minneapolis-St. Paul corridor anchors Medtronic's vertically integrated manufacturing footprint, sustaining hardware-software bundling advantages.
Canada
Ontario and Quebec provincial coverage gaps force private-pay models with premium pricing tolerance, while British Columbia and Alberta offer more generous formulary inclusion. Health Canada medical device licensing requirements parallel FDA standards but with distinct timeline variations. Toronto's hospital network procurement committees increasingly consolidate vendor selection authority through value-based frameworks.
Mexico
Price-sensitive patient populations drive adoption of lower-cost external pump alternatives and informal cross-border supply channels. COFEPRIS medical device registration requirements create compliance barriers that favor established multinational registrants. Mexico City Metro specialty diabetes clinics concentrate pump initiation training capacity, though penetration remains below North American averages.
North America Insulin Infusion Pumps Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America Insulin Infusion Pumps Market. The vendor base concentrates around three dominant positions: vertically integrated multinationals with captive manufacturing, proprietary form-factor specialists, and algorithm-driven interoperability platforms. Strategic moves center on CGM-pump convergence partnerships and direct-to-consumer pharmacy channel bypass of traditional durable medical equipment distributors.
Within the vertically integrated tier, Medtronic anchors hardware-software bundling through its Minneapolis-based manufacturing footprint. Insulet exemplifies the proprietary form-factor archetype with tubeless patch-pump architecture. Tandem Diabetes Care occupies the interoperability platform position, leveraging algorithm-driven closed-loop integration with third-party continuous glucose monitors.
| Leading Market Players |
|---|
| Medtronic |
| Insulet |
| Tandem Diabetes Care |
| Ypsomed |
| Roche |
| Ascensia |
| Modular Medical |
| SOOIL Development |
| AgVa Healthcare |
| Others |
Value Network & Pricing Analysis
MEMS fabrication scale economies in Taiwanese and South Korean foundries concentrate precision component supply, compressing unit costs for motor assemblies while elevating price floors for algorithm-integrated systems that demand FDA-validated software stacks. This concentration bifurcates margin capture between hardware commoditization and closed-loop premium tiers.
Pricing Analysis
After-sales consumable revenue from infusion sets and CGM sensors drives lifetime value multiples that exceed hardware margins by substantial ratios. Three-tier pricing structure across premium closed-loop, standard tubed pumps, and economy patch configurations segments buyers by clinical complexity and insurance coverage depth. Cost compression in standard external pumps intensifies as group purchasing organization contracts consolidate United States hospital procurement, while home care patients with private-pay capacity in Ontario and Quebec absorb premium patch-pump pricing. Medicare beneficiaries demonstrate highest price sensitivity due to coinsurance exposure on durable medical equipment.
Supply Chain Analysis
Shenzhen-to-Long Beach container transit chokepoints expose sub-miniature motor and sensor shipments to lead-time volatility that ripples through manufacturer inventory buffers. Precision electromechanical components draw from contract manufacturers concentrated in China, Taiwan, and Malaysia, with MEMS die fabrication resting on photolithography equipment anchored in Dutch and Japanese supplier networks. Single-source vulnerability concentrates in rare-earth magnet supply for miniature drive motors. Distribution runs through durable medical equipment distributors facing margin compression from CVS and Walgreens specialty pharmacy bypass channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-long-acting once-weekly basal insulin formulations under development threaten pump-dependent patient conversion, forcing incumbents to deepen algorithm differentiation and consumable lock-in to defend substitution.
For Market Incumbents: Shield core revenue streams by accelerating FDA Breakthrough Devices Program submissions for adaptive closed-loop algorithms that widen the efficacy gap against injectable alternatives. Deepen backward integration into MEMS micropump fabrication to reduce East Asian contract manufacturer dependency. Secure exclusive CGM-pump convergence partnerships with Dexcom or Abbott to forestall interoperability commoditization. For New Entrants and Emerging Players: FDA software-as-medical-device pre-submission pathways compress validation timelines for algorithm-first platforms that bypass hardware manufacturing capital intensity. White-space volume concentrates in Canada provincial coverage gaps, particularly Ontario and Quebec private-pay segments where premium pricing tolerance exceeds United States Medicare-constrained markets. Direct-to-consumer pharmacy channel partnerships with Walgreens or CVS specialty networks bypass entrenched DME distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among patch-pump specialists with seven-day wear time extensions that deepen supply reorder frequency and patient lock-in. Five-to-ten year viability favors algorithm-driven interoperability platforms over hardware-commoditized tubed pump manufacturers. Acquisition target archetype: closed-loop software assets with established clinical trial infrastructure and CMS remote therapeutic monitoring reimbursement positioning. Signal to watch: FDA supplemental PMA submission volume for machine-learning model updates as indicator of compliance burden moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Devices Submission | Accelerated review compresses commercialization timelines for artificial pancreas configurations by 12-18 months versus standard PMA routes. |
| CGM-Pump Convergence Partnership | Integration with Dexcom G7 or Abbott FreeStyle Libre eliminates proprietary sensor development burden while enabling single-vendor closed-loop control. |
| Direct-to-Consumer Pharmacy Channel | CVS and Walgreens specialty networks capture margin compression by bypassing traditional durable medical equipment distributor intermediaries. |
| MEMS Micropump Backward Integration | In-house MEMS fabrication reduces East Asian contract manufacturer dependency and extends patch-pump wear times from three to seven days. |
| CMS Remote Therapeutic Monitoring Positioning | Prospective reimbursement expansion for connected-device data transmission creates recurring revenue streams beyond hardware sales cycles. |
Research Methodology
Initial hypotheses were tested against primary input from endocrinologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary interviews with diabetes clinic administrators and insulin pump training specialists cross-referenced against CMS Medicare reimbursement databases, FDA 510(k) and PMA filing records, and provincial formulary listings from Ontario, Quebec, and British Columbia. Bottom-up patient population modeling and top-down manufacturer revenue triangulation converged on segment-level estimates.
Variance decomposition across hardware form factor, end-user channel, and technology integration depth shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, care delivery setting, closed-loop algorithm maturity, and regional reimbursement cluster. CAGRs derived from log-linear trend fitting to historical volume trajectories adjusted for regulatory approval velocity and substitution threat progression. Forecast inputs incorporated FDA software-as-medical-device guidance evolution timelines and CMS national coverage determination pipeline status.
Underlying assumptions cover stable CMS reimbursement frameworks and continued FDA Breakthrough Devices Program availability, with deviation risk concentrated in ultra-long-acting insulin formulation approval timelines and Canadian provincial formulary expansion decisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
North America and Europe Artificial Pancreas Systems Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
United Kingdom Continuous Glucose Monitoring Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market