
 Glycated Albumin Market | 2026-2036
Glycated Albumin Market Size, Share, and Industry Trends Forecast 2026-2036
Glycated Albumin Market Outlook
Hospital procurement channels for glycated albumin diagnostics is narrowing as integrated delivery networks consolidate vendor contracts. Asahi Kasei Pharma Corporation anchors the Japanese market through captive distribution to university hospitals and reference laboratories. Diazyme Laboratories competes in North America by specializing in enzyme-based assay formats for automated chemistry platforms. EKF Diagnostics extends its presence across European diagnostic chains through CE-marked point-of-care systems.
Glycated albumin refers to serum albumin modified by non-enzymatic glycation, typically measured via enzymatic assay or high-performance liquid chromatography with a reference interval of approximately eleven to seventeen percent in diabetic patients; laboratories deploy this biomarker to capture two-to-three week average glucose exposure where HbA1c proves unreliable. Test kits and reagents dominate current revenue as consumable pull-through from installed analyzer bases, while preventive health applications represent the fastest-expanding segment as wellness programs incorporate intermediate-term glucose surveillance. Analyzers retain margin concentration among vendors with closed-system architectures that lock in reagent contracts.
The FDA governs glycated albumin assays as Class II medical devices requiring 510(k) clearance, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE marking that reshape product development timelines. Japan's PMDA maintains distinct approval pathways for glycated albumin reagents used in reimbursed diabetes management protocols. Stakeholders must monitor evolving payer decisions on glycated albumin reimbursement parity with HbA1c across major health systems.
Market Dynamics
Integrated delivery networks in the United States are consolidating glycated albumin procurement contracts, compressing vendor margins and forcing reagent suppliers toward closed-system architectures that lock in recurring consumable revenue.
Growth Catalysts
- 510(k) Pathway Recognition:FDA classification of glycated albumin assays as Class II medical devices with established predicate clearance routes accelerates product entry for enzymatic and chromatographic formats.
- Hospital Laboratory Consolidation:University medical centers in Japan and Germany are standardizing intermediate-term glucose monitoring protocols that incorporate glycated albumin alongside HbA1c for perioperative diabetes management.
- Enzymatic Assay Automation:Chemistry platform integration enables high-throughput processing without dedicated HPLC infrastructure, expanding test accessibility to mid-tier diagnostic laboratories.
Market Restraints
- Reimbursement Parity Gaps:United States Medicare and commercial payers maintain variable coverage policies for glycated albumin relative to HbA1c, creating revenue uncertainty for hospital outreach laboratories.
- Reference Interval Standardization:Lack of harmonized calibrator materials across enzymatic and HPLC methods produces inter-laboratory variability that complicates multi-site clinical trial enrollment.
- Albumin Turnover Confounding:Conditions including nephrotic syndrome and cirrhosis alter serum albumin half-life, limiting glycated albumin reliability in chronic kidney disease populations where glucose monitoring is most critical.
Strategic Opportunities
- Point-of-Care Expansion:CE-marked handheld analyzers from European manufacturers enable capillary testing in ambulatory settings outside traditional laboratory workflows.
- Preventive Health Integration:Corporate wellness programs in the United States are incorporating intermediate-term glucose surveillance into metabolic screening panels for prediabetic employee populations.
- IVDR Clinical Evidence Requirements:EMA's strengthened post-market surveillance mandates create first-mover advantage for vendors with preemptive real-world evidence generation capabilities.
Industry Challenges
- Multi-platform Validation Burden:Reagent manufacturers must maintain separate analytical performance dossiers for each automated chemistry analyzer model, fragmenting regulatory submission resources.
- Legacy System Interoperability:Hospital information systems in Germany and Japan require customized middleware development to integrate glycated albumin results into existing diabetes dashboard displays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycated Albumin Market |
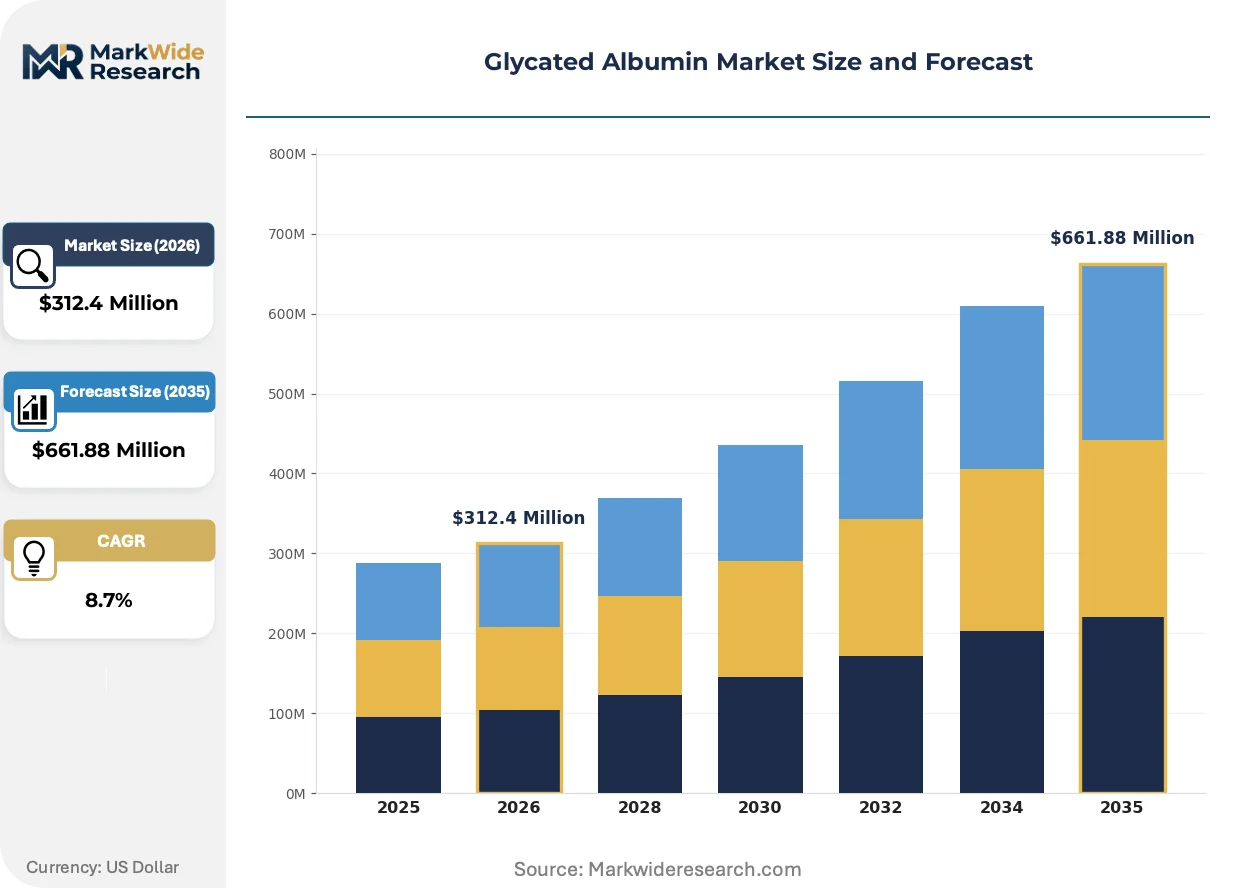
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Analyzers, Reagents, Controls Application: Diabetes Monitoring, Clinical Research, Laboratory Testing, Preventive Health End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Distribution Channel: Online Retail, Direct Sales, Third-Party Distributors, Healthcare Providers |
| Companies Covered | Abbexa Ltd., Abnova Corporation, Asahi Kasei Pharma Corporation, Maccura Biotechnology, LifeSpan BioSciences, Diazyme Laboratories, EKF Diagnostics, Tosoh Bioscience, Weldon Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycated Albumin Market Strategic Shifts
Digital connectivity and assay miniaturization are reconfiguring how glycated albumin testing reaches patients, shifting value capture from centralized laboratories toward distributed diagnostic nodes.
Enzymatic glycated albumin quantification is virtualizing the traditional HPLC workflow by enabling measurement on standard clinical chemistry analyzers without dedicated chromatography infrastructure. Reference laboratories in the United States are adopting this format to consolidate diabetes biomarker testing onto single platforms. This virtualization compresses capital requirements for test deployment and accelerates turnaround time from batch processing to random-access availability.
EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for CE marking that extend product development timelines by twelve to eighteen months for novel assay formats. Manufacturers must now submit real-world performance data from European reference sites prior to market authorization. Small and mid-size reagent vendors are responding by partnering with academic medical centers in Germany and France for prospective validation studies.
Integrated health systems in the United States are unbundling glycated albumin testing from bundled diabetes management payments, creating direct-to-employer contracting channels for diagnostic laboratory networks. This procurement model change displaces traditional hospital-based reference laboratory relationships with national commercial laboratories. The shift is most visible in self-insured employer populations seeking intermediate-term glucose surveillance for workforce metabolic health programs.
Glycated Albumin Market Segmentation
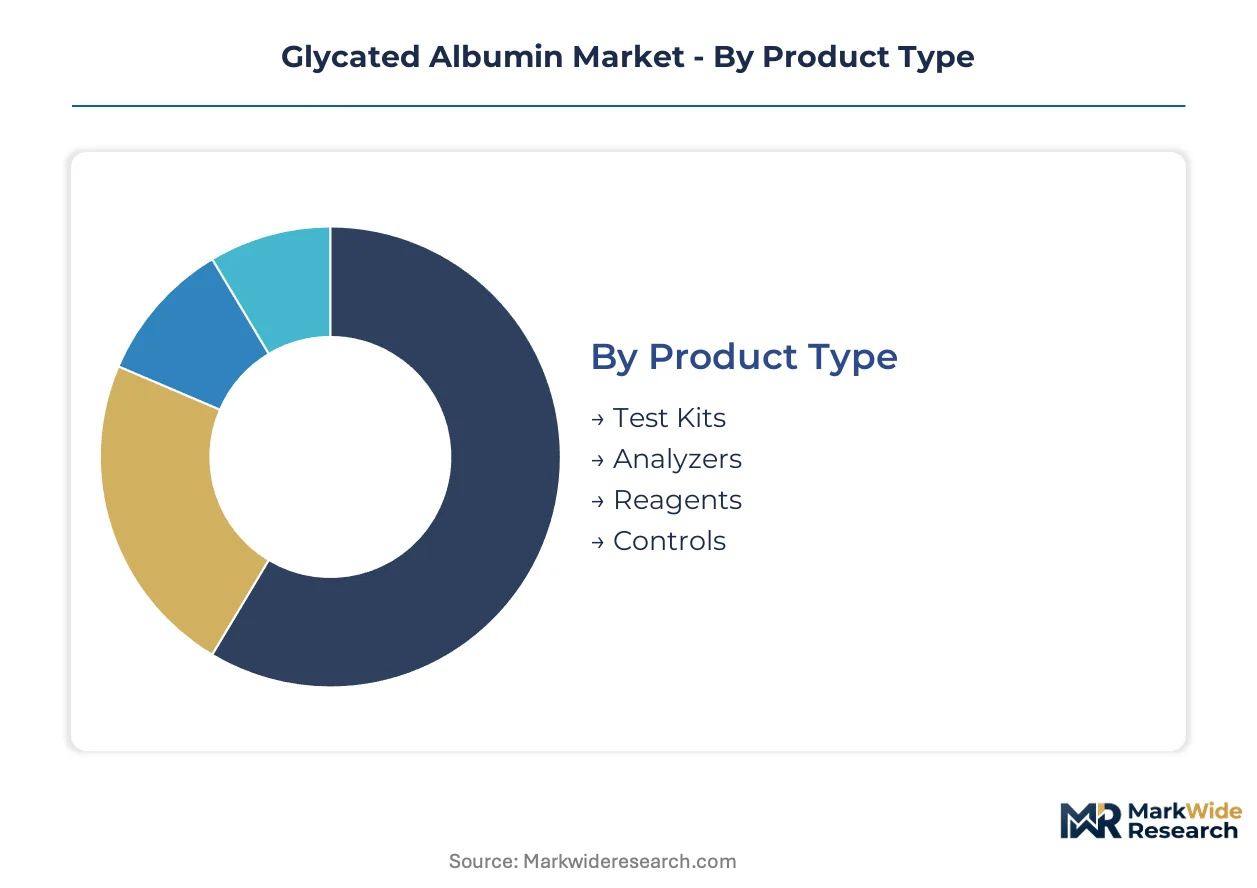
Glycated albumin testing fragments across four distinct segmentation dimensions. Product architecture determines margin capture between consumable pull-through and capital equipment. Application scope separates acute clinical utility from emerging wellness surveillance. End-user concentration and channel economics further reshape competitive positioning across geographies.
Product Type:
Cost tier stratification separates consumable-dependent revenue from capital-intensive analyzer placement.
- Test Kits:Single-use enzymatic assay cartridges enable random-access processing on automated chemistry platforms. Hospital laboratories in Japan standardize these formats for perioperative glucose surveillance protocols.
- Reagents:Liquid-stable enzymatic formulations drive recurring revenue through closed-system contracts. Integrated delivery networks in the United States consolidate procurement around multi-year reagent supply agreements that lock in test volumes.
- Analyzers:Dedicated HPLC and chemistry-integrated systems carry higher upfront capital requirements. Mid-tier diagnostic laboratories in Germany favor platform consolidation over dedicated analyzer acquisition.
- Controls:Calibrator materials and quality assurance panels address inter-laboratory harmonization gaps. Reference laboratories require these for method standardization across multi-site networks.
Reagents hold installed capacity. Test kits are rotating up the share rankings.
Application:
Clinical utility depth varies from reimbursed diabetes management to discretionary wellness screening.
- Diabetes Monitoring:Intermediate-term glucose surveillance captures two-to-three week glycemic exposure where HbA1c proves unreliable. Hospital laboratories deploy this biomarker for perioperative patients with hemoglobin variants.
- Preventive Health:Corporate wellness programs incorporate intermediate-term glucose surveillance into metabolic screening panels. Self-insured employers in the United States contract directly with diagnostic laboratory networks for workforce surveillance.
- Laboratory Testing:Reference and hospital laboratories process glycated albumin as part of expanded diabetes biomarker panels. Enzymatic assay automation enables high-throughput consolidation onto existing chemistry infrastructure.
- Clinical Research:Pharmaceutical trials employ glycated albumin for shorter-term glycemic endpoint measurement. Academic medical centers in Germany and France generate real-world evidence for IVDR compliance.
Diabetes monitoring anchors current revenue. Preventive health applications are climbing the fastest.
End User:
Customer type concentration shifts from hospital-based reference laboratories toward distributed diagnostic nodes.
- Diagnostic Laboratories:National commercial laboratories and hospital outreach operations process the majority of glycated albumin test volumes. Integrated health systems in the United States unbundle testing from bundled diabetes payments.
- Hospitals:University medical centers standardize glycated albumin alongside HbA1c for inpatient glucose management. Japanese university hospitals anchor captive distribution relationships with domestic suppliers.
- Research Institutions:Academic medical centers conduct analytical validation studies for regulatory submission. European sites generate prospective performance data for EMA IVDR compliance.
- Home Care:Point-of-care capillary testing extends reach beyond traditional laboratory workflows. CE-marked handheld analyzers enable ambulatory deployment in European markets.
Diagnostic laboratories command current capacity. Home care is gaining share fastest.
Distribution Channel:
Supply concentration patterns reflect procurement consolidation and regulatory pathway requirements.
- Direct Sales:Manufacturers maintain captive relationships with large integrated delivery networks and reference laboratory chains. Long-term reagent contracts lock in recurring revenue streams.
- Third-Party Distributors:Regional medical supply networks reach mid-tier hospital laboratories and independent diagnostic facilities. These intermediaries carry inventory risk for specialized reagent formats.
- Healthcare Providers:Group purchasing organizations aggregate demand across hospital systems for negotiated pricing. Procurement consolidation compresses vendor margins toward volume-based arrangements.
- Online Retail:E-commerce channels serve smaller research institutions and point-of-care device procurement. Limited regulatory complexity enables direct-to-customer fulfillment for CE-marked products.
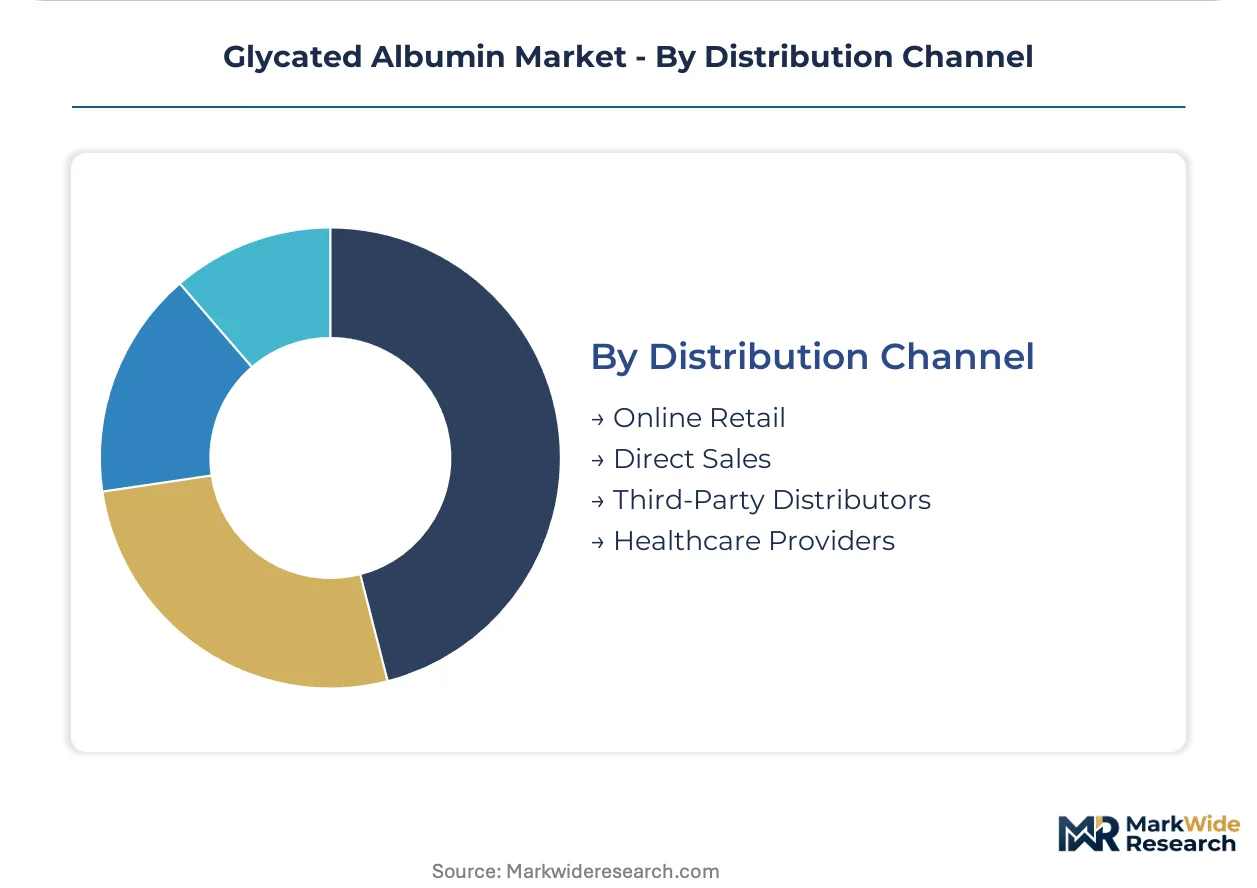
Direct sales hold installed capacity. Healthcare provider contracting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese university hospitals while German diagnostic chains compress vendor margins through consolidated procurement. The United States generates volume leadership through integrated delivery network standardization. European reference laboratories navigate IVDR compliance timelines that extend product entry by twelve to eighteen months.
United States
Integrated health systems unbundle glycated albumin testing from bundled diabetes payments, creating direct-to-employer contracting channels for workforce metabolic surveillance. FDA 510(k) clearance pathways accelerate enzymatic assay entry for automated chemistry platforms. National commercial laboratories in the Midwest and Southeast consolidate procurement around multi-year reagent supply agreements.
Japan
University medical centers standardize perioperative glucose surveillance protocols that incorporate glycated albumin alongside HbA1c for hemoglobin variant patients. PMDA maintains distinct approval pathways for reimbursed diabetes management reagents. Tokyo and Osaka anchor captive distribution relationships where domestic suppliers lock in recurring consumable revenue through closed-system contracts.
Germany
Reference laboratory networks adopt enzymatic formats to consolidate diabetes biomarker testing onto single platforms without dedicated HPLC infrastructure. EMA IVDR mandates real-world performance data from European reference sites prior to market authorization. Bavaria and Baden-Württemberg generate prospective validation studies for regulatory submission compliance.
China
Domestic biotechnology firms expand enzymatic assay production for hospital laboratory networks serving tier-one and tier-two cities. NMPA oversight governs in vitro diagnostic registration through distinct pathways for imported versus domestic reagents. Shanghai and Beijing clusters drive analytical performance dossiers for automated chemistry analyzer integration.
United Kingdom
National Health Service trusts evaluate glycated albumin for intermediate-term glucose surveillance in prediabetic population screening programs. MHRA post-Brexit regulatory frameworks align with IVDR evidence standards while maintaining separate UKCA marking requirements. London and Southeast England concentrate clinical research activity for pharmaceutical trial endpoint measurement.
Glycated Albumin Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in reagent and calibrator supply. The vendor base separates between closed-system architects capturing recurring consumable revenue and open-platform reagent suppliers competing on analytical performance. Three archetypes dominate: integrated diagnostic conglomerates with captive distribution, mid-size enzymatic assay specialists, and point-of-care device manufacturers. Consolidation pressures favor multi-year reagent contracts and strategic partnerships with academic medical centers for real-world evidence generation.
Among Japanese pharmaceutical conglomerates, Asahi Kasei Pharma Corporation anchors the domestic market through university hospital relationships. Diazyme Laboratories and EKF Diagnostics occupy positions in the enzymatic assay and point-of-care tiers respectively, representing North American and European competitive vectors. These three exemplify how geographic origin shapes regulatory pathway strategy and customer access models.
| Leading Market Players |
|---|
| Abbexa Ltd. |
| Abnova Corporation |
| Asahi Kasei Pharma Corporation |
| Maccura Biotechnology |
| LifeSpan BioSciences |
| Diazyme Laboratories |
| EKF Diagnostics |
| Tosoh Bioscience |
| Weldon Biotech |
| Others |
Value Chain & Pricing Dynamics
Tokyo and Osaka anchor captive reagent manufacturing relationships that lock university hospitals into closed-system contracts with premium pricing power. Japanese domestic suppliers extract margin through multi-year consumable agreements, while mid-tier diagnostic laboratories in Germany and the United States face procurement consolidation that compresses vendor margins toward volume-based arrangements.
Pricing Analysis
Configured-to-order pricing for customized enzymatic assay formats commands substantial premiums over standard liquid-stable reagent formulations. The dominant structure runs through multi-year reagent supply agreements that lock in test volumes, with price differentiation driven by FDA 510(k) certification tier and chemistry platform integration complexity. Cost compression in the open-platform reagent tier is intensifying because integrated delivery networks consolidate vendor contracts. Hospital outreach laboratories exhibit highest price sensitivity, while Japanese university medical centers demonstrate lowest sensitivity due to captive distribution relationships.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for enzymatic assay component sourcing. Manufacturing concentrates in Japan, Germany, and the United States for finished reagent formulations, drawing from bovine serum albumin, chromatography-grade solvents, and enzyme catalyst precursors. Single-source vulnerability persists for specialized calibrator materials used in inter-laboratory harmonization. Distribution runs through direct sales channels for large integrated delivery networks, with third-party distributors handling mid-tier hospital laboratory reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glycated albumin market is recovering from reimbursement parity uncertainty as FDA recognition of the biomarker's complementary role to HbA1c stabilizes payer coverage decisions. Hospital laboratory consolidation and enzymatic assay automation are the cyclical drivers restoring vendor pricing power.
For Market Incumbents: Entrench closed-system architectures that lock in recurring consumable revenue through multi-year reagent contracts with integrated delivery networks. Invest in preemptive real-world evidence generation capabilities at academic medical centers in Germany and France to satisfy EMA IVDR post-market surveillance mandates before competitors. The threat of open-platform reagent suppliers competing on analytical performance requires defensive certification investment in automated chemistry analyzer integrations. For New Entrants and Emerging Players: Pursue point-of-care expansion in European ambulatory settings where CE-marked handheld analyzers bypass traditional laboratory procurement consolidation. Corporate wellness programs in the United States represent the most penetrable segment, with self-insured employers seeking direct-to-laboratory contracting for workforce metabolic surveillance. A go-to-market angle emphasizing capillary testing convenience for prediabetic population screening bypasses entrenched hospital reference laboratory relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic assay virtualization specialists consolidating diabetes biomarker testing onto single chemistry platforms. Long-term viability over the next decade hinges on reimbursement parity achievement with HbA1c across Medicare and commercial payer networks. Acquisition targets should demonstrate preemptive IVDR compliance dossiers and European reference site relationships. The signal to watch is payer policy harmonization for glycated albumin coverage in chronic kidney disease populations where albumin turnover confounding currently limits clinical utility.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Reagent Contracting | Multi-year agreements with integrated delivery networks lock in recurring consumable revenue streams. |
| IVDR Real-World Evidence Generation | Preemptive validation studies at German academic medical centers accelerate European market authorization timelines. |
| Enzymatic Assay Platform Integration | Chemistry analyzer consolidation eliminates dedicated HPLC infrastructure requirements for mid-tier laboratories. |
| Direct-to-Employer Contracting | Self-insured wellness programs bypass traditional hospital-based reference laboratory procurement channels. |
| Point-of-Care Capillary Testing | CE-marked handheld analyzers extend reach beyond centralized laboratory workflows into ambulatory settings. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EMA IVDR submission records, hospital procurement contracts, and GPO pricing agreements. The research team conducted structured interviews with clinical laboratory directors, diagnostic reagent procurement managers, biomedical engineers, and payer policy specialists. Secondary validation drew from CMS Medicare reimbursement data, PMDA approved device listings, and chemistry analyzer manufacturer technical specifications. Bottom-up test volume modeling triangulated against top-down market sizing from installed analyzer base estimates.
Forecast inputs include enzymatic versus HPLC method adoption curves, integrated delivery network consolidation rates, and reimbursement policy harmonization trajectories across the projection horizon. Segmentation dimensions modeled encompass product architecture, application scope from clinical to wellness surveillance, end-user concentration patterns, and distribution channel economics. CAGRs were derived from test volume expansion rates and per-test pricing trends. Industry-specific inputs include reference interval standardization progress and albumin turnover confounding prevalence in target patient populations.
Sensitivities concentrate around payer coverage decisions for glycated albumin relative to HbA1c and harmonization timeline for calibrator materials across assay methods. Forecasts reflect assumptions regarding FDA 510(k) predicate clearance continuity and EMA IVDR evidence requirement stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Philippines Oral Anti-Diabetic Drug Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
BRICS Diabetes Drugs Market
Diabetes Care
Type 2 Diabetes Drugs and Devices Market
Diabetes Care
North America Insulin Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
North America Oral Anti-Diabetic Drug Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Gestational Diabetes Market