
 Global Female Sexual Dysfunction Treatment Market | 2026-2036
Global Female Sexual Dysfunction Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Female Sexual Dysfunction Treatment Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating which manufacturers can serve European patients versus those locked out of the region. Pfizer Inc. leverages its established cardiovascular research infrastructure to cross-apply vascular mechanisms into arousal disorder therapies. Sprout Pharmaceuticals Inc. specializes in neurotransmitter-targeting oral medications following its prior regulatory engagements with the FDA. PALATIN anchors its position through peptide-based drug development platforms focused on melanocortin receptor pathways.
Female sexual dysfunction treatment encompasses pharmacological and device-based interventions targeting physiological and psychological barriers to sexual response, including vasodilatory agents, hormone modulation protocols, and neuromodulator compounds administered through oral, topical, or injectable routes. Oral medications command the largest revenue share within product type segmentation due to patient preference for non-invasive administration and established pharmacy distribution. Hormone therapy represents the fastest-expanding therapy area as postmenopausal dysfunction diagnoses rise in aging populations across developed healthcare systems. Online pharmacies are capturing margin pools within distribution channels by circumventing traditional stigma barriers through discreet fulfillment models.
The FDA maintains stringent efficacy endpoints for hypoactive sexual desire disorder drug approvals, while the EMA applies divergent benefit-risk frameworks that delay unified launch timelines across North American and European markets. BIS certification requirements in India create additional market access layers for imported hormone therapies and mechanical devices. Stakeholders must monitor how regulatory divergence between the FDA and EMA on subjective endpoint validation shapes portfolio prioritization and geographic sequencing decisions.
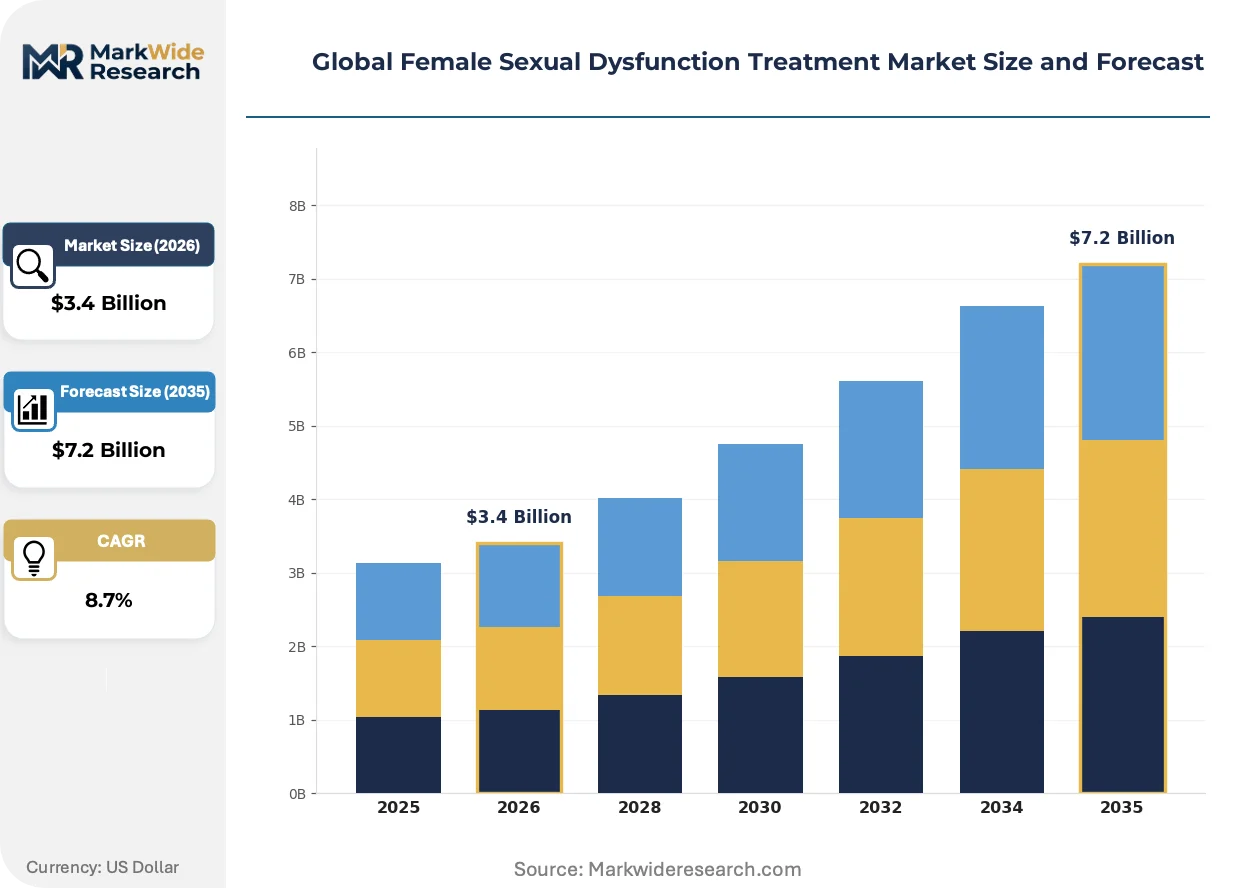
Market Dynamics
FDA endpoint requirements for hypoactive sexual desire disorder trials are compressing development timelines while EMA divergence forces parallel track investments, reshaping how sponsors allocate clinical resources across Atlantic markets.
Growth Catalysts
- Postmenopausal Hormone Protocols:Aging demographics in Japan, Germany, and the United States are expanding the addressable patient base for estrogen-modulating therapies. Gynecology clinics in these markets are adding dedicated sexual health service lines.
- Online Pharmacy Distribution:Discreet fulfillment models are circumventing traditional stigma barriers and capturing patients who previously avoided brick-and-mortar pharmacy pickup. This channel expansion is particularly pronounced in markets with mature e-commerce infrastructure.
- CE Marking Pathway Clarity:EU Medical Device Regulation implementation is creating predictable market access timelines for device manufacturers, enabling portfolio planning certainty that MDR transition uncertainty previously obstructed.
Market Restraints
- Subjective Endpoint Validation:FDA insistence on patient-reported outcome measures creates measurement variability that complicates Phase III trial design and increases regulatory risk for novel mechanisms.
- Specialist Infrastructure Concentration:Certified sexual medicine practitioners cluster in urban United States corridors and select Western European capitals, leaving vast geographic segments with diagnosis access gaps.
- Reimbursement Pathway Fragmentation:Payer coverage for female sexual dysfunction therapies remains inconsistent across United States commercial plans and virtually absent in several European statutory systems, constraining volume realization.
Strategic Opportunities
- Brazil and Mexico Market Development:ANVISA regulatory frameworks are maturing for sexual health therapeutics, creating first-mover advantages for sponsors establishing local clinical and commercial infrastructure ahead of competitor entry.
- Neuromodulator-Device Convergence:Combination protocols pairing transdermal delivery systems with wearable biofeedback hardware represent untapped white space between pharmacology and physical medicine.
- India PLI Scheme Alignment:Domestic manufacturing incentives for active pharmaceutical ingredients could reduce cost structures for hormone synthesis operations serving Asian and Middle Eastern markets.
Industry Challenges
- Sexual Medicine Fellowship Pipeline:Accredited training program scarcity limits the specialist workforce required to diagnose and manage complex dysfunction cases, creating a bottleneck that marketing investment alone cannot resolve.
- Legacy EHR Integration:Diagnostic coding for female sexual dysfunction remains inconsistent across hospital system electronic health records, complicating patient identification and outcomes tracking for real-world evidence generation.
- Patent Cliff Navigation:Expiring exclusivity on established arousal disorder compounds is accelerating generic entry, compressing branded pricing power and forcing pipeline replenishment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Female Sexual Dysfunction Treatment Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Medications, Topical Creams, Hormone Therapy, Vacuum Devices, Injectable Agents Therapy Area: Hypoactive Sexual Desire Disorder, Arousal Disorder, Orgasmic Disorder, Pain Disorders, Postmenopausal Dysfunction End User: Gynecology Clinics, Sexual Wellness Centers, Diagnostic Laboratories, Home Care Settings Distribution Channel: Pharmacy Chains, Online Pharmacies, Hospitals, Specialty Clinics |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Duchesnay Pharmaceutical Group Inc., Mayne Pharma Group Limited, Sprout Pharmaceuticals Inc., Cipla Limited, Merck & Co. Inc., Novo Nordisk AS, PALATIN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Female Sexual Dysfunction Treatment Market Shifts & Advancements
Peptide-based drug delivery systems and digital therapeutic adjuncts are converging to reshape treatment protocols, while regulatory divergence between major agencies forces adaptive clinical strategies.
Intravaginal laser and radiofrequency devices are miniaturizing from clinic-based systems to handheld consumer formats. Aesthetic medicine practices in South Korea and Spain are adopting these portable units for in-office protocols. This form factor shift is miniaturizing capital requirements for market entry and enabling direct-to-consumer channels that bypass traditional gynecology gatekeepers.
EMA benefit-risk frameworks for sexual dysfunction therapeutics are diverging from FDA subjective endpoint standards, forcing sponsors to maintain dual trial designs. European regulators emphasize quality-of-life composite measures over desire-frequency counts. Multinational sponsors are responding by sequencing United States filings first, delaying European launches by 18-36 months.
Subscription-based telehealth models are displacing traditional in-person consultation as the initial patient touchpoint. Direct-to-consumer platforms in the United Kingdom and Australia are capturing diagnosis and prescription initiation before specialist referral. This channel rotation is most visible among perimenopausal cohorts seeking discretion and appointment flexibility.
Global Female Sexual Dysfunction Treatment Market Segmentation
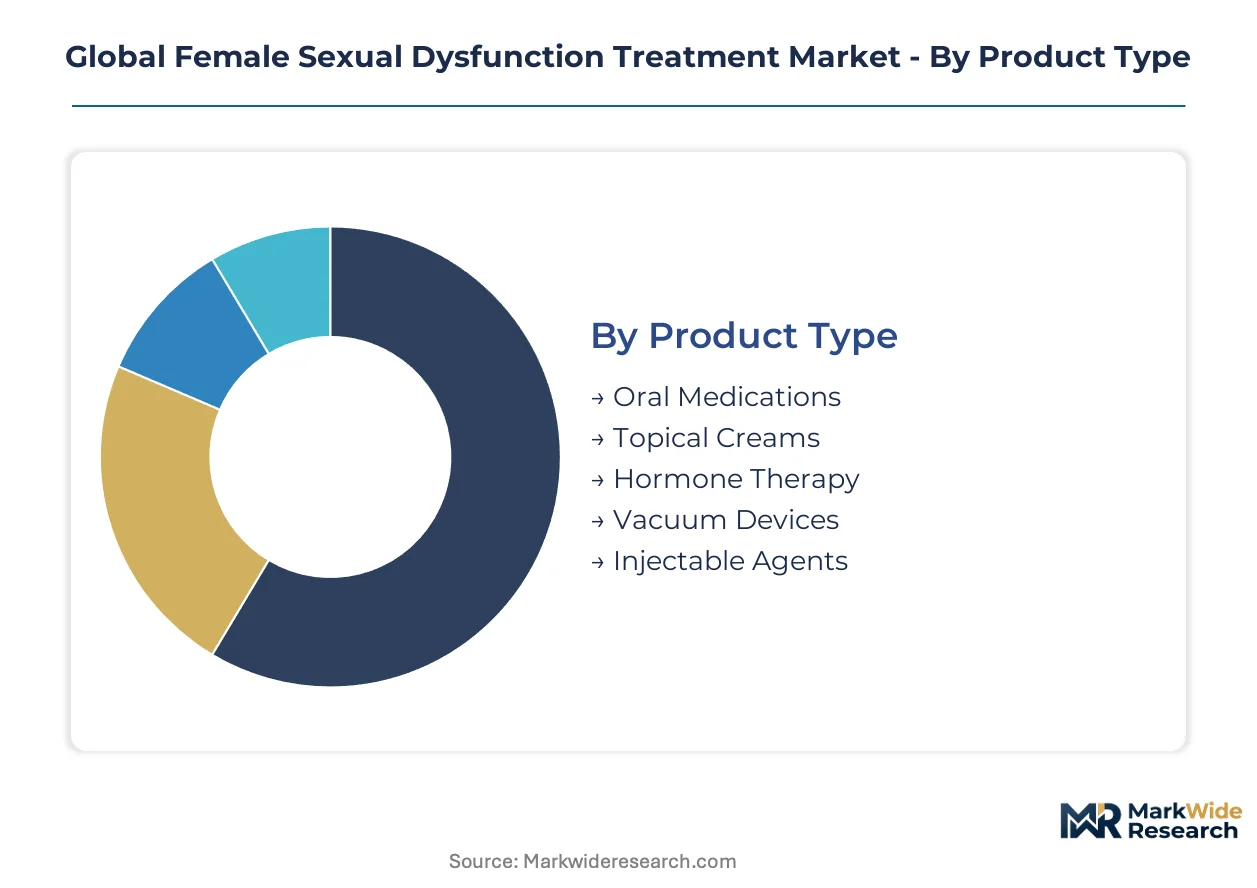
Segmentation in female sexual dysfunction treatment reveals how channel preferences and clinical settings reshape product development priorities. Manufacturers must align formulation decisions with whether patients seek discretion through direct-to-consumer channels or clinical validation through specialist encounters.
Product Type:
Channel mix varies sharply by administration route, with oral formulations flowing through pharmacy chains and online platforms while devices and injectables concentrate in specialty clinic procurement.
- Oral Medications:Small-molecule tablets and capsules targeting neurotransmitter pathways dominate pharmacy dispensing volumes. United States demand concentrates through CVS and Walgreens retail networks, driven by patient preference for at-home administration without clinical appointments.
- Hormone Therapy:Estrogen-modulating protocols including patches, gels, and oral combinations require laboratory monitoring that channels demand through gynecology clinics with in-house phlebotomy. Germany's statutory reimbursement for menopausal hormone management accelerates adoption among aging patient cohorts.
- Topical Creams:Vasodilatory and anesthetic formulations for localized application.
- Vacuum Devices:Mechanical arousal enhancement systems with clinic-based fitting protocols.
- Injectable Agents:Peptide-based and vasoactive compounds administered in clinical settings.
Oral medications dominate installed base. Hormone therapy is where expansion concentrates.
Therapy Area:
Cost tier stratification separates premium-priced novel mechanisms for desire disorders from standardized pain management protocols with generic competition.
- Hypoactive Sexual Desire Disorder:Neurotransmitter-targeting interventions command premium pricing due to FDA-mandated efficacy trials and limited approved alternatives. United States specialist infrastructure in Boston and San Francisco corridors supports diagnosis and prescription initiation.
- Postmenopausal Dysfunction:Hormone-based and non-hormonal protocols address estrogen decline symptoms with established safety profiles. Japan's aging demographic and national health insurance coverage for menopausal care expands addressable volumes.
- Arousal Disorder:Vascular and neuromodulatory interventions for physiological response deficits.
- Orgasmic Disorder:Psychological and pharmacological combination approaches with variable reimbursement.
- Pain Disorders:Topical anesthetics and physical therapy protocols facing pricing pressure from generic alternatives.
Hypoactive sexual desire disorder commands premium positioning. Postmenopausal dysfunction is expanding most quickly.
End User:
Patient volume concentrates in settings offering integrated diagnosis and treatment, with standalone laboratories losing share to full-service clinical environments.
- Gynecology Clinics:Full-service women's health facilities combining diagnostic workup, prescription initiation, and follow-up monitoring. United Kingdom NHS sexual health service expansions in Manchester and Birmingham increase referral volumes.
- Sexual Wellness Centers:Specialized facilities in Madrid, Barcelona, and Milan aesthetic medicine clusters adopt laser and radiofrequency devices for in-office protocols.
- Diagnostic Laboratories:Hormone testing and physiological assessment services without treatment capabilities.
- Home Care Settings:Self-administered topical and oral protocols with telehealth oversight.
Gynecology clinics dominate installed base. Sexual wellness centers are where expansion concentrates.
Distribution Channel:
Geographic maturity of e-commerce infrastructure determines online pharmacy penetration, with brick-and-mortar retention in markets with pharmacy-based primary care traditions.
- Online Pharmacies:Discreet fulfillment platforms capture stigma-sensitive patient segments through subscription models. Australia's mature telehealth regulatory framework supports direct-to-consumer prescription pathways bypassing traditional gatekeepers.
- Pharmacy Chains:Multi-location retail networks with established formulary negotiations and insurance billing capabilities.
- Hospitals:Integrated health system pharmacies serving inpatient and outpatient sexual medicine departments.
- Specialty Clinics:Limited-distribution channels for high-touch device fittings and injectable administration.
Pharmacy chains dominate installed base. Online pharmacies are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers concentrate around insured perimenopausal cohorts seeking discreet access through telehealth platforms. Germany and Japan anchor European and Asian demand through aging demographics and statutory reimbursement frameworks. Brazil and India represent emerging volume frontiers where regulatory maturation is unlocking private-pay segments.
United States
Insured perimenopausal women in urban corridors drive prescription volumes for oral desire-disorder therapies. FDA guidance on subjective endpoint validation shapes clinical trial investments by sponsors targeting Boston and San Francisco specialist clusters. CVS and Walgreens pharmacy networks dominate fulfillment, though Ro and Hims telehealth platforms are capturing initiation visits.
Germany
Statutory health insurance coverage for menopausal hormone management accelerates adoption among aging cohorts in Bavaria and North Rhine-Westphalia. EMA benefit-risk frameworks emphasize quality-of-life composites that diverge from FDA standards, delaying unified launch timelines. Berlin and Munich gynecology clinics are expanding dedicated sexual health service lines with in-house phlebotomy.
Japan
National health insurance reimbursement for postmenopausal dysfunction protocols expands addressable volumes in Tokyo and Osaka metropolitan areas. PMDA consultation pathways for female sexual dysfunction therapeutics are maturing, though cultural stigma channels demand toward discrete clinic environments. Kanto region specialists are adopting hormone patch protocols ahead of national guideline updates.
Brazil
Private-pay segments in São Paulo and Rio de Janeiro are expanding as ANVISA regulatory frameworks mature for sexual health therapeutics. Aesthetic medicine practices in these corridors are adopting laser and radiofrequency devices for in-office protocols. Local clinical infrastructure investments by multinational sponsors are creating first-mover positioning ahead of competitor entry.
India
BIS certification requirements for imported hormone therapies and mechanical devices create additional market access layers for foreign manufacturers. Maharashtra and Karnataka are emerging as domestic manufacturing hubs through PLI scheme alignment for active pharmaceutical ingredients. Mumbai and Bangalore gynecology chains are adding sexual health consultations to capture urban professional women.
Global Female Sexual Dysfunction Treatment Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with cross-therapeutic area infrastructure. The competitive structure concentrates around cardiovascular research platforms repurposing vascular mechanisms, neurotransmitter-targeting specialists with prior regulatory engagements, and peptide-based drug development platforms. Strategic moves center on portfolio diversification into adjacent women's health indications and geographic sequencing decisions that navigate FDA-EMA regulatory divergence.
Within the multinational pharmaceutical tier, Pfizer Inc. and GlaxoSmithKline plc exemplify players leveraging established research infrastructure across therapeutic areas. Sprout Pharmaceuticals Inc. occupies a specialist position focused on neurotransmitter-targeting oral medications with prior FDA regulatory experience. PALATIN anchors the peptide-based development segment through melanocortin receptor pathway platforms. These three represent distinct competitive archetypes: repurposed cardiovascular infrastructure, neurotransmitter specialization, and peptide-based innovation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Duchesnay Pharmaceutical Group Inc. |
| Mayne Pharma Group Limited |
| Sprout Pharmaceuticals Inc. |
| Cipla Limited |
| Merck & Co. Inc. |
| Novo Nordisk AS |
| PALATIN |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between API manufacturers and hormone therapy sponsors lock in supply access and price visibility across multi-year procurement cycles. These contracts insulate sponsors from active pharmaceutical ingredient volatility while committing volume thresholds that shape manufacturing capacity planning in India and China.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate procurement between hormone therapy sponsors and API manufacturers. Three-tier pricing structure across premium peptide-based formulations, standard oral tablets, and economy topical generics separates reimbursement-eligible prescriptions from cash-pay segments. Pricing pressure stems from generic entry on expiring arousal disorder patents. Cash-pay patients in Brazil and India exhibit highest price sensitivity; insured perimenopausal cohorts in Germany and Japan demonstrate lowest elasticity.
Supply Chain Analysis
Inventory buffers for melanocortin receptor peptides extend lead times beyond standard small-molecule synthesis cycles. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland. Finished formulation depends on estrogen precursors sourced from soybean and yam extraction, peptide synthesis reagents, and specialized transdermal patch substrates. Single-source vulnerability runs through FDA-registered peptide manufacturers. Distribution runs through pharmacy chains and online fulfillment platforms with cold-chain requirements for injectable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from wellness-positioned devices and direct-to-consumer hormone testing kits that bypass traditional clinical gatekeepers. Defense requires portfolio moves that embed pharmacological treatments within broader care protocols.
For Market Incumbents: Compound therapeutic moats by integrating digital companion apps with prescription protocols to capture adherence data and erect switching costs. Deepen backward integration into peptide manufacturing through captive supply agreements with Indian API specialists. Acquire telehealth platforms in Australia and the United Kingdom to control patient initiation channels before competitors establish subscription relationships.
For New Entrants and Emerging Players: Differentiate on neuromodulator-device convergence protocols that pair transdermal delivery with wearable biofeedback hardware. Target sexual wellness centers in Madrid, Barcelona, and Milan aesthetic medicine clusters where device adoption outpaces pharmaceutical prescribing. Pursue ANVISA pre-submission pathways in Brazil to secure first-mover positioning before multinational sponsors complete local infrastructure investments.
For Investors and Strategic Acquirers: Peptide-based development platforms with melanocortin receptor expertise represent the priority acquisition archetype for portfolio diversification into female sexual dysfunction. Long-term viability hinges on regulatory navigation capabilities across FDA subjective endpoint requirements and EMA quality-of-life composite frameworks. Monitor FDA guidance document releases on patient-reported outcome validation as inflection indicators for trial design cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Regulatory Track Investment | Parallel FDA and EMA trial designs compress launch sequencing delays across Atlantic markets. |
| Telehealth Platform Acquisition | Direct-to-consumer channels in Australia and the United Kingdom capture diagnosis before specialist referral. |
| API Manufacturing Scale-Up | Indian PLI scheme alignment reduces cost structures for hormone synthesis serving Asian demand. |
| Peptide Pipeline Expansion | Melanocortin receptor programs address arousal disorder mechanisms with differentiated efficacy profiles. |
| Reimbursement Strategy Development | Statutory coverage negotiations in Germany and Japan unlock volume among aging insured cohorts. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs.
Sensitivity analysis tested forecast robustness across regulatory approval probability scenarios and pricing elasticity assumptions. Segmentation dimensions modeled include therapy area, product type, administration route, regional regulatory cluster, and distribution channel. CAGRs derived from epidemiological trend extrapolation, treatment rate penetration curves, and pricing trajectory analysis. Forecast inputs incorporated postmenopausal demographic projections and telehealth adoption velocity patterns.
The analysis sits within stated boundaries; outcomes outside current FDA guidance stability or EMA benefit-risk framework continuity would require recalibration. Forecasts reflect documented assumptions regarding reimbursement pathway expansion and specialist workforce growth. Patent cliff timing, regulatory divergence intensity, and generic entry acceleration represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Europe Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Global Dry Eye Syndrome Treatment Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Nonalcoholic Steatohepatitis Market
Specialty Medicine
Bartter Syndrome Treatment Market