
 Diabetes Injection Pens Market | 2026-2036
Diabetes Injection Pens Market Size, Share, and Industry Trends Forecast 2026-2036
Diabetes Injection Pens Market Analysis
Home care is shifting from hospital-centric diabetes management toward patient-directed injection routines. Novo Nordisk A/S leverages its integrated insulin and GLP-1 portfolio to dominate pen-based delivery systems. Eli Lilly and Company anchors its position through sustained R&D investment in dose-adjustable pen architectures. Sanofi competes across both disposable and reusable delivery formats in European and Asian markets.
Diabetes injection pens are spring-loaded, precision-dose drug delivery devices engineered to administer insulin or GLP-1 agonists subcutaneously through ultra-fine needles, typically calibrated in one-unit increments for metabolic control. Insulin pens retain the largest volume footprint, though GLP-1 agonist pens are capturing disproportionate growth as semaglutide and tirzepatide prescriptions expand. Pre-filled disposable pens command the majority of value share in developed markets, while cartridge-based reusable systems sustain stronger penetration in cost-sensitive regions where refill economics matter.
FDA 21 CFR Part 820 quality system regulations and EU MDR Class IIa device requirements govern pen design validation, biocompatibility testing, and post-market surveillance across major commercial jurisdictions. ISO 11608 needle-based injection systems standards define dose accuracy, injection force, and sterility benchmarks that manufacturers must satisfy for market access. Stakeholders should monitor how tightening EUDAMED traceability mandates and evolving USP <797> compounding standards reshape supply chain documentation burdens and competitive compliance costs.
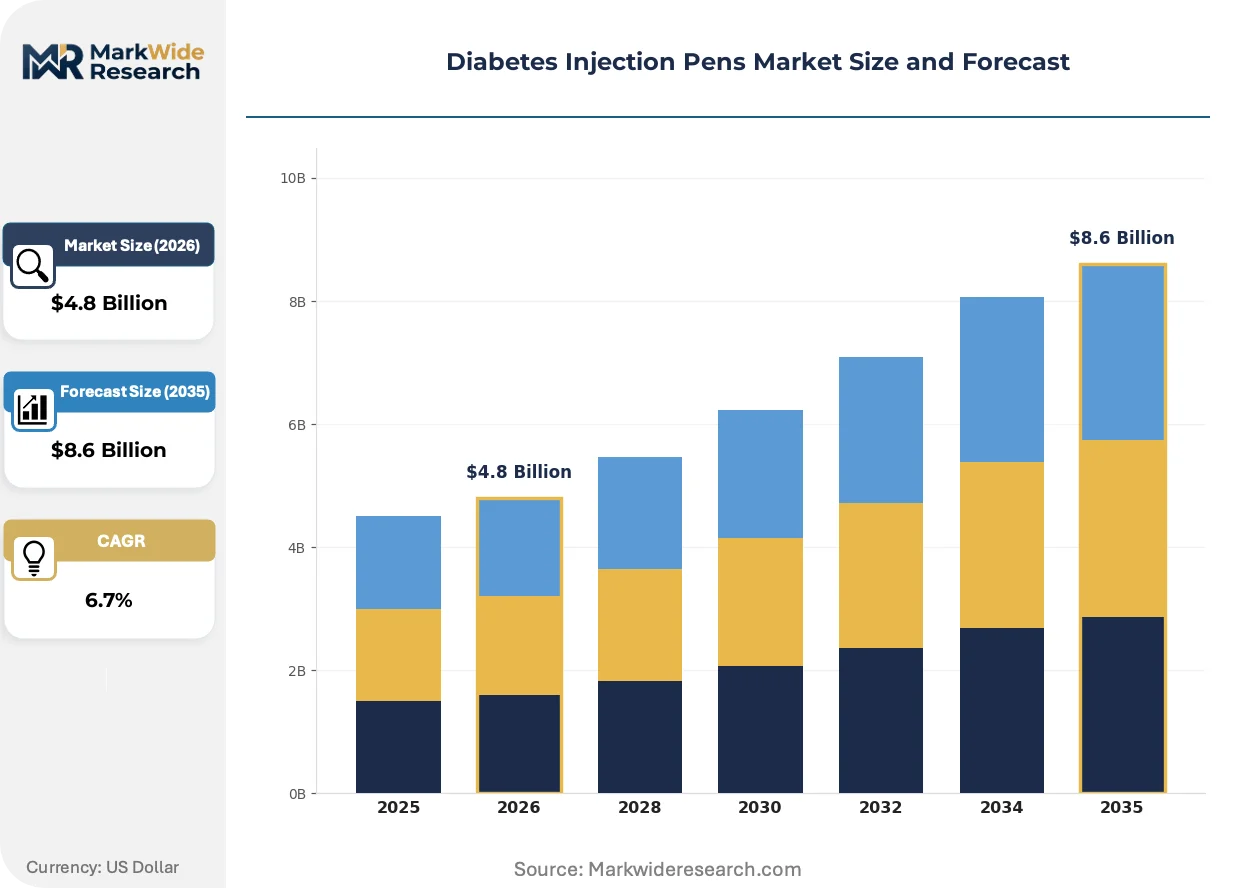
Market Dynamics
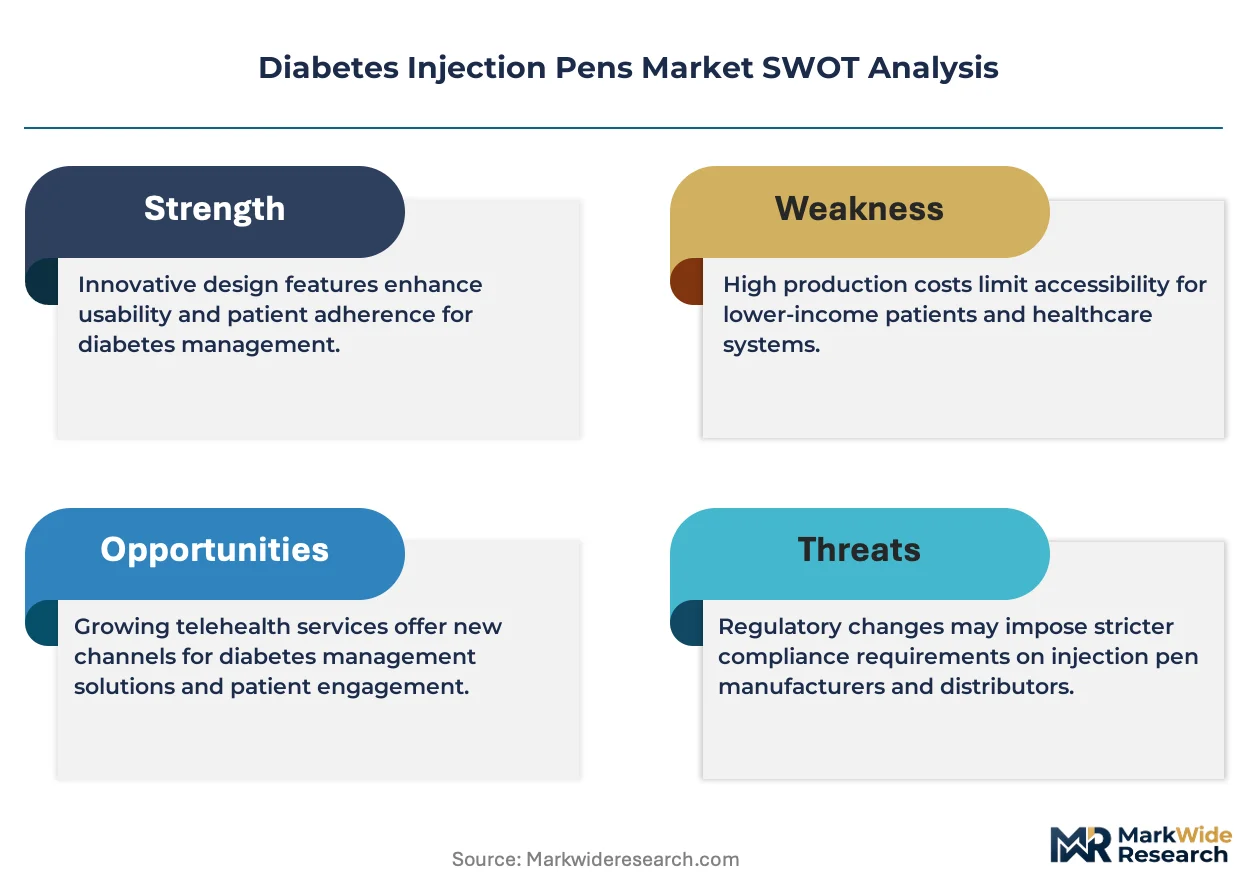
GLP-1 agonist therapies are compressing the traditional insulin-dominant market structure as semaglutide and tirzepatide prescriptions redirect patient volumes toward dual-hormone metabolic management. FDA 21 CFR Part 820 quality system regulations and EU MDR Class IIa device requirements are simultaneously tightening dose-accuracy and needle-safety validation thresholds, forcing manufacturers to re-engineer spring-loaded mechanisms and biocompatibility testing protocols.
Growth Catalysts
- Home care self-administration:Patients managing type 2 diabetes prioritize injection convenience over clinical visits, accelerating pen adoption in residential settings across Germany and Japan.
- EMA MDR traceability mandates:EUDAMED device registration requirements are standardizing supply chain documentation, reducing counterfeit penetration in European distribution channels.
- Ultra-fine needle engineering:32-gauge and 34-gauge needle technologies reduce injection pain perception, expanding patient compliance among pediatric and needle-averse demographics.
Market Restraints
- Specialized polymer supply concentration:Medical-grade polycarbonate and cyclic olefin polymer production clusters in East Asian chemical hubs, exposing pen manufacturers to input cost volatility and logistics disruption.
- Reimbursement pathway fragmentation:GLP-1 therapy coverage varies across United States commercial payers and Medicare Advantage plans, creating prescribing friction and patient access barriers.
- Reusable pen technical limitations:Cartridge-based systems require patient dexterity for dose dialing and needle attachment, limiting adoption among elderly populations with reduced fine motor control.
Strategic Opportunities
- Connected pen ecosystem integration:Bluetooth-enabled dose logging and smartphone app pairing is expanding into United States and German markets, capturing adherence data for payers and clinicians.
- Latin American market underpenetration:Brazil and Mexico exhibit low disposable pen penetration relative to North American benchmarks, presenting volume expansion potential as local reimbursement frameworks mature.
- Japanese PMDA fast-track pathways:Japan's priority review designation for combination diabetes devices accelerates regulatory timelines for manufacturers introducing dual-chamber insulin-GLP-1 pens.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization studies require 18-24 month validation cycles, delaying product iterations and competitive response capabilities.
- Legacy health record integration complexity:Connected pen data streams must interface with Epic, Cerner, and regional electronic medical record architectures, demanding substantial software engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diabetes Injection Pens Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, GLP-1 Agonist Pens, Fixed-Dose Combination Pens, Dose-Adjustable Pens Delivery Mode: Pre-filled, Cartridge-Based, Disposable, Reusable End User: Hospitals, Clinics, Home Care, Pharmacies Patient Demographics: Pediatric Patients, Adult Patients, Elderly Patients, Special Needs Patients |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, Ypsomed Holding AG, Becton, Dickinson and Company, Merck KGaA, AstraZeneca, Owen Mumford, Haselmeier GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diabetes Injection Pens Market Emerging Trajectories
Precision dosing mechanisms and digital connectivity layers are converging to transform injection pens from passive delivery devices into active therapeutic monitoring platforms. Manufacturers are embedding sensors and wireless modules that capture real-world adherence patterns.
Smart pen technology with integrated dose memory and time-stamped injection logging is expanding into United States endocrinology practices and large health system formularies. Endocrinologists and diabetes educators prescribe connected systems to identify missed doses and optimize titration schedules. This capability is compressing the information gap between clinical visits, enabling remote therapeutic monitoring and reducing HbA1c variability.
EU MDR Class IIa device requirements and FDA 21 CFR Part 820 quality system regulations are mandating enhanced post-market surveillance and unique device identification traceability. Manufacturers must maintain EUDAMED registration and submit periodic safety reports, elevating compliance infrastructure costs. Pre-filled disposable pen categories face the steepest documentation burdens, prompting some suppliers to consolidate product portfolios and exit marginal SKUs.
Patient-directed pharmacy procurement is displacing traditional physician-sample distribution for GLP-1 pen initiation in United States and German markets. Retail pharmacy channels and mail-order fulfillment now capture first-fill prescriptions previously routed through clinic inventory. This channel rotation is most visible in United States commercial insurance segments where pharmacy benefit managers steer volume toward preferred retail networks and 90-day supply programs.
Diabetes Injection Pens Market Segmentation
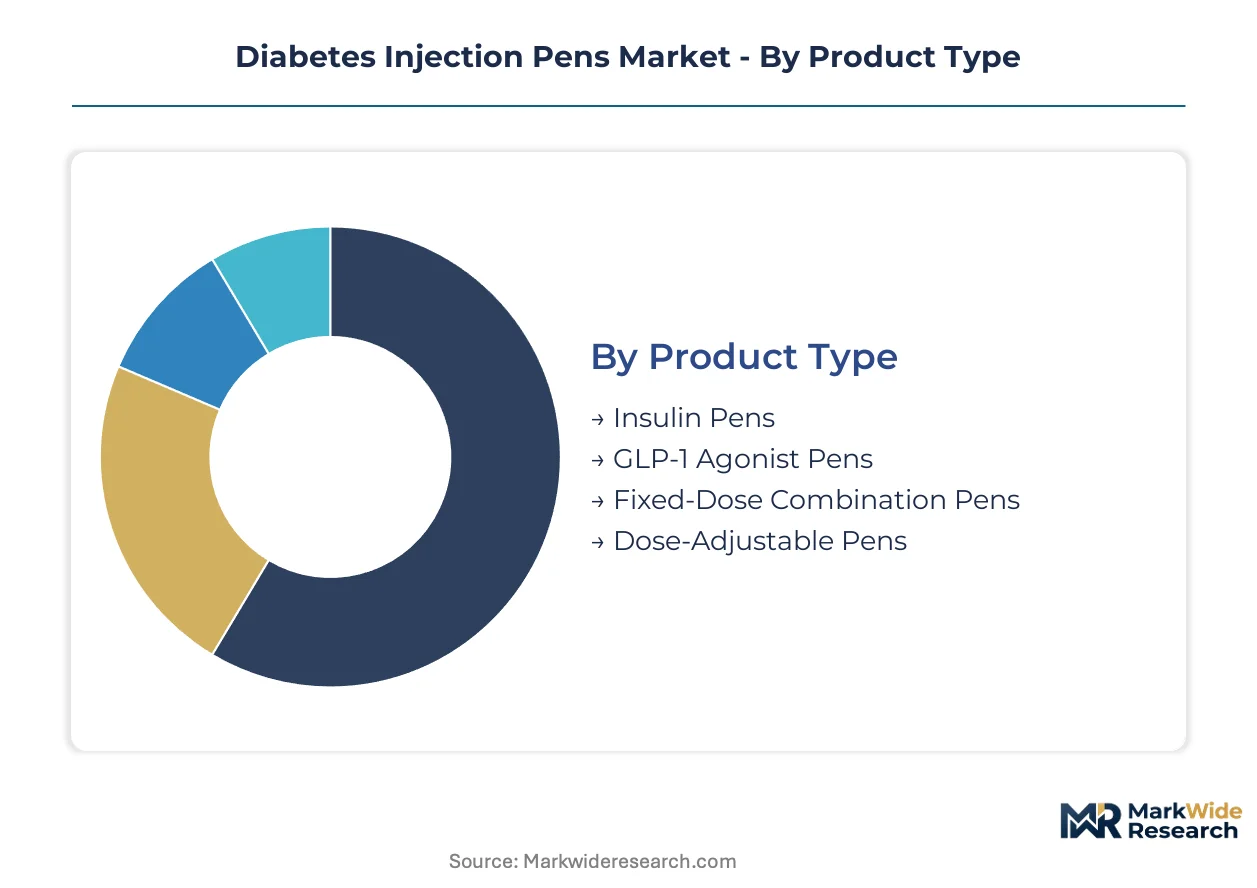
Pen architecture and patient capability requirements create distinct procurement patterns across diabetes care settings. Manufacturers configure spring-loaded mechanisms, dose calibration systems, and connectivity modules differently for each segment to match clinical workflows and reimbursement pathways.
Product Type:
Prescriber preference for single-hormone versus combination therapy drives divergent engineering priorities and regulatory submission strategies.
- Insulin Pens:Spring-loaded devices calibrated for basal and bolus insulin analogs dominate hospital formularies and retail pharmacy channels. Demand concentrates in United States Medicare Part D and German statutory health insurance programs where long-acting insulin reimbursement is standardized.
- GLP-1 Agonist Pens:Pre-filled disposable systems engineered for weekly semaglutide and tirzepatide administration are capturing disproportionate growth in United States endocrinology practices and Japanese diabetes centers as prescribers prioritize cardiovascular risk reduction alongside glycemic control.
- Fixed-Dose Combination Pens:Dual-chamber devices merge insulin and GLP-1 agonists in single injection sequences for complex type 2 diabetes management.
- Dose-Adjustable Pens:Precision-dial mechanisms enable 0.5-unit or 1-unit titration increments for insulin-sensitive pediatric and elderly populations.
Insulin pens lead volumes today; GLP-1 agonist pens are gaining share fastest.
Delivery Mode:
Capital expenditure tolerance and supply chain reliability requirements separate institutional buyers from individual patients.
- Pre-filled:Factory-sealed pens with integrated drug reservoirs eliminate patient assembly steps and reduce dosing errors. United States pharmacy benefit managers and Japanese hospital purchasing consortia favor pre-filled formats for 90-day supply programs and inventory standardization.
- Cartridge-Based:Reusable pen bodies accept replaceable insulin or GLP-1 cartridges, reducing per-injection material costs for high-volume users in German home care settings where refill economics influence patient choice.
- Disposable:Single-use pens with fixed drug loads dominate GLP-1 therapy initiation in United States retail channels.
- Reusable:Durable pen housings with multi-year lifespans sustain penetration in cost-sensitive markets and environmental compliance-focused European procurement frameworks.
Pre-filled disposables anchor revenue; reusable systems are expanding most quickly in sustainability-sensitive jurisdictions.
End User:
Clinical oversight intensity and documentation requirements shape device feature specifications and connectivity integration depth.
- Home Care:Self-administration settings demand intuitive dose dialing, audible click feedback, and Bluetooth-enabled adherence logging for remote monitoring by United States accountable care organizations and Japanese diabetes educators.
- Hospitals:Inpatient units require tamper-evident packaging, barcode scanning compatibility, and integration with Epic or Cerner electronic medical record systems for medication administration verification.
- Clinics:Outpatient endocrinology practices prioritize sample pens for therapy initiation and patient training programs.
- Pharmacies:Retail dispensing channels capture first-fill GLP-1 prescriptions previously routed through physician sample closets in United States commercial insurance segments.
Home care generates the steepest volume climb; hospitals retain the highest per-unit specification thresholds.
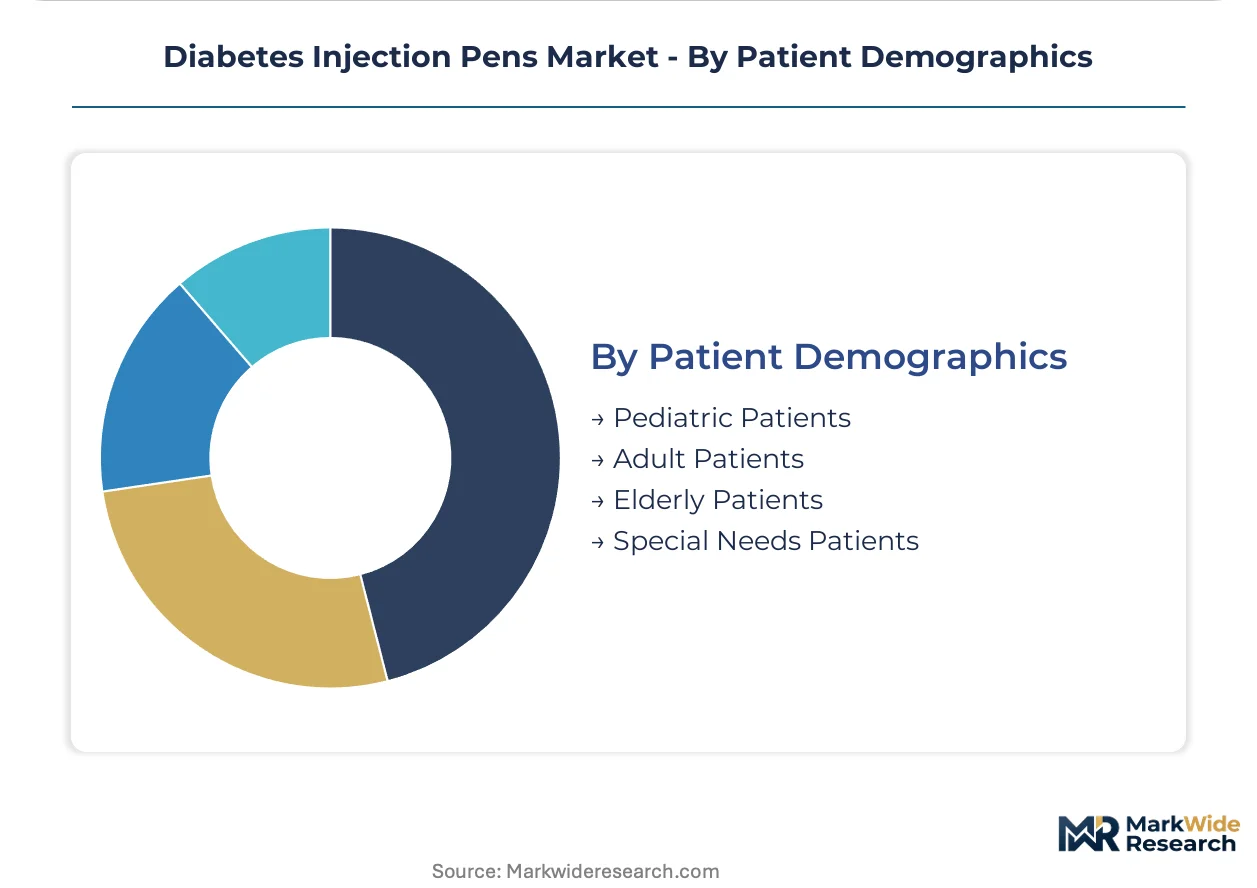
Patient Demographics:
Motor control capability, cognitive load tolerance, and caregiver involvement determine interface complexity and safety feature requirements.
- Elderly Patients:Reduced fine motor control and polypharmacy complexity necessitate large-font dose displays, ergonomic grips, and automated needle shielding in Japanese and German markets where diabetes prevalence skews older.
- Pediatric Patients:Needle anxiety and growth hormone interaction considerations drive demand for ultra-fine 32-gauge needles and gamified adherence apps in United States pediatric endocrinology centers.
- Adult Patients:Working-age populations balance discretion, portability, and workplace injection privacy in device selection.
- Special Needs Patients:Visual impairment, arthritis, or cognitive limitations require voice-guided dosing or caregiver-assisted injection aids.
Elderly patients dominate current prescription volumes; pediatric segments are climbing the fastest as early-onset type 2 diabetes expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between jurisdictions are redirecting manufacturing investment toward regions with streamlined device approval pathways. Pen producers balance FDA and EU MDR compliance burdens against faster market access in targeted geographies.
United States
Pharmacy benefit managers and Medicare Part D reimbursement standardization sustain high disposable pen penetration across retail channels. FDA 21 CFR Part 820 quality system regulations enforce rigorous dose-accuracy validation for spring-loaded mechanisms. Boston and Minneapolis medical device clusters host engineering centers refining connected pen Bluetooth integration for accountable care organization remote monitoring programs.
Germany
Statutory health insurance reimbursement for insulin and GLP-1 therapies anchors strong home care pen adoption in residential settings. EU MDR Class IIa device requirements and EUDAMED traceability mandates standardize supply chain documentation across distribution networks. Baden-Württemberg polymer processing hubs supply medical-grade polycarbonate housings to pen manufacturers serving European markets.
Japan
Aging demographics and high type 2 diabetes prevalence concentrate prescription volumes among elderly patients requiring ergonomic pen designs. PMDA fast-track pathways for combination diabetes devices accelerate regulatory timelines for dual-chamber insulin-GLP-1 systems. Osaka and Nagoya precision manufacturing districts produce ultra-fine 32-gauge needles for pediatric and needle-averse patient segments.
China
Expanding domestic insulin production capacity and government health insurance expansion for diabetes management drive volume growth in tier-one cities. NMPA medical device registration requirements govern biocompatibility testing and sterility validation for locally manufactured pens. Shanghai and Suzhou medical device industrial parks attract multinational joint ventures seeking cost-optimized production for Asia-Pacific distribution.
Brazil
Underpenetration of disposable pen formats relative to North American benchmarks presents expansion opportunity as local reimbursement frameworks mature. ANVISA medical device regulations align with ISO 11608 needle-based injection systems standards for dose accuracy certification. São Paulo pharmaceutical distribution corridors consolidate pen logistics for Latin American regional supply.
Diabetes Injection Pens Market Vendor Landscape
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers extend delivery device capabilities alongside drug development. The market structure concentrates around vertically integrated drug-device combinations and specialized pen engineering suppliers serving multiple therapeutic areas. Three archetypes define competitive positioning: integrated pharma-device developers controlling end-to-end insulin and GLP-1 ecosystems, dedicated pen technology specialists licensing platforms to drug marketers, and contract manufacturers producing private-label devices for regional distributors. Capacity expansion in polymer molding and spring mechanism fabrication represents the primary competitive move, followed by strategic partnerships bridging drug formulation expertise with device engineering.
Among integrated pharmaceutical developers, Novo Nordisk A/S and Eli Lilly and Company exemplify the dominant archetype combining proprietary drug portfolios with captive pen delivery systems. Sanofi occupies a position bridging integrated development and multi-format supply across disposable and reusable architectures. Ypsomed Holding AG represents the specialist engineering tier, supplying pen platforms to drug marketers lacking in-house device capabilities.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| Ypsomed Holding AG |
| Becton, Dickinson and Company |
| Merck KGaA |
| AstraZeneca |
| Owen Mumford |
| Haselmeier GmbH |
| Others |
Supply Flow & Price Mechanics
Precision polymer engineering talent clusters in Baden-Württemberg and Osaka-Nagoya manufacturing corridors, and labor-cost differentials between these German-Japanese hubs and emerging Chinese production zones widen pricing-tier spreads across pre-filled disposable and reusable pen categories.
Pricing Analysis
Distributor margins for GLP-1 agonist pens absorb 15-25 percentage points of end-user price in United States pharmacy benefit manager networks. Pricing stratifies across premium connected-pen tiers with Bluetooth logging, standard disposable formats for insulin therapy, and economy reusable systems for cost-sensitive German home care markets. Cost compression in standard disposable tiers intensifies as Novo Nordisk and Eli Lilly consolidate volume contracts with United States retail chains. Pediatric endocrinology practices show lowest price sensitivity due to reimbursement standardization, while uninsured elderly patients in Brazilian cash markets exhibit highest sensitivity.
Supply Chain Analysis
ISO 13485 and EU MDR quality management certifications gate supplier entry, forcing pen manufacturers to audit polymer molders and spring fabricators against 18-month validation timelines. Medical-grade polycarbonate housings draw from German and Japanese chemical hubs, while ultra-fine 32-gauge needle production centers on Osaka precision manufacturing districts and Suzhou medical device parks. Single-source vulnerability concentrates in cyclic olefin polymer feedstocks from East Asian petrochemical complexes. Distribution runs through United States pharmacy benefit manager networks, German statutory health insurance procurement consortia, and Japanese hospital purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diabetes injection pen production operates as a geographic-arbitrage play between FDA-regulated United States assembly and EU MDR-governed European manufacturing, with quality-system compliance costs running 40% higher in the latter jurisdiction.
For Market Incumbents: Acquire precision spring mechanism fabrication capabilities to secure supply continuity against Japanese and German component concentration. Consolidate polymer molding capacity in Baden-Württemberg to defend margin position against emerging Chinese competitors. Threat substitution from oral GLP-1 formulations demands accelerated investment in connected-pen adherence data platforms to preserve formulary access. For New Entrants and Emerging Players: Begin with Brazilian and Mexican pharmacy channels where disposable pen penetration lags North American benchmarks by 30-40 percentage points. Target elderly patient segments in Japanese home care markets requiring ergonomic grip modifications. Pursue private-label manufacturing contracts with regional insulin producers lacking captive device engineering. For Investors and Strategic Acquirers: Integrated pharmaceutical-device developers are the most active acquirers in this space, capturing vertical margin pools across drug and delivery combinations. Target specialist pen engineering firms with ISO 11608 certification portfolios and existing supply relationships with mid-tier GLP-1 marketers. Watch FDA breakthrough device designations for dual-chamber insulin-GLP-1 systems as inflection signal for portfolio consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Pen Ecosystem Integration | Bluetooth-enabled dose logging captures adherence data for United States accountable care organization remote monitoring programs. |
| Dual-Chamber Combination Device Development | Single-injection insulin-GLP-1 delivery addresses polypharmacy burden in Japanese elderly diabetes populations. |
| Latin American Distribution Partnership | Brazilian pharmacy channel expansion captures volume growth as local reimbursement frameworks mature. |
| EU MDR Compliance Infrastructure Investment | EUDAMED traceability registration secures European market access amid tightening post-market surveillance mandates. |
| Ultra-Fine Needle Manufacturing Scale-Up | 32-gauge and 34-gauge production capacity expansion serves pediatric and needle-averse patient compliance needs. |
Methodological Framework
Multiple input streams — structured interviews with diabetes device engineering directors, formulary access specialists at United States pharmacy benefit managers, and hospital procurement managers in German statutory health insurance networks — were reconciled against secondary validation from FDA 510(k) filings, EUDAMED device registrations, and Japanese PMDA approval databases. Bottom-up pen shipment estimates by product architecture and hormone type were triangulated against top-down insulin and GLP-1 prescription volume data from CMS Medicare Part D and German GKV-Spitzenverband reporting.
Data-stream reconciliation across the projection horizon applied patient demographic segmentation by age cohort and therapy line, delivery mode differentiation between pre-filled disposable and cartridge-based reusable formats, and regional regulatory cluster grouping by FDA, EU MDR, and PMDA jurisdiction. CAGRs were derived from fitted growth curves anchored to reported prescription volumes and device replacement cycles. Forecast inputs incorporated connected-pen adoption curves in United States endocrinology practices and GLP-1 therapy expansion rates in Japanese diabetes centers.
Several conditions sit outside the modeled scope, including oral GLP-1 formulation clinical trial outcomes, biosimilar insulin pricing litigation settlements, and raw material supply disruptions from East Asian petrochemical hub congestion. Forecasts reflect documented assumptions regarding reimbursement pathway stability and regulatory timeline predictability. A model refresh is warranted upon material change in FDA breakthrough device designation patterns or EMA MDR audit intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
Digital Diabetes Care Market
Diabetes Care
Europe Insulin Infusion Pumps Market
Diabetes Care
Italy Continuous Glucose Monitoring Devices Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Type 2 Diabetes Mellitus Treatment Market
Diabetes Care
France Insulin Infusion Pump Market
Diabetes Care
Smart Glucose Monitors Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
India Continuous Glucose Monitoring (CGM) Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Global Diabetes Pen Market