
 Middle East and Africa Diabetes Market | 2026-2036
Middle East and Africa Diabetes Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Diabetes Market Foresight
The UAE's mandatory health insurance expansion for chronic diseases is pivoting reimbursement structures toward preventive monitoring technologies. Novo Nordisk leverages its insulin production footprint to sustain supply security across North African markets. Julphar anchors regional manufacturing capabilities for oral hypoglycemics, competing with imported brands on cost structure. Abbott differentiates through continuous glucose monitor distribution networks spanning Gulf hospital systems.
Diabetes care in the Middle East and Africa encompasses pharmacological interventions, metabolic monitoring devices, and digital health infrastructure designed to manage chronic hyperglycemia and prevent microvascular complications. Insulin formulations require cold-chain logistics maintaining two-to-eight-degree Celsius stability throughout distribution, while oral hypoglycemics such as metformin and sulfonylureas function through hepatic glucose suppression and pancreatic beta-cell stimulation. Continuous glucose monitors represent the fastest-growing product category as Gulf hospital systems replace finger-prick protocols with real-time data streams. Home care end users command expanding share as Saudi and Emirati health ministries push ambulatory management to reduce inpatient burden. Telemedicine solutions within the technology segment attract venture deployment for remote endocrinology consultations across geographically dispersed populations.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority govern device approvals and pharmaceutical import licensing, while the UAE's Ministry of Health and Prevention enforces Gulf Standardization Organization conformity marks for glucose monitoring equipment. These frameworks elevate compliance costs for new entrants but protect incumbent suppliers with established regulatory dossiers. Stakeholders must monitor how national insurance reimbursement lists evolve to include wearable devices and mobile app-integrated diagnostics.
Market Dynamics
Continuous glucose monitoring systems are displacing finger-prick protocols across Gulf hospital systems, compressing diagnostic timelines while expanding real-time data capture requirements for diabetes management infrastructure.
Growth Catalysts
- SFDA Device Acceleration Pathways:Saudi Food and Drug Authority streamlined registration for wearable glucose monitors, reducing approval timelines for connected diabetes devices entering the Kingdom's hospital procurement channels.
- UAE Mandatory Chronic Disease Coverage:Emirates health insurance mandates now classify preventive monitoring technologies as reimbursable, redirecting patient cost burden toward ambulatory glucose management solutions.
- Saudi Specialist Center Expansion:Ministry of Health networks are multiplying diabetes treatment facilities across Riyadh and Jeddah, concentrating demand for integrated monitoring and insulin delivery systems.
Market Restraints
- Cold-Chain Distribution Costs:Insulin formulations require two-to-eight-degree Celsius stability throughout Middle Eastern and African logistics corridors, elevating last-mile expenditure in thermally challenging climates.
- South African Registration Tightening:Health Products Regulatory Authority imposed stricter clinical evidence requirements for glucose monitoring technologies, extending market entry timelines for non-established suppliers.
- Import Dependency Concentration:Oral hypoglycemic manufacturing remains concentrated in Indian and European supply bases, exposing North African markets to currency fluctuation and shipping disruption risks.
Strategic Opportunities
- Telemedicine Integration White Space:Remote endocrinology consultation platforms remain underdeveloped across geographically dispersed Saudi and Emirati populations, creating venture deployment targets for app-integrated diagnostic workflows.
- Egyptian Manufacturing Localization:Pharmaceutical production incentives under national industrial development frameworks could anchor regional oral hypoglycemic supply, reducing import leakage.
- Gulf Standardization Organization Convergence:Unified conformity marking requirements across UAE, Saudi Arabia, Kuwait, and Qatar enable single-registration market access for glucose monitoring equipment suppliers.
Industry Challenges
- Endocrinology Specialist Scarcity:Gulf health systems face shortages of certified diabetes care physicians, constraining patient-to-provider ratios in expanding Ministry of Health center networks.
- Legacy System Interoperability:Hospital information systems across South African public health infrastructure lack standardized data exchange protocols with continuous glucose monitor outputs, complicating EHR integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Diabetes Market |
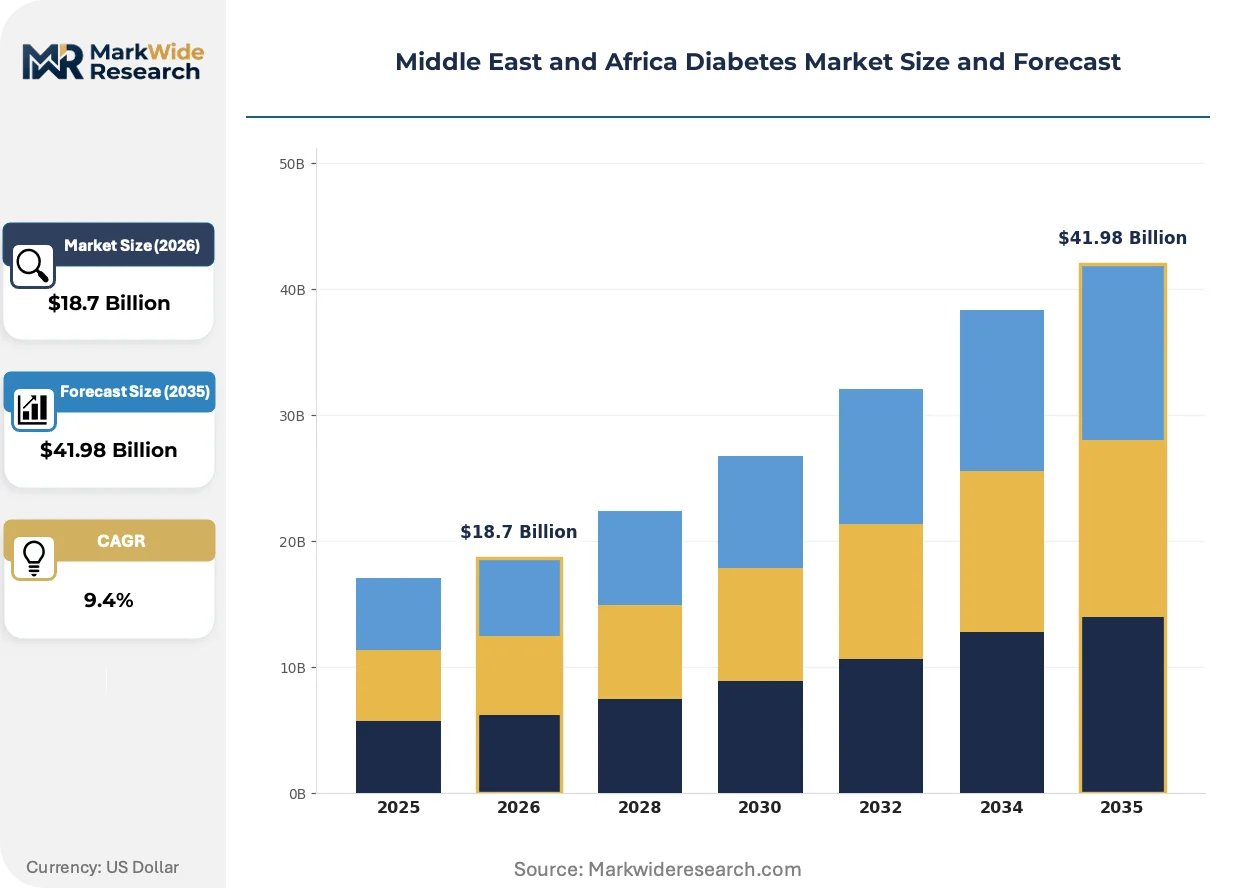
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Oral Hypoglycemics, Continuous Glucose Monitors, Blood Glucose Test Strips End User: Hospitals, Diabetes Clinics, Home Care, Retail Pharmacies Distribution Channel: Direct Sales, Wholesalers, E-commerce, Retail Stores Technology: Wearable Devices, Mobile Apps, Telemedicine Solutions, Advanced Diagnostics |
| Companies Covered | AstraZeneca, Julphar, Novo Nordisk, Medtronic, Abbott, Sanofi, Merck & Co., Hikma, Eli Lilly and Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Diabetes Market Shifts & Advancements
Digital health infrastructure is penetrating diabetes management workflows across Middle Eastern and African care settings, converging sensor hardware, cloud analytics, and reimbursement policy into integrated chronic disease platforms.
Continuous glucose monitoring technology is automating real-time hyperglycemia detection through subcutaneous sensor arrays transmitting glucose readings to receiver devices and smartphone applications. Saudi hospital systems are replacing manual finger-prick testing protocols with these connected systems at accelerating procurement rates. The technology is automating nursing workflow reduction while enabling predictive hypoglycemia alerts that compress emergency intervention response times.
South African Health Products Regulatory Authority tightened medical device registration requirements for glucose monitoring technologies, demanding expanded clinical evidence packages from manufacturers seeking market authorization. This regulatory friction elevates compliance expenditure for new entrants while protecting incumbent suppliers with established regulatory dossiers. Imported continuous glucose monitor brands with existing South African registrations are consolidating distribution partnerships to defend channel position against delayed competitors.
Home-based diabetes management is displacing inpatient glycemic control as Saudi and Emirati health ministries prioritize ambulatory care models to reduce hospital burden. Patients are acquiring personal continuous glucose monitors through retail pharmacy channels rather than institutional procurement, fragmenting traditional device distribution pathways. This behavioral rotation is most visible in Dubai and Abu Dhabi, where health insurance reimbursement for preventive monitoring technologies has redirected patient acquisition patterns toward direct-to-consumer models.
Middle East and Africa Diabetes Market Segmentation
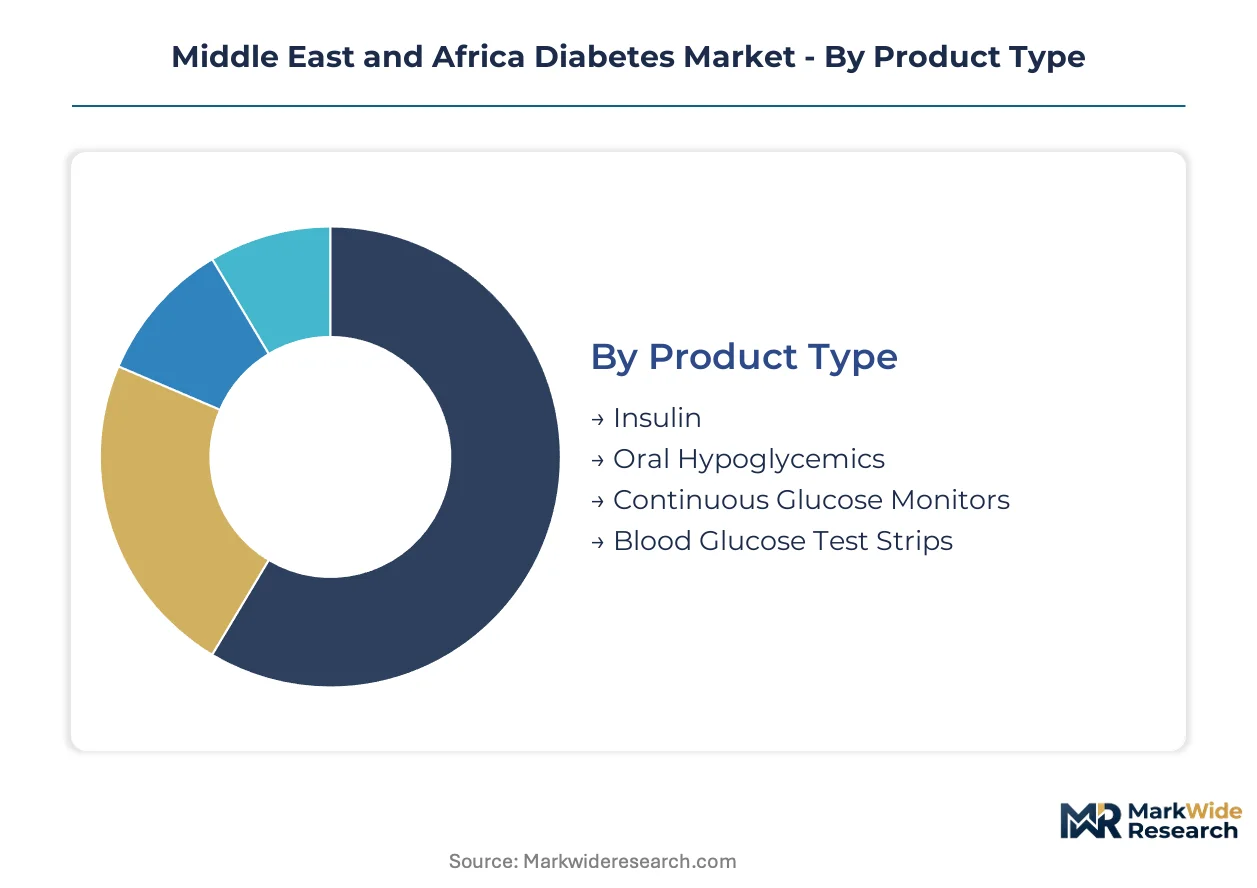
Diabetes care delivery across Middle East and Africa fragments across therapeutic modalities, care settings, and technology interfaces. Procurement patterns diverge sharply between institutional hospital buyers and ambulatory home-care consumers, requiring distinct go-to-market architectures.
Product Type:
Cost tier separates acute intervention buyers from preventive monitoring adopters across Gulf and North African markets.
- Insulin:Injectable formulations requiring cold-chain logistics at two-to-eight-degree Celsius stability. Demand concentrates in Saudi Ministry of Health specialist centers where inpatient glycemic management protocols drive bulk procurement of rapid-acting and long-acting analogs.
- Continuous Glucose Monitors:Subcutaneous sensor arrays transmitting real-time glucose data to receivers and smartphone applications. UAE hospital systems and Dubai retail pharmacies are displacing finger-prick protocols fastest as mandatory chronic disease insurance redirects patient acquisition toward ambulatory monitoring.
- Oral Hypoglycemics:Metformin and sulfonylurea tablets manufactured regionally by Julphar and imported from Indian supply bases.
- Blood Glucose Test Strips:Single-use electrochemical strips for handheld meters, still dominant in South African public health infrastructure lacking CGM interoperability.
Insulin leads volumes today; continuous glucose monitors are gaining share fastest.
End User:
Application context determines device specification, reimbursement pathway, and procurement cycle length.
- Hospitals:Acute care institutions across GCC states deploying integrated monitoring and insulin delivery systems for inpatient hyperglycemia management. Saudi specialist center expansion is concentrating demand for enterprise-scale device contracts with multi-year service agreements.
- Home Care:Individual patients acquiring personal continuous glucose monitors through retail pharmacy channels rather than institutional procurement. Dubai and Abu Dhabi health insurance reimbursement for preventive monitoring technologies has fragmented traditional distribution pathways toward direct-to-consumer models.
- Diabetes Clinics:Outpatient facilities within Ministry of Health networks providing specialist endocrinology consultations.
- Retail Pharmacies:Community dispensaries serving oral hypoglycemic prescriptions and over-the-counter glucose testing supplies.
Hospitals dominate procurement value; home care is expanding most quickly.
Distribution Channel:
Customer type dictates channel preference between institutional procurement and individual acquisition.
- Direct Sales:Manufacturer-to-institution contracts for continuous glucose monitor systems and insulin pump installations. Gulf hospital procurement channels favor direct relationships with established regulatory dossiers.
- E-commerce:Online platforms enabling patient-direct acquisition of wearable devices and subscription sensor refills. UAE and Saudi consumer bases are rotating toward digital purchase pathways for home-care diabetes management.
- Wholesalers:Regional distributors handling cold-chain insulin logistics across thermally challenging Middle Eastern and African corridors.
- Retail Stores:Physical pharmacy counters for immediate-need test strips and emergency glucose supplies.
Direct sales capture institutional value; e-commerce is climbing the fastest.
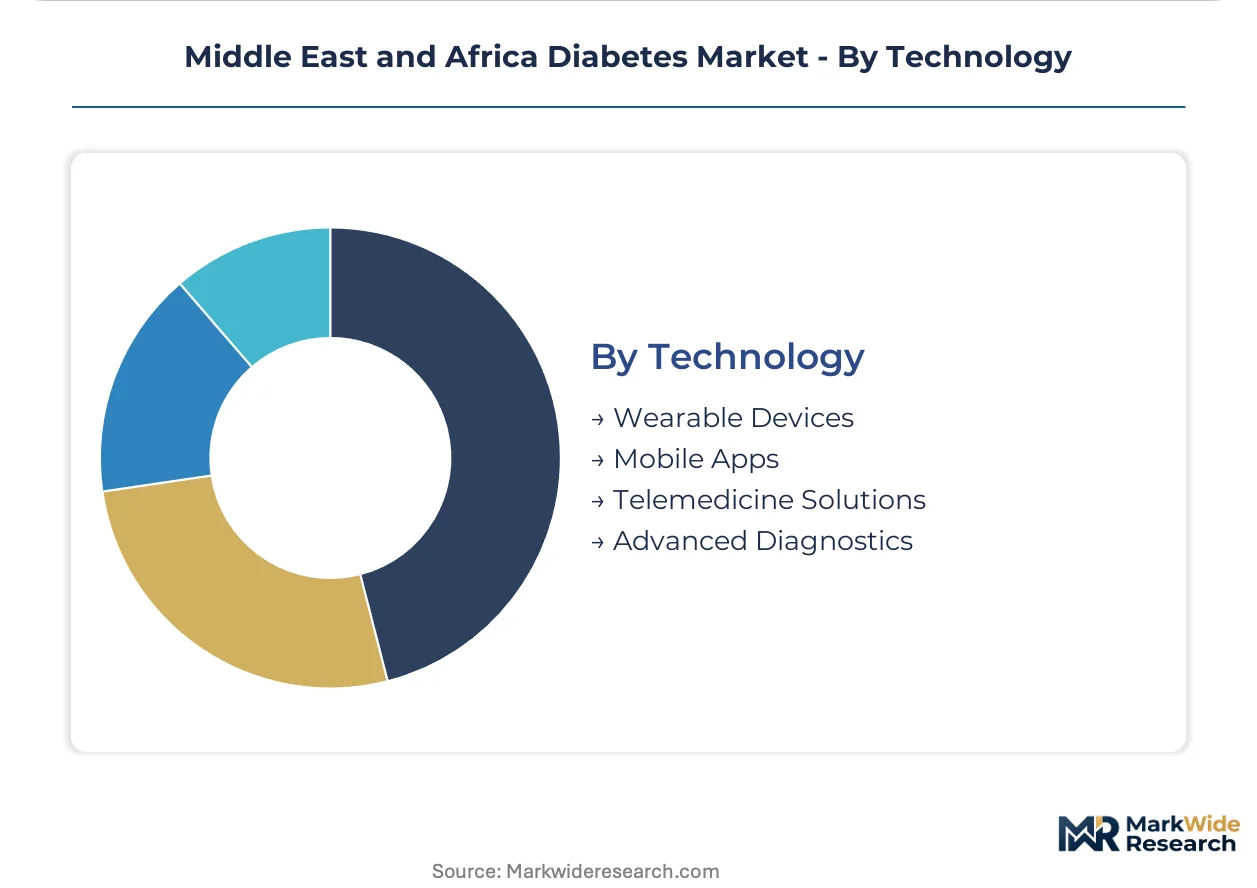
Technology:
Maturity stage separates deployed infrastructure from venture-stage innovation platforms.
- Wearable Devices:Continuous glucose monitor hardware comprising subcutaneous sensors, transmitters, and receiver units. SFDA device acceleration pathways are compressing approval timelines for connected diabetes devices entering Saudi hospital procurement.
- Telemedicine Solutions:Remote endocrinology consultation platforms for geographically dispersed Saudi and Emirati populations. This segment remains underdeveloped, creating venture deployment targets for app-integrated diagnostic workflows.
- Mobile Apps:Smartphone software integrating glucose data visualization, meal logging, and insulin dosing calculators.
- Advanced Diagnostics:Predictive analytics and artificial intelligence tools for hypoglycemia risk stratification.
Wearable devices anchor current deployment; telemedicine solutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes care infrastructure in the Middle East and Africa traces its modern lineage to post-1980s Gulf state hospital investments, which established specialist endocrinology capacity before expanding into ambulatory monitoring networks.
Saudi Arabia
Ministry of Health specialist center expansion in Riyadh and Jeddah is concentrating demand for integrated insulin delivery systems. SFDA device acceleration pathways compress approval timelines for wearable glucose monitors entering hospital procurement. Eastern Province industrial zones are attracting cold-chain logistics investments for temperature-stable insulin distribution.
United Arab Emirates
Mandatory health insurance expansion for chronic diseases is redirecting patient acquisition toward preventive monitoring technologies. MOHAP enforces Gulf Standardization Organization conformity marks for glucose monitoring equipment entering Dubai and Abu Dhabi markets. Dubai Healthcare City clusters telemedicine ventures targeting remote endocrinology consultations for geographically dispersed Emirati populations.
South Africa
Health Products Regulatory Authority tightened medical device registration requirements, extending market entry timelines for glucose monitoring suppliers lacking established dossiers. Public health infrastructure in Gauteng and Western Cape provinces retains finger-prick testing dominance due to legacy system interoperability gaps with continuous glucose monitor outputs. Cape Town medical device distributors are consolidating partnerships with incumbent CGM brands.
Egypt
Pharmaceutical production incentives under national industrial development frameworks could anchor regional oral hypoglycemic manufacturing. Cairo and Alexandria pharmaceutical zones currently import metformin and sulfonylurea tablets from Indian supply bases. Local production would reduce currency exposure for North African markets dependent on external API sourcing.
Israel
Digital health infrastructure development in Tel Aviv and Haifa technology corridors is generating venture deployment for app-integrated diagnostic workflows. The national health insurance system reimburses continuous glucose monitoring for Type 1 diabetes patients, establishing precedent for Gulf market policy emulation. Medical device R&D clusters are licensing sensor technologies to Saudi and Emirati hospital procurement channels.
Middle East and Africa Diabetes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the diabetes care value chain. The market exhibits tiered concentration: multinational pharmaceutical corporations anchor insulin and oral hypoglycemic supply, while specialized device manufacturers capture monitoring technology premiums. Three archetypes dominate: integrated pharma-device conglomerates, regional manufacturing specialists, and pure-play monitoring technology suppliers. Competitive moves center on regulatory dossier accumulation and distribution partnership consolidation rather than price-based rivalry.
Among Nordic-based insulin producers, Novo Nordisk occupies a position exemplifying supply security architecture across North African corridors. Within regional manufacturing, Julphar represents the specialist archetype for oral hypoglycemic production competing on cost structure against imported brands. Abbott anchors the monitoring technology tier through distribution networks spanning Gulf hospital systems, illustrating how established regulatory approvals defend channel position against delayed entrants.
| Leading Market Players |
|---|
| AstraZeneca |
| Julphar |
| Novo Nordisk |
| Medtronic |
| Abbott |
| Sanofi |
| Merck & Co. |
| Hikma |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Continuous glucose monitor sensor miniaturization is compressing per-unit production costs while concentrating manufacturing expertise among three dominant suppliers. This technological transition simultaneously reduces patient acquisition costs and elevates barriers for second-tier device manufacturers lacking scale economies in subcutaneous sensor fabrication.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by reimbursement eligibility and clinical integration depth. Price differentiation rests on SFDA registration status and hospital procurement contract scale, with Gulf ministry networks commanding volume discounts unavailable to retail pharmacy channels. Pricing pressure stems from Indian oral hypoglycemic imports competing on metformin tablet cost structure. Home-care patients exhibit highest price sensitivity, while Saudi Ministry of Health specialist centers prioritize device reliability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with European and Indian pharmaceutical manufacturers for oral hypoglycemic active pharmaceutical ingredients. Geographic supply concentration centers on Denmark for insulin analog production, India for metformin and sulfonylurea tablets, and Ireland for continuous glucose monitor sensor arrays. Raw material dependencies include recombinant DNA substrates, electrochemical sensor membranes, and cold-chain refrigerants. Tariff exposure runs through North African import corridors dependent on Euro-denominated API sourcing. Distribution runs through Julphar's regional manufacturing hubs and Abbott's Gulf hospital direct sales networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa diabetes market functions as a regulatory compounder where SFDA device acceleration pathways and UAE mandatory chronic disease coverage are structurally expanding reimbursable demand for connected monitoring technologies.
For Market Incumbents: Acquire regulatory dossier portfolios from delayed entrants facing South African Health Products Regulatory Authority clinical evidence requirements. Consolidate distribution partnerships with Dubai retail pharmacy chains before home-care patient acquisition fragments further. Defend against telemedicine platform disintermediation by embedding software companion capabilities into continuous glucose monitor hardware subscriptions. For New Entrants and Emerging Players: Begin with telemedicine integration white space across Saudi Arabia's geographically dispersed Eastern Province populations. Target Egyptian pharmaceutical manufacturing incentives for oral hypoglycemic localization to reduce import dependency exposure. Pursue Gulf Standardization Organization conformity marking as single-registration gateway across UAE, Saudi Arabia, Kuwait, and Qatar hospital procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking established SFDA or MOHAP regulatory approvals. Long-term viability favors asset-light telemedicine platforms with app-integrated diagnostic workflows over capital-intensive insulin cold-chain logistics operators. Monitor UAE health insurance reimbursement list expansions for wearable devices as inflection signal for home-care segment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Device Registration Acceleration | Compresses market entry timelines for connected glucose monitors entering Saudi hospital procurement channels. |
| Egyptian Pharmaceutical Manufacturing Localization | Reduces currency exposure for North African markets dependent on Indian API sourcing. |
| Telemedicine Platform Development | Captures venture deployment targets for remote endocrinology consultations across dispersed Saudi populations. |
| Gulf Standardization Organization Convergence | Enables single-registration market access for glucose monitoring equipment across four Gulf health ministries. |
| Home-Care Distribution Channel Expansion | Redirects patient acquisition toward direct-to-consumer models as UAE insurance mandates cover preventive monitoring. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, biomedical engineers, formulary directors at Gulf health ministries, and regulatory affairs specialists at SFDA and MOHAP informed demand-side assumptions. Secondary validation drew from SFDA device registration databases, MOHAP reimbursement list publications, hospital procurement contract disclosures, and trade flow records for insulin and oral hypoglycemic imports. Triangulation between patient volume estimates and manufacturer shipment data anchored market sizing integrity.
Historical trendline analysis identified inflection points where UAE mandatory chronic disease coverage and Saudi specialist center expansion altered procurement patterns. Segmentation modeling spanned product type, end user, distribution channel, and technology maturity stage across the projection horizon. CAGRs derived from regression analysis against diagnosed diabetes prevalence trajectories, insurance penetration rates, and device replacement cycles. Forecast inputs incorporated SFDA approval velocity, MOHAP reimbursement schedule revisions, and cold-chain logistics capacity expansion in Eastern Province industrial zones.
Several conditions sit outside the modeled scope, including geopolitical disruption to Red Sea shipping corridors, abrupt currency devaluations in Egyptian or South African markets, and pandemic-scale public health emergencies redirecting ministry budgets. Forecasts reflect assumptions regarding regulatory pathway stability and insurance mandate enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Global Diabetic Foot Ulcer Treatment Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
BRICS Diabetes Treatment and Prevention Market
Diabetes Care
North America Continuous Glucose Monitoring Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Type-1 Diabetes Treatment Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Europe Diabetes Care Devices Market
Diabetes Care
France Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Blood Glucose Test Strip Market