
 Insulin Resistance Market | 2026-2036
Insulin Resistance Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Resistance Market Outlook
CE marking under the EU Medical Device Regulation (MDR) for glucose monitoring systems is collapsing the window for unvalidated wearable entrants, forcing recertification cycles that favor incumbents with established quality management systems. Eli Lilly and Company leverages its endocrinology manufacturing scale to anchor supply contracts with major hospital purchasing networks. Novo Nordisk competes through vertical control over active pharmaceutical ingredient production for GLP-1 receptor agonists, sustaining margin structures that newer entrants struggle to match. Sanofi differentiates via its established basal insulin portfolio and European distribution infrastructure.
Insulin resistance denotes a pathophysiological state where cellular glucose uptake becomes impaired despite elevated circulating insulin levels, quantified clinically through HOMA-IR scores or hyperinsulinemic-euglycemic clamp studies, with primary commercial purpose centered on preventing progression to type 2 diabetes and reducing cardiovascular event burden. Oral medications command the largest revenue pool within product type categories due to decades of payer familiarity and generic availability, while continuous glucose monitors represent the fastest-expanding segment as real-time metabolic data integration spreads from intensive insulin users to prediabetic monitoring protocols. Among delivery modes, wearable devices are capturing disproportionate R&D allocation as manufacturers race to merge pharmacokinetic dosing with biosensor feedback loops.
The FDA's metabolic and endocrinology division, alongside EMA's Committee for Medicinal Products for Human Use, shapes trial design requirements that extend development timelines for novel insulin sensitizers, while ISO 15197 standards for blood glucose meter accuracy create technical barriers at the device layer. India's CDSCO has tightened bioequivalence protocols for metformin formulations, redirecting generic manufacturer investment toward facility upgrades. Stakeholders must monitor how payer evidence requirements for cardiovascular outcome trials are shifting prior to formulary placement decisions for next-generation therapies.
Market Dynamics
The insulin resistance market is being fundamentally restructured by the convergence of pharmacotherapy and real-time biosensor feedback, as continuous glucose monitoring platforms migrate from intensive insulin users into prediabetic populations and reshape how metabolic disorders are managed clinically.
Growth Catalysts
- Medicare reimbursement expansion:The US Centers for Medicare and Medicaid Services has broadened coverage for continuous glucose monitoring devices to include prediabetic patients, accelerating device penetration beyond traditional insulin-dependent cohorts.
- EMA accelerated assessment pathways:The European Medicines Agency's priority medicines scheme is compressing review timelines for novel insulin sensitizers, pulling forward commercial launch windows for metabolic disorder therapies.
- Hospital purchasing network consolidation:Integrated delivery networks across the United States are centralizing formulary decisions, creating volume concentration that favors suppliers with manufacturing scale and supply chain reliability.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for GLP-1 receptor agonists remains concentrated among a limited set of European and Asian contract manufacturers, exposing the market to single-source disruption risk.
- EU MDR recertification burden:The Medical Device Regulation's tightened clinical evidence requirements for glucose monitoring systems is forcing substantial reinvestment in quality management systems, disadvantaging smaller wearable entrants.
- Cardiovascular outcome trial costs:Payer demands for hard cardiovascular endpoint data prior to formulary placement are extending development timelines and inflating clinical trial budgets for novel therapeutic candidates.
Strategic Opportunities
- Prediabetic monitoring protocols:Employer-sponsored wellness programs and primary care networks in the United States are adopting continuous glucose monitoring for metabolic screening, opening a patient population an order of magnitude larger than treated diabetes.
- India's CDSCO bioequivalence tightening:Stricter facility standards for metformin generic manufacturers are creating acquisition opportunities for compliant producers with upgraded manufacturing infrastructure.
- Pharmacokinetic-biosensor convergence:Integration of automated insulin dosing algorithms with real-time glucose data streams is enabling closed-loop therapeutic systems that command premium positioning.
Industry Challenges
- HOMA-IR standardization gaps:Variability in insulin assay methodologies across clinical laboratories complicates patient stratification and trial endpoint consistency, requiring harmonization investments.
- Legacy EMR integration friction:Continuous glucose monitor data streams face interoperability barriers with established electronic medical record architectures, demanding custom interface development.
- Specialized endocrinology workforce scarcity:Shortages of clinicians trained in advanced metabolic monitoring are constraining the clinical adoption velocity of integrated pharmacotherapy-device protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Resistance Market |
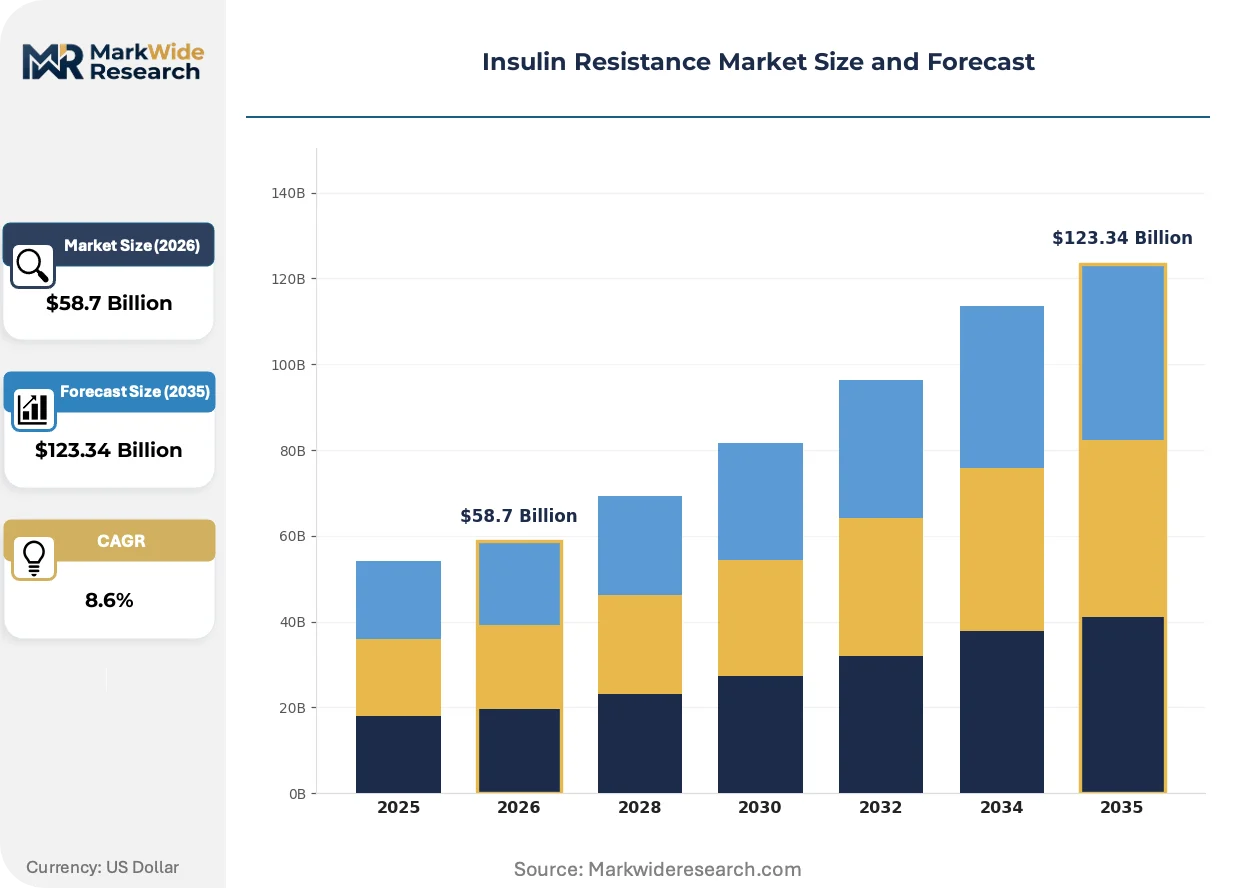
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $123.34 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Injectables, Oral Medications, Continuous Glucose Monitors, Insulin Pumps Application: Type 2 Diabetes Management, Pharmacotherapy, Weight Management, Cardiovascular Health End User: Hospitals, Clinics, Home Care Settings, Research Institutions Delivery Mode: Subcutaneous Injection, Intravenous Infusion, Oral Administration, Wearable Devices |
| Companies Covered | AstraZeneca, Novartis, Eli Lilly and Company, Viking Therapeutics, Sanofi, Novo Nordisk, Pfizer, AdipoPharma, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Resistance Market Strategic Shifts
Real-time metabolic data is becoming the central organizing principle for insulin resistance management, with sensor technology, regulatory frameworks, and care delivery models all reorienting around continuous rather than episodic monitoring paradigms.
Microneedle-based interstitial glucose sensors are miniaturizing the form factor and application burden of continuous monitoring, enabling patch-based wearables that patients apply without clinical assistance. Primary care networks in the United States are adopting these systems for prediabetic screening protocols at accelerating rates. This miniaturization is compressing the boundary between consumer wellness devices and clinical-grade diagnostics, forcing regulatory recalibration of classification thresholds.
The FDA's breakthrough device designation pathway for metabolic monitoring systems is creating expedited market access for novel biosensor platforms that demonstrate superior accuracy against ISO 15197 standards. Manufacturers are responding by prioritizing algorithm development over hardware iteration, recognizing that software-based glycemic prediction carries lower regulatory burden than novel physical sensing modalities. Prediabetic monitoring applications are attracting disproportionate development resource allocation under this framework.
Employer-sponsored health plans are unbundling continuous glucose monitoring from traditional diabetes management bundles, creating standalone reimbursement codes for metabolic wellness applications. Benefits administrators at large self-insured corporations are driving this shift, negotiating direct contracts with device manufacturers outside traditional pharmacy benefit manager channels. This channel disintermediation is most pronounced in the United States, where employer health spending concentration creates leverage for procurement innovation.
Insulin Resistance Market Segmentation
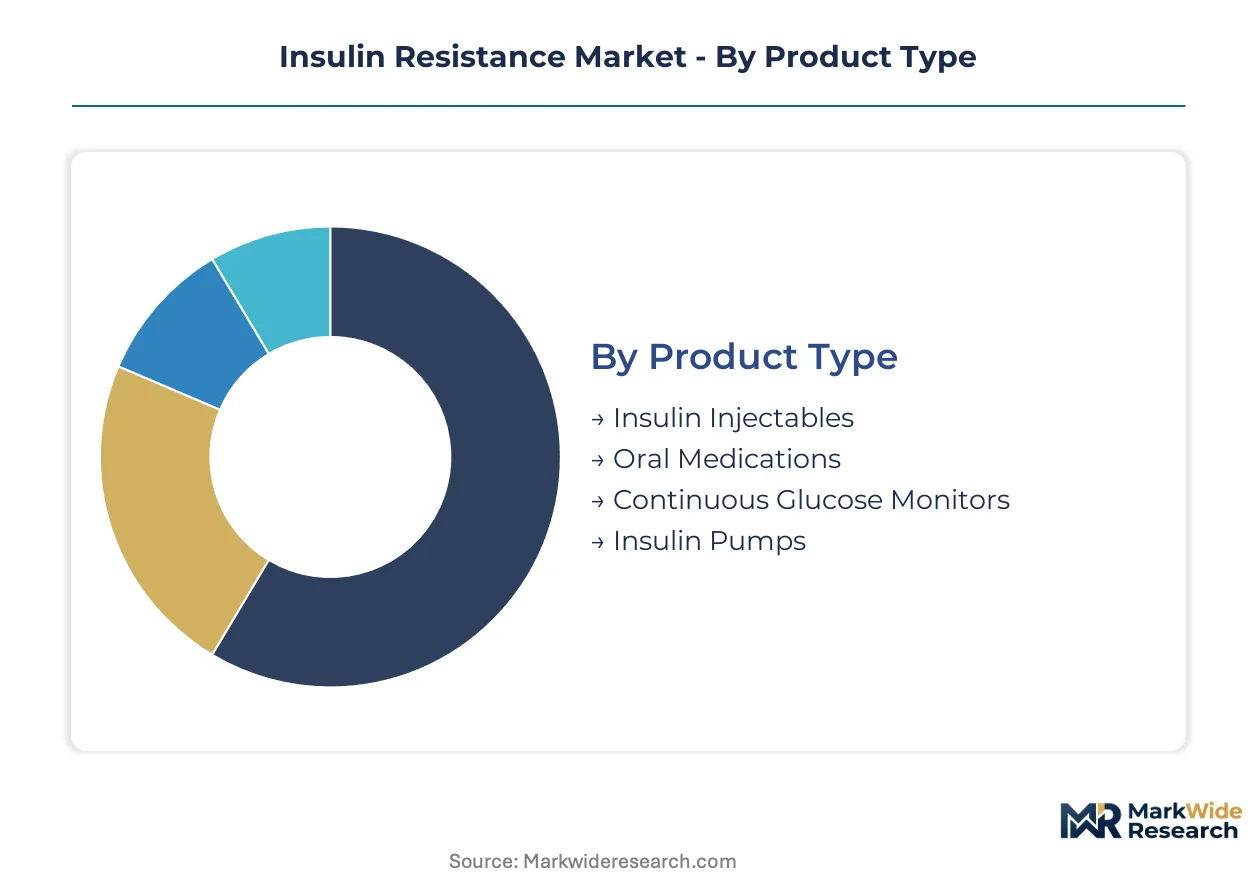
Segmentation in the insulin resistance market reveals distinct margin architectures across pharmacotherapy, device technology, and care delivery modalities. Each category carries divergent regulatory burdens and reimbursement pathways that reshape competitive positioning.
Product Type:
Margin concentration sits with device platforms integrating software algorithms, while commoditized drug categories compete on manufacturing scale.
- Continuous Glucose Monitors:Real-time interstitial glucose sensors paired with predictive analytics platforms command premium positioning through recurring software subscriptions. Demand concentrates in United States integrated care networks where Medicare reimbursement expansion for prediabetic populations pulls volumes upward, constrained by ISO 15197 accuracy validation requirements.
- Oral Medications:Metformin formulations and novel insulin sensitizers leverage decades of payer familiarity and generic availability to anchor volume share. Hospital purchasing networks in the United States centralize procurement around suppliers with demonstrated bioequivalence compliance, particularly as India's CDSCO tightens facility standards.
- Insulin Injectables:GLP-1 receptor agonists and basal insulin formulations face API supply concentration risks across European and Asian contract manufacturers.
- Insulin Pumps:Automated delivery systems with closed-loop algorithms require substantial clinical evidence investment for FDA metabolic and endocrinology division approval.
The dominant share belongs to Oral Medications, while Continuous Glucose Monitors is closing the gap fastest.
Application:
Revenue pools track patient population scale, with prediabetic protocols expanding addressable markets beyond traditional diabetes management.
- Type 2 Diabetes Management:Established therapeutic protocols for progressed metabolic disease concentrate demand in hospital systems with specialized endocrinology workforce capacity. United States formulary placement decisions increasingly require cardiovascular outcome trial data, extending development timelines for novel candidates.
- Pharmacotherapy:Preventive drug interventions for insulin-resistant populations without full diabetes diagnosis represent the steepest expansion trajectory as employer-sponsored wellness programs adopt metabolic screening. Primary care networks drive this shift through protocols integrating HOMA-IR scoring with continuous monitoring feedback.
- Weight Management:GLP-1 receptor agonist applications for obesity treatment pull device and drug volumes through overlapping metabolic pathways.
- Cardiovascular Health:Payer demands for hard endpoint data prior to reimbursement approval inflate clinical trial budgets across this indication.
Type 2 Diabetes Management retains the largest installed base, though Pharmacotherapy is expanding most quickly.
End User:
Procurement authority is shifting toward integrated delivery networks that centralize formulary decisions across multiple care settings.
- Hospitals:Acute care facilities with specialized endocrinology departments anchor high-value therapeutic protocols requiring intensive monitoring infrastructure. United States hospital purchasing network consolidation creates volume concentration favoring suppliers with manufacturing scale and supply chain reliability.
- Home Care Settings:Patient-administered monitoring and dosing systems bypass clinical facility capacity constraints, enabled by microneedle sensor miniaturization that eliminates application assistance requirements. United States employer-sponsored health plans drive this shift through standalone reimbursement codes for metabolic wellness applications.
- Clinics:Outpatient facilities face workforce scarcity constraints in advanced metabolic monitoring adoption.
- Research Institutions:Academic medical centers conduct hyperinsulinemic-euglycemic clamp studies for novel therapeutic validation.
Hospitals command the dominant procurement volume, while Home Care Settings is gaining share fastest.
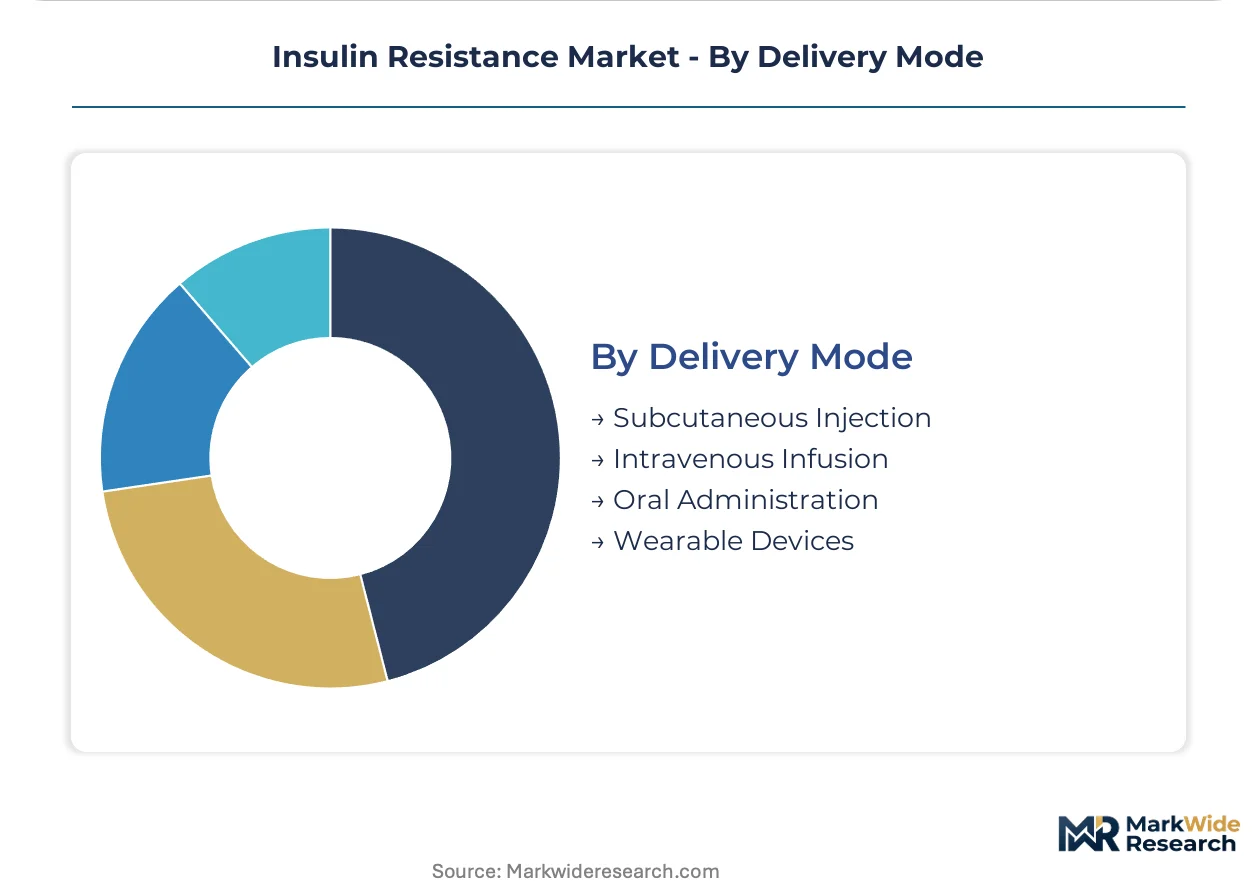
Delivery Mode:
Technology convergence between sensing and dosing is collapsing traditional modality boundaries into integrated therapeutic systems.
- Wearable Devices:Patch-based biosensors merging continuous glucose monitoring with automated insulin dosing algorithms enable closed-loop therapeutic platforms. FDA breakthrough device designation pathways accelerate market access for platforms demonstrating superior glycemic prediction accuracy against established standards.
- Subcutaneous Injection:Pen-based and pump-mediated delivery remains the standard for GLP-1 receptor agonists and basal insulin, constrained by patient adherence variability and injection burden.
- Oral Administration:First-line metformin therapy maintains volume leadership through payer familiarity and generic cost structures.
- Intravenous Infusion:Hospital-based intensive insulin protocols reserve this mode for acute metabolic decompensation requiring precise glycemic control.
Oral Administration holds the widest patient reach, though Wearable Devices is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing networks and Medicare reimbursement expansion concentrate buyer authority in the United States, while European regulatory frameworks and Asian manufacturing clusters shape supply-side positioning across metabolic disorder therapies.
United States
Integrated care networks in Texas and Florida are centralizing formulary decisions for prediabetic pharmacotherapy protocols. FDA breakthrough device designation pathways accelerate market access for novel biosensor platforms. The Minneapolis medical device cluster anchors continuous glucose monitor manufacturing scale.
Germany
EMA accelerated assessment pathways compress review timelines for insulin sensitizers targeting cardiovascular outcomes. The country's national pharmaceutical regulator enforces stringent bioequivalence standards for metformin generics. The Rhine-Ruhr pharmaceutical manufacturing belt concentrates GLP-1 receptor agonist active pharmaceutical ingredient production.
China
NMPA reform of medical device classification rules is recalibrating entry barriers for glucose monitoring systems. The country's national pharmaceutical regulator tightened bioequivalence protocols for oral hypoglycemic agents. The Yangtze River Delta medical technology corridor hosts expanding biosensor foundry capacity.
India
CDSCO facility standard upgrades for metformin manufacturers are redirecting investment toward compliant production infrastructure. The central drug regulator's tightened bioequivalence requirements favor producers with upgraded quality management systems. The Hyderabad-Visakhapatnam pharmaceutical belt anchors generic oral medication export capacity.
Japan
PMDA priority review vouchers for metabolic disorder therapies pull forward commercial launch timelines. The national pharmaceutical regulator emphasizes cardiovascular outcome data for formulary placement decisions. The Kansai region's precision manufacturing base supports miniaturized sensor component fabrication.
Insulin Resistance Market Competitive Environment
Player mix skews toward diversified pharmaceutical conglomerates with endocrinology manufacturing scale, creating tiered competitive dynamics where API supply control and hospital purchasing network contracts determine positioning. Two strategic archetypes dominate: vertically integrated API producers capturing margin through upstream control, and device-pharma convergence platforms merging biosensor feedback with automated dosing. Competitive moves center on manufacturing capacity expansion for GLP-1 agonist supply security and strategic partnerships bridging pharmacotherapy with continuous monitoring data streams.
Among diversified pharmaceutical conglomerates, Eli Lilly and Company, Novo Nordisk, and Sanofi occupy positions exemplifying distinct competitive vectors. The Indianapolis-based firm represents manufacturing scale advantages in endocrinology supply contracts. The Danish producer anchors upstream control over peptide active pharmaceutical ingredient production. The Paris-headquartered conglomerate exemplifies European distribution infrastructure leverage combined with established basal insulin portfolio breadth.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis |
| Eli Lilly and Company |
| Viking Therapeutics |
| Sanofi |
| Novo Nordisk |
| Pfizer |
| AdipoPharma |
| Boehringer Ingelheim |
| Others |
Value Chain & Pricing Dynamics
Manufacturing scale advantages in GLP-1 receptor agonist peptide synthesis anchor price floors across the insulin resistance market, concentrating margin power with incumbents commanding multi-ton active pharmaceutical ingredient capacity while forcing smaller entrants toward cost-plus contract structures indexed to raw material volatility.
Pricing Analysis
Cost-plus contracts with API feedstock indexation dominate insulin sensitizer procurement between hospital purchasing networks and generic manufacturers. Three-tier pricing structure across premium continuous glucose monitors, standard insulin pumps, and economy oral medication tiers reflects ISO 15197 certification grade and software algorithm sophistication. Pricing pressure stems from Medicare reimbursement compression for prediabetic monitoring protocols. Primary care networks exhibit highest price sensitivity, while specialized endocrinology departments tolerate premium positioning for closed-loop therapeutic systems.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Singapore port congestion elevate landed costs for European and Asian contract manufacturers supplying North American hospital networks. Active pharmaceutical ingredient production concentrates in Germany's Rhine-Ruhr belt, India's Hyderabad-Visakhapatnam corridor, and China's Yangtze River Delta. Peptide precursor chemicals, biosensor MEMS components, and lithium-ion cell materials constitute critical input dependencies. Single-source vulnerability pervades GLP-1 agonist peptide synthesis. Distribution runs through integrated delivery network central warehouses with direct-to-clinic replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulin resistance market is approaching a platform-economics inflection where pharmacotherapy-device convergence creates winner-take-most dynamics, justified by employer-sponsored health plans unbundling continuous glucose monitoring from traditional diabetes bundles and negotiating direct manufacturer contracts outside pharmacy benefit manager channels.
For Market Incumbents: Compound manufacturing scale advantages through captive peptide synthesis capacity expansion in the Rhine-Ruhr region, securing API supply against single-source disruption while consolidating hospital purchasing network contracts. Invest in FDA breakthrough device designation pathways for closed-loop algorithm platforms to preempt biosensor-feedback convergence by emerging digital health entrants. Prioritize quality management system recertification under EU MDR ahead of smaller wearable competitors.
For New Entrants and Emerging Players: Differentiate on microneedle sensor miniaturization for employer-sponsored wellness program channels, bypassing established pharmacy benefit manager gatekeepers through direct benefits administrator contracting. Target prediabetic monitoring protocols in United States primary care networks as the most penetrable application, where HOMA-IR scoring integration with real-time feedback lacks incumbent saturation. Pursue strategic partnerships with continuous glucose monitor data platforms for algorithm development leverage.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device platforms with software subscription components, positioning continuous glucose monitor manufacturers with predictive analytics capabilities for superior cash flow quality versus commodity oral medication producers. Five-to-ten year viability favors vertically integrated API producers with hospital network contract concentration. Acquisition target archetype: compliant metformin generic manufacturers with upgraded CDSCO-certified facilities in India. Signal to watch: employer health plan standalone reimbursement code expansion for metabolic wellness applications.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification under ISO 15197 accuracy standards collapses entry windows for unvalidated wearable competitors. |
| Hospital System Partnership | Integrated delivery network formulary centralization in Texas and Florida concentrates procurement volume with scale suppliers. |
| Software Companion Development | Algorithm-based glycemic prediction carries lower FDA regulatory burden than novel physical sensing modalities. |
| Reimbursement Strategy | Medicare coverage expansion for prediabetic continuous glucose monitoring pulls device volumes beyond insulin-dependent cohorts. |
| Manufacturing Scale-Up | Multi-ton peptide API capacity in the Rhine-Ruhr belt secures margin structures against supply concentration risk. |
Study Parameters
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings across this study. Primary interviews with formulary directors, endocrinology department heads, medical device regulatory affairs leads, and GPO contracts managers combined with secondary validation through FDA 510(k) submissions, EMA assessment reports, CMS Medicare reimbursement determinations, and ISO 15197 certification records. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation frame volume estimation.
Sensitivity analysis around Medicare reimbursement policy shifts and API supply disruption scenarios stress-tests projection robustness across the analysis window. Segmentation dimensions include product type, application, end user, and delivery mode, with regional regulatory cluster differentiation. CAGRs derive from patient population epidemiology, pricing trajectory assumptions, and technology penetration curves. Forecast inputs incorporate continuous glucose monitor accuracy validation timelines and cardiovascular outcome trial completion patterns.
Decision-makers should treat outputs as directional under base assumptions of stable Medicare reimbursement expansion and sustained GLP-1 agonist demand growth; material deviation in employer-sponsored wellness program adoption or API supply disruption would warrant model refresh. Forecasts reflect documented assumptions regarding regulatory pathway timelines and hospital purchasing network consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Middle-East and Africa Blood Glucose Monitoring Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Pet Diabetes Care Devices Market
Diabetes Care
Diabetic Pen Cap Market
Diabetes Care
SGLT2 Inhibitors Treatment Market
Diabetes Care
Diabetic Footwear Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Japan Insulin Infusion Pump Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Global Diabetic Retinopathy Market
Diabetes Care
Germany Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Middle East and Africa Diabetes Pen Market