
 New Zealand Self-Monitoring Blood Glucose Market | 2026-2036
New Zealand Self-Monitoring Blood Glucose Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Self-Monitoring Blood Glucose Market Foresight
Medsafe New Zealand's updated IVD conformity assessment pathways is pivoting the cost-of-entry calculus for glucose monitoring suppliers seeking market authorization. Abbott Diabetes Care leverages its integrated flash monitoring ecosystem to sustain premium positioning across hospital and retail channels. Roche Diabetes Care anchors its presence through deep pharmacy partnerships and specialized diabetes educator networks. LifeScan Inc. competes on brand recognition and reimbursement familiarity among general practitioners.
Self-monitoring blood glucose encompasses portable electrochemical biosensor systems, typically employing glucose oxidase or hexokinase reactions on disposable test strips with measurement ranges of 20 to 600 mg/dL, designed to enable real-time metabolic tracking by diabetic individuals outside clinical settings. Test strips constitute the dominant recurring revenue pool given their consumable nature and reimbursement anchoring through Pharmac schedules, while continuous glucose monitoring systems represent the fastest-expanding technology segment as sensor accuracy improves and user calibration requirements diminish. Smart devices integrating cellular connectivity and automated data sharing with clinicians are capturing margin pools from standard meter categories.
Medsafe governs device safety and performance standards under the Medicines Act 1981 and Medical Devices Regulations 2023, while Pharmac determines public funding eligibility that directly shapes patient access and manufacturer volume commitments. Standards New Zealand adopts ISO 15197 for meter accuracy, creating a dual-compliance burden that favors established players with dedicated regulatory affairs capacity. Stakeholders must monitor Pharmac's specialty device procurement reviews and the pace of continuous monitoring reimbursement expansion to anticipate portfolio reallocation requirements.
Market Dynamics
Pharmac's specialty device procurement reviews are compressing margin pools for standard meter suppliers while accelerating continuous glucose monitoring reimbursement expansion across Auckland's metropolitan health corridors.
Growth Catalysts
- Continuous glucose monitoring reimbursement:Pharmac's expanding coverage for sensor-based systems is pulling patients away from traditional fingerstick monitoring toward automated metabolic tracking.
- Medsafe's IVD conformity pathways:The Medical Devices Regulations 2023 create clearer post-market surveillance frameworks that reward established suppliers with dedicated regulatory affairs capacity.
- Diabetes educator networks:Specialized educator channels in Wellington and Christchurch are driving protocol adoption for connected monitoring devices among newly diagnosed patients.
Market Restraints
- Test strip cost structure:The consumable-dominant revenue model locks suppliers into Pharmac pricing schedules that limit premium positioning flexibility.
- Supply concentration risk:Electrochemical biosensor manufacturing concentrates among a narrow base of Asian component suppliers, exposing distributors to input volatility.
- ISO 15197 dual-compliance burden:Standards New Zealand's adoption of international accuracy requirements alongside Medsafe's parallel assessment creates redundant certification timelines.
Strategic Opportunities
- Underpenetrated South Island corridors:Rural Canterbury and Otago regions show lagging continuous monitoring penetration relative to Auckland's saturation levels.
- Cellular-enabled smart device convergence:Integration of automated clinician data sharing with cloud-based metabolic analytics opens subscription revenue streams beyond hardware sales.
- Pharmacy network digitalization:Community pharmacy chains are piloting remote patient monitoring hubs that could displace traditional clinic-based device dispensing.
Industry Challenges
- Calibration-free sensor engineering:Manufacturers face compressed R&D timelines to eliminate user calibration requirements while maintaining ISO 15197 accuracy thresholds.
- Interoperability with legacy electronic health records:Hospital procurement committees demand seamless data integration with existing patient management systems, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Self-Monitoring Blood Glucose Market |
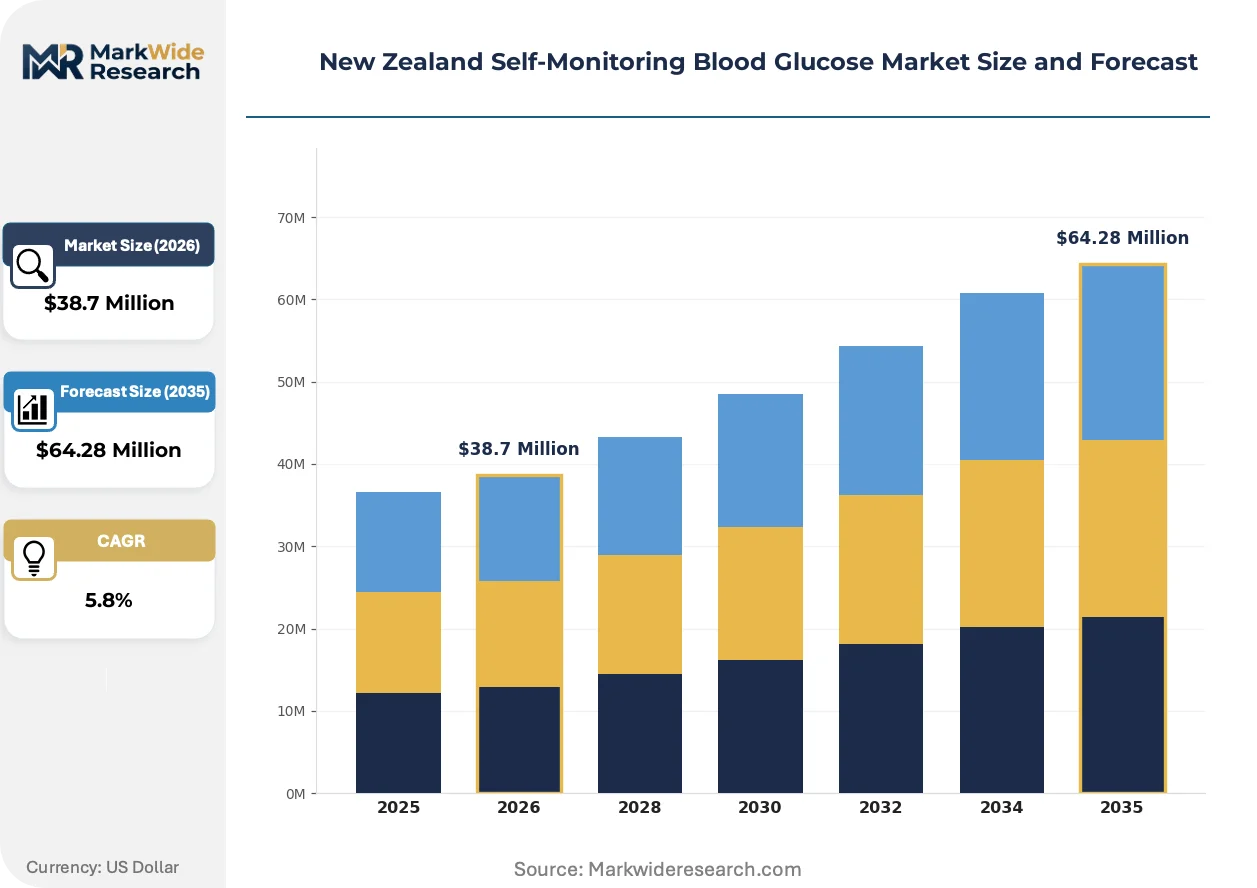
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Test Strips, Lancing Devices, Software End User: Diabetic Patients, Healthcare Professionals, Home Users, Clinics Distribution Channel: Pharmacies, Online Stores, Hospitals, Supermarkets Technology: Continuous Glucose Monitoring, Flash Glucose Monitoring, Standard Meters, Smart Devices |
| Companies Covered | Abbott Diabetes Care, Roche Diabetes Care, LifeScan Inc., Ascensia Diabetes Care, i-SENS, Inc., Trividia Health, Acon Laboratories, Medtronic, Dexcom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Self-Monitoring Blood Glucose Market Shifts & Advancements
Sensor accuracy improvements and diminishing calibration requirements are compressing the technology gap between continuous monitoring and traditional self-monitoring blood glucose systems.
Factory-calibrated glucose oxidase sensors are rewriting competitive positioning across New Zealand's diabetes care landscape. Endocrinology clinics in Auckland's metropolitan corridors are adopting these systems at accelerating pace. The technology is rewriting margin structures by shifting revenue from consumable test strips toward durable hardware-plus-subscription models.
Medsafe's Medical Devices Regulations 2023 are tightening post-market surveillance requirements for in-vitro diagnostic devices. Manufacturers must now maintain active safety monitoring systems that report adverse events within compressed timelines. The hospital channel faces the steepest compliance burden, driving procurement committees toward suppliers with established regulatory affairs infrastructure.
Patient data-sharing preferences are shifting toward automated clinician transmission without manual logging intervention. Pharmacy-based diabetes educator networks are displacing traditional general practitioner-mediated device selection in Wellington and Christchurch. This behavioral pivot is most visible among working-age Type 1 diabetes patients managing insulin therapy through smartphone-integrated systems.
New Zealand Self-Monitoring Blood Glucose Market Segmentation
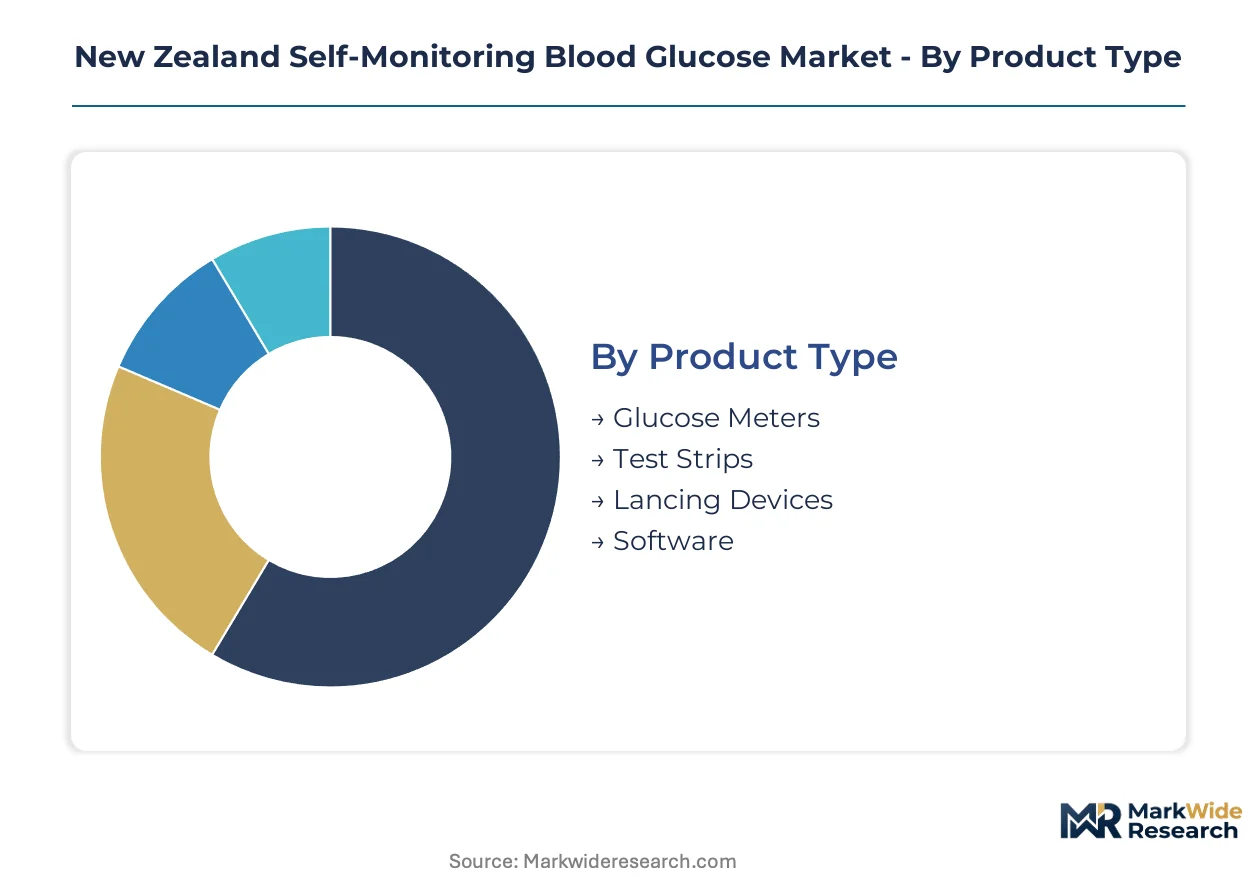
Segmentation in New Zealand's self-monitoring blood glucose market reveals how reimbursement pathways and patient preferences fragment across device categories. Pharmac's funding schedules and Medsafe's regulatory tiers create distinct commercial zones that manufacturers must navigate separately.
Product Type:
The customization-to-standardization spectrum runs from disposable consumables with fixed specifications to integrated systems requiring patient-specific calibration protocols.
- Glucose Meters:Portable electrochemical biosensor units employing glucose oxidase reactions, typically measuring 20-600 mg/dL. Demand clusters in Auckland's pharmacy networks where Pharmac-subsidized units dominate patient acquisition decisions. Hospital procurement committees favor units with ISO 15197 certification and automated data logging.
- Test Strips:Disposable biosensor strips utilizing glucose oxidase or hexokinase chemistry on electrochemical substrates. These consumables anchor recurring revenue pools through Pharmac reimbursement schedules, with volume commitments concentrated among major pharmacy chains in Wellington and Christchurch corridors.
- Lancing Devices:Spring-loaded puncture mechanisms for capillary blood sampling. Standardized designs with adjustable depth settings serve cost-sensitive home users across rural Canterbury.
- Software:Cloud-based metabolic analytics platforms with clinician dashboard integration. Adoption accelerates among Auckland endocrinology clinics pursuing remote patient monitoring protocols.
Leading the category by volume: Test Strips. Growing fastest: Software.
End User:
Cost tier stratification separates publicly funded patient populations from private-pay professional segments with distinct procurement authority.
- Diabetic Patients:Individual users managing Type 1 or Type 2 diabetes through self-directed monitoring protocols. Wellington's diabetes educator networks are pulling this segment toward connected devices with automated clinician data sharing.
- Healthcare Professionals:Endocrinologists, diabetes educators, and general practitioners prescribing or recommending device selection. Auckland metropolitan clinics concentrate demand for calibration-free sensor systems with EHR interoperability.
- Home Users:Patients or caregivers performing monitoring outside clinical supervision. Rural Otago shows lagging penetration relative to urban corridors, creating expansion opportunities for pharmacy-delivered education programs.
- Clinics:Outpatient facilities and community health centers managing device dispensing and patient training. Procurement prioritizes Medsafe-registered systems with established adverse event reporting infrastructure.
Dominant by patient count: Diabetic Patients. Steepest expansion trajectory: Healthcare Professionals.
Distribution Channel:
Geographic concentration of diabetes educator expertise determines channel effectiveness across New Zealand's North-South island divide.
- Pharmacies:Community pharmacy chains with certified diabetes educators on staff. These networks in Christchurch and Wellington are piloting remote patient monitoring hubs that displace traditional clinic-based dispensing.
- Online Stores:Direct-to-consumer platforms for private-pay devices and accessories. Regulatory complexity limits this channel to non-subsidized premium products outside Pharmac schedules.
- Hospitals:Acute care and outpatient facilities with procurement committees demanding seamless EHR integration. Compliance burden under Medical Devices Regulations 2023 favors established suppliers with dedicated regulatory affairs capacity.
- Supermarkets:Mass retail channels for basic meter kits and consumable refills. Price compression from Pharmac reimbursement limits premium positioning in this channel.
Highest transaction volume: Pharmacies. Gaining share fastest: Online Stores.
Technology:
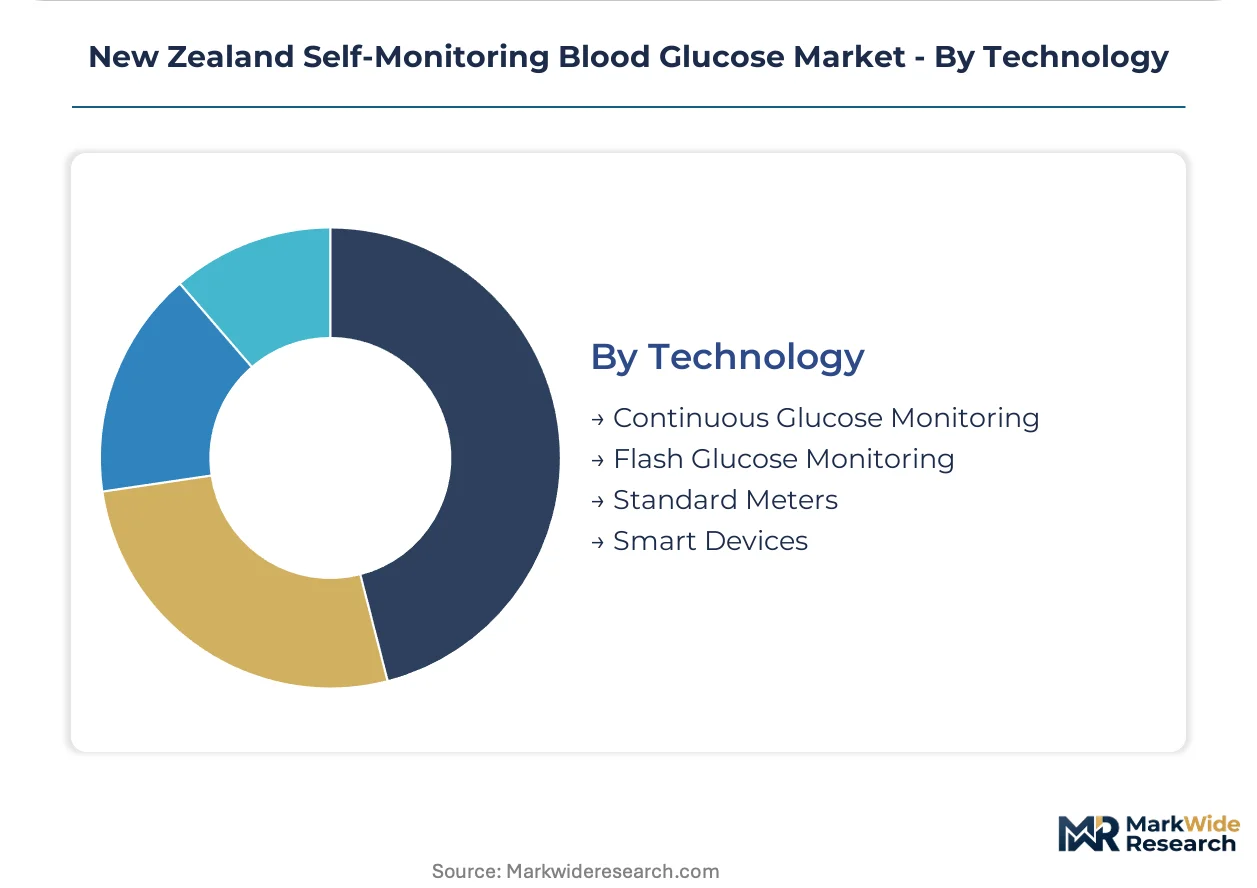
Maturity gradients separate legacy fingerstick systems from emerging sensor platforms with diminishing calibration requirements.
- Continuous Glucose Monitoring:Factory-calibrated sensor systems transmitting real-time glucose data to receivers or smartphones. Pharmac's expanding reimbursement coverage is accelerating adoption across Auckland's metropolitan health corridors.
- Flash Glucose Monitoring:Intermittent scan-based sensor systems eliminating routine fingerstick requirements. Abbott Diabetes Care's integrated ecosystem sustains premium positioning through this technology in hospital and retail channels.
- Standard Meters:Conventional electrochemical biosensors requiring fingerstick blood samples and manual test strip insertion. Pharmac pricing schedules compress margins for suppliers dependent on this mature technology category.
- Smart Devices:Cellular-enabled meters with automated clinician data sharing and cloud analytics. Subscription revenue models are displacing hardware-plus-consumable economics among working-age Type 1 patients.
Dominant by installed base: Standard Meters. Climbing the fastest: Continuous Glucose Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Auckland's health technology corridor concentrate glucose monitoring distribution infrastructure alongside Medsafe-registered warehousing facilities.
Auckland Metropolitan Health Corridors
Endocrinology clinics and pharmacy networks cluster along Auckland's northern and central health corridors, driving concentrated demand for connected monitoring devices. Pharmac's reimbursement schedules anchor patient access decisions across this zone. Medsafe's post-market surveillance requirements favor established suppliers with dedicated regulatory affairs capacity in these corridors.
Wellington Diabetes Educator Networks
Specialized educator channels in Wellington are pulling newly diagnosed patients toward automated data-sharing protocols. The country's national pharmaceutical regulator maintains active safety monitoring systems reporting adverse events within compressed timelines. Community health centers in the Greater Wellington region prioritize Medsafe-registered systems with established compliance infrastructure.
Christchurch Pharmacy Hubs
Certified diabetes educators on staff at community pharmacy chains are piloting remote patient monitoring programs. Pharmac's specialty device procurement reviews shape volume commitments among major pharmacy networks. The Canterbury region shows accelerating continuous monitoring penetration relative to rural South Island corridors.
Rural Canterbury and Otago
Underpenetrated rural corridors show lagging continuous monitoring adoption compared to Auckland saturation levels. Pharmacy-delivered education programs are expanding device access outside metropolitan supervision. Farm-based Type 2 diabetes patients in these regions remain anchored to traditional fingerstick monitoring protocols.
North Island Secondary Cities
Hamilton and Tauranga health networks are replicating Auckland's connected device adoption patterns at compressed scale. Regional procurement committees demand seamless electronic health record integration extending sales cycles. These corridors represent expansion targets for cellular-enabled smart device subscription models.
New Zealand Self-Monitoring Blood Glucose Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across New Zealand's glucose monitoring sector, creating a tiered structure where regulatory capacity separates sustainable participants from marginal operators. The market consolidates around suppliers with established Medsafe registration histories and Pharmac reimbursement familiarity. Three archetypes dominate: integrated flash monitoring ecosystems, deep pharmacy partnership networks, and brand-recognition-dependent general practitioner channels. Competitive moves concentrate on portfolio diversification toward continuous monitoring and strategic partnerships with diabetes educator networks.
Among the integrated ecosystem tier, Abbott Diabetes Care and Roche Diabetes Care occupy positions that exemplify contrasting channel strategies—hospital-retail convergence versus pharmacy-educator anchoring—while LifeScan Inc. represents the brand-recognition archetype competing on reimbursement familiarity among primary care prescribers.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Roche Diabetes Care |
| LifeScan Inc. |
| Ascensia Diabetes Care |
| i-SENS, Inc. |
| Trividia Health |
| Acon Laboratories |
| Medtronic |
| Dexcom |
| Others |
Supply & Pricing Matrix
Certified diabetes educator concentrations in Auckland's metropolitan health corridors create labor-cost differentials that widen pricing-tier spreads between premium calibration-free sensor systems and standard fingerstick meters.
Pricing Analysis
Short lead-time premiums apply to continuous glucose monitoring sensors with factory-calibrated glucose oxidase chemistry, while spot inventory of standard test strips trades at compressed margins. The dominant pricing structure runs subscription-based for hardware-plus-software bundles versus per-unit transactional for disposable consumables. Price differentiation hinges on ISO 15197 certification tier and after-sales educator support bundling. Cost compression in the standard meter tier is intensifying because Pharmac's pricing schedules lock suppliers into fixed reimbursement bands. Home users in rural Canterbury show highest price sensitivity, while Auckland endocrinology clinics demonstrate lowest sensitivity given bundled procurement budgets.
Supply Chain Analysis
Workforce availability for electrochemical biosensor manufacturing concentrates in South Korea, Taiwan, and coastal China, where specialized cleanroom technicians command wage premiums. Raw material dependencies span glucose oxidase enzyme substrates, palladium electrode coatings, and medical-grade polymer casings. Single-source vulnerability from Asian component suppliers exposes distributors to input volatility when Medsafe tightens post-market surveillance documentation requirements. Distribution runs through pharmacy chains with certified educator staff, supplemented by hospital procurement committees demanding seamless electronic health record integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
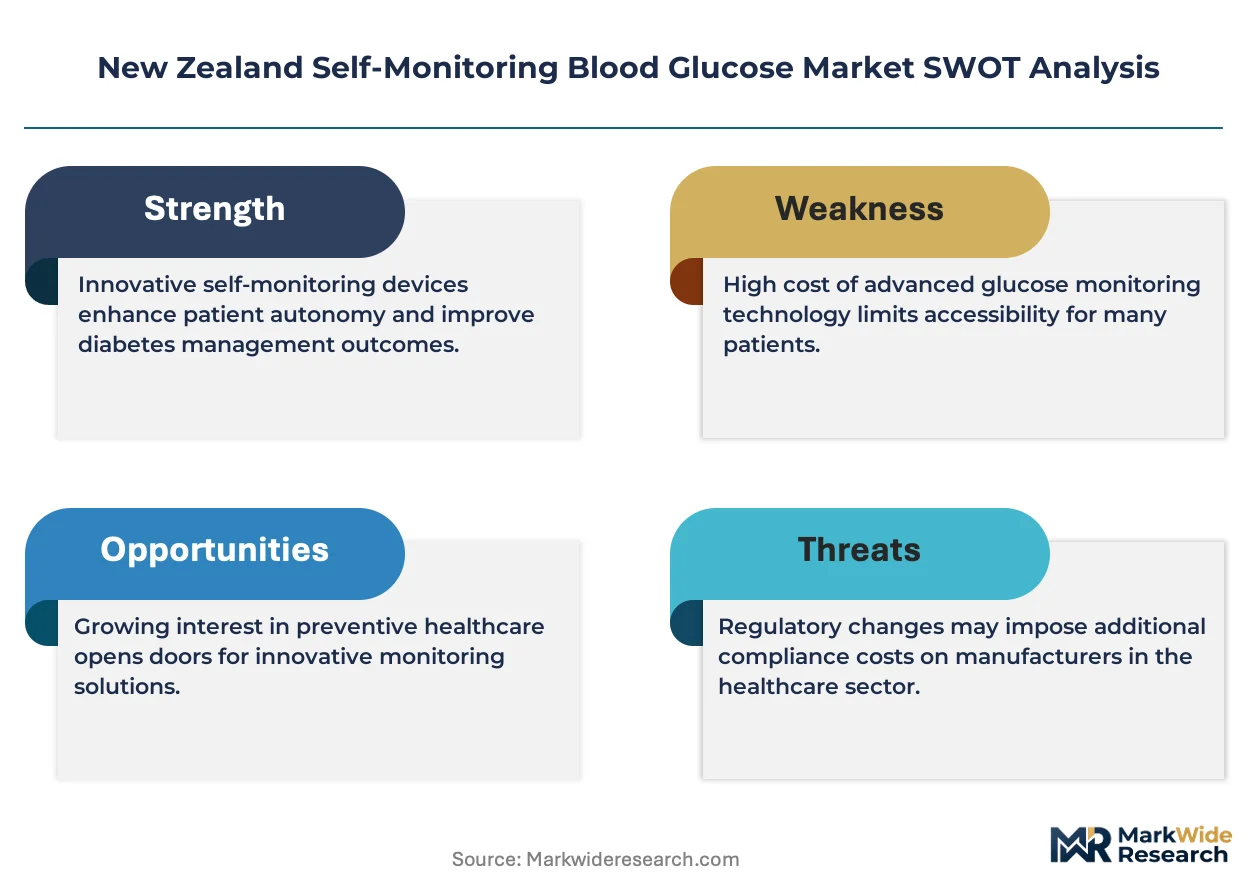
New Zealand's self-monitoring blood glucose market functions as a cost-of-compliance story where Medsafe's Medical Devices Regulations 2023 erect barrier-to-entry moats favoring suppliers with established regulatory affairs infrastructure and Pharmac reimbursement familiarity.
For Market Incumbents: To counter continuous glucose monitoring reimbursement expansion pulling patients from traditional fingerstick systems, deepen backward integration into sensor calibration technology and secure exclusive pharmacy educator network partnerships in Wellington and Christchurch corridors. For New Entrants and Emerging Players: Factory-calibrated sensor platforms with eliminated user calibration requirements offer the most penetrable wedge into underpenetrated rural Canterbury and Otago regions where continuous monitoring adoption lags Auckland saturation levels; pursue pharmacy-delivered education programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regulatory-affairs-capable mid-tier suppliers given Pharmac's expanding continuous monitoring coverage; over the medium-term horizon, target acquisition archetypes combining ISO 15197 certification with established Medsafe adverse event reporting infrastructure. Watch Pharmac's specialty device procurement review timelines as the critical inflection signal for portfolio reallocation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Medsafe Registration Pathway Investment | Dedicated regulatory affairs capacity accelerates market authorization under Medical Devices Regulations 2023. |
| Pharmacy Educator Network Partnership | Certified diabetes educator channels in Christchurch and Wellington displace traditional clinic-based dispensing. |
| Calibration-Free Sensor Development | Factory-calibrated glucose oxidase systems eliminate user intervention while maintaining ISO 15197 accuracy thresholds. |
| Electronic Health Record Integration | Seamless data connectivity with hospital patient management systems extends procurement committee approval cycles. |
| Cellular-Enabled Smart Device Launch | Automated clinician data sharing captures subscription revenue from working-age Type 1 diabetes patients. |
Research Methodology
Document review covered Medsafe registration databases, Pharmac reimbursement schedules, and ISO 15197 certification records, complemented by interviews with endocrinologists, hospital procurement managers, pharmacy chain diabetes educators, and biomedical engineers. Secondary validation drew from Medical Devices Regulations 2023 guidance documents, Standards New Zealand adoption protocols, and GPO contract repositories. Bottom-up patient population estimates triangulated against top-down device shipment data across the analysis window.
Market sizing outputs segmented across product type, end user, distribution channel, and technology maturity tiers throughout the forecast period. CAGRs derived from regression analysis of historical reimbursement expansion patterns and sensor accuracy improvement curves. Modeled inputs incorporated Pharmac specialty device procurement review timelines and continuous glucose monitoring coverage expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Medsafe post-market surveillance enforcement intensity and Asian component supplier disruption scenarios. Assumptions reflect current regulatory frameworks and reimbursement schedules. Material deviation in Pharmac coverage decisions or ISO 15197 accuracy standard revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Asia Pacific Diabetes Drug Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Asia Pacific Diabetes Pen Market
Diabetes Care
Mexico Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
South Korea Insulin Infusion Pump Market
Diabetes Care
Canada Self-Monitoring Blood Glucose Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market