
 Egypt Diabetes Care Devices Market | 2026-2036
Egypt Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Diabetes Care Devices Market Foresight
The Egypt diabetes care devices market is recalibrating around a widening gap between premium continuous glucose monitoring systems and basic glucose meters priced for mass subsidy programs. Novo Nordisk A/S leverages its long-standing insulin franchise to bundle delivery devices with therapy portfolios across Egyptian hospital networks. Sanofi S.A. competes through localized distribution partnerships that sustain pharmacy shelf presence in secondary cities. Abbott Diabetes Care anchors the premium tier with factory-calibrated sensor technology that reduces clinician intervention requirements.
Diabetes care devices encompass instruments for glucose surveillance, insulin delivery, and metabolic data management, typically incorporating electrochemical sensors, micro-pump mechanisms, or Bluetooth-enabled transmitters operating within narrow biological tolerance bands. Their commercial purpose centers on enabling glycemic control outside clinical settings while reducing long-term complication burdens on national health systems. Continuous glucose monitors lead device-type growth as Egyptian endocrinology departments expand remote patient monitoring programs. Wearable technology within the technology segment captures disproportionate investment from private diagnostics centers seeking differentiation. Retail pharmacies dominate distribution channels, though online stores represent the fastest-expanding route as Cairo-based telehealth platforms integrate device fulfillment.
Egypt's Ministry of Health and Population oversees device registration through the Egyptian Drug Authority, while the country's national health insurance authority determines reimbursement tiers that directly shape patient access to advanced systems. Compliance with ISO 15197 standards for glucose meter accuracy remains mandatory for market authorization, filtering out uncertified imports from regional gray markets. Stakeholders must monitor how Egypt's local manufacturing incentives under pharmaceutical sector development plans reshape procurement preferences for domestically assembled devices.
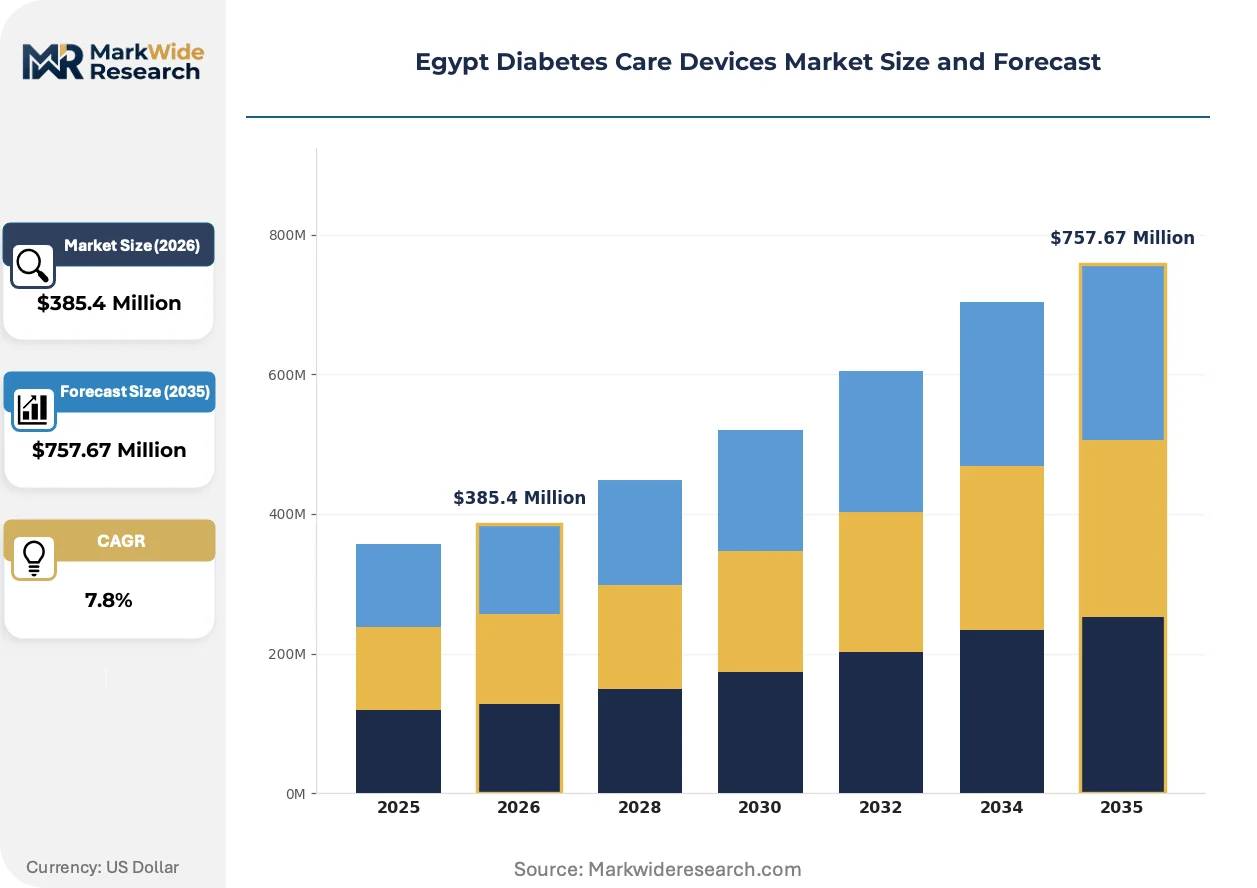
Market Dynamics
Egypt's diabetes care devices market is recalibrating around the Egyptian Drug Authority's accelerated registration pathways for locally assembled glucose meters, which is compressing import dependency while fragmenting competitive tiers between subsidized basic units and premium continuous monitoring systems.
Growth Catalysts
- Universal Health Insurance Authority reimbursement expansion:The national chronic disease program now covers glucose test strips for Type 2 patients in Greater Cairo and Alexandria, expanding addressable patient pools beyond private-pay segments.
- Telehealth platform integration:Cairo-based digital health providers are bundling device fulfillment with remote endocrinology consultations, creating new prescription-to-delivery channels for insulin pens and continuous monitors.
- Factory-calibrated sensor technology:Electrochemical sensors requiring no fingerstick calibration are reducing clinical intervention burdens and enabling home-based glycemic management without routine hospital visits.
Market Restraints
- Import concentration for premium continuous monitors:Sensor manufacturing remains concentrated in Western European and North American supply bases, exposing Egyptian distributors to currency volatility and extended lead times.
- ISO 15197 compliance costs:Mandatory accuracy certification for glucose meters filters out uncertified regional imports but raises barriers for domestic assemblers seeking market authorization.
- Basic meter substitution pressure:Subsidized conventional glucometers under national health programs limit patient willingness to self-fund premium continuous monitoring upgrades.
Strategic Opportunities
- Secondary city pharmacy networks:Alexandria and Mansoura present underpenetrated distribution nodes where localized partnerships can establish device shelf presence ahead of hospital network expansion.
- Bluetooth-enabled transmitter convergence:Integration of electrochemical sensors with smartphone data platforms is opening remote patient monitoring contracts with private diagnostic chains seeking differentiation.
- Domestic assembly incentives:Pharmaceutical sector development plans include local manufacturing preferences that reshape procurement criteria for hospital tenders and ministry supply contracts.
Industry Challenges
- Biomedical engineering talent scarcity:Electrochemical sensor calibration and micro-pump mechanism maintenance require specialized technicians that Egyptian technical institutes currently underproduce.
- Multi-stakeholder integration complexity:Aligning Egyptian Drug Authority registration timelines with Universal Health Insurance Authority reimbursement approvals delays product commercialization by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Diabetes Care Devices Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insulin Pumps, Glucose Meters, Continuous Glucose Monitors, Lancets End User: Hospitals, Clinics, Home Care, Diagnostics Centers Distribution Channel: Retail Pharmacies, Online Stores, Hospital Pharmacies, Wholesalers Technology: Smart Devices, Wearable Technology, Mobile Applications, Cloud Solutions |
| Companies Covered | Novo Nordisk A/S, Sanofi S.A., Abbott Diabetes Care, Dexcom, Inc., Omnipod, Medtronic PLC, Eli Lilly and Company, Egyptian German Insulin Company, Roche Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Diabetes Care Devices Market Shifts & Advancements
Continuous glucose monitoring architecture is consolidating around factory-calibrated systems that eliminate manual intervention, while regulatory pathways and distribution channels undergo parallel compression to match patient demand for home-based diabetes management.
Factory-calibrated continuous glucose monitors eliminate fingerstick calibration requirements through stable electrochemical sensor chemistry. Egyptian private diagnostic centers are adopting these systems at accelerated rates to differentiate their remote monitoring offerings. This technology is consolidating the premium tier around systems that reduce clinician labor while compressing basic meter margins in urban markets.
Egyptian Drug Authority registration pathways now prioritize ISO 15197-certified devices with documented local assembly plans. This regulatory pressure is fragmenting import flows between premium uncertified channels and subsidized domestic supply lines. Hospital procurement departments in Greater Cairo are responding by bifurcating tenders into certified basic units and premium continuous monitoring contracts.
Retail pharmacy dominance is yielding to integrated telehealth fulfillment as Cairo-based platforms embed device logistics within subscription care models. Secondary cities remain pharmacy-dependent, but urban patients increasingly expect same-day sensor delivery coordinated with virtual endocrinology consultations. This channel rotation is most visible in Greater Cairo, where hospital network referrals now route through digital health platforms rather than standalone retail counters.
Egypt Diabetes Care Devices Market Segmentation
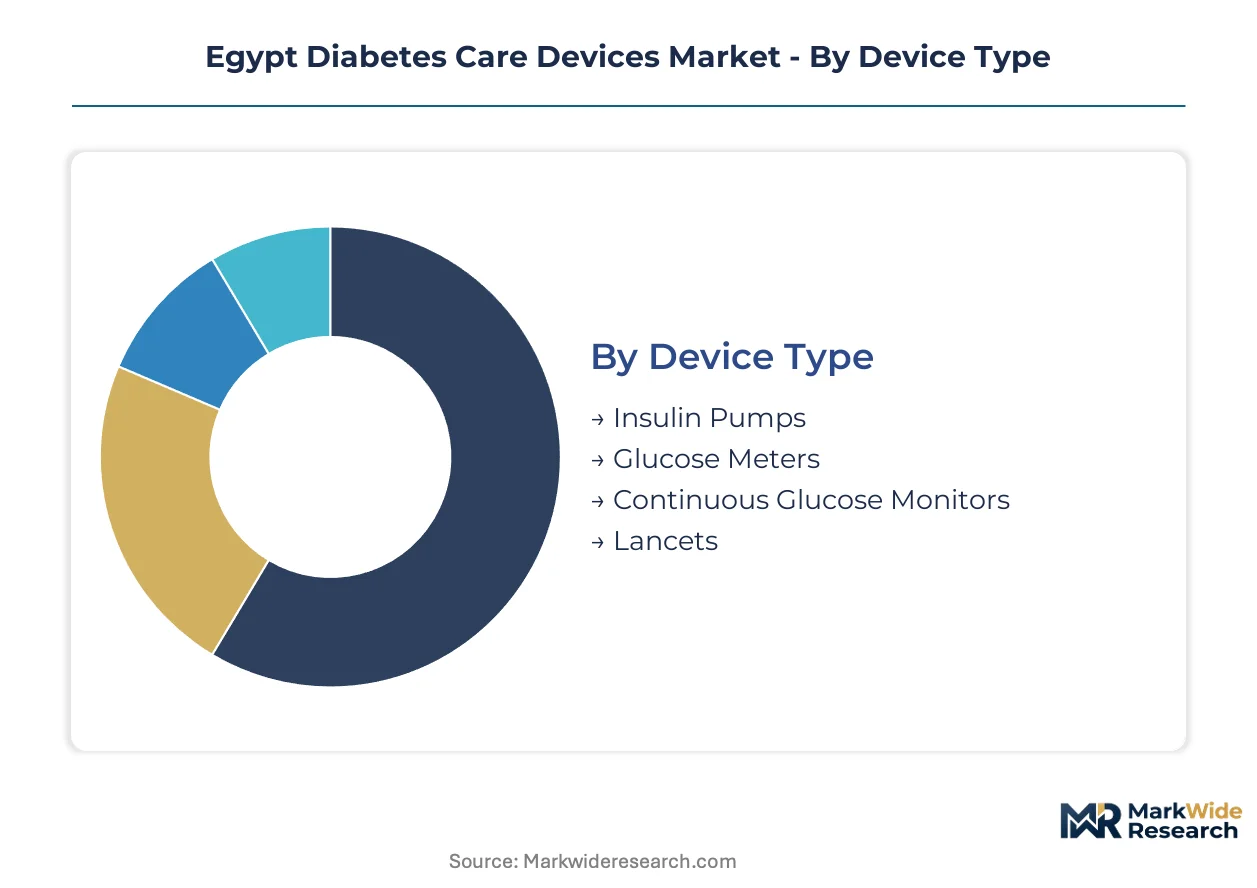
Segmentation in Egypt's diabetes care devices market reveals distinct procurement patterns across device sophistication levels and care settings. Understanding these divides enables suppliers to align registration strategies with Egyptian Drug Authority pathways and Universal Health Insurance Authority reimbursement tiers.
Device Type:
Capital intensity varies sharply across device categories, with sensor manufacturing and micro-pump assembly demanding the heaviest upfront investment in cleanroom infrastructure and calibration systems.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors eliminate fingerstick requirements through stable chemistry. Demand concentrates in Greater Cairo private diagnostic centers seeking remote monitoring differentiation, though import dependency exposes distributors to currency volatility.
- Insulin Pumps:Micro-pump mechanisms with Bluetooth-enabled dose tracking enable precise basal-bolus delivery. Procurement clusters in Alexandria hospital networks expanding endocrinology departments, constrained by biomedical engineering talent scarcity for maintenance protocols.
- Glucose Meters:ISO 15197-certified electrochemical strips dominate subsidized procurement under national chronic disease programs.
- Lancets:Single-use penetration devices represent the lowest-margin, highest-volume consumable category.
Continuous glucose monitors absorb the bulk of installed capacity; continuous glucose monitors are expanding most quickly as telehealth platforms integrate sensor fulfillment.
End User:
Customer concentration patterns reveal where procurement authority sits and how reimbursement flows shape device selection criteria across Egypt's healthcare hierarchy.
- Home Care:Urban Egyptian households managing Type 2 diabetes drive demand for simplified, factory-calibrated systems. Adoption accelerates in Greater Cairo where telehealth platforms bundle device delivery with virtual endocrinology consultations.
- Diagnostics Centers:Private chains in Alexandria and Mansoura seek wearable technology differentiation for remote patient monitoring contracts. These facilities prioritize Bluetooth-enabled transmitters that reduce clinician labor while capturing recurring sensor revenue.
- Hospitals:Greater Cairo hospital networks anchor premium device procurement through tender processes bifurcated between certified basic units and continuous monitoring contracts.
- Clinics:Secondary city outpatient facilities remain dependent on subsidized glucose meters with limited upgrade pathways.
Home care captures the deepest volume penetration; diagnostics centers are climbing the fastest as private chains expand remote monitoring capabilities.
Distribution Channel:
Channel economics determine margin retention and patient access speed, with digital platforms disrupting traditional pharmacy dominance in urban corridors.
- Online Stores:Cairo-based telehealth platforms embed device logistics within subscription care models, enabling same-day sensor delivery coordinated with virtual consultations. This channel is gaining share fastest where hospital network referrals route through digital health platforms.
- Retail Pharmacies:Dominant in secondary cities including Mansoura, where localized partnerships sustain shelf presence for insulin pens and test strips ahead of hospital network expansion.
- Hospital Pharmacies:Captive procurement channels within Greater Cairo and Alexandria hospital networks, aligned with tender-based continuous monitor contracts.
- Wholesalers:Traditional distribution backbone for subsidized glucose meter supply into ministry programs.
Retail pharmacies retain the widest geographic coverage; online stores are gaining share fastest as urban patients expect integrated fulfillment.
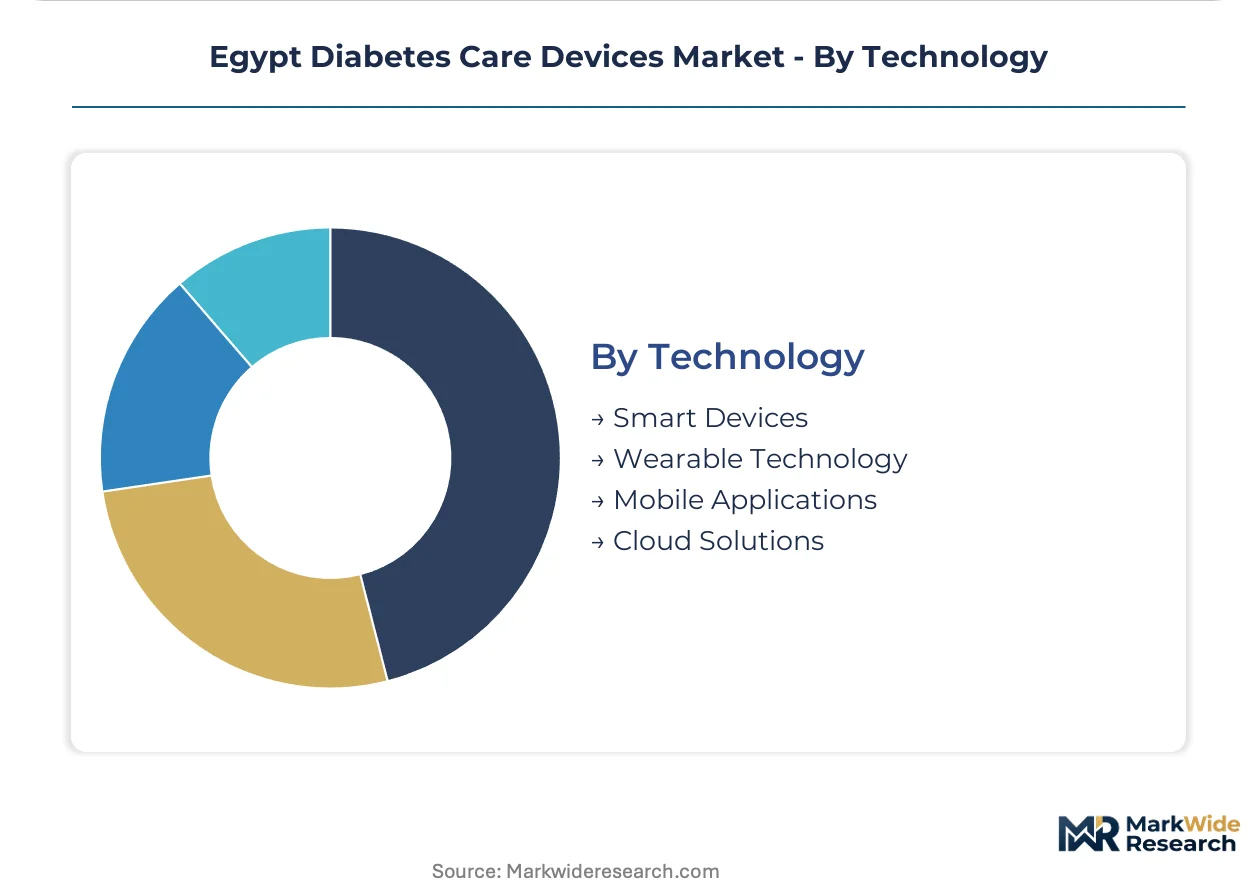
Technology:
Technology tiering separates premium subscription models from basic hardware, with data platform integration becoming the primary value capture mechanism.
- Wearable Technology:Skin-adherent electrochemical sensors with factory calibration dominate private diagnostic center investment. These systems reduce clinical intervention requirements while enabling continuous data streams for remote monitoring programs.
- Smart Devices:Bluetooth-enabled glucose meters and insulin pens with dose logging target home care patients seeking simplified glycemic management without smartphone dependency.
- Mobile Applications:Data visualization platforms aggregating sensor feeds for patient and clinician dashboards.
- Cloud Solutions:Backend infrastructure for multi-patient monitoring dashboards deployed by hospital networks.
Wearable technology commands the highest per-patient revenue; smart devices are expanding most quickly as basic meter users seek incremental connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo dominates Egypt's diabetes care devices landscape, anchoring procurement volume through hospital network tenders and telehealth platform integration while Alexandria and secondary cities fragment across pharmacy-dependent distribution models.
Greater Cairo
Urban households managing Type 2 diabetes drive factory-calibrated continuous glucose monitor adoption through Cairo-based telehealth platforms bundling device fulfillment with virtual endocrinology consultations. The Egyptian Drug Authority operates accelerated registration pathways prioritizing ISO 15197-certified devices with local assembly documentation. New Cairo and Giza host private diagnostic chains expanding remote patient monitoring contracts with Bluetooth-enabled sensor systems.
Alexandria
Hospital networks in Egypt's second-largest city anchor insulin pump procurement as endocrinology departments expand specialized diabetes services. The Universal Health Insurance Authority determines reimbursement tiers that shape patient access to advanced delivery systems versus subsidized basic meters. Smouha and Sidi Gaber districts concentrate private diagnostic centers seeking wearable technology differentiation for recurring sensor revenue models.
Mansoura
Secondary city pharmacy networks sustain shelf presence for insulin pens and test strips ahead of hospital network penetration, creating localized partnership opportunities for distributors. Ministry of Health and Population chronic disease programs channel subsidized glucose meter supply through traditional wholesale channels. The Nile Delta city's outpatient clinics remain dependent on basic certified units with limited upgrade pathways to continuous monitoring.
Suez Canal Zone
Port Said and Ismailia leverage logistics infrastructure for medical device import handling, though patient demand concentrates in government hospital procurement of conventional meters. Egyptian Drug Authority compliance costs for ISO 15197 certification filter regional gray market flows entering through transit routes. Industrial zones near Port Said are attracting pharmaceutical sector development incentives for domestic device assembly.
Upper Egypt
Assiut and Sohag governorates exhibit underpenetrated device distribution where ministry subsidy programs dominate over private-pay premium segments. National health insurance expansion into rural chronic disease management is gradually extending glucose test strip coverage beyond Greater Cairo and Alexandria. Local technical institutes in Minya face biomedical engineering talent scarcity constraining maintenance capacity for advanced insulin delivery systems.
Egypt Diabetes Care Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification and calibration sophistication spectrum, with factory-calibrated continuous monitors commanding pricing multiples over basic ISO 15197-certified meters. The vendor base stratifies into three tiers: multinational manufacturers with integrated therapy-device portfolios, regional distributors leveraging localized pharmacy partnerships, and emerging domestic assemblers capturing ministry tender volume through accelerated Egyptian Drug Authority pathways. Consolidation pressure concentrates among import-dependent premium sensor suppliers exposed to currency volatility, while fragmentation persists in subsidized basic meter supply. Dominant competitive moves include strategic partnerships with Cairo telehealth platforms and backward integration into local assembly operations to qualify for procurement preferences.
Within the multinational integrated portfolio tier, Novo Nordisk A/S and Sanofi S.A. represent European-origin pharmaceutical-device bundlers whose long-standing insulin franchises anchor hospital network relationships across Egyptian urban centers. Abbott Diabetes Care occupies a position exemplifying the premium sensor technology archetype, with factory-calibrated systems reducing clinician intervention requirements for private diagnostic chains. These three entities illustrate how competitive positioning stratifies between therapy-anchored bundlers and standalone device technology specialists in a market recalibrating around local assembly incentives and telehealth integration.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi S.A. |
| Abbott Diabetes Care |
| Dexcom, Inc. |
| Omnipod |
| Medtronic PLC |
| Eli Lilly and Company |
| Egyptian German Insulin Company |
| Roche Diabetes Care |
| Others |
Supply & Pricing Matrix
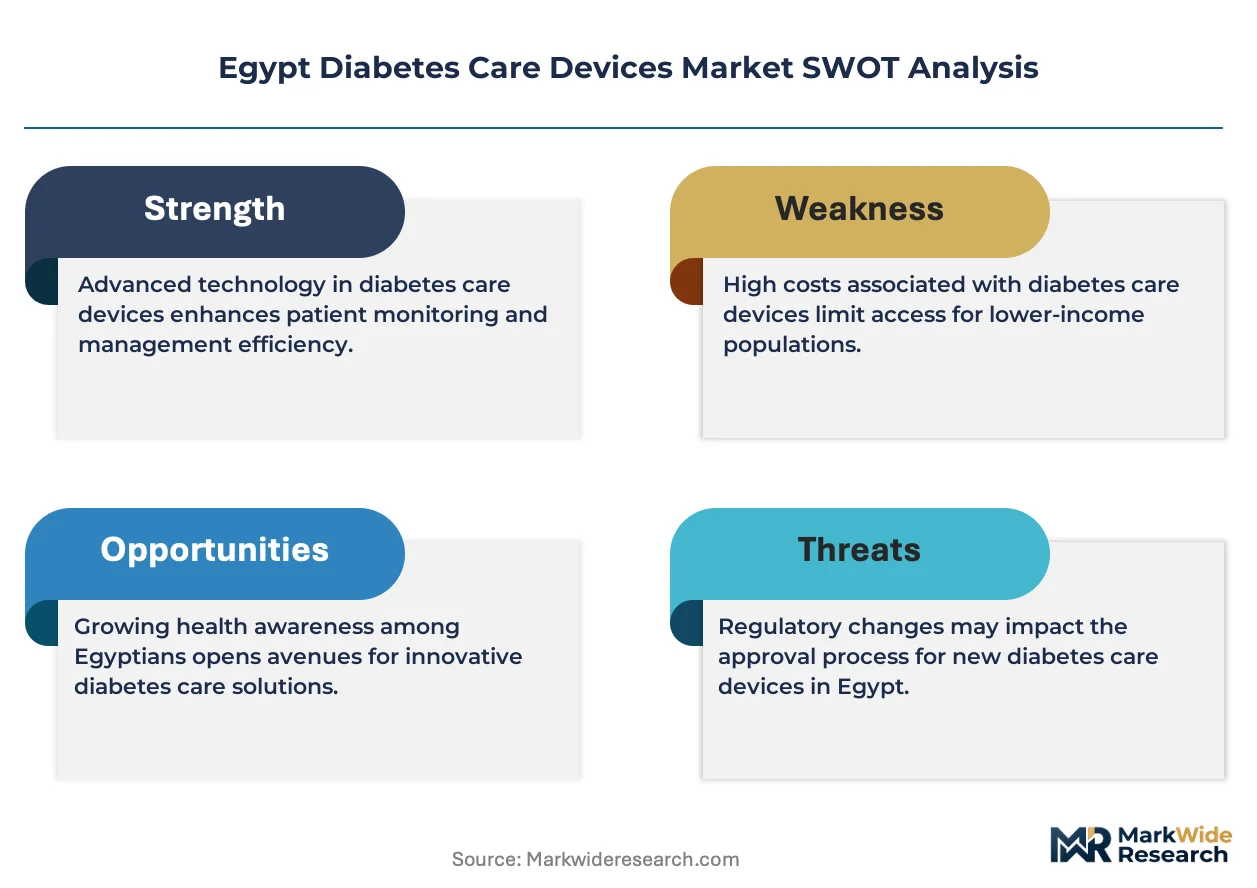
ISO 15197 certification gates qualified supply and premium-tier pricing access in Egypt's diabetes care devices market, as uncertified imports face exclusion from national health program procurement while factory-calibrated sensors command reimbursement-backed premiums.
Pricing Analysis
Outcome-based pricing anchored to reduced hospitalization rates separates premium continuous glucose monitors from basic glucose meters in Egyptian procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and local assembly status, with the Universal Health Insurance Authority determining reimbursement tiers that shape patient willingness to self-fund upgrades. Cost compression in the basic meter segment intensifies because subsidized national program supply limits private-pay conversion. Public hospital procurement committees exhibit highest price sensitivity, while private diagnostic centers in Greater Cairo demonstrate lowest sensitivity due to remote monitoring contract margins.
Supply Chain Analysis
Biomedical engineering talent scarcity in Egyptian technical institutes constrains domestic assembly capacity expansion for sensor manufacturing and micro-pump production. Electrochemical sensor components and micro-pump mechanisms draw from concentrated supply bases in Germany, Switzerland, and the United States, with Bluetooth transmitter modules sourced from Chinese electronics clusters. Single-source vulnerability in factory-calibrated sensor chemistry exposes Egyptian distributors to extended lead times and currency volatility. Distribution runs through hospital network tenders in Greater Cairo and Alexandria, with retail pharmacy networks sustaining secondary city penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's diabetes care devices market is consolidating around regulatory compliance barriers and local assembly incentives that favor integrated players with Egyptian Drug Authority registration capabilities and ministry supply relationships.
For Market Incumbents: Extend backward integration into domestic glucose meter assembly to capture pharmaceutical sector development incentives and qualify for accelerated registration pathways. Anchor hospital network relationships through bundled insulin-device portfolios that resist substitution from emerging local assemblers seeking ministry tender volume. For New Entrants and Emerging Players: The price-point gap between premium continuous monitors and subsidized basic meters creates white-space opportunity for mid-tier Bluetooth-enabled smart devices targeting home care patients in Greater Cairo. Secondary city pharmacy networks in Mansoura and the Nile Delta present underpenetrated distribution nodes where localized partnerships can establish shelf presence ahead of hospital network expansion. For Investors and Strategic Acquirers: Egyptian Drug Authority approval of domestic assembly facilities is the leading indicator that procurement preferences are shifting toward locally qualified suppliers. The five-to-ten year viability window favors acquisition targets with established ISO 15197 certification and existing relationships with Cairo-based telehealth platforms. Watch for Universal Health Insurance Authority reimbursement expansion into continuous monitoring categories as the signal for premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Egyptian Drug Authority Registration Acceleration | Fast-track pathways for locally assembled devices reshape competitive access to ministry tenders. |
| Telehealth Platform Integration | Cairo-based digital health providers bundle device fulfillment with virtual endocrinology consultations. |
| Domestic Assembly Partnership | Joint ventures with Egyptian technical institutes address biomedical engineering talent scarcity constraints. |
| Universal Health Insurance Reimbursement Strategy | Tiered coverage expansion determines patient access to premium continuous monitoring systems. |
| Secondary City Pharmacy Network Expansion | Localized distribution partnerships in Alexandria and Mansoura capture pre-hospital network demand. |
Research Methodology
Document review covered Egyptian Drug Authority registration databases, Universal Health Insurance Authority reimbursement circulars, and pharmaceutical sector development plan filings, complemented by interviews with hospital procurement managers, biomedical engineers at private diagnostic chains, retail pharmacy network heads, and endocrinology department directors. Secondary sources included hospital tender records, GPO contracts, and customs import data for glucose monitoring device categories. Bottom-up patient population estimates were triangulated against top-down ministry program expenditure figures.
Historical adoption curves for continuous glucose monitors and insulin delivery systems were cross-referenced against panel input from device distributors and telehealth platform operators. Segmentation modeling across device type, end user, distribution channel, and technology tiers captured differential growth trajectories. CAGRs were derived from fitted growth curves applied to addressable patient pools and reimbursement expansion schedules. Forecast inputs incorporated Egyptian Drug Authority registration pipeline status and pharmaceutical sector local assembly incentive uptake rates.
Underlying measurement precision varies by segment; continuous glucose monitor projections carry tighter precision than basic glucose meter estimates due to concentrated procurement visibility in hospital networks. Forecasts reflect assumptions regarding reimbursement expansion timing and domestic assembly capacity buildout that could revise if regulatory pathways shift. A small set of triggers—Universal Health Insurance Authority coverage decisions, Egyptian Drug Authority local assembly certification approvals, and telehealth platform partnership announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Germany Digital Diabetes Management Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
Global Smart Diabetes Management Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Germany Continuous Glucose Monitoring Market