
 Global Casting Devices Market | 2026-2036
Global Casting Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Casting Devices Market Analysis
Market Context
Skilled orthopedic technicians is reorganizing supply dynamics across the casting devices sector as specialized labor shortages in developed healthcare systems constrain production scale-up. Google Inc. leverages its connected health data infrastructure to explore cast monitoring integrations, while Apple Inc. competes through wearable ecosystem extensions that complement immobilization recovery tracking. Samsung Electronics Co. Ltd. anchors its position via material science partnerships that advance fiberglass composite durability in clinical environments.
Technical Definition and Segment Structure
Casting devices encompass rigid or semi-rigid external supports fabricated from plaster, fiberglass, thermoplastic, or synthetic polymers, designed to immobilize fractured or post-surgical limbs through anatomical conformance and load distribution. These devices maintain bone alignment, reduce edema, and protect healing tissue from mechanical stress during rehabilitation cycles. Fiberglass materials now lead volume deployment in hospital settings due to their radiolucency and water-resistant properties, while thermoplastic segments represent the fastest-growing category as outpatient clinics adopt remoldable solutions for pediatric and sports medicine applications. Plaster retains economy-tier dominance in emerging markets where cost sensitivity and traditional clinical training sustain legacy consumption patterns.
Regulatory Framework and Outlook
The FDA enforces biocompatibility and mechanical performance standards under 21 CFR medical device regulations, while the EU Medical Device Regulation mandates CE marking with enhanced clinical evidence requirements for cast materials classified as Class I reusable surgical instruments. Japan's PMDA and China's NMPA impose additional skin-contact material testing protocols that shape export qualification timelines for multinational suppliers. Stakeholders must monitor evolving harmonization between ISO 13485 quality management systems and national pharmacovigilance reporting obligations to sustain market access across jurisdictions.
Market Dynamics
FDA's updated medical device classification criteria for cast materials is compressing product approval timelines and elevating competitive entry barriers, while skilled orthopedic technician shortages in developed healthcare systems constrain production scale-up across the casting devices sector.
Growth Catalysts
- Aging Demographics:Hospital settings in the United States, Germany, and Japan are expanding fracture management interventions as elderly populations require more orthopedic cast applications.
- CE Marking Requirements:The EU Medical Device Regulation mandates enhanced clinical evidence for cast materials classified as Class I reusable surgical instruments, accelerating quality differentiation among compliant suppliers.
- Fiberglass Composite Advances:Material science partnerships are advancing radiolucent and water-resistant fiberglass properties that improve clinical workflow efficiency in hospital environments.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic polymer and fiberglass resin costs fluctuate with crude oil derivatives, compressing margin stability for manufacturers dependent on petroleum-based inputs.
- Specialized Labor Concentration:Skilled orthopedic technician training programs concentrate in Western Europe and North America, creating supply bottlenecks when demand surges in emerging markets lacking equivalent vocational infrastructure.
- Plaster Legacy Entrenchment:Traditional plaster casting retains economy-tier dominance in cost-sensitive emerging markets where clinical training curricula and procurement habits sustain lower-margin consumption patterns.
Strategic Opportunities
- Pediatric Thermoplastic Expansion:Outpatient clinics in Japan and Germany are adopting remoldable thermoplastic solutions for pediatric and sports medicine applications where anatomical growth requires cast adjustment.
- Connected Health Integration:Wearable ecosystem extensions and cast monitoring integrations are creating new value propositions in post-operative recovery tracking for ambulatory care settings.
- China NMPA Streamlining:China's National Medical Products Administration is harmonizing skin-contact material testing protocols with ISO standards, reducing export qualification timelines for multinational suppliers entering domestic hospital procurement channels.
Industry Challenges
- ISO 13485 Implementation Complexity:Quality management system harmonization across FDA, EU MDR, and Japan PMDA jurisdictions demands dedicated compliance personnel and extended certification timelines for mid-tier manufacturers.
- Legacy Equipment Integration:Hospital casting departments face friction when incorporating thermoplastic molding systems alongside established plaster and fiberglass application stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Casting Devices Market |
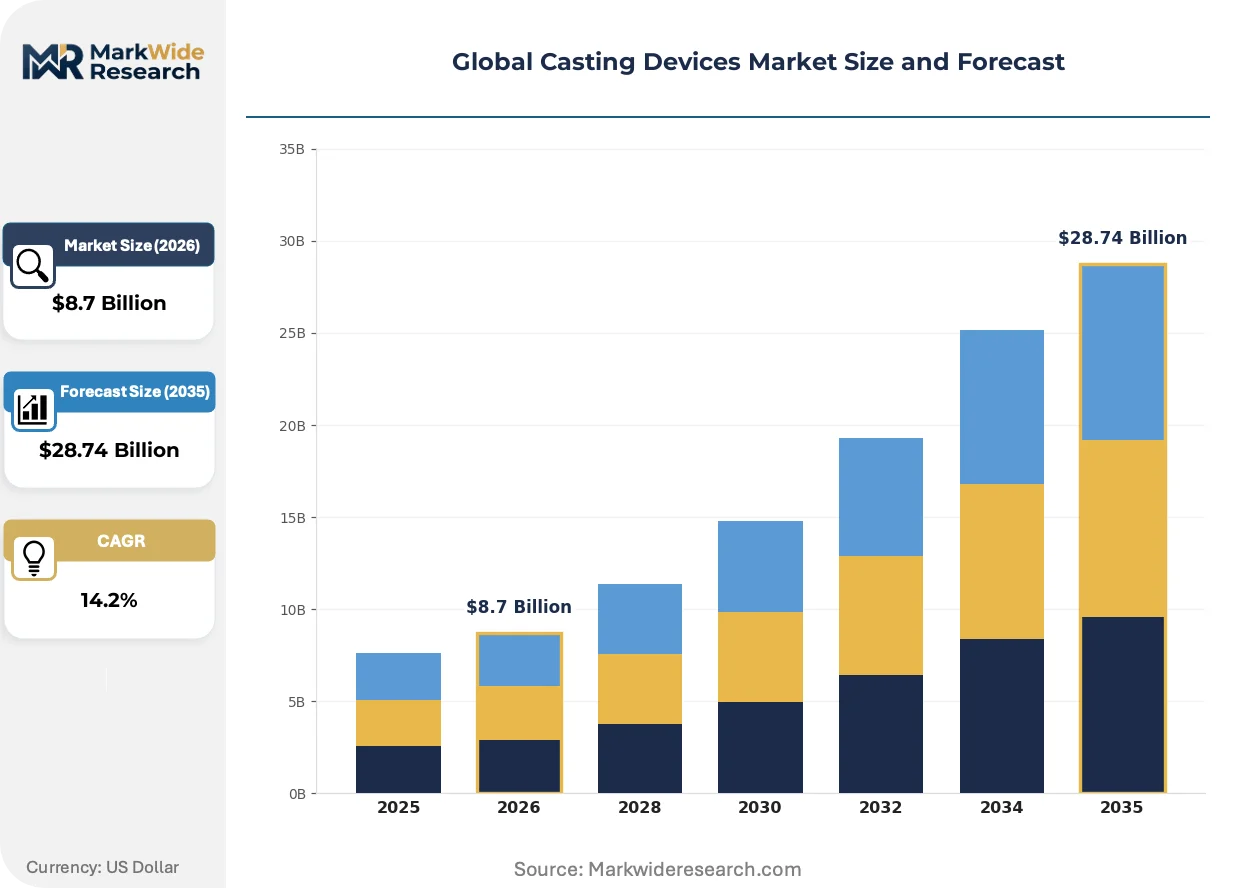
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthopedic Casts, Dental Casts, Sports Casts, Body Casts Material: Plaster, Fiberglass, Thermoplastic, Synthetic End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Application: Fracture Management, Post-Surgical Support, Immobilization, Pain Relief |
| Companies Covered | Google Inc., Apple Inc., Roku Inc., Samsung Electronics Co. Ltd., Microsoft Corporation, Amazon.com, Inc., LG Electronics Inc., ASUSTeK Computer Inc., Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Casting Devices Market Emerging Trajectories
Material convergence with digital health infrastructure is actively restructuring how immobilization devices capture, transmit, and act upon patient recovery data throughout rehabilitation cycles.
Sensor-embedded casting systems is decomposing the traditional separation between structural support and physiological monitoring. Hospital systems in the United States are piloting pressure and temperature sensing fiberglass composites for diabetic fracture patients. This convergence is decomposing standalone cast applications into integrated recovery management nodes that feed electronic health record systems.
Japan's PMDA has tightened biocompatibility documentation requirements for long-duration skin-contact materials under revised pharmaceutical and medical device guidelines. Manufacturers must now submit extended cytotoxicity and sensitization testing for casts exceeding 30-day wear periods. Thermoplastic segments serving pediatric populations face the steepest compliance cost increases as remoldable materials undergo more frequent skin interaction cycles.
Hospital procurement departments are consolidating casting device purchasing through integrated supply agreements that bundle materials with technician training and application equipment. Group purchasing organizations in Germany are displacing traditional distributor relationships with direct manufacturer contracts that specify outcome metrics including application time and complication rates. This concentration is most visible in university hospital networks where standardization across orthopedic departments reduces inventory complexity.
Global Casting Devices Market Segmentation
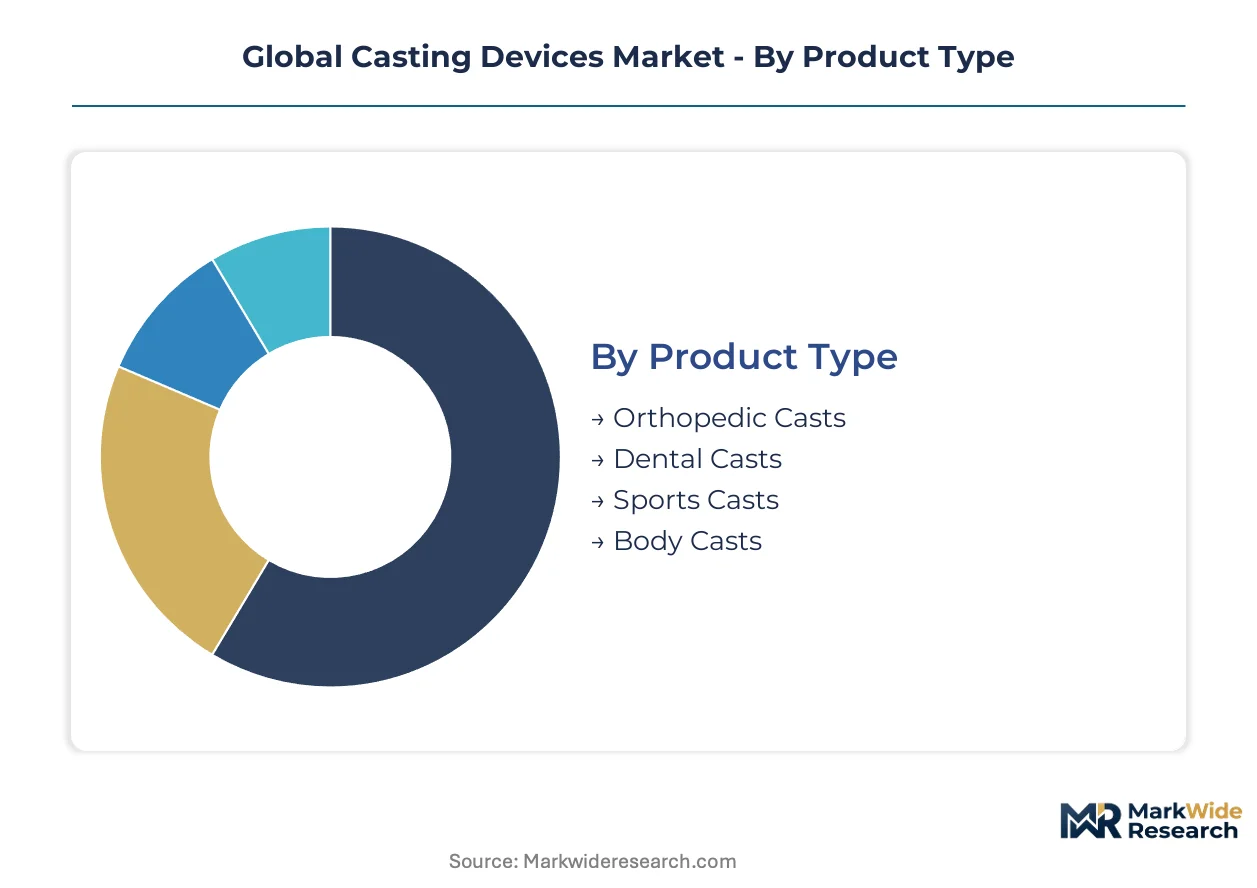
Casting device manufacturers configure product portfolios across four intersecting dimensions that determine reimbursement pathways, procurement channels, and clinical workflow integration. Material selection and end-user targeting drive the steepest margin differentials in this market.
Product Type:
Orthopedic casts command the widest margin pools due to hospital procurement consolidation and premium material specifications, while dental and sports variants operate on narrower spreads tied to outpatient volume economics.
- Orthopedic Casts:Rigid external supports fabricated from fiberglass or thermoplastic polymers for limb fracture immobilization. Demand concentrates in United States hospital systems where aging populations require more post-traumatic interventions and Medicare reimbursement favors durable medical equipment.
- Dental Casts:Plaster-based or digital impression materials used in prosthodontics and orthodontics for occlusal mapping and appliance fabrication. Germany's dental laboratory networks sustain steady consumption despite digital scanning displacement in premium segments.
- Sports Casts:Lightweight, removable immobilization devices for athletic injury management in Japan's professional sports medicine clinics.
- Body Casts:Torso-encasing supports for spinal deformity correction in pediatric scoliosis treatment across specialized United States academic medical centers.
The dominant share belongs to Orthopedic Casts, while Sports Casts are closing the gap fastest through ambulatory surgery center expansion.
Material:
Volume leadership and growth velocity diverge sharply in this category, with legacy materials defending installed base economics against advanced polymers capturing premium positioning.
- Fiberglass:Woven glass fiber mats impregnated with polyurethane resin, delivering radiolucency and water resistance for hospital radiology workflows. United States orthopedic departments favor this material for its compatibility with magnetic resonance imaging and reduced application time versus plaster alternatives.
- Thermoplastic:Low-temperature moldable polymers that soften in warm water and rigidify at room temperature, enabling remoldable fitting for pediatric patients with growth-adjustment requirements. Japan's outpatient clinics are adopting these solutions fastest for sports medicine applications where anatomical change necessitates cast modification.
- Plaster:Gypsum-based bandages retaining cost advantage in India's rural health sub-centers and traditional training curricula.
- Synthetic:Polypropylene and polyethylene blends offering breathability in Germany's long-term care facilities managing pressure ulcer risk.
Fiberglass maintains volume leadership across hospital procurement channels, though Thermoplastic is expanding most quickly through pediatric and sports medicine clinic adoption.
End User:
Customer type determines pricing architecture more than material composition, with institutional buyers extracting volume discounts that independent channels cannot match.
- Hospitals:Acute care facilities with centralized orthopedic departments and integrated supply agreements. United States university hospital networks in Boston and Philadelphia are consolidating casting device purchasing through group purchasing organizations that bundle materials with technician training and outcome metrics.
- Clinics:Outpatient facilities including orthopedic specialty practices and urgent care centers. Germany's ambulatory care networks favor thermoplastic solutions for same-day application and removal capabilities that reduce patient return visits.
- Rehabilitation Centers:Post-acute facilities in Japan managing stroke and trauma recovery with extended immobilization protocols.
- Home Care:Direct-to-patient channels for cast liners and waterproof covers in United States Medicare Advantage plans emphasizing aging-in-place.
Hospitals retain the dominant procurement volume, while Clinics are gaining share fastest through ambulatory surgery migration and same-day discharge protocols.
Application:
Clinical indication shapes material specification and reimbursement coding, with trauma applications commanding premium pricing against maintenance indications.
- Fracture Management:Acute immobilization following traumatic bone disruption, requiring anatomical conformance and load-bearing capacity. United States emergency departments prioritize fiberglass for its rapid hardening and imaging compatibility in high-throughput trauma settings.
- Post-Surgical Support:Protective immobilization following orthopedic procedures such as tendon repair or joint arthrodesis. Germany's statutory health insurance system reimburses thermoplastic options for procedures requiring staged range-of-motion progression.
- Immobilization:Prolonged fixation for congenital conditions or neurological spasticity in Japan's pediatric rehabilitation networks.
- Pain Relief:Temporary support for soft tissue injuries without bony involvement in United States occupational medicine clinics.
Fracture Management holds the dominant clinical volume, while Post-Surgical Support is climbing fastest through arthroscopy and sports medicine procedure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium material pricing in United States hospital networks runs 40-60% above procurement costs in India's rural health sub-centers, creating a structural arbitrage that multinational suppliers exploit through tiered product portfolios.
United States
Medicare reimbursement policies favor durable medical equipment with radiolucent properties, accelerating fiberglass adoption in Boston and Philadelphia university hospital networks. FDA's 21 CFR biocompatibility standards compress approval timelines for sensor-embedded casting systems. Group purchasing organizations in the Northeast Corridor are consolidating procurement through outcome-based contracts that bundle materials with technician training.
Germany
Statutory health insurance reimbursement for thermoplastic options drives outpatient clinic adoption in Bavaria and North Rhine-Westphalia. EU Medical Device Regulation CE marking requirements with enhanced clinical evidence mandates filter non-compliant suppliers from procurement channels. Baden-Württemberg's medical technology cluster anchors fiberglass composite research partnerships between manufacturers and university hospitals.
Japan
Aging demographics and professional sports medicine expansion concentrate demand in Tokyo's orthopedic departments and Osaka's rehabilitation networks. PMDA's tightened biocompatibility documentation for long-duration skin-contact materials elevates compliance costs for pediatric thermoplastic segments. Kansai region clinics lead remoldable solution adoption for growth-adjustment applications.
China
Hospital procurement channel expansion in Yangtze River Delta and Pearl River Delta regions absorbs premium fiberglass volumes from multinational exporters. NMPA harmonization of skin-contact testing protocols with ISO standards reduces export qualification barriers for European and American suppliers. Beijing-Tianjin-Hebei corridor academic medical centers pilot integrated supply agreements with outcome specifications.
India
Cost-sensitive rural health infrastructure sustains plaster bandage consumption in Maharashtra and Gujarat sub-centers despite urban hospital fiberglass transitions. Central Drugs Standard Control Organization oversight of medical device quality creates compliance friction for imported synthetic materials. Karnataka's private hospital networks in Bangalore cluster represent the fastest premium material uptake outside metro Delhi.
Global Casting Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with sensor-embedded systems and connected health integrations commanding premium positioning against commodity fiberglass and plaster manufacturers competing on volume scale. The vendor base separates into three tiers: diversified electronics conglomerates leveraging health data infrastructure, specialized medical device fabricators with regulatory certification depth, and regional material suppliers serving cost-sensitive procurement channels. Dominant competitive moves center on strategic partnerships between material scientists and digital health platforms, alongside capacity consolidation through hospital group purchasing organization direct contracting.
Among diversified technology conglomerates, Google Inc. and Apple Inc. exemplify the data-platform archetype, while Samsung Electronics Co. Ltd. anchors the material-science partnership model. These three occupy positions where ecosystem integration capabilities determine competitive viability more than standalone casting device manufacturing scale. Specialized orthopedic suppliers sit within a fragmented mid-tier where ISO 13485 certification and jurisdiction-specific regulatory relationships define market access. Regional fabricators in emerging markets compete through plaster and economy synthetic production where clinical training curricula and procurement habits sustain legacy consumption patterns against premium material conversion pressures.
| Leading Market Players |
|---|
| Google Inc. |
| Apple Inc. |
| Roku Inc. |
| Samsung Electronics Co. Ltd. |
| Microsoft Corporation |
| Amazon.com, Inc. |
| LG Electronics Inc. |
| ASUSTeK Computer Inc. |
| Sony Corporation |
| Others |
Supply Flow & Price Mechanics
FDA's 21 CFR biocompatibility standards gate both supplier qualification timelines and price differentiation between sensor-embedded premium systems and commodity fiberglass alternatives. CE marking under EU MDR compresses approval pathways for compliant manufacturers while elevating entry barriers that protect incumbent pricing power in hospital procurement channels.
Pricing Analysis
The customization-premium spread separates configured-to-order thermoplastic pediatric solutions from standard fiberglass hospital contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Price differentiation hinges on ISO 13485 compliance depth and after-sales training bundling. Cost compression in economy plaster segments is intensifying because petrochemical resin volatility feeds through to synthetic polymer alternatives. Rural health sub-centers in India exhibit highest price sensitivity; United States university hospital networks show lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Specialized orthopedic technician training concentration in Western Europe and North America creates a chokepoint constraining production scale-up when demand surges in emerging markets. Manufacturing draws from China, Germany, and the United States for fiberglass composite fabrication and thermoplastic polymer formulation. Raw material dependencies center on polyurethane resin systems, woven glass fiber mats, and low-temperature moldable polymers. Single-source vulnerability runs through petrochemical feedstock suppliers concentrated in Gulf Coast and Rotterdam refining clusters. Distribution runs through group purchasing organization direct contracts displacing traditional distributor relationships in hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected health integration and sensor-embedded casting systems constitute a high-growth disruption reshaping competitive positioning. FDA's evolving medical device classification criteria for cast materials accelerates this inflection by compressing approval timelines for digital-native entrants.
For Market Incumbents: Fortify regulatory certification depth across FDA, EU MDR, and Japan PMDA jurisdictions to defend against digital health platform entrants leveraging data infrastructure. Deepen backward integration into fiberglass composite resin production to offset petrochemical feedstock volatility. Prioritize ISO 13485 harmonization investments that sustain hospital group purchasing organization contract eligibility. For New Entrants and Emerging Players: Anchor in pediatric thermoplastic segments where remoldable solutions address growth-adjustment requirements underserved by legacy plaster and rigid fiberglass alternatives. Target outpatient clinic channels in Japan and Germany where same-day application capabilities reduce patient return visits and statutory reimbursement favors innovation. Pursue material science partnerships with university hospital research clusters to accelerate clinical validation. For Investors and Strategic Acquirers: EU MDR CE marking harmonization with ISO standards reshapes the acquisition landscape by filtering non-compliant suppliers from procurement channels. Long-term viability centers on targets with regulatory certification depth spanning multiple jurisdictions rather than single-market fabricators. Monitor NMPA streamlining progress in China as signal for export qualification timeline compression enabling multinational supplier entry into domestic hospital procurement channels.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates quality differentiation among hospital suppliers in Germany and France. |
| Hospital System Partnership | Group purchasing organization direct contracts bundle materials with technician training in Boston networks. |
| Software Companion Development | Sensor-embedded fiberglass composites feed electronic health record systems in United States pilot programs. |
| Backward Integration | In-house polyurethane resin production insulates margin stability against crude oil derivative volatility. |
| Reimbursement Strategy | Medicare Advantage aging-in-place coverage expands direct-to-patient channels for cast liners and waterproof covers. |
Methodological Framework
A standing panel of orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract repositories, and CMS Medicare durable medical equipment reimbursement schedules. Bottom-up demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across material type, end-user channel, clinical application, and regional regulatory cluster segmentation. CAGRs derived from regression analysis of historical adoption curves adjusted for demographic and reimbursement inflection points. Industry-specific forecast inputs incorporated skilled technician training pipeline capacity and petrochemical resin price volatility indices.
Decision-makers should treat outputs as directional under assumptions of stable regulatory harmonization progress and continued hospital procurement consolidation; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as FDA device classification criteria and EU MDR enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
PDA Closure Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
US Bathroom and Toilet Assist Devices Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Interatrial Shunt Market