
 Dental Laboratories Market | 2026-2036
Dental Laboratories Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Laboratories Market Intelligence
Skilled dental technician labor availability is collapsing across North America and Western Europe, forcing laboratories to automate workflows or consolidate. Dentsply Sirona leverages its integrated CAD/CAM hardware-software ecosystem to capture recurring consumable revenue from laboratories locked into its file formats. Straumann Group anchors its position through proprietary implant-abutment connections that drive captive restorative work back to its partner lab network. Henry Schein competes by controlling distribution reach into independent practices that feed case volume to affiliated laboratories.
Dental laboratories are commercial fabrication facilities that produce custom oral prosthetics, restorative devices, and orthodontic appliances from patient-specific impressions or digital scans, typically using biocompatible ceramics, cobalt-chrome alloys, or photopolymer resins processed through sintering, milling, or additive manufacturing to achieve ISO-defined marginal fit tolerances. Crowns and bridges remain the mature revenue base where price compression is sharpest, while 3D-printed dentures and clear aligner models represent the fastest-expanding fabrication segments as chairside scanning adoption widens the digital case pipeline. Ceramic and zirconia materials command premium positioning against metal-based alternatives as anterior esthetic standards rise among private-pay patients.
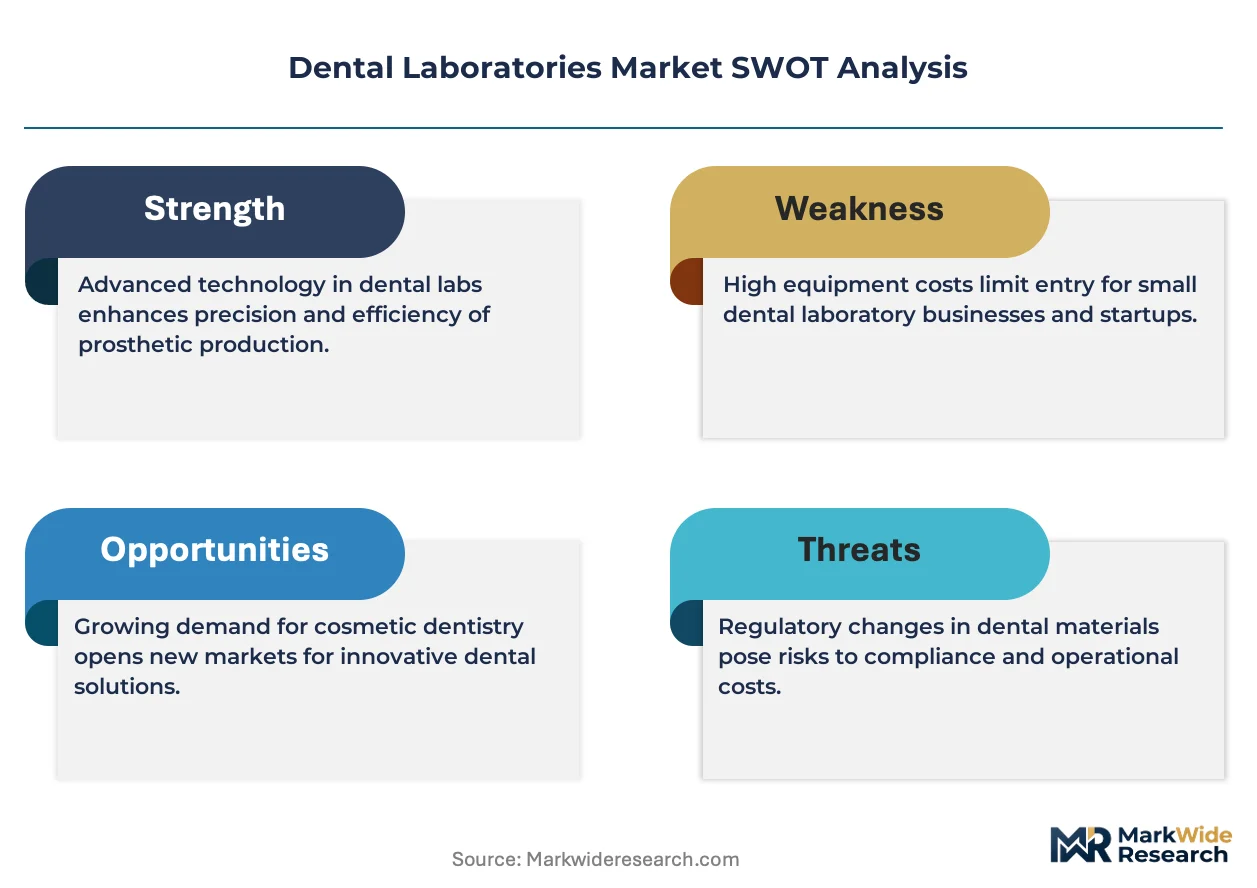
FDA 510(k) clearance requirements for CAD/CAM milling systems and EU MDR Class IIa rules for custom-made dental devices impose validation burdens that favor laboratories with documented quality management systems. The EPA monitors particulate emissions from alloy grinding and acrylic finishing operations, pushing urban labs toward centralized production or wet-milling enclosures. Stakeholders must monitor how FDA digital dentistry guidance and EU MDR notified body capacity constraints reshape the cost structure of remaining independent versus corporate-affiliated laboratory operations.
Market Dynamics
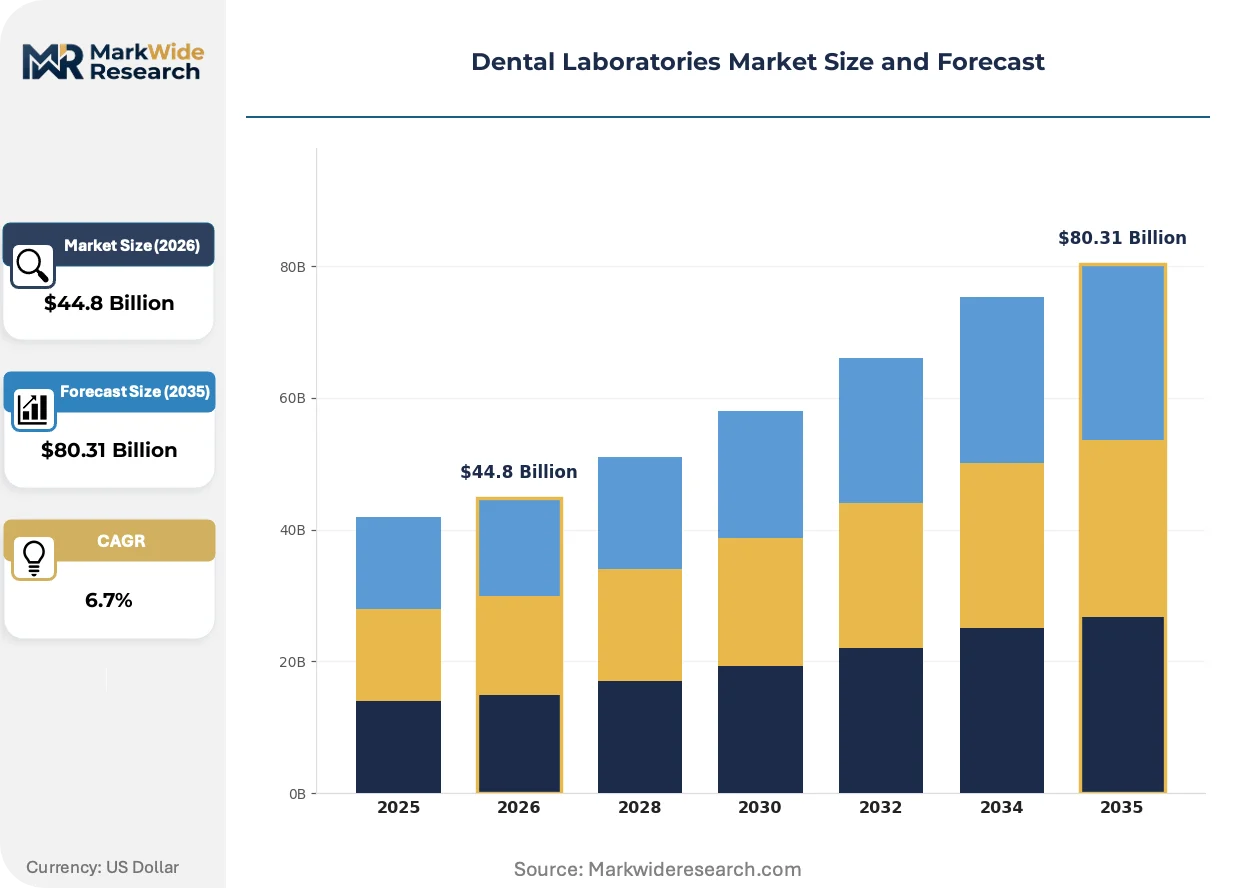
Dental laboratories confront a structural squeeze between collapsing technician labor pools and accelerating digital case volumes from chairside scanners. Automation investments now determine survival thresholds as fabrication demand outpaces skilled workforce replacement rates.
Growth Catalysts
- EU MDR Class IIa pathways:Streamlined conformity assessment for custom-made devices accelerates laboratory certification timelines across European markets, reducing notified body bottlenecks for quality-system-documented operators.
- Clear aligner model fabrication:Orthodontic clear aligner production is absorbing excess milling capacity as direct-to-consumer brands outsource thermoforming substrate manufacturing to certified dental laboratories.
- Zirconia sintering automation:Continuous furnace systems with robotic loading are compressing unit labor hours per crown in high-throughput United States laboratories serving metropolitan dental practice clusters.
Market Restraints
- Precious metal alloy volatility:Palladium and gold price swings destabilize cost forecasting for cast partial denture frameworks, squeezing margin predictability in traditional removable prosthetics.
- EPA particulate enforcement:Wet-milling enclosure mandates and dust collection upgrades impose capital burdens on urban United States laboratories operating in leased industrial space with limited ventilation retrofit options.
- Monolithic zirconia substitution:Full-contour zirconia crowns are displacing porcelain-fused-to-metal restorations, eroding the premium pricing layer that subsidized complex case workflows in mid-size laboratories.
Strategic Opportunities
- Chairside scanner integration services:Laboratories capturing STL file management and design optimization for general practices lacking in-house CAD capability are securing recurring digital workflow revenue streams.
- India dental tourism corridor:Export-oriented fabrication hubs in Gujarat and Tamil Nadu are positioning for ISO-certified production serving price-sensitive European and Middle Eastern dental chains.
- FDA 3D-printed denture resin clearance:Expanded 510(k) pathways for photopolymer denture base materials enable same-day digital denture workflows that compress traditional five-appointment protocols into single-visit solutions.
Industry Challenges
- CAD/CAM technician training deficits:North American vocational programs graduate insufficient operators proficient in 3Shape and exocam design suites, forcing laboratories to internalize six-month onboarding cycles.
- EU MDR technical documentation burden:Custom-device file retention and post-market surveillance obligations consume administrative bandwidth at small-to-mid laboratories without dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Laboratories Market |
| Market Size in 2026 | $44.8 Billion |
| Market Size in 2035 | $80.31 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Bridges, Dentures, Orthodontics End User: Dental Clinics, Hospitals, Orthodontic Practices, Dental Schools Material: Metal, Ceramic, Composite, Resin Technology: CAD/CAM, 3D Printing, Milling, Casting |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, Straumann Group, Ivoclar Vivadent, Glidewell Dental, National Dentex Corporation, Henry Schein, A-dec Inc., 3M Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Laboratories Market Strategic Shifts & Innovations
Digital fabrication hardware is compressing physical footprints while expanding throughput ceilings. Regulatory frameworks are hardening quality documentation requirements. Buyer procurement patterns are fragmenting across direct digital channels and traditional distributor relationships.
Desktop five-axis milling units are miniaturizing production workflows previously requiring centralized industrial equipment. Mid-size United States laboratories are deploying compact sintering furnaces and wet-milling stations in satellite locations closer to suburban dental clusters. This geographic redistribution is compressing shipping turnaround times from days to hours for same-day crown delivery commitments.
EU MDR notified body capacity constraints are reshaping competitive readiness timelines for custom dental device manufacturers. Laboratories with pre-existing ISO 13485 quality management systems are securing faster conformity assessment slots, while uncertified competitors face twelve-to-eighteen month validation queues. German and Swiss laboratories with established TÜV SÜD or DEKRA relationships are capturing displaced case volume from lagging Mediterranean operators.
Dental practice procurement patterns are fragmenting across direct manufacturer portals and traditional distributor relationships. Large United States dental service organizations are consolidating vendor lists through Henry Schein and Patterson centralized purchasing, while independent practices increasingly source consumables through Dentsply Sirona's CEREC Club and Straumann's partner lab networks. This bifurcation is compressing price transparency and fragmenting loyalty mechanisms across the laboratory customer base.
Dental Laboratories Market Segmentation
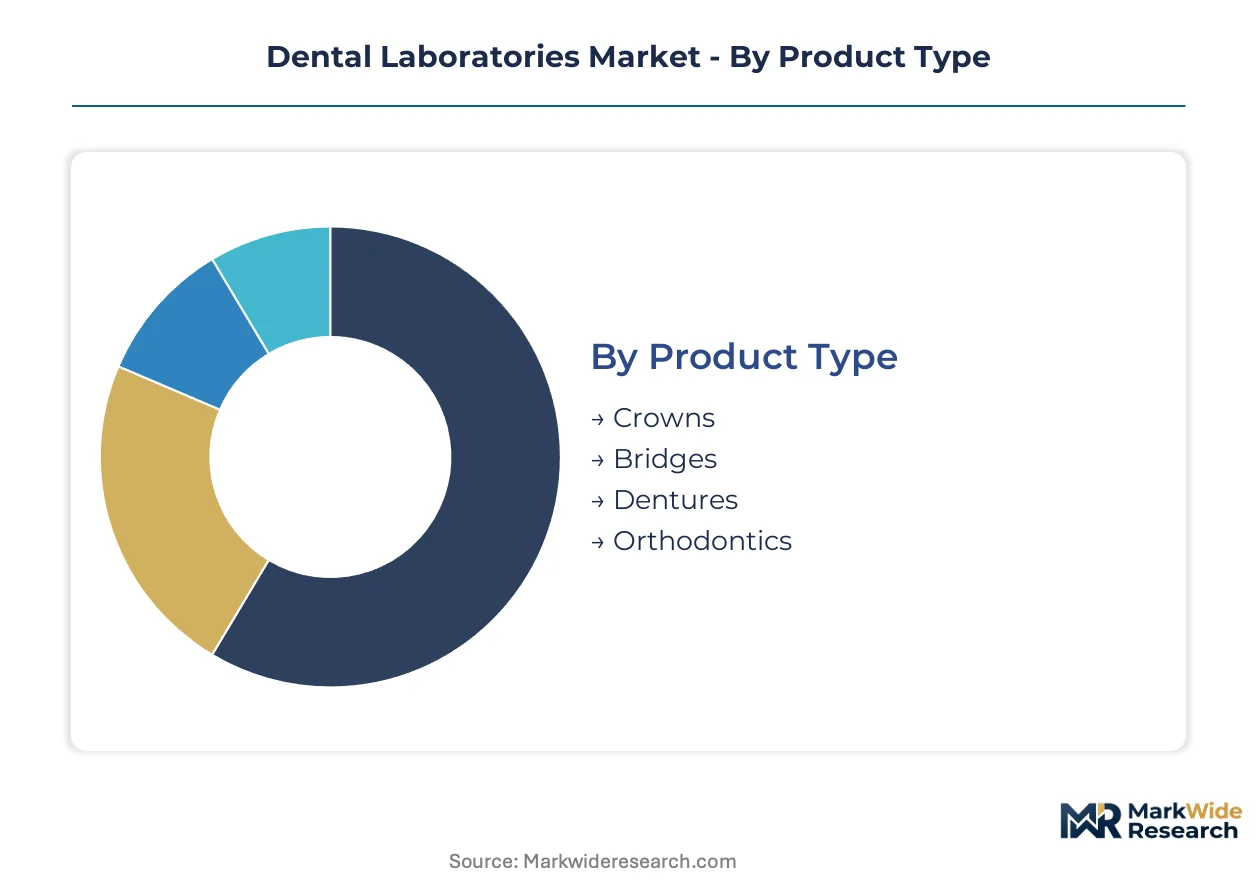
Dental laboratory segmentation reveals how fabrication workflows, procurement channels, and margin structures diverge across product categories and customer types. Laboratories configure equipment and staffing differently depending on which segments dominate their case mix.
Product Type:
Channel flow varies sharply: crowns and bridges move through high-volume distributor networks, while dentures and orthodontics increasingly route through direct digital portals.
- Crowns:Monolithic zirconia and lithium disilicate restorations dominate fabrication schedules. United States metropolitan laboratories serving dental service organizations are compressing unit economics through sintering furnace automation.
- Bridges:Multi-unit fixed prosthetics require precision-milled frameworks with ISO-defined marginal fit tolerances. German laboratories with TÜV SÜD certification are capturing complex anterior cases from price-competitive Mediterranean operators facing EU MDR bottlenecks.
- Dentures:3D-printed photopolymer base resins are displacing conventional acrylic processing workflows.
- Orthodontics:Clear aligner thermoforming substrates absorb excess milling capacity from direct-to-consumer brands.
Crowns dominate installed base. Orthodontics is where expansion concentrates.
End User:
Customer procurement maturity determines pricing leverage and service bundling opportunities.
- Dental Clinics:General practices with chairside scanners generate STL file volumes requiring laboratory design optimization services. United States independent clinics lacking in-house CAD capability outsource crown design to regional laboratories for recurring per-case fees.
- Hospitals:Academic medical centers and trauma facilities demand complex implant-supported prosthetics with documented biocompatibility certification. Swiss hospital procurement departments prioritize laboratories with ISO 13485 quality systems for reconstructive case referrals.
- Orthodontic Practices:Specialty clinics drive clear aligner model fabrication demand.
- Dental Schools:Training institutions consume pre-fabricated study models and educational kits.
Dental clinics anchor volume throughput. Hospitals command premium pricing tiers.
Material:
Material selection tracks patient payment type and anterior-posterior positioning.
- Metal:Cobalt-chrome and precious alloy frameworks persist in removable partial dentures. Palladium price volatility destabilizes cost forecasting for cast frameworks in traditional prosthetics segments.
- Ceramic:Zirconia and lithium disilicate command anterior esthetic premiums from private-pay patients. Chinese laboratories in Guangdong province are scaling continuous sintering lines for monolithic zirconia crown exports.
- Composite:Chairside provisional materials and temporary crown stocks.
- Resin:Photopolymer denture bases and aligner thermoforming substrates.
Ceramic captures margin concentration. Resin is climbing the fastest.
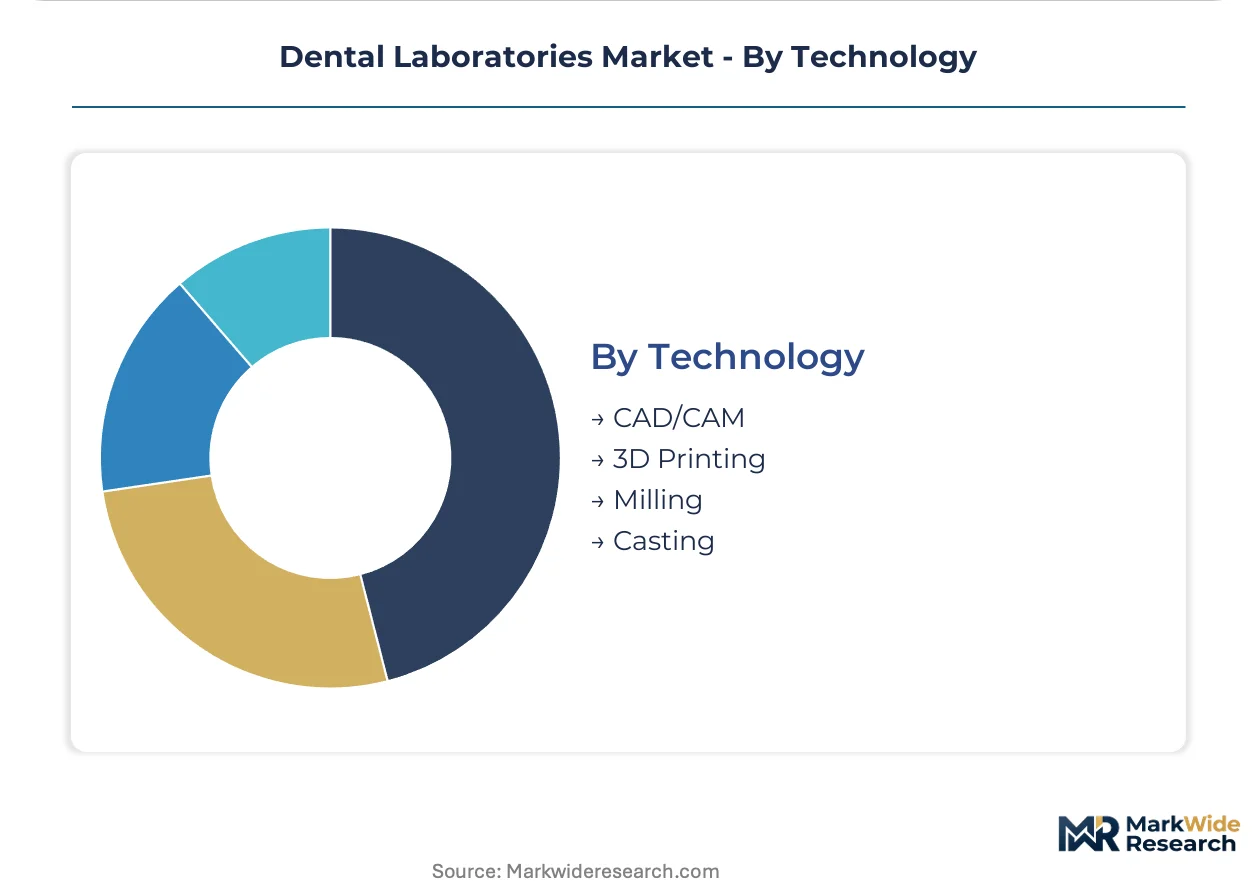
Technology:
Capital equipment choices lock laboratories into specific consumable ecosystems and file format dependencies.
- CAD/CAM:Integrated design-to-milling workflows dominate crown and bridge production. Dentsply Sirona's CEREC ecosystem captures recurring consumable revenue from laboratories locked into proprietary file formats.
- 3D Printing:Photopolymer resin systems enable same-day denture bases and surgical guides. FDA 510(k) clearance expansion for denture resins is compressing traditional five-appointment protocols into single-visit solutions.
- Milling:Five-axis subtractive machining persists in zirconia and titanium implant components.
- Casting:Traditional alloy investment methods retain niche application for precious metal frameworks.
CAD/CAM anchors production capacity. 3D printing is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German laboratories commanding premium margins for ISO-certified complex prosthetics, while price-sensitive case volume migrates toward export-oriented fabrication hubs in China and India where sintering automation compresses unit economics.
United States
Metropolitan laboratory clusters in California, Texas, and New York absorb digital case volumes from dental service organizations deploying chairside scanners. FDA 510(k) clearance requirements for CAD/CAM milling systems favor laboratories with documented quality management systems. Chicago-based fabrication networks are consolidating through sintering furnace automation to offset technician labor shortages.
Germany
Precision-milled implant components and complex anterior bridges drive demand from private-pay patients seeking biocompatibility certification. EU MDR Class IIa conformity assessment timelines compress for laboratories holding TÜV SÜD or DEKRA quality system documentation. Stuttgart and Munich industrial zones host concentrated CAD/CAM equipment manufacturing that feeds downstream laboratory automation.
China
Guangdong province laboratories scale continuous zirconia sintering lines for monolithic crown exports serving Middle Eastern and European dental chains. NMPA regulatory pathways for custom dental devices are streamlining alongside domestic CAD/CAM adoption in tier-one cities. Shenzhen fabrication hubs integrate chairside scanner file management for same-day crown delivery commitments.
Switzerland
Hospital procurement departments in Zurich and Geneva prioritize laboratories with ISO 13485 systems for reconstructive implant-supported prosthetics. Swissmedic oversight of custom-device technical documentation aligns with EU MDR requirements, creating regulatory continuity for cross-border case referrals. Basel-region laboratories leverage proximity to precision machining suppliers for titanium abutment fabrication.
India
Gujarat and Tamil Nadu export-oriented hubs position for ISO-certified production serving price-sensitive European markets. CDSCO regulatory harmonization with international standards accelerates certification timelines for laboratories targeting dental tourism corridors. Ahmedabad fabrication clusters absorb clear aligner model outsourcing from direct-to-consumer orthodontic brands.
Dental Laboratories Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated CAD/CAM ecosystem providers capturing recurring consumable revenue while independent laboratories compete on turnaround speed and design customization. The vendor base separates into three strategic tiers: multinational equipment-software integrators, mid-scale regional fabrication networks, and specialized implant-focused laboratories. Consolidation pressures favor laboratories with captive digital workflow partnerships or proprietary file format lock-in. Competitive moves concentrate on automation capital deployment and quality system certification to secure hospital and dental service organization vendor status.
Among integrated equipment-software providers, Dentsply Sirona and Straumann Group exemplify archetypes leveraging proprietary ecosystems to capture downstream laboratory case volume. Envista Holdings Corporation occupies a position within the dental technology platform tier. Mid-scale independent networks like Glidewell Dental and National Dentex Corporation represent consolidation plays targeting metropolitan dental cluster density. Henry Schein anchors distribution-centric positioning through practice-facing supply relationships that feed affiliated laboratory case pipelines.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| Straumann Group |
| Ivoclar Vivadent |
| Glidewell Dental |
| National Dentex Corporation |
| Henry Schein |
| A-dec Inc. |
| 3M Health Care |
| Others |
Cost & Logistics Intelligence
Sintering furnace automation in high-throughput United States laboratories compresses unit labor hours per crown while simultaneously establishing price floors that smaller operators cannot match. This scale-driven dynamic concentrates supply among capital-intensive networks and fragments price-setting power across metropolitan dental clusters.
Pricing Analysis
The customization-premium spread separates ISO-certified complex prosthetics from standard monolithic zirconia crowns. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic delivery cost. Cost compression in the standard tier is intensifying because Chinese laboratories in Guangdong province scale continuous sintering lines for export markets. Dental service organizations demonstrate highest price sensitivity through centralized purchasing programs, while Swiss hospital procurement departments show lowest sensitivity for reconstructive implant cases demanding biocompatibility documentation.
Supply Chain Analysis
Inbound logistics costs for zirconia powder shipments from Chinese processing facilities through Los Angeles and Rotterdam ports influence working capital cycles at European and North American laboratories. Raw material dependencies center on yttria-stabilized zirconia from Chinese suppliers, cobalt-chrome alloy feedstock from German foundries, and photopolymer resins from Japanese chemical manufacturers. Single-source vulnerability for premium zirconia powders creates exposure to export licensing shifts. Distribution runs through Henry Schein and Patterson centralized purchasing platforms serving dental service organizations, alongside direct digital portals for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental laboratories face high-growth disruption from FDA 510(k) clearance expansion for 3D-printed denture resins, which compresses traditional five-appointment protocols into single-visit solutions and reconfigures competitive viability thresholds.
For Market Incumbents: Consolidate through sintering furnace automation investments in metropolitan United States clusters to offset collapsing technician labor availability. Capture recurring consumable revenue by deepening proprietary file format lock-in for chairside scanner ecosystems, defending against emerging direct-to-consumer orthodontic brands that outsource thermoforming substrate manufacturing. For New Entrants and Emerging Players: Anchor in ISO-certified export-oriented fabrication hubs in Gujarat and Tamil Nadu serving price-sensitive European dental chains. Target clear aligner model fabrication for direct-to-consumer orthodontic brands as the most penetrable segment, leveraging CDSCO regulatory harmonization to accelerate certification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratories with established TÜV SÜD or DEKRA quality system documentation capturing displaced case volume from Mediterranean operators facing EU MDR bottlenecks. Long-term viability rests on automation capital deployment and quality certification securing hospital vendor status. Watch FDA digital dentistry guidance revisions as the inflection indicator for same-day workflow adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | Sintering furnace robotics compress unit labor hours at high-throughput metropolitan laboratories. |
| Quality System Certification | ISO 13485 documentation secures faster EU MDR conformity assessment slots against notified body bottlenecks. |
| Chairside Scanner Integration | STL file management services capture recurring digital workflow revenue from CAD-incapable general practices. |
| Geographic Consolidation | Metropolitan laboratory networks reduce shipping turnaround times for same-day crown delivery commitments. |
| Regulatory Pathway Navigation | FDA 510(k) clearance for photopolymer denture resins enables single-visit digital denture workflows. |
Research Approach
Initial hypotheses were tested against primary input from dental laboratory owners, CAD/CAM equipment operators, hospital procurement managers, and GPO contracts managers and refined through secondary validation. Primary fieldwork drew from FDA 510(k) filings, EU MDR notified body capacity reports, customs trade data for zirconia powder shipments, and hospital procurement database records. Bottom-up and top-down triangulation reconciled equipment installation counts with consumable revenue estimates across the analysis window.
Variance decomposition separated volume effects from price-mix effects across product type, material, technology, and end-user segmentation dimensions. CAGRs were derived from modeled unit economics and adoption curve parameters. Industry-specific forecast inputs incorporated chairside scanner penetration rates and EU MDR certification queue lengths.
Material uncertainties — regulatory guidance revisions, precious metal alloy price volatility, and technician labor availability shocks — sit outside the modeled envelope. Forecasts reflect assumptions about automation adoption trajectories and notified body capacity normalization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Carpule Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental Chair Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Global Dental Restorative Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Needle Market