
 US Dental Chains Market | 2026-2036
US Dental Chains Market Size, Share, and Industry Trends Forecast 2026-2036
US Dental Chains Market Intelligence
Procedure bundling into subscription-style membership plans is recalibrating how uninsured and underinsured patients select providers. Heartland Dental leverages its scale across supported practices to standardize clinical protocols and back-office operations. Smile Brands anchors its competitive stance through franchisee support systems that reduce overhead for individual operators. Pacific Dental Services differentiates via its proprietary practice management platform and emphasis on doctor-led care models.
US dental chains are multi-site oral healthcare organizations that deliver preventive, restorative, and specialty services through centralized administration, shared technology infrastructure, and standardized clinical protocols, typically operating facilities exceeding 10,000 square feet with digital radiography and electronic health record integration. General dentistry generates the highest visit volume and serves as the patient acquisition gateway, while cosmetic dentistry commands superior fee-for-service margins due to limited insurance reimbursement. Orthodontics represents the fastest-expanding service line as clear aligner technology broadens the adult treatment pool beyond adolescent traditional braces.
FDA oversight of medical devices including intraoral scanners and CAD/CAM milling systems shapes capital investment requirements for chain-level technology standardization. OSHA bloodborne pathogen standards and state dental board regulations govern clinic staffing ratios, sterilization protocols, and continuing education mandates that directly affect operating costs. HIPAA compliance obligations intensify as patient data flows increase between tele-dentistry platforms, imaging systems, and centralized billing operations. Stakeholders must weigh the pace of state-level Medicaid reimbursement reform against the capital requirements for same-day dentistry technology deployment.
Market Dynamics
Clear aligner technology is absorbing orthodontic patient flow previously reserved for traditional bracket systems, forcing US dental chains to reconfigure chair utilization and specialty staffing models around same-day treatment starts.
Growth Catalysts
- Medicare Advantage dental expansion:CMS-approved supplemental benefits are unlocking senior patient segments previously excluded from commercial coverage pools.
- Same-day CAD/CAM milling:Chairside ceramic restoration production compresses appointment counts and elevates per-visit economics for crown and bridge procedures.
- Sun Belt metropolitan concentration:Houston, Phoenix, and Tampa patient bases are expanding through retiree migration and employer-sponsored relocation packages.
Market Restraints
- State Medicaid reimbursement volatility:Individual state legislature decisions on expansion create patchwork coverage maps that destabilize revenue forecasting for safety-net dependent locations.
- OSHA bloodborne pathogen compliance costs:Sterilization protocol upgrades and staff training mandates impose recurring operational overhead that scales with clinic count.
- Clear aligner manufacturing concentration:Supply chain dependence on a narrow set of thermoplastic material suppliers exposes chains to input cost spikes and allocation constraints.
Strategic Opportunities
- Subscription membership models:Uninsured patient segments in Texas and Florida are migrating toward bundled preventive care packages that bypass traditional payer intermediaries.
- Tele-dentistry triage integration:Remote consultation platforms are converging with intraoral imaging to filter emergency cases and optimize specialist referral routing.
- HIPAA-compliant data infrastructure:Centralized billing and imaging system investments create defensible operational moats through patient record portability and cross-location scheduling.
Industry Challenges
- Doctor recruitment and retention:General dentistry and orthodontic specialist shortages in high-growth metropolitan markets are compressing compensation structures and extending vacancy periods.
- Legacy practice management system integration:Acquired independent practices often operate incompatible electronic health record platforms that require costly data migration and workflow standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Dental Chains Market |
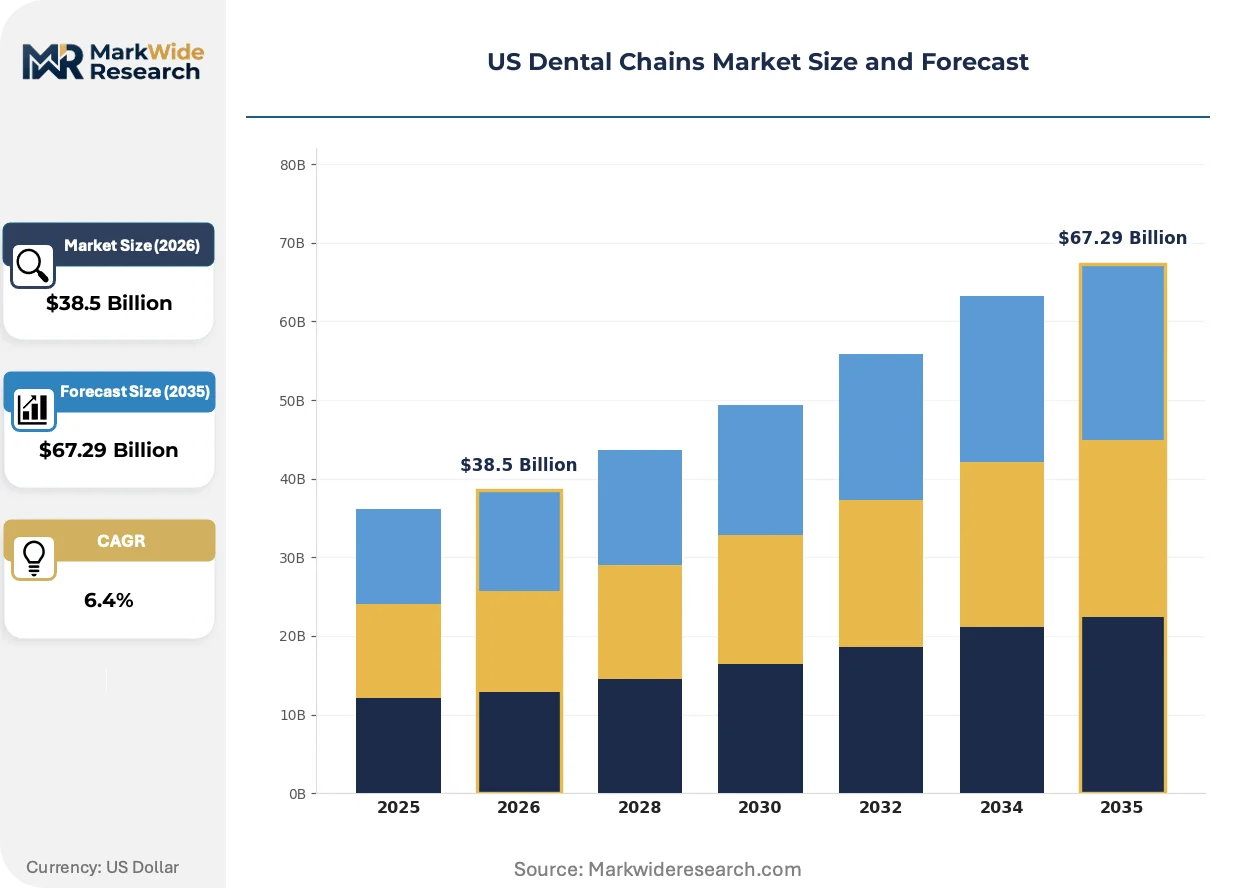
| Market Size in 2026 | $38.5 Billion |
| Market Size in 2035 | $67.29 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Dentistry, Orthodontics, Cosmetic Dentistry, Pediatric Dentistry Business Model: Franchise, Corporate-Owned, Joint Venture, Independent Patient Demographics: Adults, Seniors, Children, Families Technology Adoption: Tele-dentistry, Digital Imaging, CAD/CAM Systems, CRM Software |
| Companies Covered | Heartland Dental, The Aspen Group (TAG), Pacific Dental Services, Smile Brands, Dental Care Alliance, Affordable Care, Western Dental, Great Expressions Dental Centers, Sonrava Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Dental Chains Market Strategic Shifts & Innovations
Digital workflow integration is reshaping how US dental chains configure clinical space, with technology deployment decisions now preceding real estate selection rather than following it.
Intraoral scanning hardware is absorbing impression-taking volume across adult restorative and orthodontic intake workflows. Multi-location operators are standardizing on specific scanner ecosystems to enable centralized lab communication and reduce training friction. This technology compression is collapsing the traditional two-visit crown model into single-appointment production.
FDA medical device oversight of CAD/CAM milling systems and 3D printing resins is tightening premarket notification requirements for chairside manufacturing equipment. Capital investment timelines are lengthening as chains await 510(k) clearance confirmations before platform commitments. Smaller regional operators lacking dedicated regulatory affairs staff are deferring technology refresh cycles.
Patient acquisition channels are fragmenting away from insurance directory dependence toward direct-to-consumer digital engagement. Subscription membership plans and transparent fee schedules are displacing traditional payer-mediated search behavior in Sun Belt markets. This channel shift is most pronounced among uninsured and underinsured households in Florida and Arizona metropolitan corridors.
US Dental Chains Market Segmentation
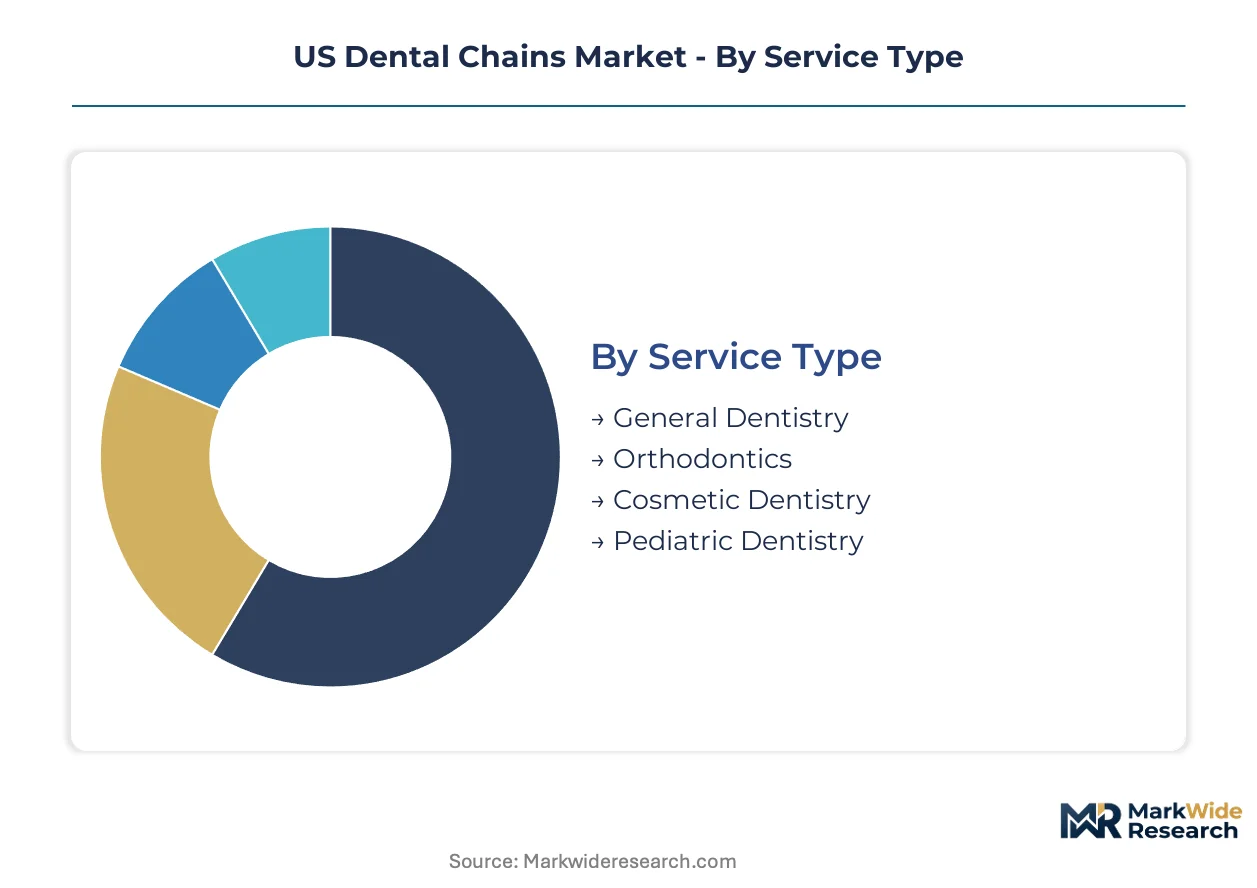
Service mix and operational architecture determine revenue stability and capital intensity for US dental chains. Patient demographic targeting shapes geographic expansion priorities across Sun Belt metropolitan corridors.
Service Type:
Standalone service lines operate with dedicated equipment and staffing protocols, while integrated multi-specialty platforms share infrastructure across treatment categories.
- General Dentistry:Preventive cleanings, diagnostic imaging, and basic restorative procedures form the clinical foundation. Demand concentrates in family-oriented suburban locations across Houston and Tampa where employer-sponsored dental benefits remain prevalent.
- Orthodontics:Clear aligner therapy and traditional bracket systems require specialized technician training and extended treatment protocols. Adult patient flow in Phoenix and Scottsdale is accelerating as direct-to-consumer marketing reduces stigma around later-life correction.
- Cosmetic Dentistry:Veneers, whitening, and aesthetic restorations command premium fee schedules outside insurance networks.
- Pediatric Dentistry:Child-specific behavioral techniques and smaller equipment footprints serve developmental age groups.
Volume placements concentrate in General Dentistry; the faster expansion belongs to Orthodontics.
Business Model:
Capital deployment patterns separate asset-heavy operators from those leveraging third-party infrastructure.
- Franchise:Licensees pay royalties for brand access and operational support while retaining local ownership. Texas and Florida markets show heavy franchise concentration due to favorable state dental board regulations on non-dentist ownership.
- Corporate-Owned:Centralized control over clinical protocols and technology procurement enables standardization. Arizona's Phoenix-Tucson corridor attracts corporate roll-ups seeking scale efficiencies in back-office functions.
- Joint Venture:Dentist equity participation aligns clinical autonomy with administrative support.
- Independent:Solo practitioners and small partnerships operate without chain affiliation.
Corporate-Owned models dominate capital deployment; Franchise arrangements are climbing the fastest.
Patient Demographics:
Reimbursement pathways and treatment frequency vary sharply across life-stage segments.
- Adults:Working-age patients aged 18-64 drive routine preventive volume through employer-sponsored coverage. Tampa and Orlando corridors show elevated adult demand from service sector employment clusters.
- Seniors:Medicare Advantage dental riders are unlocking previously uncovered patient pools. Houston's retiree migration patterns concentrate senior demand in suburban clinic networks.
- Children:Medicaid-dependent pediatric volume fluctuates with state-level eligibility decisions.
- Families:Multi-generational household targeting optimizes appointment scheduling efficiency.
Adult segments anchor revenue stability; Seniors are gaining share fastest.
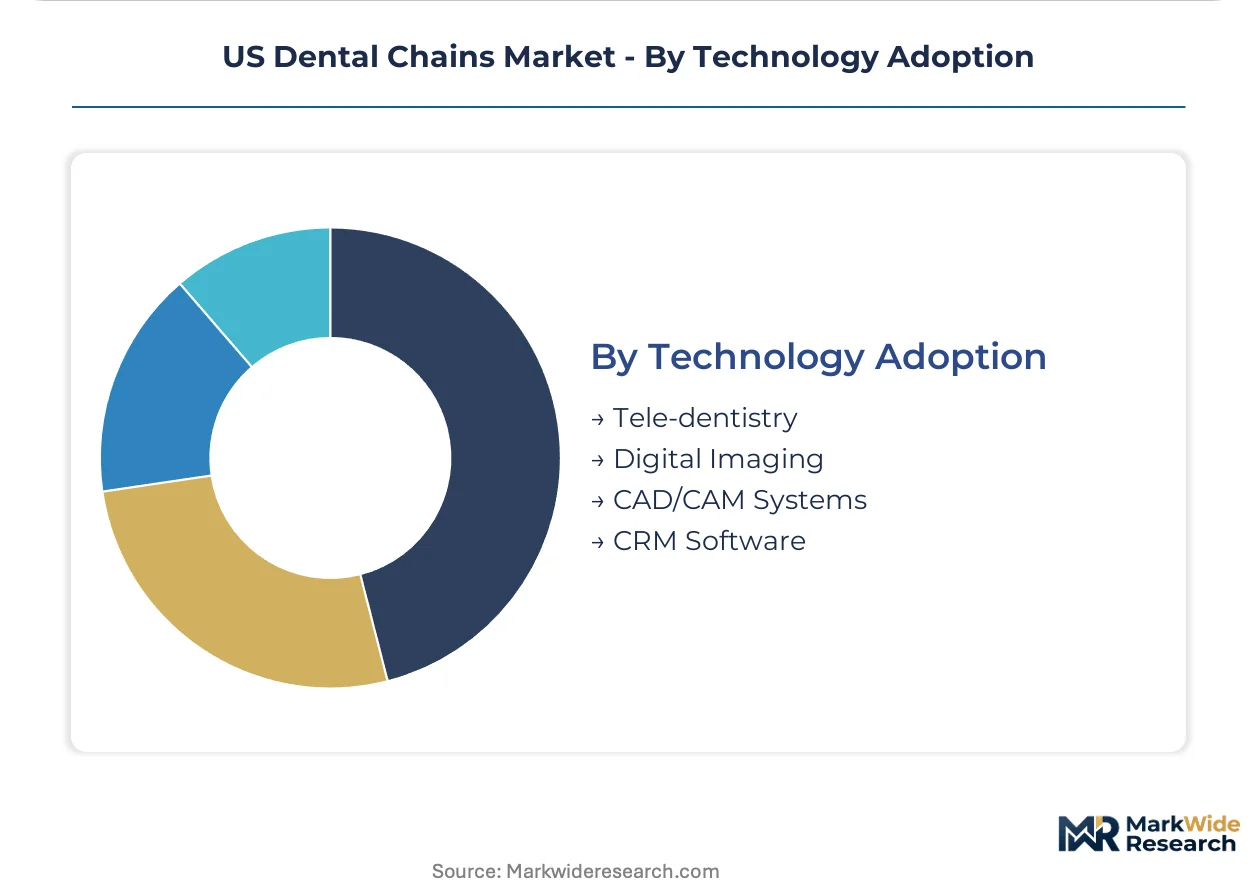
Technology Adoption:
Integration depth separates point solutions from platform-wide infrastructure commitments.
- Tele-dentistry:Remote consultation platforms filter emergency cases and extend reach into underserved rural counties. Arizona Medicaid programs have expanded reimbursement for synchronous video consultations.
- Digital Imaging:Intraoral scanners and CBCT systems replace analog radiography workflows. Phoenix-area chains standardize on specific scanner ecosystems to reduce training friction across acquired practices.
- CAD/CAM Systems:Chairside milling compresses crown delivery into single appointments.
- CRM Software:Patient communication and recall management tools reduce no-show rates.
Digital Imaging commands the largest installed base; Tele-dentistry is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US dental chains concentrate service delivery in high-growth metropolitan corridors while production of dental equipment and materials flows from specialized manufacturing zones. Patient demand clusters where retiree migration intersects with employer-sponsored benefit pools.
Texas
Houston and Dallas-Fort Worth metroplexes absorb expanding patient volume from employer relocation packages and Sun Belt migration. State dental board regulations permit non-dentist ownership structures that accelerate franchise model penetration. The Houston corridor anchors multi-specialty clinic networks targeting energy sector employee benefit pools.
Florida
Tampa and Orlando corridors concentrate Medicare Advantage enrollment growth among senior populations seeking comprehensive dental riders. Florida Medicaid program decisions on pediatric coverage directly influence safety-net clinic revenue stability. The I-4 corridor between Tampa and Orlando hosts dense clustering of corporate-owned facilities competing for retiree patient flow.
Arizona
Phoenix and Scottsdale markets show elevated clear aligner demand from adult patients responding to direct-to-consumer orthodontic marketing. Arizona Health Care Cost Containment System expanded tele-dentistry reimbursement for synchronous video consultations. The Phoenix-Tucson corridor attracts corporate roll-ups seeking back-office scale efficiencies.
California
Los Angeles and San Diego metropolitan areas present fragmented competitive landscapes with high specialist concentration. Cal/OSHA bloodborne pathogen standards impose sterilization protocol costs that scale with clinic network expansion. The Southern California corridor maintains premium cosmetic dentistry volume outside traditional insurance networks.
Ohio
Cleveland and Cincinnati markets demonstrate stable employer-sponsored coverage retention despite manufacturing employment shifts. State dental board continuing education mandates affect staffing costs for multi-location operators. The Ohio River Valley corridor supports mid-market chain positioning between premium coastal and value Sun Belt strategies.
US Dental Chains Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US dental chains landscape. Consolidation pressure intensifies as scale-dependent technology investments favor larger platform operators. Three archetypes dominate: doctor-led support organizations, franchise aggregators, and vertically integrated corporate platforms. M&A activity targets independent practice acquisition for patient base transfer, while technology standardization investments differentiate multi-location efficiency.
Within the support organization tier, Heartland Dental exemplifies the doctor-led model that preserves clinical autonomy while centralizing administrative functions. Smile Brands anchors franchisee-focused positioning through operational support systems that reduce individual operator overhead. Pacific Dental Services occupies the corporate-integrated archetype through proprietary practice management infrastructure and technology platform standardization.
| Leading Market Players |
|---|
| Heartland Dental |
| The Aspen Group (TAG) |
| Pacific Dental Services |
| Smile Brands |
| Dental Care Alliance |
| Affordable Care |
| Western Dental |
| Great Expressions Dental Centers |
| Sonrava Health |
| Others |
Cost & Logistics Intelligence
Thermoplastic aligner resin price indices cascade through US dental chain supply chains into three-tier pricing structures across premium, standard, and economy service levels. Input cost volatility from petroleum-derived polymers compresses margins on clear aligner procedures while elevating subscription membership plan attractiveness for uninsured patient segments. This cost transmission mechanism forces chains to rebalance equipment procurement timing against patient acquisition economics.
Pricing Analysis
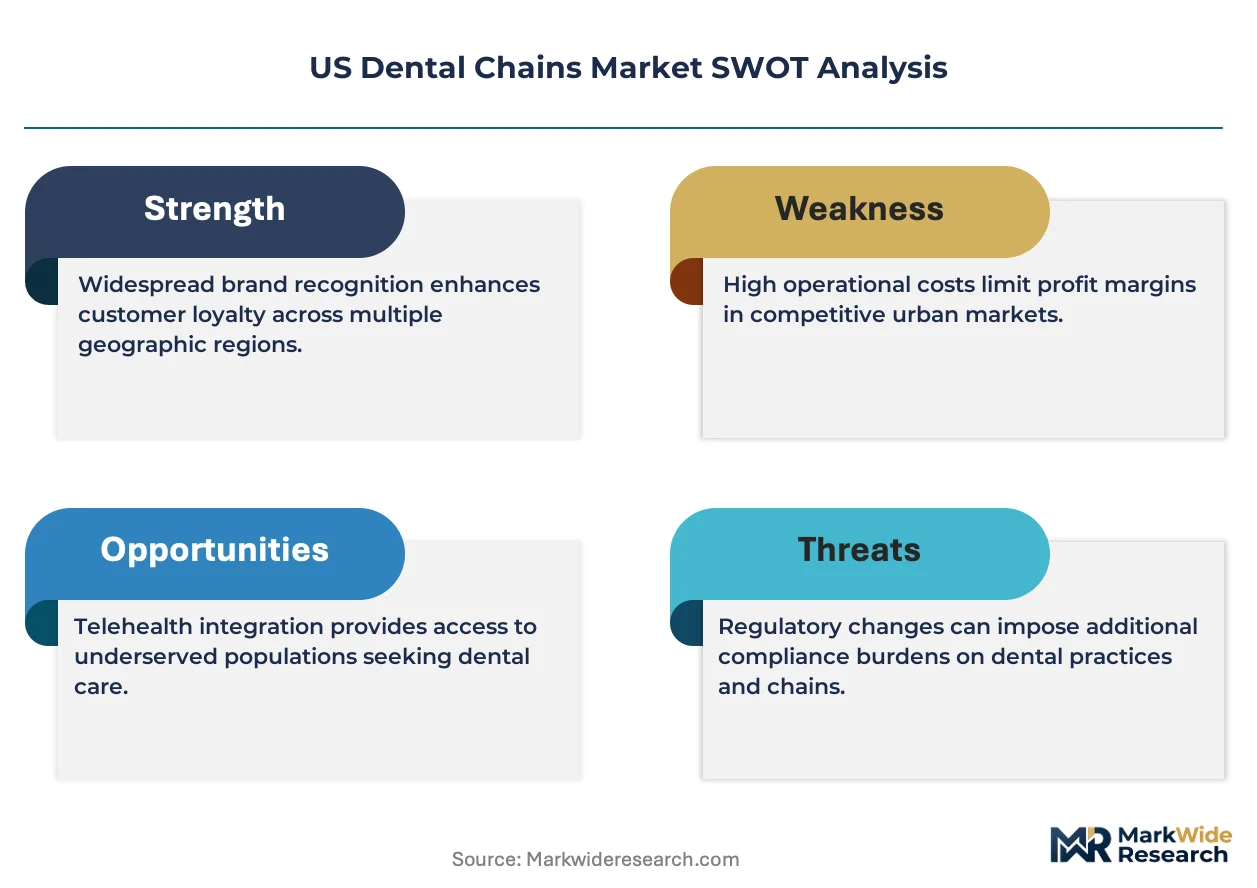
Margin tightening in economy-tier preventive services reflects state Medicaid reimbursement volatility and escalating OSHA compliance overhead. Three-tier pricing structure across premium, standard, and economy levels separates cosmetic fee-for-service procedures from insurance-mediated general dentistry and membership-based preventive bundles. Cost-down pressure on standard-tier restorative work accelerates because CAD/CAM capital depreciation demands higher chair utilization rates. Price sensitivity concentrates among uninsured households in Texas and Florida metropolitan corridors, while Medicare Advantage-enrolled seniors show reduced elasticity for comprehensive treatment packages.
Supply Chain Analysis
Regional distribution centers in Memphis and Dallas anchor hub-and-spoke patterns for chairside milling consumables and sterilization supplies. Manufacturing concentration for clear aligner thermoplastics centers on Germany and US specialty chemical producers, with scanner hardware sourcing from China and Japan optical component suppliers. Raw material dependencies include petroleum-based resins, precision optical sensors, and ceramic milling blanks. Single-source vulnerability around FDA-cleared aligner material formulations exposes chains to allocation constraints during supply shocks. Distribution runs through dental supply cooperatives and direct manufacturer relationships to clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US dental chains constitute a consolidation play where scale-dependent technology investments force sub-scale independent operators toward acquisition or exit. Same-day CAD/CAM deployment requirements and proprietary practice management platform development costs create insurmountable capital barriers for regional competitors lacking corporate backing.
For Market Incumbents: Lock in specialist dentist supply through equity participation structures and accelerated training pipelines before orthodontic labor markets tighten further. Acquire independent practices in Phoenix and Tampa corridors to transfer patient bases onto centralized billing platforms and standardize scanner ecosystems. Defensive consolidation against direct-to-consumer clear aligner entrants demands proprietary tele-dentistry triage integration and membership plan penetration in uninsured segments. For New Entrants and Emerging Players: Medicare Advantage dental expansion in Florida and Arizona opens a window for senior-focused clinic networks targeting retiree migration corridors with comprehensive care packages. White-space targets include Medicaid-dependent pediatric dentistry in Texas expansion counties and corporate occupational dental services for energy sector employers in Houston. Go-to-market positioning should emphasize transparent subscription pricing and same-day restorative capabilities to differentiate from insurance-mediated competitors. For Investors and Strategic Acquirers: The window for entry favors corporate-integrated platforms with proprietary technology infrastructure over fragmented franchise aggregators. Long-term viability hinges on patient data portability moats and cross-location scheduling efficiency rather than brand recognition alone. Acquisition target archetype: mid-scale regional chains with established dentist relationships but legacy practice management systems requiring modernization. Watch state-level Medicaid reimbursement decisions as the critical inflection indicator for safety-net clinic valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Practice Management Platform Development | Centralized billing and imaging integration creates patient record portability advantages across acquired locations. |
| Same-Day CAD/CAM Technology Deployment | Chairside crown production compresses appointment counts and elevates per-visit economics in restorative procedures. |
| Subscription Membership Plan Expansion | Bundled preventive care packages bypass traditional payer intermediaries in Texas and Florida uninsured segments. |
| Specialist Dentist Equity Partnership Structures | Doctor retention alignment addresses recruitment shortages in high-growth Phoenix and Tampa metropolitan markets. |
| Tele-Dentistry Triage Platform Integration | Remote consultation filtering optimizes emergency case routing and specialist referral efficiency across clinic networks. |
Research Approach
Multi-period observation of Medicare Advantage enrollment patterns, state Medicaid expansion decisions, and clear aligner procedure volume anchored the trend analysis, supplemented by interviews with dental practice owners, group procurement officers, state dental board administrators, and DSO operations executives. Secondary validation drew from CMS Medicare data, FDA 510(k) device clearance filings, state dental board regulatory records, and OSHA compliance disclosure databases. Bottom-up clinic count and revenue modeling triangulated against top-down market sizing from payer enrollment statistics and equipment manufacturer shipment data.
Input-output matrices mapped service line revenue contributions across general dentistry, orthodontics, cosmetic procedures, and pediatric care against capital requirements for scanner ecosystems, CAD/CAM milling systems, and practice management platform licensing. Segmentation dimensions modeled included service type, business model architecture, patient demographic targeting, and technology adoption depth across the analysis window. CAGRs were derived from patient volume growth trajectories, reimbursement rate assumptions, and equipment depreciation schedules. Industry-specific forecast inputs incorporated Sun Belt migration patterns and Medicare Advantage dental rider penetration curves.
Caveats apply where state-level Medicaid reimbursement reforms, FDA device clearance delays, or orthodontic specialist labor shortages could materially shift the outlook for safety-net dependent locations and same-day technology deployment timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Dental Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Orthodontic Services Market
Dental Services
Microdontia Treatment Market
Dental Services
Global Dental Support Organizations Market
Dental Services
United States Dental Services Market
Dental Services
Teledentistry Market
Dental Services
EMEA Dental Service Organization Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Services Market
Dental Services
Dental Service Organization Market
Dental Services
Periodontal Dental Service Market