
 Global Dental Restorative Market | 2026-2036
Global Dental Restorative Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Restorative Market Foresight
Germany is narrowing its position as a European manufacturing hub for precision-milled zirconia restorations, with dental laboratories in Cologne and Munich scaling CAD/CAM output. Dentsply Sirona leverages integrated digital workflow platforms spanning intraoral scanning to milling. Ivoclar Vivadent AG anchors premium ceramic and lithium disilicate supply chains through its Schaan headquarters and regional distribution nodes. GC Corporation specializes in glass ionomer formulations for emerging market price sensitivity.
Dental restorative materials encompass biocompatible substances engineered to reconstruct tooth structure lost to caries, trauma, or wear, with composite resins typically comprising silane-treated ceramic fillers in a Bis-GMA resin matrix cured via blue-light photoinitiators. Their primary purpose is to restore masticatory function and aesthetic contour while minimizing thermal expansion mismatch with natural dentin. Composite resin formulations command the broadest application scope across anterior and posterior indications, though ceramic and zirconia segments capture disproportionate margin pools in crown and bridge prosthetics. Glass ionomer cement retains defensive positioning in pediatric and geriatric applications where moisture tolerance and fluoride release outweigh mechanical demands.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements are extending market access durations for novel resin formulations and ceramic subclasses, favoring incumbents with established predicate devices and quality management systems. ISO 4049 and ISO 6872 standards govern mechanical property baselines for polymer-based and ceramic restorative materials respectively, creating compliance thresholds that filter regional suppliers. Japan's PMDA maintains distinct biocompatibility testing protocols that add regulatory layers for Asia-Pacific market entry. Stakeholders must monitor convergence between national dental device registries and environmental regulations targeting mercury-phase-down in amalgam, as this dual pressure reshapes material portfolios and manufacturing footprints.
Market Dynamics
Digital chairside workflows are compressing traditional laboratory intermediation, forcing material suppliers to reconfigure distribution architectures and technical support models around single-visit dentistry.
Growth Catalysts
- EU MDR biocompatibility documentation:Tightened predicate device requirements for permanent implantable materials are accelerating consolidation toward suppliers with established quality management systems and technical file libraries.
- Private dental practice digitization:Intraoral scanner penetration in US specialist clinics is pulling demand for compatible resin and ceramic blocks through integrated CAD/CAM procurement bundles.
- Lithium disilicate ceramic formulations:Superior flexural strength and translucency profiles are expanding anterior-posterior application scope beyond traditional crown and bridge limitations.
Market Restraints
- Zirconia powder supply concentration:Premium-grade yttria-stabilized zirconia feedstock production clusters in East Asian chemical processing hubs, creating geographic single-point vulnerability.
- Silver and rare earth input volatility:Photoinitiator chemistry and glass ionomer metallic oxide additives face commodity price swings that compress formulation margin predictability.
- Amalgam phase-down substitution ceiling:Environmental regulations targeting mercury elimination in EU member states are exhausting the addressable base of traditional material displacement.
Strategic Opportunities
- India's specialist training expansion:Government dental college capacity building and private prosthodontics fellowship growth are creating underpenetrated demand for premium ceramic systems.
- China's NMPA streamlined Class II pathways:Recent technical review efficiency reforms for dental materials are shortening market access timelines for compliant foreign suppliers.
- Chairside 3D printing convergence:Photopolymer resin formulation advances combined with desktop printer reliability improvements are enabling same-day temporary and definitive restoration production.
Industry Challenges
- CAD/CAM technician certification bottlenecks:Digital workflow competency gaps in traditional dental laboratory workforces are slowing technology adoption curves and support cost recovery.
- ISO 4049 and ISO 6872 harmonization delays:Divergent national adoption timelines for revised mechanical property testing standards are fragmenting product registration strategies.
- Legacy practice management system integration:Digital impression file compatibility constraints with established patient record architectures are creating workflow friction in multi-site dental groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Restorative Market |
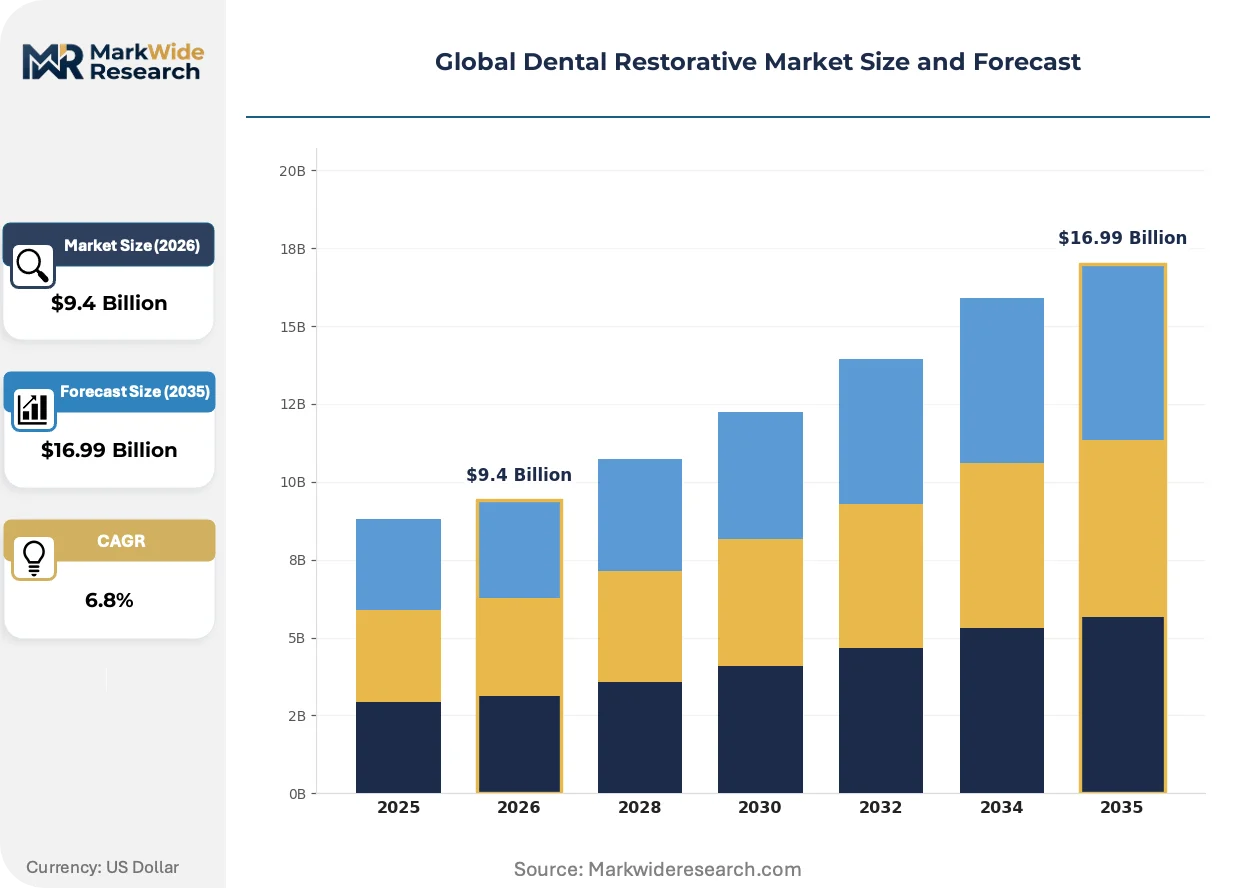
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resin, Amalgam, Glass Ionomer Cement, Ceramic, Resin-Modified Glass Ionomer, Gold Alloys Material Composition: Acrylic, Zirconia, Porcelain, Lithium Disilicate, Metal-Ceramic, Polycarbonate Application: Anterior Restorations, Posterior Restorations, Crowns, Bridges, Inlays, Onlays End User: Dental Clinics, Private Practices, Hospitals, Dental Laboratories, Academic Institutions, Mobile Dental Units |
| Companies Covered | 3M Company, Dentsply Sirona, Ivoclar Vivadent AG, Danaher Corporation, Institut Straumann AG, Zimmer Biomet Holdings, Inc., Septodont Holding, Envista Holdings Corporation, GC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Restorative Market Shifts & Advancements
Material science advances and regulatory convergence are simultaneously elevating performance baselines and compressing commercialization timelines across restorative categories.
Universal adhesive systems with simplified etch-and-rinse protocols are reducing technique sensitivity and chair time for composite resin placement. General practitioner adoption in Germany and the United States is accelerating as manufacturers bundle these chemistries with bulk-fill formulations. Single-bottle adhesive technology is rendering obsolete multi-step bonding systems that dominated the previous decade.
Japan's PMDA has implemented distinct biocompatibility testing protocols for resin-based restorative materials that exceed ISO 10993 baseline requirements. This regulatory layering is extending technical documentation preparation timelines for Asia-Pacific market entrants. Suppliers are responding by establishing Tokyo-based regulatory affairs capabilities and local clinical testing partnerships.
Dental service organizations are consolidating procurement authority across multi-clinic networks, shifting purchasing decisions from individual practitioners to centralized supply chain functions. This concentration is compressing supplier sales cycles and intensifying price negotiation leverage in the United States. Large group practices are unbundling after-sales technical support from material pricing, forcing manufacturers to demonstrate standalone value for training and warranty services.
Global Dental Restorative Market Segmentation
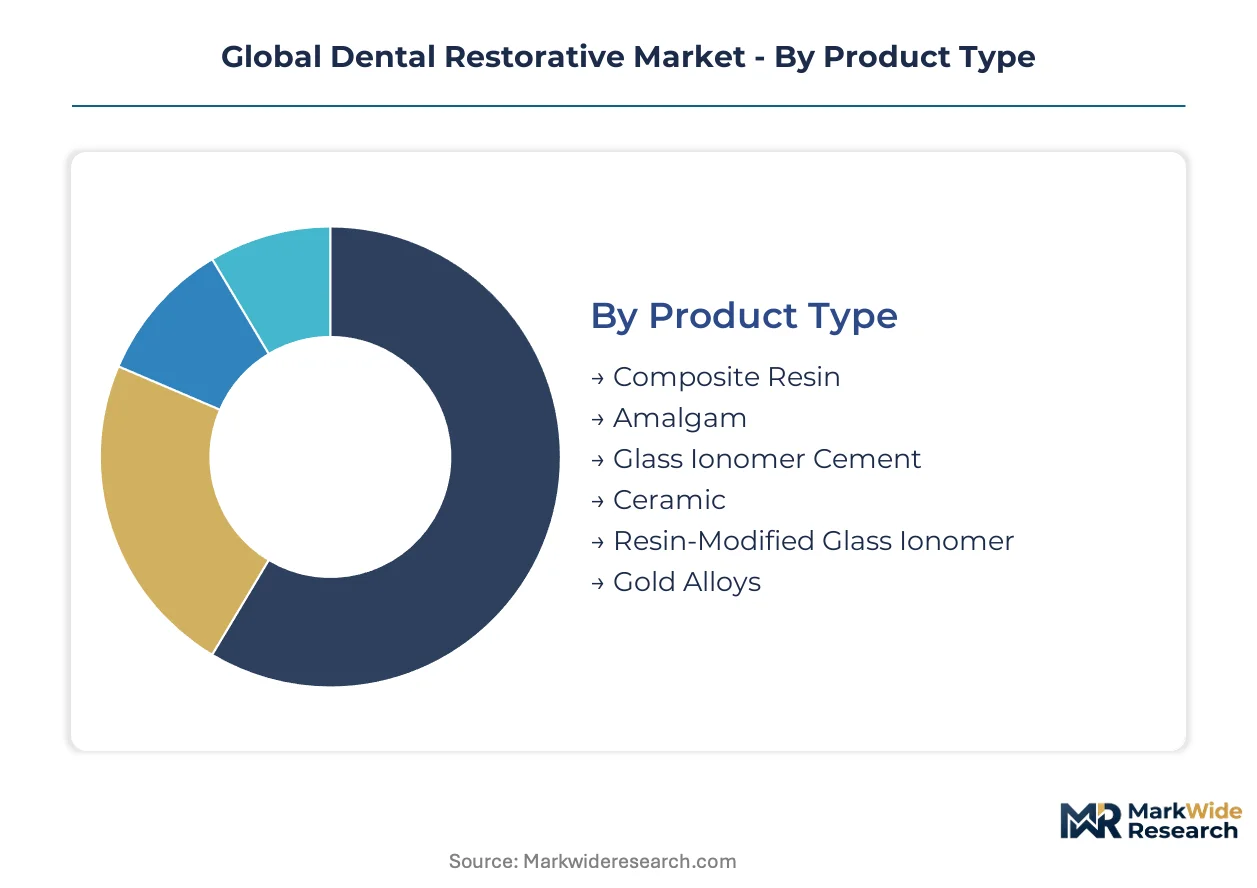
Segmentation in dental restorative materials reveals divergent service intensity requirements across product categories. Technical support demands vary sharply between chairside consumables and laboratory-fabricated prosthetics.
Product Type:
After-sales service intensity stratifies sharply across product categories, with ceramic systems requiring CAD/CAM technical support while composite resins demand chairside troubleshooting protocols.
- Composite Resin:Silane-treated ceramic fillers suspended in Bis-GMA resin matrices cure via blue-light photoinitiators. Demand concentrates in United States private practices deploying intraoral scanner-integrated workflows, where bulk-fill formulations compress placement time. Technical support focuses on shade-matching protocols and polymerization depth optimization.
- Ceramic:Zirconia and lithium disilicate blocks require precision milling parameters and sintering calibration. Germany's Cologne and Munich laboratory clusters drive premium-grade consumption, supported by Dentsply Sirona's integrated platform training infrastructure.
- Amalgam:Mercury-containing alloy facing environmental phase-down regulations across EU member states. Remaining demand localizes in price-sensitive emerging markets with limited enforcement capacity.
- Glass Ionomer Cement:Fluoride-releasing formulation retains defensive positioning in pediatric and geriatric moisture-tolerant applications.
- Resin-Modified Glass Ionomer:Hybrid chemistry bridges mechanical performance and chemical adhesion for intermediate restoration durability.
- Gold Alloys:Precision-cast noble metal restorations persist in specific posterior indications despite material cost premiums.
Composite resin holds the largest share; momentum sits with ceramic systems.
Material Composition:
Cost tier stratification separates premium-grade zirconia from economy acrylic alternatives, with mid-range lithium disilicate capturing expanding anterior-posterior crossover applications.
- Zirconia:Yttria-stabilized tetragonal polycrystals deliver flexural strength exceeding 900 MPa for posterior crown durability. Premium-grade powder production concentrates in East Asian chemical processing hubs, creating supply vulnerability.
- Lithium Disilicate:Controlled crystallization yields superior translucency with adequate strength for anterior-posterior bridge applications. China's NMPA streamlined Class II pathways accelerate compliant foreign supplier penetration.
- Acrylic:Provisional restoration material dominates temporary crown and bridge fabrication.
- Porcelain:Feldspathic and aluminous variants retain aesthetic-layer applications in metal-ceramic systems.
- Metal-Ceramic:Porcelain-fused-to-metal substructures persist in high-strength posterior indications.
- Polycarbonate:Thermoplastic resin serves provisional and orthodontic temporary applications.
Zirconia commands premium pricing tiers; lithium disilicate climbs the fastest.
Application:
Application scope determines margin structure, with single-unit restorations flowing through chairside workflows while multi-unit prosthetics sustain laboratory intermediation.
- Crowns:Full-coverage restorations represent the highest-volume definitive prosthetic category. United States dental service organization consolidation shifts procurement authority to centralized supply chain functions.
- Anterior Restorations:Aesthetic-critical indications demand translucency-optimized ceramics and layered composite techniques. India's specialist training expansion creates underpenetrated demand for premium ceramic systems.
- Posterior Restorations:Masticatory load-bearing requirements prioritize mechanical strength over optical properties.
- Bridges:Multi-unit fixed prosthodontics retain laboratory fabrication dependence despite digital impression adoption.
- Inlays:Conservative cavity preparations preserve tooth structure with indirect ceramic or composite fabrication.
- Onlays:Cusp-covering restorations bridge direct and indirect technique classifications.
Crowns hold the largest share; anterior restorations gain share fastest.
End User:
Customer type dictates purchasing behavior, with dental laboratories negotiating bulk material contracts while private practices prioritize chairside convenience and technical support responsiveness.
- Dental Laboratories:Centralized fabrication facilities purchase zirconia blocks and ceramic ingots in volume. Germany's precision-milled output scaling drives regional supply chain concentration.
- Private Practices:Solo and group practitioners procure chairside-compatible resin and ceramic systems. United States intraoral scanner penetration pulls demand through integrated CAD/CAM procurement bundles.
- Dental Clinics:Multi-chair facilities balance inventory efficiency against procedure mix diversity.
- Hospitals:Institutional procurement emphasizes contract pricing and standardization across departments.
- Academic Institutions:Training programs drive early-career material preference formation through curriculum-specified products.
- Mobile Dental Units:Field-deployed services prioritize moisture-tolerant glass ionomer formulations for environmental reliability.
Dental laboratories hold the largest share; private practices expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and intraoral scanner penetration anchor United States demand, while EU MDR technical documentation requirements reshape European supplier consolidation. China's NMPA streamlines Class II pathways for compliant foreign entrants. Japan's PMDA maintains distinct biocompatibility protocols extending Asia-Pacific market access timelines.
United States
Dental service organizations consolidate procurement authority across multi-clinic networks, compressing supplier sales cycles. FDA 510(k) predicate device requirements favor incumbents with established quality management systems. Specialist training capacity expansion in urban corridors drives premium ceramic system adoption.
Germany
Precision-milled zirconia output scales in Cologne and Munich laboratory clusters. EU MDR biocompatibility documentation tightens permanent implantable material standards. CAD/CAM platform training infrastructure concentrates around integrated digital workflow providers.
China
Government dental college capacity building and private prosthodontics fellowship growth create underpenetrated demand. NMPA streamlined Class II technical review reforms shorten market access timelines for compliant foreign suppliers. Yangtze River Delta chemical processing hubs anchor premium-grade yttria-stabilized zirconia feedstock production.
Japan
PMDA distinct biocompatibility testing protocols for resin-based materials exceed ISO 10993 baseline requirements. Regulatory affairs capabilities and local clinical testing partnerships concentrate in Tokyo. METI industrial policy supports dental device registry convergence with environmental regulations.
India
Government dental college capacity building and private prosthodontics fellowship growth drive specialist training expansion. Central Drugs Standard Control Organization oversees medical device quality standards. Metropolitan dental laboratory networks in Mumbai and Delhi-NCR scale CAD/CAM technical competency programs.
Global Dental Restorative Market Competitive Landscape
Capability concentration sits with integrated digital workflow platform providers; scale advantage sits with diversified multinational dental conglomerates. The market structures around three tiers: premium ceramic system specialists, broad-line consumables suppliers, and regional price-competitive formulators. Consolidation pressures intensify as EU MDR technical file requirements filter subscale competitors. Dominant competitive moves include strategic partnerships around chairside 3D printing convergence and backward integration into zirconia powder supply security.
Among Switzerland-based precision manufacturers, Institut Straumann AG exemplifies the premium implantable materials archetype through its Schaan headquarters positioning. Dentsply Sirona occupies the integrated digital workflow tier, leveraging its Charlotte and Bensheim presence across intraoral scanning to milling value chains. GC Corporation represents the Asia-Pacific formulation specialist model, with Tokyo-based operations anchoring glass ionomer chemistry for emerging market price sensitivity.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona |
| Ivoclar Vivadent AG |
| Danaher Corporation |
| Institut Straumann AG |
| Zimmer Biomet Holdings, Inc. |
| Septodont Holding |
| Envista Holdings Corporation |
| GC Corporation |
| Others |
Supply & Pricing Matrix
Yttria-stabilized zirconia powder concentration in East Asian chemical processing hubs determines both premium-ceramic pricing spreads and supply chain redundancy gaps. FDA 510(k) and EU MDR compliance costs propagate downstream as tiered certification premiums, compressing margin buffers for non-integrated formulators while rewarding incumbents with captive technical file libraries.
Pricing Analysis
German laboratory clusters command 15-25% premiums over Southeast Asian milling centers for identically graded zirconia blocks, reflecting CAD/CAM technical support bundling and sintering calibration guarantees. Three-tier pricing structure across premium, standard, and economy levels separates ISO 6872-certified lithium disilicate from uncertified economy ceramics and provisional-grade acrylics. Cost compression in economy resin segments is intensifying because dental service organization procurement consolidation unbundles after-sales support from material pricing. Pediatric and mobile dental units exhibit highest price sensitivity, while German and United States prosthodontic specialists absorb premium ceramic markups for anterior aesthetic cases.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts between Japanese glass ionomer formulators and Indian distributor networks, straining working capital for mid-tier suppliers. Premium-grade zirconia feedstock draws from China, Japan, and South Korea; photoinitiator chemistry rests on German and United States specialty chemical outputs; rare earth oxide additives for glass ionomer formulations hinge on Chinese and Australian mining operations. Single-source vulnerability concentrates in yttria-stabilized powder supply, where three chemical processors control majority global capacity. Distribution runs through regional dental laboratory networks for ceramic blocks, while chairside resins flow through integrated CAD/CAM procurement bundles direct to United States private practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chairside 3D printing convergence represents an early-cycle expansion tailwind, with photopolymer formulation advances compressing same-day restoration production timelines below traditional laboratory intermediation. Penetration curves for intraoral scanner-integrated workflows in United States specialist clinics validate technology adoption acceleration.
For Market Incumbents: Pre-empt chairside 3D printing resin formulation standardization by locking exclusive photopolymer supply agreements with desktop printer manufacturers before open-platform chemistry commoditization accelerates. Backward integration into yttria-stabilized zirconia powder production secures margin control against East Asian feedstock price volatility. Defensive patent positioning around universal adhesive simplified-etch protocols protects composite resin attachment revenue streams from generic formulation erosion.
For New Entrants and Emerging Players: India's government dental college capacity building and private prosthodontics fellowship growth create underpenetrated demand for premium ceramic systems with localized technical support infrastructure. China's NMPA streamlined Class II pathways offer fastest regulatory access for compliant foreign suppliers with existing ISO 13485 quality systems. Target chairside 3D printing resin formulations as the most penetrable segment, leveraging open-platform printer compatibility as the primary go-to-market angle against incumbent closed-system bundling.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors integrated digital workflow platform providers with captive CAD/CAM training infrastructure. Long-term viability over the next decade hinges on regulatory compliance scale advantages as EU MDR technical documentation requirements filter subscale competitors. Acquisition target archetype: mid-cap ceramic system specialists with established predicate device libraries and regional laboratory network relationships. Monitor FDA 510(k) clearance timeline extensions for novel resin subclasses as the inflection signal for incumbent consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconia Powder Supply | Captive feedstock production insulates margin predictability against East Asian chemical processing concentration. |
| Chairside 3D Printing Resin Formulation Partnership | Exclusive photopolymer supply agreements with desktop printer manufacturers preempt open-platform commoditization. |
| CAD/CAM Technical Training Infrastructure Expansion | Platform-locked education programs create switching costs for German and United States laboratory customers. |
| Universal Adhesive Patent Portfolio Defense | Simplified etch-and-rinse protocol IP protection sustains composite resin premium pricing against generic erosion. |
| India Specialist Training Program Sponsorship | Early-career curriculum specification at government dental colleges shapes long-term material preference formation. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filing records, and ISO 4049/6872 standard revision drafts preceded structured interviews with dental laboratory technical directors, private practice prosthodontists, GPO procurement managers, and CAD/CAM platform training specialists. Secondary validation drew from customs trade data for zirconia powder imports, dental device registration filings with China's NMPA and Japan's PMDA, and SEC 10-K segment disclosures from listed dental conglomerates. Bottom-up demand modeling for resin and ceramic consumption triangulated against top-down market sizing from national dental workforce statistics and procedure volume estimates.
Assumptions held intraoral scanner penetration curves and EU MDR compliance cost trajectories within observed historical patterns while varying China's NMPA review efficiency reforms and India's specialist training expansion pace across sensitivity scenarios. Segmentation modeling spanned product type, material composition, application scope, and end-user channel, with additional dimensioning by regulatory certification tier and digital workflow integration level. CAGRs derived from logistic adoption curve fitting for chairside technologies and linear extrapolation for mature laboratory-fabricated categories, with ceramic system growth rates anchored to Germany and United States precision-milled output scaling.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by mid-cap ceramic specialists or rapid open-platform 3D printing standardization would shift outcomes beyond modeled ranges. Macroeconomic deviation in rare earth and silver commodity markets, regulatory acceleration of amalgam phase-down timelines, or technological breakthrough in bioprinted dental tissue substitutes would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Dental Apex Locator Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
Global Dental Microscope Market