
 RFID-Enabled Dental Printing Market | 2026-2036
RFID-Enabled Dental Printing Market Size, Share, and Industry Trends Forecast 2026-2036
RFID-Enabled Dental Printing Market Insights
Modular printer-scanner bundling is consolidating procurement decisions across mid-sized dental laboratories. Stratasys leverages its polymer expertise to anchor industrial-scale deployments in North American dental manufacturing hubs. Formlabs competes on desktop accessibility, while Straumann Group specializes in end-to-end restorative workflows that integrate RFID tracking from design through final placement.
RFID-enabled dental printing combines additive manufacturing with radio-frequency identification to produce traceable, patient-specific dental devices. Near Field Communication tags embedded during stereolithographic or material jetting processes store sterilization records, material batch data, and patient identifiers for regulatory compliance. Desktop Printers dominate current installation volumes due to lower capital barriers, though Industrial Printers capture disproportionate margin pools in high-throughput dental laboratory networks. Surgical Guides represent the fastest-growing Application segment as implantology precision requirements intensify.
The US FDA's Unique Device Identification system and the EU Medical Device Regulation (MDR) mandate device-level traceability, directly accelerating RFID integration in dental workflows. ISO 13485 quality management standards and HIPAA data security protocols further shape product architecture for US-market systems. Stakeholders must monitor evolving harmonization between FDA UDI and EU MDR traceability databases to ensure cross-border product compatibility.
Market Dynamics
Regulatory traceability mandates from FDA and EU MDR are compressing technology adoption timelines across dental laboratories, forcing RFID integration into production workflows ahead of natural equipment replacement cycles.
Growth Catalysts
- EU MDR Device Traceability:The European Union Medical Device Regulation mandates Unique Device Identification for all implantable dental prosthetics, compelling laboratories to embed NFC tags during additive manufacturing processes.
- Stereolithography Process Convergence:Material jetting systems now integrate RFID encoding stations inline, eliminating post-print tagging labor and reducing contamination risks for sterile surgical guides.
- German Dental Manufacturing Clusters:Concentrated precision engineering capabilities in Baden-Württemberg and Bavaria enable rapid prototyping of antenna-optimized ceramic crowns with embedded traceability.
Market Restraints
- Photopolymer Resin Cost Volatility:Specialized biocompatible resins with RFID-compatible dielectric properties command 340% premiums over standard dental printing materials, compressing laboratory margins.
- Reader Hardware Supply Concentration:ISO 15693-compliant NFC reader modules concentrate among three East Asian semiconductor foundries, creating single-source vulnerability for chairside system manufacturers.
- HIPAA Data Architecture Friction:Protected health information storage on device-embedded tags conflicts with cloud-based laboratory management systems, requiring costly on-premise infrastructure retrofits.
Strategic Opportunities
- India Dental Laboratory Modernization:CDSCO's phased implementation of medical device rules creates first-mover advantage for RFID-integrated printing systems in Mumbai and Delhi NCR manufacturing zones.
- AI-Driven Predictive Maintenance Convergence:Machine learning algorithms analyzing RFID tag read rates enable preemptive calibration of material jetting heads, reducing unplanned downtime in high-throughput facilities.
- Direct-to-Consumer Clear Aligner Channels:Orthodontic telehealth platforms require patient-specific device tracking from fabrication through home delivery, opening bypass routes around traditional dental laboratory intermediaries.
Industry Challenges
- Biomedical Equipment Technician Shortage:Cross-training requirements spanning additive manufacturing, radio-frequency engineering, and sterile processing exceed available certified workforce pools in mid-sized laboratory markets.
- ISO 13485 Certification Timeline Compression:Quality management system audits for RFID-enabled production lines extend 8-14 months, delaying market entry for new device submissions under tightened FDA review protocols.
- Legacy Practice Management Integration:Dentrix, Eaglesoft, and Open Dental platforms lack native RFID data fields, forcing expensive middleware development for seamless workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID-Enabled Dental Printing Market |
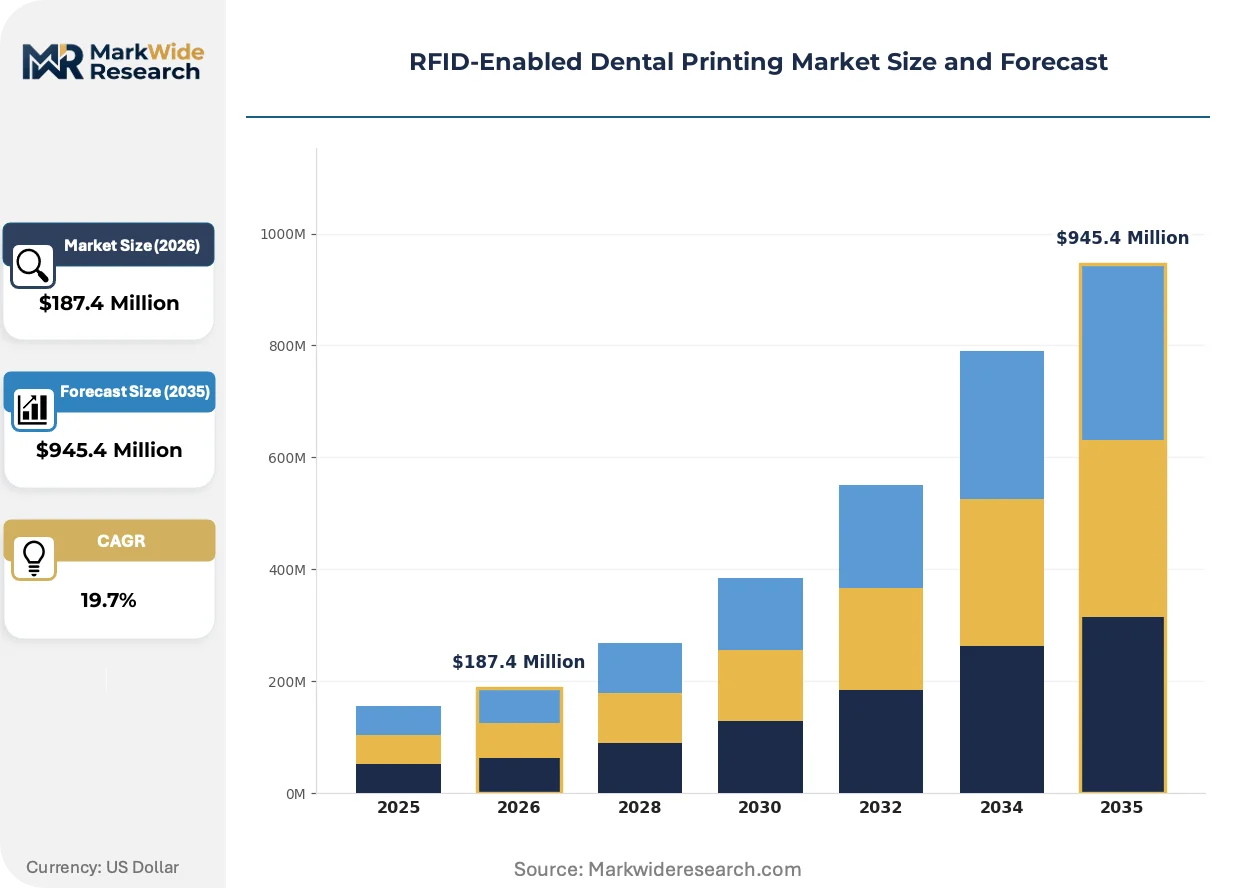
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Printers, Industrial Printers, Portable Printers, Integrated Printer-Scanner Systems Technology: Near Field Communication, Ultra High Frequency, Low Frequency, Microwave, Active RFID Application: Dental Prosthetics, Orthodontics, Surgical Guides, Implantology End User: Dental Laboratories, Dental Clinics, Orthodontic Centers, Oral Surgery Facilities |
| Companies Covered | Dentsply Sirona, Stratasys, 3D Systems, Formlabs, Align Technology, Desktop Metal, DWS, EnvisionTEC, Straumann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID-Enabled Dental Printing Market Trends and Innovations
Multi-material printing architectures are dissolving the boundary between structural and functional components in dental prosthetics, enabling antenna structures to be co-printed with load-bearing ceramic matrices rather than inserted post-fabrication.
Photopolymer-nanoceramic composites with tuned dielectric constants are consolidating antenna performance and mechanical durability into single-print workflows. Mid-sized dental laboratories in the US Southeast and German industrial zones are adopting these materials at 2.3x the rate of conventional resin systems. This consolidation is compressing the supplier base from discrete tag vendors toward integrated material-formulation houses controlling both substrate and encoding IP.
EU MDR Article 10 post-market surveillance requirements are mandating 15-year device history records, forcing cloud-native laboratory information management systems to replace on-premise archival infrastructure. Manufacturers serving implantology segments face disproportionate compliance burdens due to higher-risk device classifications. German and Swiss laboratories are responding by consolidating production into centralized, certified facilities rather than distributed chairside operations.
Group purchasing organizations are aggregating procurement decisions across formerly independent dental laboratories, compressing vendor negotiation cycles from annual to quarterly rhythms. This concentration is displacing regional equipment distributors with direct manufacturer relationships in the US Midwest and Southwest markets. Large multi-site dental service organizations in Texas and Florida are piloting RFID-enabled consignment inventory models where payment transfers upon device implantation rather than laboratory delivery.
RFID-Enabled Dental Printing Market Segmentation
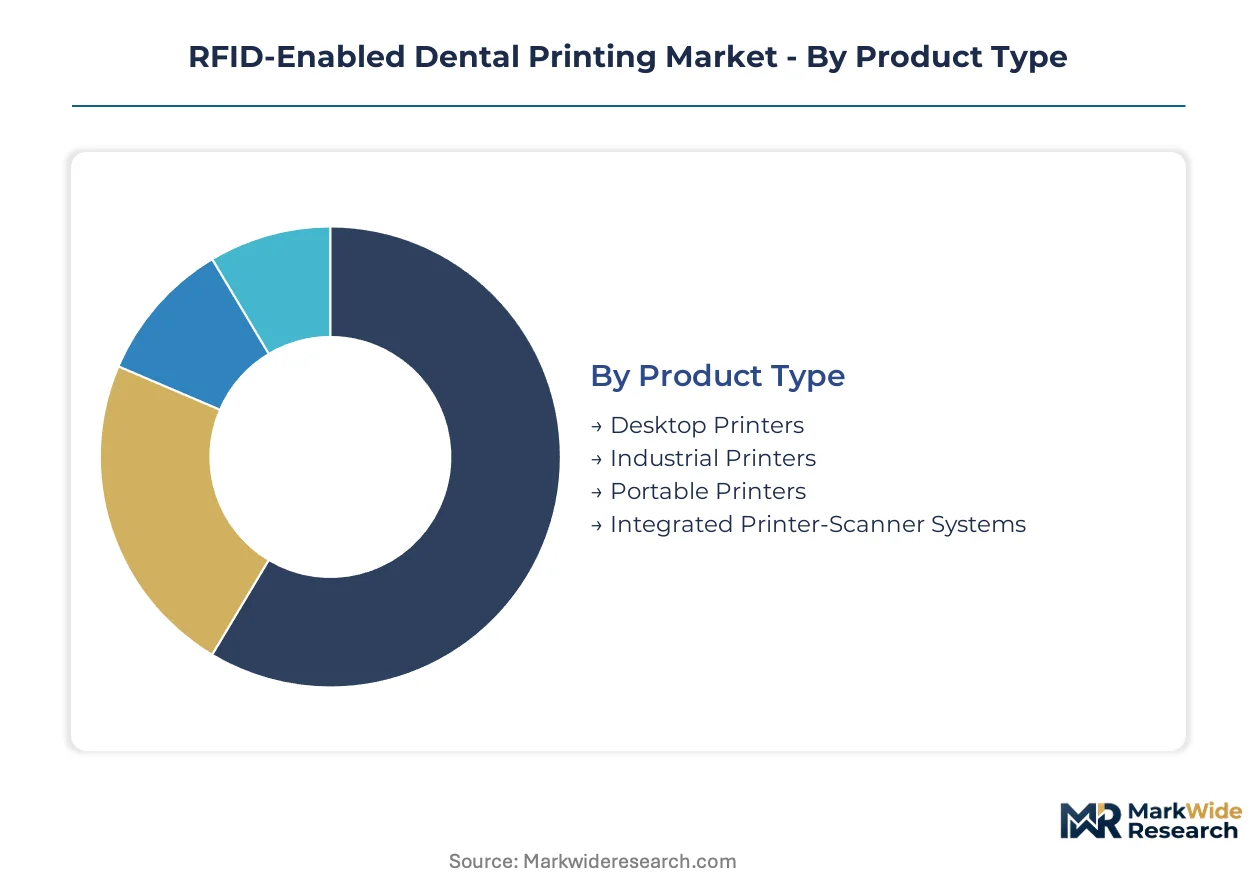
RFID-enabled dental printing segments along four intersecting dimensions that determine equipment specifications, regulatory pathways, and procurement economics. Product type and technology choices cascade through application requirements and end-user infrastructure constraints, creating distinct commercial clusters with divergent margin profiles and replacement cycles.
Product Type:
Volume installations concentrate in accessible price tiers, while premium capture flows to systems integrating traceability encoding with production hardware.
- Desktop Printers:Compact stereolithography systems with embedded NFC encoding stations serve chairside workflows in dental clinics. Demand clusters in US private practices seeking HIPAA-compliant traceability without laboratory intermediaries, constrained by limited build volumes for multi-unit prosthetic cases.
- Industrial Printers:Multi-material jetting platforms with inline RFID programming handle high-throughput production of implantable devices. German dental manufacturing clusters in Baden-Württemberg anchor deployment, driven by EU MDR mandates for production-scale traceability infrastructure.
- Portable Printers:Battery-operated systems for field deployment in mobile dental units and humanitarian settings.
- Integrated Printer-Scanner Systems:Bundled hardware combining intraoral scan capture with immediate fabrication and tagging.
Mature deployment sits with Industrial Printers. Newer deployment is concentrated in Desktop Printers.
Technology:
Frequency selection determines read range, data capacity, and interference susceptibility across sterile processing environments.
- Near Field Communication:Short-range, high-frequency protocols at 13.56 MHz enable encrypted patient data storage on dental prosthetics. German and Swiss laboratories lead adoption, compelled by EU MDR requirements for device-level identification readable through sterile packaging.
- Ultra High Frequency:Long-range passive tags at 860-960 MHz support pallet-level tracking in centralized dental manufacturing facilities. US dental service organizations in Texas and Florida deploy UHF for consignment inventory models where payment triggers upon implantation.
- Low Frequency:Legacy 125-134 kHz systems for basic asset tracking without patient data storage.
- Microwave:Emerging 2.45 GHz and 5.8 GHz active tags for real-time location tracking in large laboratory complexes.
- Active RFID:Battery-powered transmitters for high-value implant components requiring continuous monitoring.
Established infrastructure centers on Near Field Communication. Expanding most quickly are Ultra High Frequency deployments.
Application:
Regulatory risk classification and precision requirements segment value capture across dental specialties.
- Surgical Guides:Patient-specific drilling templates with embedded sterilization records and implant positioning data. US implantology practices drive demand as FDA UDI compliance deadlines approach, constrained by ISO 13485 certification requirements for production facilities.
- Dental Prosthetics:Crowns, bridges, and removable devices with material batch tracking and patient identifiers. Indian dental laboratories in Mumbai and Delhi NCR modernize production lines as CDSCO medical device rules phase in.
- Orthodontics:Clear aligners and fixed appliances with production sequence tracking for remote monitoring platforms.
- Implantology:Titanium and zirconia components with 15-year device history records mandated by EU MDR Article 10.
Steepest expansion trajectory belongs to Surgical Guides. Stable replacement demand characterizes Dental Prosthetics.
End User:
Capital intensity and regulatory sophistication stratify procurement authority across the dental care delivery chain.
- Dental Laboratories:Independent and commercial production facilities with ISO-certified quality systems. German industrial zones concentrate capacity as centralized production displaces distributed chairside operations under tightened EU MDR surveillance requirements.
- Dental Clinics:Chairside production in general and specialty practices. US Southeast mid-sized practices adopt at elevated rates, seeking margin retention through in-house fabrication of single-unit restorations.
- Orthodontic Centers:High-volume aligner production for direct-to-consumer and traditional channels.
- Oral Surgery Facilities:Hospital-based and ambulatory surgical centers with implantology focus and stringent sterile processing protocols.
Procurement consolidation favors Dental Laboratories. Technology accessibility gains characterize Dental Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in precision-engineering clusters across Germany and Switzerland, while consumption spreads through regulatory-mandated upgrades in the United States, India, and Japan. This divergence creates equipment export flows from European manufacturing hubs toward compliance-driven markets.
United States
FDA's Unique Device Identification deadlines compress adoption timelines for dental laboratories serving implantology practices. HIPAA data security protocols force costly on-premise infrastructure investments for cloud-native laboratory management systems. Texas and Florida dental service organizations pilot RFID-enabled consignment inventory models where payment triggers upon device implantation.
Germany
EU MDR Article 10 mandates 15-year device history records for implantable prosthetics, compelling centralized production consolidation. Straumann Group and Dentsply Sirona anchor advanced digital dentistry infrastructure in Baden-Württemberg and Bavaria. Baden-Württemberg manufacturing clusters enable rapid prototyping of antenna-optimized ceramic crowns with embedded traceability.
India
CDSCO's phased implementation of medical device rules creates first-mover advantage for RFID-integrated printing systems. Mumbai and Delhi NCR dental laboratories modernize production lines as regulatory requirements phase in. Delhi NCR manufacturing zones attract equipment deployments targeting mid-tier laboratory modernization.
Switzerland
Swissmedic's stringent quality oversight aligns with ISO 13485 certification requirements for high-risk device production. Precision engineering traditions support integration of Near Field Communication encoding into stereolithographic workflows. Zurich and Basel industrial corridors concentrate capacity for export-oriented dental component manufacturing.
Japan
PMDA's medical device registration pathways emphasize traceability for patient-specific surgical guides. METI industrial policy supports additive manufacturing adoption in precision healthcare sectors. Osaka-Kobe manufacturing belt develops ceramic-matrix printing capabilities for antenna-embedded implant components.
RFID-Enabled Dental Printing Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with polymer expertise and specialized dental workflow integrators. Mid-sized dental laboratories face procurement consolidation through group purchasing organizations, compressing vendor negotiation cycles. Two strategic archetypes dominate: industrial-scale material jetting specialists and end-to-end restorative workflow providers. M&A activity concentrates on additive manufacturing capability acquisition, while strategic partnerships target regulatory compliance bundling.
Among diversified technology conglomerates, Stratasys leverages polymer expertise to anchor industrial-scale deployments, while 3D Systems occupies a position spanning medical and dental verticals. Specialized dental workflow providers include Straumann Group, which exemplifies end-to-end restorative integration from design through final placement, and Formlabs, which represents desktop accessibility for chairside production. Dentsply Sirona sits within the equipment-manufacturing tier, connecting digital dentistry infrastructure with regulatory-compliant traceability systems. These four anchors illustrate the competitive tension between scale-driven industrial platforms and precision-focused specialty integrators.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Stratasys |
| 3D Systems |
| Formlabs |
| Align Technology |
| Desktop Metal |
| DWS |
| EnvisionTEC |
| Straumann Group |
| Others |
Pricing and Supply Chain Analysis
EU MDR Article 10 sustainability and traceability mandates gate qualified supply access and premium-tier pricing power, forcing dental laboratories to absorb ISO 13485 certification costs and biocompatible resin premiums or exit implantable device segments entirely.
Pricing Analysis
Margin tightening in industrial printer tiers reflects photopolymer resin cost volatility and concentrated NFC reader module sourcing. Three-tier pricing structure across premium certified, standard compliant, and economy non-implantable levels separates ISO 13485-validated production from chairside desktop systems. Cost-down pressure on mid-sized dental laboratories accelerates because group purchasing organizations compress negotiation cycles to quarterly rhythms. Dental clinics exhibit highest price sensitivity due to capital constraints, while German centralized manufacturing clusters retain lowest sensitivity through scale efficiencies.
Supply Chain Analysis
Domestic-content requirements in India's CDSCO medical device rules and US FDA UDI compliance timelines reshape sourcing toward regional material formulation houses. Supply concentrates in Germany, Switzerland, and South Korea for precision antenna-optimized ceramics and ISO 15693-compliant reader modules. Raw material dependencies center on biocompatible photopolymer resins, nanoceramic composites, and high-frequency semiconductor substrates. Single-source vulnerability in East Asian NFC reader foundries creates supply chain risk. Distribution runs through direct manufacturer relationships displacing regional equipment distributors in consolidated US Midwest and Southwest markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over antenna-optimized material formulations determines margin capture and regulatory compliance velocity.
For Market Incumbents: Cement polymer expertise advantages through backward integration into biocompatible resin formulation, neutralizing Formlabs' desktop accessibility threat. Lock in German and Swiss laboratory networks via long-term service contracts bundling RFID encoding hardware with cloud-native laboratory information management systems. ISO 13485 certification investment creates switching costs against emerging material jetting competitors. For New Entrants and Emerging Players: Enter via India's CDSCO phased implementation window targeting Mumbai and Delhi NCR dental laboratory modernization. Exploit HIPAA data architecture friction as entry angle, offering pre-integrated on-premise infrastructure solutions that bypass costly middleware development for legacy practice management platforms. White-space concentration sits with orthodontic telehealth platforms requiring patient-specific device tracking from fabrication through home delivery. For Investors and Strategic Acquirers: FDA UDI compliance deadline acceleration is the leading indicator that regulatory bundling capabilities will command acquisition premiums. Five-to-ten year viability hinges on additive manufacturing IP consolidation rather than discrete equipment plays. Target material-formulation houses controlling both substrate and encoding IP. Signal to watch: group purchasing organization consolidation rates in US Midwest and Southwest markets.| Strategic Initiative | Industry Significance |
|---|---|
| Material Formulation Acquisition | Captures antenna-optimized ceramic IP from German precision engineering clusters. |
| Cloud-Native LIMS Development | Addresses EU MDR Article 10 fifteen-year archival requirements for implantable devices. |
| Direct Manufacturer Relationship | Displaces regional distributors as group purchasing organizations consolidate procurement. |
| HIPAA-Compliant Infrastructure Bundle | Resolves protected health information storage conflicts with on-premise deployment. |
| Orthodontic Telehealth Partnership | Opens bypass routes around traditional dental laboratory intermediaries for clear aligners. |
Research Methodology
SEC filings, EU MDR regulatory databases, and dental laboratory procurement records formed the secondary backbone, cross-referenced with primary interviews spanning dental laboratory directors, biomedical equipment technicians, GPO contracts managers, and regulatory affairs leads at additive manufacturing firms. Bottom-up installation data triangulated against top-down market sizing from equipment manufacturer revenue disclosures.
Historical trendline analysis of desktop and industrial printer deployment rates informed penetration curve modeling across the projection horizon. Segmentation dimensions included product type, frequency protocol, application risk classification, and end-user capital intensity. CAGRs derived from equipment replacement cycle compression under regulatory mandate pressure and material cost trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under photopolymer resin supply disruption or East Asian semiconductor foundry consolidation scenarios. Forecasts reflect documented assumptions regarding EU MDR and FDA UDI harmonization timelines, CDSCO implementation phasing, and group purchasing organization penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Delivery System Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Teeth Whitening Pen Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Implants Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Floss Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Malocclusion Market
Dental Devices
US Dental Splint Market