
 3D-Printed Dental Restoration Market | 2026-2036
3D-Printed Dental Restoration Market Size, Share, and Industry Trends Forecast 2026-2036
3D-Printed Dental Restoration Market Insights
European dental polymer producers is rebalancing supply toward photoreactive resin formulations as chairside manufacturing scales. Stratasys leverages its fused deposition modeling heritage to serve high-volume dental laboratories with production-grade hardware. Formlabs anchors the desktop stereolithography segment where dental clinics operate compact systems for same-day crown delivery. SprintRay controls the North American chairside workflow market through integrated hardware-software-sinewave resin ecosystems.
3D-printed dental restoration denotes the additive fabrication of permanent or provisional oral prostheses using biocompatible photopolymers, ceramics, or metal alloys cured via directed energy or material extrusion, typically achieving layer resolutions of 25-100 micrometers for occlusal surface fidelity. The technology serves restorative dentistry by collapsing traditional multi-appointment lab workflows into single-visit clinical procedures. Crowns and bridges occupy the dominant margin pool given their high unit value and established reimbursement pathways across developed health systems. Dental laboratories represent the fastest-growing end-user channel as centralized production models adopt multi-jet fusion systems for overnight batch manufacturing of denture bases and surgical guides.
FDA 510(k) clearances and ISO 10993 biocompatibility standards govern material eligibility for intraoral long-term use, while the EU Medical Device Regulation imposes post-market surveillance obligations on 3D-printed prosthesis manufacturers selling into European dental practices. The EPA regulates volatile organic compound emissions from photopolymer resin processing in open-format printers deployed across United States dental clinics. Stakeholders must monitor evolving software-as-medical-device classifications that could reclassify AI-generated restoration design platforms under stricter premarket review frameworks.
Market Dynamics
Dental laboratories are consolidating production workflows around photoreactive resin systems that collapse multi-appointment protocols into same-day clinical delivery. This compression of chairside manufacturing timelines is restructuring supplier relationships and capital allocation across restorative dentistry.
Growth Catalysts
- FDA 510(k) Clearance Pathways:Streamlined premarket review for biocompatible photopolymers is accelerating product commercialization timelines for resin manufacturers targeting United States dental clinics.
- Chairside Manufacturing:Compact stereolithography systems deployed in dental practices are eliminating traditional lab intermediaries for crown and bridge fabrication.
- ISO 10993 Standards:Harmonized biocompatibility testing protocols are reducing regulatory friction for material suppliers seeking multi-jurisdiction market access.
Market Restraints
- Photopolymer Feedstock Concentration:European specialty chemical producers dominate photoreactive resin supply, creating vulnerability to input cost volatility and trade friction.
- Capital Equipment Intensity:Multi-jet fusion systems for denture base production require substantial upfront investment, limiting adoption among mid-size dental laboratories.
- EPA VOC Regulations:Emission controls on open-format printers in United States clinics are constraining equipment selection and operational flexibility.
Strategic Opportunities
- Software-as-Medical-Device Classification:Evolving FDA frameworks for AI-generated restoration design platforms present first-mover advantages for integrated hardware-software vendors.
- Post-Market Surveillance Mandates:EU Medical Device Regulation requirements are creating service revenue streams for compliance management providers supporting European dental practices.
- Surgical Guide Expansion:Convergence of intraoral scanning and photopolymer printing is opening adjacent applications in implantology workflow automation.
Industry Challenges
- Digital Workflow Integration:Dental laboratories face technical debt from legacy CAD/CAM systems that resist seamless data exchange with newer additive platforms.
- Biocompatibility Certification Timelines:ISO 10993 cytotoxicity and sensitization testing protocols extend material validation cycles, delaying product launches.
- Resin Handling Expertise:Clinical staff require specialized training in photopolymer storage, exposure protocols, and post-processing to achieve consistent occlusal fidelity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D-Printed Dental Restoration Market |
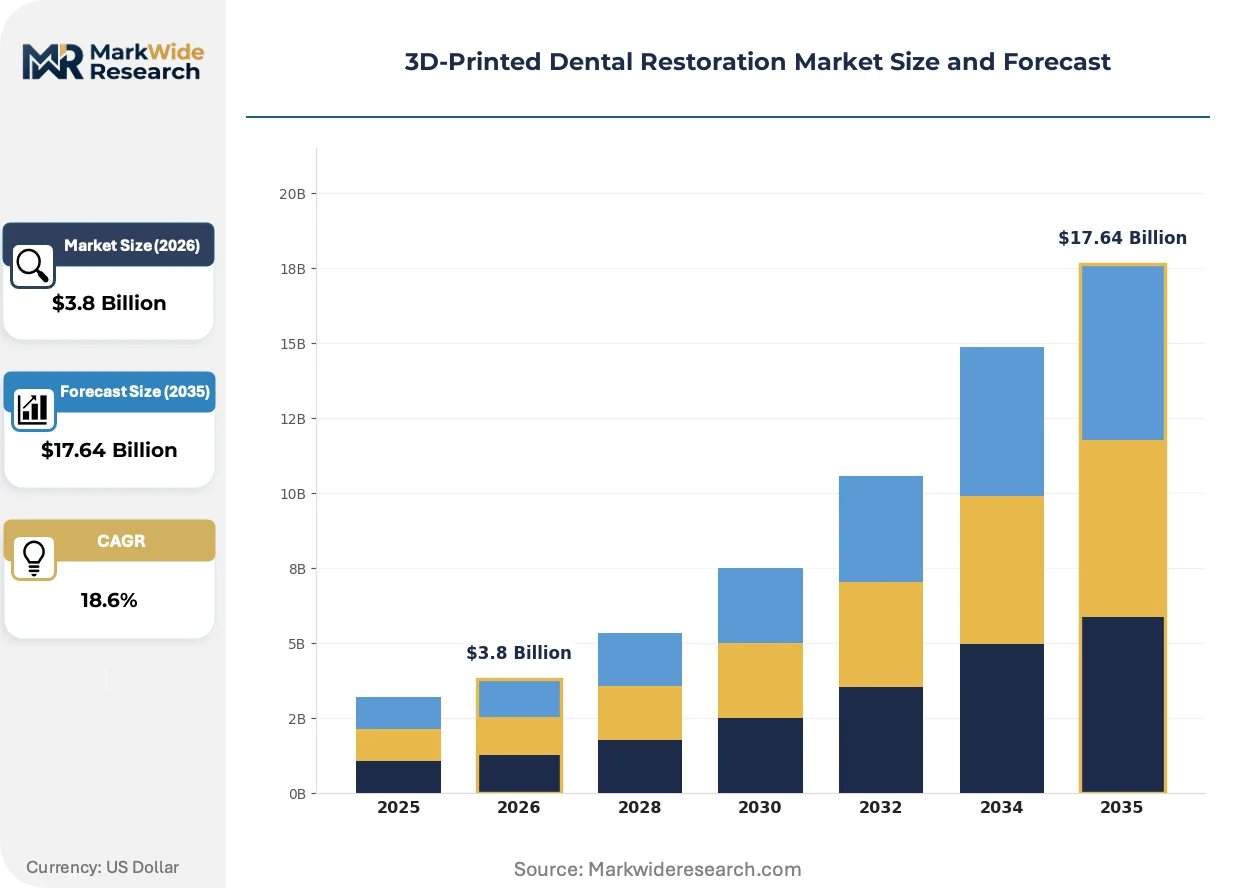
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Bridges, Dentures, Inlays, Onlays Technology: Stereolithography, Digital Light Processing, Fused Deposition Modeling, Selective Laser Sintering, Multi Jet Fusion Application: Restorative Dentistry, Orthodontics, Prosthodontics, Surgical Guides, Maxillofacial Reconstruction End User: Dental Clinics, Dental Laboratories, Academic Institutions, Research Centers |
| Companies Covered | Stratasys, 3D Systems, Formlabs, SprintRay, DWS, Asiga, Prodways, Rapid Shape, Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D-Printed Dental Restoration Market Trends and Innovations
Photopolymer chemistry advances and regulatory digitization are converging to compress restoration delivery timelines while expanding the addressable procedure set beyond traditional crown and bridge applications.
Nanoceramic-filled photopolymers are absorbing mechanical load requirements previously reserved for milled zirconia and metal alloys. High-throughput dental laboratories in Germany and the United States are adopting these materials for definitive posterior restorations. The technology is absorbing margin pressure from conventional milling centers by eliminating tooling costs and reducing material waste rates.
EU Medical Device Regulation post-market surveillance obligations are forcing prosthesis manufacturers to deploy traceability systems that link individual restorations to resin batch records. Dental laboratories serving European practices are investing in blockchain-anchored documentation to satisfy notified body audits. This regulatory burden falls heaviest on smaller labs lacking dedicated quality management infrastructure.
Subscription-based equipment access models are displacing outright purchase structures for chairside printing systems. Dental clinics in urban United States markets are prioritizing all-inclusive service contracts that bundle resin supply, preventive maintenance, and software updates. California and New York practice groups are negotiating multi-site fleet arrangements that aggregate volume for preferential resin pricing.
3D-Printed Dental Restoration Market Segmentation
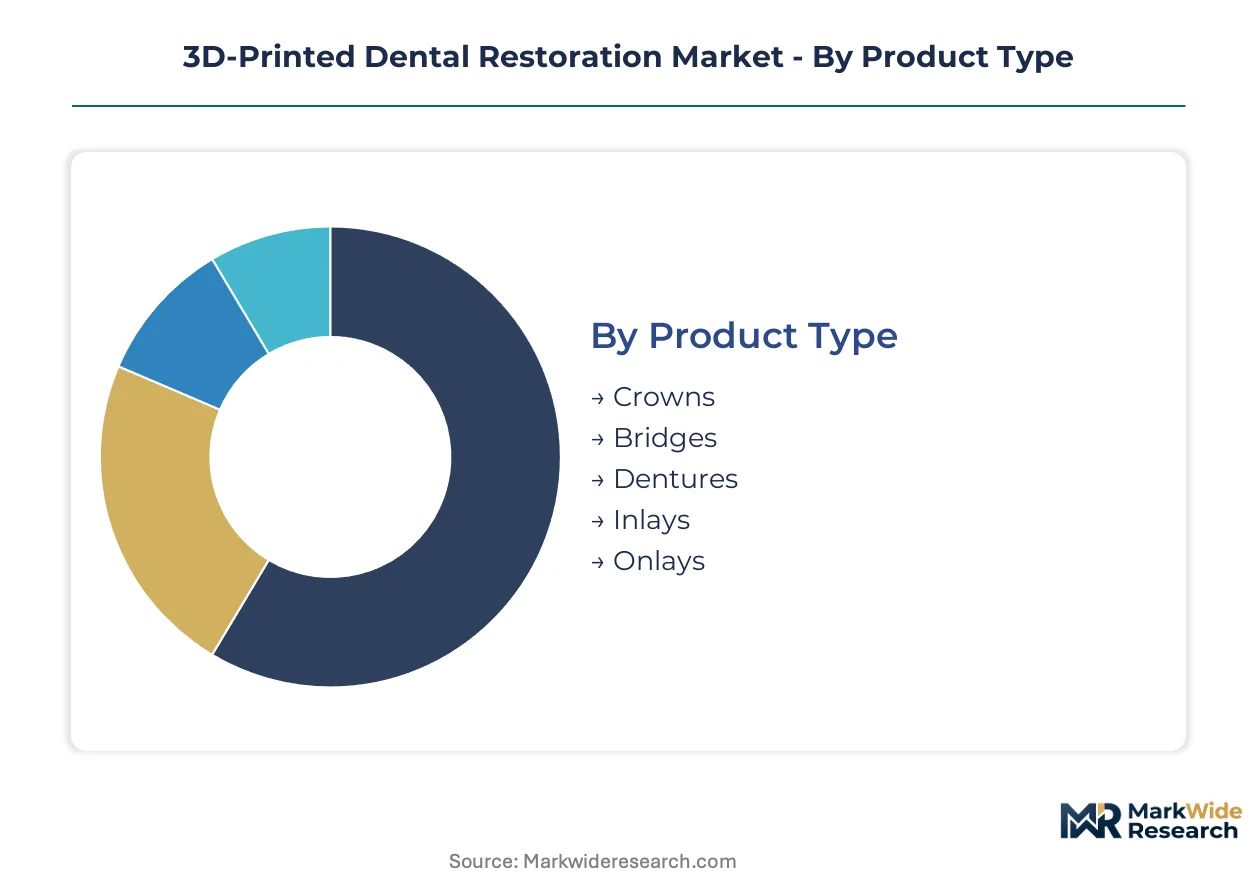
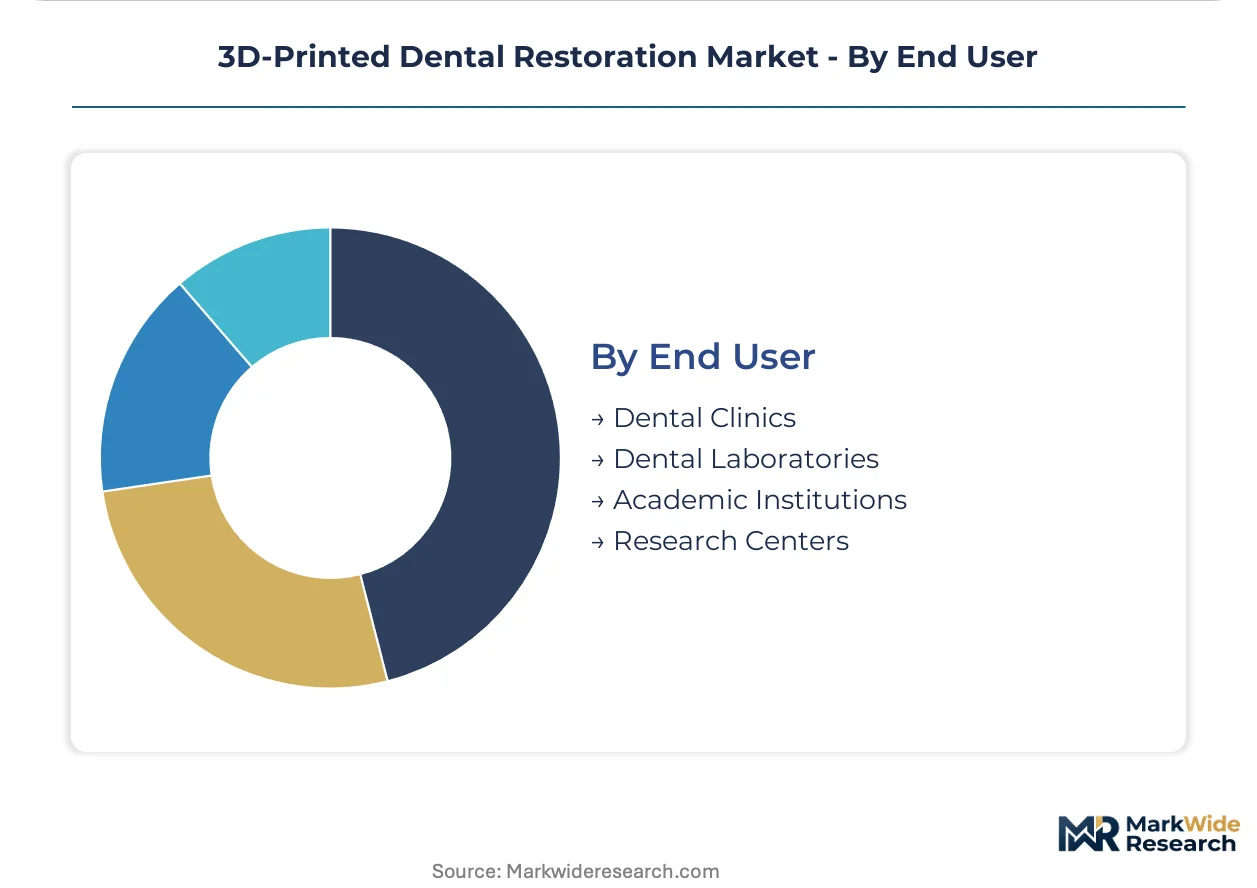
Segmentation reveals how additive manufacturing technology penetrates distinct clinical workflows, with product type and end-user channel determining equipment specifications, resin chemistry requirements, and regulatory compliance burdens. Understanding these divisions exposes where capital deployment concentrates and where margin compression threatens incumbent suppliers.
Product Type:
Material specifications and mechanical load requirements differentiate prosthesis categories, with occlusal stress tolerance dictating photopolymer formulation choices.
- Crowns:Single-unit restorations demand nanoceramic-filled photopolymers achieving flexural strength above 150 MPa for posterior load-bearing applications. Demand concentrates in United States urban dental clinics where chairside same-day delivery commands premium reimbursement rates from commercial payers.
- Bridges:Multi-unit fixed prostheses require high-precision interproximal margins and connector dimensions maintained within 50-micrometer tolerances. German dental laboratories dominate production volume, leveraging CE-marked resin workflows and automated post-processing lines to serve high-throughput practice networks.
- Dentures:Full and partial removable appliances utilize baseplate resins with low water sorption properties for dimensional stability.
- Inlays:Intracoronal restorations occupy niche indications where conservative tooth preparation preserves structural integrity.
- Onlays:Cusp-covering designs bridge the gap between direct composite and full-crown coverage in posterior quadrants.
Crowns lead on scale; bridges lead on momentum.
Technology:
Cost tier and throughput requirements segment hardware acquisition decisions, with capital intensity separating centralized laboratory systems from compact clinical units.
- Stereolithography:Laser-based photopolymerization achieves 25-micrometer layer resolution for occlusal surface fidelity in definitive restorations. Desktop systems priced under $10,000 dominate dental clinic procurement in California and New York practice groups seeking same-day crown delivery without lab intermediaries.
- Digital Light Processing:Projector-based curing enables faster print speeds through full-layer exposure, trading absolute precision for throughput gains in high-volume crown production.
- Fused Deposition Modeling:Thermoplastic extrusion serves provisional and diagnostic applications where biocompatibility requirements permit non-photopolymer materials.
- Selective Laser Sintering:Powder-bed fusion processes nylon and PEEK polymers for removable partial denture frameworks requiring fatigue resistance.
- Multi Jet Fusion:HP's binder jetting technology produces denture bases and surgical guides in overnight batch runs at centralized laboratory facilities.
Multi Jet Fusion leads on scale; Stereolithography leads on momentum.
Application:
Volume and margin concentration vary across dental specialties, with restorative procedures commanding the largest addressable patient base.
- Restorative Dentistry:Crown and bridge fabrication represents the primary revenue pool, with photopolymer systems displacing conventional milling for single-visit protocols.
- Prosthodontics:Complex full-mouth rehabilitation cases drive demand for precision-fitted removable and fixed prostheses.
- Surgical Guides:Implantology workflow automation is expanding fastest as intraoral scanning and CBCT integration enables patient-specific drill guide production.
- Orthodontics:Clear aligner manufacturing and indirect bonding trays utilize similar photopolymer platforms with distinct material clearances.
- Maxillofacial Reconstruction:Custom cranioplasty implants and facial prostheses require medical-grade biocompatibility certifications beyond standard dental resin classifications.
Restorative Dentistry leads on scale; Surgical Guides lead on momentum.
End User:
Customer type determines equipment footprint, staffing requirements, and software integration complexity, with laboratory consolidation reshaping vendor relationships.
- Dental Laboratories:Centralized production facilities adopt multi-printer fleets and automated post-processing to serve regional practice networks with overnight turnaround. German and United States laboratories are expanding fastest, consolidating previously fragmented local lab capacity into scaled production hubs.
- Dental Clinics:Chairside manufacturing eliminates shipping delays and remake cycles, requiring compact systems operable by auxiliary staff with limited training.
- Academic Institutions:Dental schools integrate additive platforms into preclinical curricula, training students on digital workflows.
- Research Centers:Biomaterials development programs test novel photopolymer formulations for regulatory submission.
Dental Laboratories lead on scale; Dental Clinics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing 3D-printed dental restoration production toward jurisdictions with streamlined biocompatibility certification pathways. Cost-of-compliance gaps between FDA 510(k) and EU MDR frameworks are accelerating capital migration to markets offering faster material clearance timelines.
United States
FDA 510(k) premarket review pathways for photopolymer resins attract resin manufacturers seeking rapid commercialization timelines. EPA volatile organic compound regulations constrain open-format printer deployment in California and New York dental clinics. SprintRay anchors the chairside workflow ecosystem through integrated hardware-software-resin platforms serving urban practice groups.
Germany
CE-marked material standards and dental lab digitization initiatives compress same-day restoration throughput timelines. EU Medical Device Regulation post-market surveillance obligations force prosthesis manufacturers to deploy batch traceability systems. Bavarian dental laboratories consolidate regional capacity into scaled production hubs serving Central European practice networks.
China
NMPA biocompatibility standards for intraoral photopolymers are harmonizing with ISO 10993 protocols to accelerate import substitution. Domestic resin producers in the Yangtze River Delta region scale nanoceramic-filled formulations for posterior crown applications. Shanghai dental clinics adopt compact stereolithography systems for same-day delivery protocols.
Japan
PMDA medical device classifications for 3D-printed prostheses impose rigorous cytotoxicity testing requirements on resin suppliers. METI industrial policy supports dental additive manufacturing adoption through standardization initiatives. Osaka-based dental laboratories integrate multi-jet fusion systems for overnight denture base production.
Switzerland
Swissmedic certification requirements for permanent dental restorations emphasize long-term biocompatibility validation. Precision manufacturing heritage supports high-resolution stereolithography equipment development. Zurich dental clinics pioneer subscription-based equipment access models bundling resin supply and preventive maintenance.
3D-Printed Dental Restoration Market Competitive Landscape
United States producers anchor the chairside manufacturing tier; European specialists hold the centralized laboratory production segment. Market structure fragments across hardware-software integration depth, with vertically integrated vendors commanding premium positioning against component suppliers. Three archetypes dominate: integrated workflow platforms, precision hardware specialists, and resin chemistry innovators. Competitive moves concentrate on strategic partnerships between equipment manufacturers and dental software providers, plus capacity expansion into automated post-processing lines.
Among United States-based fabricators, Stratasys and 3D Systems exemplify the production-grade hardware archetype serving high-volume dental laboratories. Formlabs occupies a position within the desktop stereolithography tier where compact systems target clinic-level same-day delivery. SprintRay represents the integrated ecosystem approach through its control of North American chairside workflow markets. These three anchors illustrate how geographic origin and organizational structure shape competitive positioning across distinct customer segments.
| Leading Market Players |
|---|
| Stratasys |
| 3D Systems |
| Formlabs |
| SprintRay |
| DWS |
| Asiga |
| Prodways |
| Rapid Shape |
| Carbon |
| Others |
Pricing and Supply Chain Analysis
Photoreactive resin feedstock indices in the Rhine-Ruhr chemical cluster cascade through three pricing tiers that separate premium nanoceramic formulations from standard chairside resins and economy-grade baseplate materials. This cost structure concentrates margin capture with European specialty chemical producers while compressing equipment vendors into subscription-based service models.
Pricing Analysis
Distributor markups on photopolymer resins vary by certification tier, with FDA 510(k)-cleared materials commanding substantial premiums over CE-marked equivalents in United States clinics. Three-tier pricing structure across premium, standard, and economy levels separates definitive posterior restorations from provisional appliances and diagnostic models. Pricing pressure stems from subscription bundling that aggregates hardware, software, and resin supply into single contracts. Mid-size dental laboratories exhibit highest price sensitivity due to capital constraints on multi-jet fusion system acquisition.
Supply Chain Analysis
Specialized polymer chemist availability in Bavaria, North Carolina's Research Triangle, and Shanghai's Yangtze River Delta anchors photoreactive resin production capacity. European and Chinese suppliers draw from acrylate monomer feedstocks, photoinitiator additives, and nanoceramic fillers to formulate biocompatible dental materials. Single-source vulnerability concentrates in photoinitiator supply from German specialty chemical producers. Distribution runs through authorized dental supply distributors serving regional laboratory networks and direct-to-clinic logistics for chairside system vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as chairside manufacturing adoption in dental clinics creates durable recurring revenue streams from resin consumption. FDA clearance timelines and ISO 10993 certification requirements erect defensive moats around incumbent positions.
For Market Incumbents: Lock in resin supply exclusivity through backward integration into photoinitiator production or long-term offtake agreements with Rhine-Ruhr chemical producers. Deepen software-hardware integration to capture AI-generated design workflows before regulatory reclassification tightens premarket review requirements.
For New Entrants and Emerging Players: The premium-to-economy price gap in nanoceramic-filled resins offers entry space for domestic Chinese producers undercutting European imports. Target mid-size United States dental laboratories underserved by integrated ecosystem vendors. Pursue white-label resin supply partnerships with equipment manufacturers seeking second-source security.
For Investors and Strategic Acquirers: Asymmetric upside sits with resin chemistry innovators possessing ISO 10993 biocompatibility dossiers and FDA 510(k) clearance track records. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than hardware differentiation alone. Monitor EPA VOC enforcement actions as signal for equipment vendor consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Expansion | EU MDR batch traceability systems create recurring compliance service revenue for European dental laboratories. |
| Software-as-Medical-Device Investment | FDA premarket review of AI design platforms favors integrated hardware-software vendors with regulatory affairs infrastructure. |
| Resin Chemistry Backward Integration | In-house photoinitiator production secures margin capture and supply continuity against European feedstock concentration. |
| Subscription Service Model Deployment | All-inclusive contracts bundling resin supply and maintenance lock in dental clinic customer lifetime value. |
| Automated Post-Processing Scale-Up | Overnight batch manufacturing capabilities differentiate centralized laboratory production hubs from chairside competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory operations directors, clinic practice managers, resin formulation chemists, and biomedical regulatory consultants with secondary validation against FDA 510(k) clearance databases, EPA emission compliance filings, and ISO 10993 biocompatibility test reports. Bottom-up equipment shipment analysis and top-down resin consumption estimates triangulated market sizing across the projection horizon.
Segment-weighting approaches modeled technology type, product category, end-user channel, and application area as independent dimensions. CAGRs derived from installed base growth rates, resin consumption per restoration unit, and pricing trajectory assumptions for subscription versus transactional revenue models. Forecast inputs incorporated chairside manufacturing penetration curves and dental laboratory consolidation patterns.
Caveats apply where FDA software-as-medical-device reclassification, EU MDR post-market surveillance enforcement intensity, or photoinitiator supply disruptions could materially shift the outlook. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Global Dental Lasers Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Amalgamators Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Self-Ligating Bracket Sales Market
Dental Devices
North America Aligner Sheet Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Dental Calipers Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Laboratory Handpiece Market