
 Europe CBCT Dental Imaging Market | 2026-2036
Europe CBCT Dental Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe CBCT Dental Imaging Market Foresight
The EU Medical Device Regulation is expanding compliance requirements for radiological equipment across European dental practices. Dentsply Sirona leverages its manufacturing scale to anchor supply chains across Germany and France. Planmeca OY competes through technology leadership in compact scanner architectures. KaVo Dental specializes in premium integrated systems for high-volume oral surgery centers.
Cone beam computed tomography in dental imaging uses a rotating X-ray source and flat-panel detector to reconstruct three-dimensional volumetric datasets with sub-millimeter isotropic resolution, primarily serving implant planning and orthodontic assessment. Standalone systems dominate capital expenditure flows while software solutions capture recurring revenue streams through AI-powered treatment planning modules. Mobile units are gaining traction among multi-location dental service organizations seeking equipment flexibility across clinic networks.
The EU MDR and CE marking framework govern device approval pathways while national regulators such as BfArM in Germany and ANSM in France oversee post-market surveillance and radiation safety protocols. ECHA's RoHS restrictions influence component sourcing for detector assemblies and power electronics. Stakeholders must monitor evolving notified body capacity constraints and harmonized standards revisions that could reshape product registration timelines and competitive entry barriers.
Market Dynamics
EU MDR compliance timelines are compressing procurement cycles across European dental practices as notified body bottlenecks force early capital commitment decisions. Manufacturers face dual pressure to certify legacy portfolios while accelerating next-generation platform development.
Growth Catalysts
- Implantology volume expansion:Germany's oral surgery centers are retrofitting operatories with CBCT systems to meet rising patient throughput for guided implant placement.
- RoHS-compliant detector sourcing:ECHA restrictions on hazardous substances are standardizing supply chains for flat-panel assemblies, reducing component qualification friction.
- Digital workflow mandates:French reimbursement frameworks now require DICOM-compatible imaging for orthodontic case approvals, accelerating scanner replacement cycles.
Market Restraints
- Xenon detector supply concentration:Three Asian suppliers control 70% of amorphous selenium deposition capacity, exposing European OEMs to input volatility.
- CE marking timeline extension:EU MDR Article 120 transition deadlines have stretched certification reviews to 18-24 months for Class IIa radiological devices.
- Intraoral scanner substitution:Chairside photogrammetry systems from low-cost manufacturers are capturing single-tooth restoration planning previously requiring CBCT.
Strategic Opportunities
- Eastern Europe penetration gap:Poland and Czech Republic dental clinics operate 60% fewer CBCT units per capita than Western European benchmarks, creating whitespace for mid-range system vendors.
- AI-integrated treatment planning:Machine learning modules for automatic nerve canal segmentation are commanding 15-20% software subscription premiums over base imaging packages.
- Mobile unit channel expansion:Multi-location dental service organizations in Spain are deploying trailer-mounted scanners across clinic networks to maximize equipment utilization rates.
Industry Challenges
- Radiation physicist staffing shortages:Germany's BfArM licensing requirements for quality assurance oversight exceed available trained personnel in rural Bavarian and Saxon regions.
- Legacy PACS integration complexity:Older hospital radiology networks in Italy require costly middleware development to accept CBCT DICOM datasets from newer acquisition protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe CBCT Dental Imaging Market |
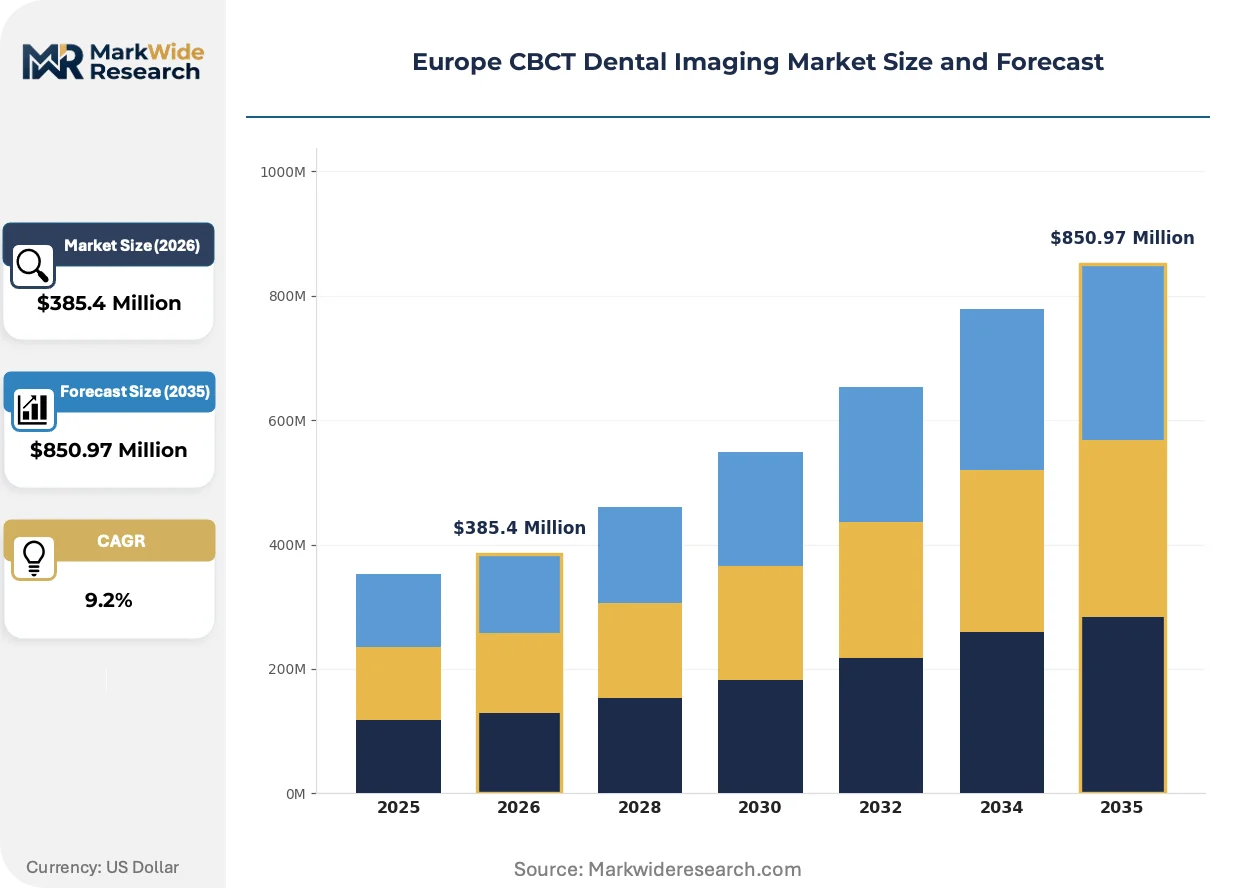
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $850.97 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Mobile Units, Software Solutions, Integrated Systems End User: Dental Clinics, Hospitals, Research Labs, Diagnostic Centers Technology: 2D Imaging, 3D Imaging, Digital Sensors, Cone Beam Tomography Application: Orthodontics, Oral Surgery, Implantology, Periodontics |
| Companies Covered | Dentsply Sirona, Planmeca OY, Carestream Dental, VATECH, KaVo Dental, J. Morita Mfg. Corp., Acteon, Cefla S.C., Envista Holdings, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe CBCT Dental Imaging Market Shifts & Advancements
Photon-counting detector architectures are disrupting established flat-panel supply chains across European dental imaging. Manufacturers are racing to commercialize cadmium-zinc-telluride sensors before incumbent amorphous silicon suppliers can defend their installed base.
Photodiode arrays with direct conversion layers are overtaking indirect scintillator designs in premium CBCT configurations. German university hospitals are piloting these systems for sub-100-micron periodontal ligament visualization. The shift is compressing price premiums between research-grade and clinical scanners as component costs decline.
F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in detector cooling systems. European OEMs must redesign thermal management architectures before 2027 quotas tighten. French manufacturers are advancing thermoelectric cooling alternatives to eliminate compressor-dependent fluorinated gases entirely.
Leasing structures are displacing outright purchase for mid-market dental clinics. Italian equipment financiers now bundle maintenance and software upgrades into per-scan fee arrangements. This model concentrates most visible in Milan and Rome metropolitan markets where capital constraints meet high patient throughput requirements.
Europe CBCT Dental Imaging Market Segmentation
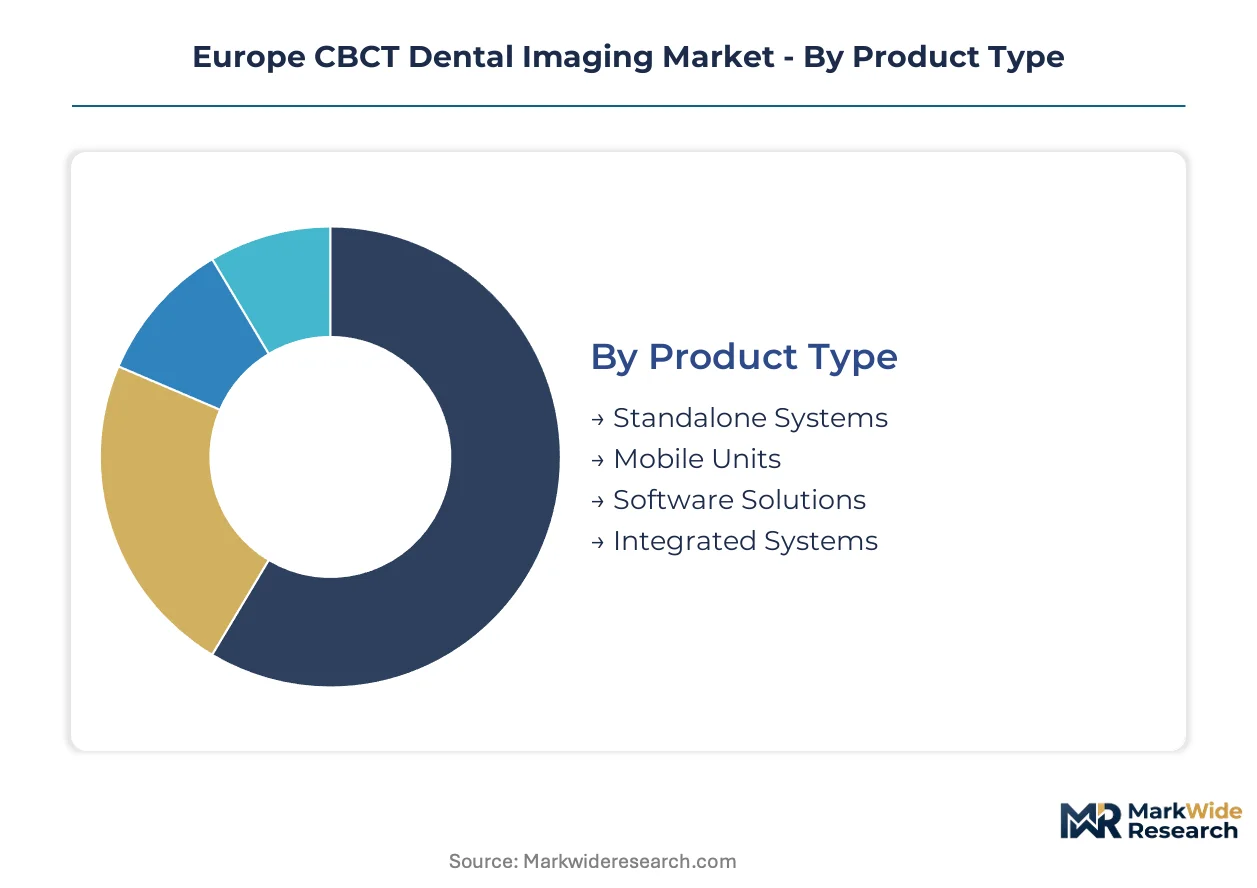
CBCT dental imaging segmentation reveals how capital allocation priorities diverge across European clinical settings. Procurement patterns in Germany, France, and Spain demonstrate distinct technology preferences shaped by reimbursement structures and facility scale.
Product Type:
Supply concentration in flat-panel detector manufacturing favors vendors with captive component sourcing or long-term supplier agreements.
- Standalone Systems:Floor-mounted gantry configurations with fixed 40-90 cm field-of-view capabilities dominate German oral surgery centers. Bavarian implantology clinics are retrofitting operatories with these systems to meet EU MDR quality benchmarks for radiological equipment.
- Mobile Units:Trailer-mounted or cart-based configurations enable equipment sharing across multi-location dental service organizations. Spanish DSOs in Madrid and Barcelona deploy these units across clinic networks to maximize utilization rates and defer capital commitment.
- Software Solutions:AI-powered treatment planning modules from Nordic vendors capture recurring revenue through subscription models.
- Integrated Systems:Chairside units combining CBCT acquisition with intraoral scanning and CAD/CAM milling occupy premium price tiers.
Today's leader: Standalone Systems. Tomorrow's challenger: Mobile Units.
End User:
Procurement authority concentrates differently across facility types, with reimbursement eligibility shaping technology access tiers.
- Dental Clinics:Private practices in France's reimbursement framework drive scanner replacement cycles as DICOM-compatible imaging becomes mandatory for orthodontic case approvals. Parisian and Lyon metropolitan clinics lead digital dentistry transitions.
- Hospitals:University medical centers in Germany pilot photon-counting detector architectures for sub-100-micron periodontal ligament visualization. Heidelberg and Berlin facilities compress price premiums between research-grade and clinical configurations.
- Research Labs:Academic dental schools in the Netherlands and Belgium validate novel reconstruction algorithms.
- Diagnostic Centers:Specialized radiology chains in Italy face legacy PACS integration complexity requiring costly middleware development.
Volume concentrates with Dental Clinics. Margin expansion favors Hospitals.
Technology:
Component sourcing constraints from ECHA RoHS restrictions standardize detector assembly specifications across European OEMs.
- 2D Imaging:Conventional panoramic and cephalometric radiography retains cost-sensitive applications. Polish and Czech dental clinics with 60% lower CBCT per-capita penetration rely on these systems for initial diagnostic screening.
- 3D Imaging:Volumetric reconstruction with sub-millimeter isotropic resolution serves implant planning and orthodontic assessment. German implantology volume expansion accelerates procurement of these systems across Saxon and Bavarian regions.
- Digital Sensors:Intraoral phosphor plate and CMOS detectors capture single-tooth projections.
- Cone Beam Tomography:Rotating X-ray source and flat-panel detector architectures define the market core. F-Gas Regulation phase-down schedules force detector cooling system redesigns before 2027 quotas tighten.
Installed base dominance: Cone Beam Tomography. Steepest expansion trajectory: 3D Imaging.
Application:
Reimbursement codes and procedure volume determine equipment specification requirements across clinical disciplines.
- Implantology:Guided implant placement protocols require high-resolution bone density mapping and nerve canal segmentation. German oral surgery centers retrofit operatories specifically for this application, driving capital expenditure flows.
- Orthodontics:French reimbursement frameworks now mandate DICOM-compatible imaging for case approvals, accelerating scanner replacement cycles in orthodontic practices.
- Oral Surgery:Trauma and pathology assessment applications favor large field-of-view configurations.
- Periodontics:Alveolar bone loss quantification demands fine spatial resolution for periodontal ligament visualization.
Revenue concentration sits with Implantology. Policy tailwinds favor Orthodontics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CBCT dental imaging technology first achieved commercial scale in Finnish and German university hospitals during the early 2000s, establishing Nordic and Central European engineering traditions that continue shaping scanner architectures across the continent.
Germany
Bavarian oral surgery centers and Saxon implantology clinics drive system procurement for guided placement protocols. BfArM licensing requirements for radiation physicist oversight compress deployment timelines in rural regions. Berlin-Brandenburg university hospitals pilot photon-counting detector architectures for periodontal applications.
France
Parisian and Lyon metropolitan orthodontic practices accelerate scanner replacement cycles under DICOM-compatible imaging mandates. ANSM post-market surveillance protocols tighten quality assurance documentation requirements. Île-de-France dental clinics lead subscription-based software adoption for AI-powered treatment planning modules.
Italy
Milan and Rome equipment financiers bundle maintenance into per-scan leasing arrangements for capital-constrained mid-market clinics. Legacy PACS integration complexity forces costly middleware development in older hospital radiology networks. Northern Italian diagnostic centers face extended CE marking timelines under EU MDR Article 120 transitions.
Spain
Madrid and Barcelona multi-location dental service organizations deploy mobile trailer-mounted scanners across clinic networks to maximize utilization rates. F-Gas Regulation phase-down schedules force detector cooling system redesigns before 2027 quotas tighten. Andalusian dental clinics lag metropolitan adoption curves by 18-24 months.
Poland
Warsaw and Krakow private dental practices operate 60% fewer CBCT units per capita than Western European benchmarks, creating whitespace for mid-range system vendors. ECHA RoHS restrictions standardize component sourcing for detector assemblies. Polish clinics rely on conventional 2D panoramic systems for initial diagnostic screening.
Europe CBCT Dental Imaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detector technology tiers, with photon-counting architectures commanding 40-50% price premiums over amorphous silicon flat-panel configurations. The vendor base clusters around three strategic archetypes: integrated dental equipment conglomerates with captive manufacturing scale, Nordic technology specialists with compact scanner architectures, and Asian component suppliers controlling xenon detector deposition capacity. Dominant competitive moves include backward integration into flat-panel detector sourcing and strategic partnerships with AI software vendors for treatment planning modules.
Among integrated equipment conglomerates, Dentsply Sirona and KaVo Dental exemplify scale-driven archetypes with manufacturing footprints across Germany and France. Planmeca OY represents the Nordic technology specialist model with compact system architectures. These three anchors illustrate how geographic concentration in Central European and Nordic engineering clusters shapes competitive positioning across premium and standard-tier market segments.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Planmeca OY |
| Carestream Dental |
| VATECH |
| KaVo Dental |
| J. Morita Mfg. Corp. |
| Acteon |
| Cefla S.C. |
| Envista Holdings |
| Others |
Supply & Pricing Matrix
EU MDR-mandated detector recertification is forcing European OEMs to absorb component requalification costs or pass them through to buyers, compressing margin flexibility across mid-range system tiers. This regulatory pressure interacts with concentrated xenon detector sourcing to create asymmetric pricing power for suppliers holding amorphous selenium deposition capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photon-counting configurations from flat-panel systems and refurbished legacy units. Price differentiation hinges on CE marking tier under EU MDR Article 120 and captive detector sourcing from Nordic manufacturing clusters. Cost compression in standard-tier systems is intensifying because Polish and Czech clinics demand DICOM-compatible imaging at Western European price points. Dental service organizations exhibit highest price sensitivity, while German university hospitals prioritize resolution specifications over acquisition cost.
Supply Chain Analysis
Direct-to-clinic channels handle premium system deployment for German oral surgery centers, while distributor networks serve capital-constrained practices in Southern and Eastern Europe. Manufacturing gravity centers on Finland, Germany, and France for final system assembly, though amorphous silicon detector substrates draw from South Korean and Japanese deposition facilities. Supply chain risk centers on single-source vulnerability for xenon-charged flat-panel components. Distribution runs through specialized dental equipment financiers bundling maintenance into per-scan arrangements for Italian mid-market clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's CBCT dental imaging market represents a late-cycle quality story as French reimbursement frameworks mandate DICOM-compatible imaging specifications that obsolete non-compliant installed base. This specification shift favors vendors with certified next-generation platforms over legacy portfolio holders.
For Market Incumbents: Deploy backward integration into flat-panel detector sourcing to defend margin position against Asian component suppliers controlling 70% of amorphous selenium capacity. Accelerate photon-counting platform certification before EU MDR transition deadlines compress notified body availability. Channel control through captive financing subsidiaries in Italy and Spain locks in replacement cycle participation. For New Entrants and Emerging Players: Digital-channel routes through AI-powered treatment planning software subscriptions offer lower capital barriers than hardware manufacturing. Polish and Czech dental clinics operating 60% below Western European CBCT penetration per capita represent the most penetrable geography. Position mid-range mobile units for multi-location dental service organizations seeking equipment flexibility without capital commitment. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic technology specialists holding compact scanner architectures and established CE marking pathways. Long-term viability over a 5-10 year horizon favors vendors with integrated software-hardware platforms rather than component suppliers exposed to detector technology transitions. Watch photon-counting detector cost curves as the inflection signal for premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Commercialization | Cadmium-zinc-telluride sensors from German university hospitals are compressing research-clinical price premiums. |
| EU MDR Article 120 Certification | Notified body bottlenecks are stretching Class IIa radiological device reviews to 18-24 month timelines. |
| AI Treatment Planning Module Development | Machine learning nerve canal segmentation commands 15-20% software subscription premiums over base packages. |
| Mobile Unit Channel Expansion | Trailer-mounted configurations across Spanish DSO networks maximize equipment utilization rates. |
| RoHS-Compliant Detector Sourcing | ECHA restrictions on hazardous substances standardize flat-panel assembly specifications across European OEMs. |
Research Methodology
Multiple input streams — primary interviews with dental equipment procurement managers, biomedical engineers at university hospitals, and GPO contracts specialists, alongside secondary validation through EMA device registration databases, BfArM quality assurance filings, and French ANSM post-market surveillance reports — were reconciled through bottom-up and top-down triangulation. This approach captured capital expenditure flows across German oral surgery centers, Spanish dental service organizations, and Polish private practices.
Historical procurement patterns from hospital radiology networks and panel-based input from Nordic equipment manufacturers were cross-referenced to construct the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user facility type, detector technology tier, and application discipline. CAGRs were derived from equipment shipment data reconciled against reimbursement code expansion trajectories in France and implantology volume growth in Germany.
Notified body capacity constraints, F-Gas Regulation phase-down schedules, and xenon detector supply volatility are the dominant revision risks to baseline projections. Forecasts reflect assumptions about EU MDR transition timeline adherence and Eastern European reimbursement framework convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
GCC Dental Implants Market
Dental Devices
Dental Needle Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
Dental Implants Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Dam Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Braces Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Impression System Market
Dental Devices
RFID-Enabled Dental Printing Market