
 Dental Liners and Bases Market | 2026-2036
Dental Liners and Bases Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Liners and Bases Market Intelligence
Cosmetic dentistry is restructuring the end-use vertical mix as patient-funded aesthetic procedures expand faster than reimbursement-dependent restorative work. Dentsply Sirona leverages its integrated digital workflow platforms to anchor chairside liner and base placement within CAD/CAM restoration protocols. GC Corporation dominates glass ionomer chemistry through captive mineral sourcing and proprietary fluoroaluminosilicate formulations. Ivoclar Vivadent AG differentiates via adhesive system compatibility testing that extends product validation across multivendor cementation workflows.
Dental liners and bases comprise protective and insulating materials applied to prepared tooth surfaces prior to definitive restoration placement, typically formulated with calcium hydroxide, glass ionomer, or resin-modified compositions that provide thermal protection, pulp sedation, or therapeutic ion release at thicknesses of 0.5 to 2.0 millimeters. Their primary commercial purpose is to prevent postoperative sensitivity and iatrogenic pulp damage in deep cavity preparations. Glass ionomer segments sustain above-average growth due to sustained fluoride release properties that align with preventive care reimbursement incentives in European dental systems. Resin-based categories occupy the premium tier where immediate light-cure handling and superior compressive strength command price premiums in time-pressed clinical environments. Calcium hydroxide formulations retain defensive utility in pulp capping applications despite displacement trends toward bioactive alternatives.
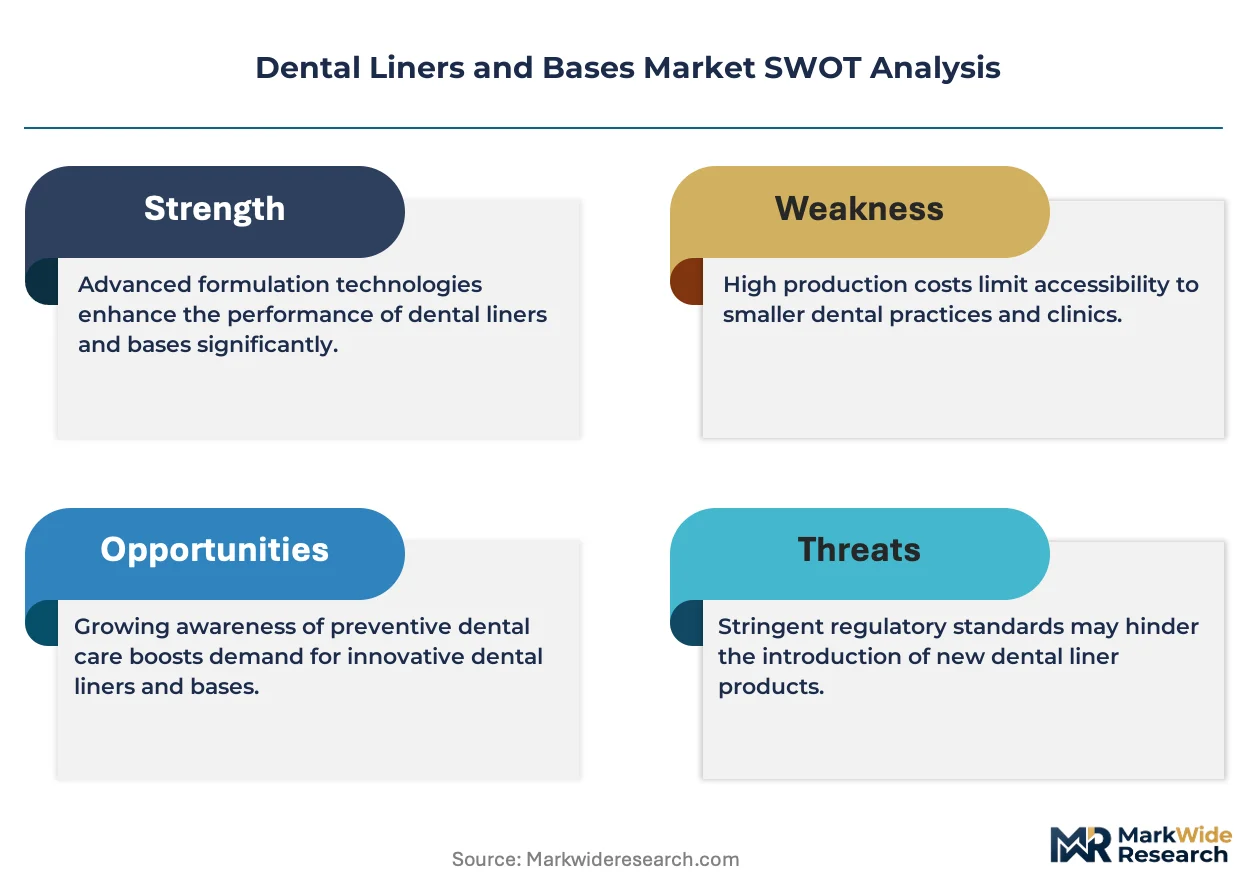
The FDA regulates dental liners and bases as Class II medical devices requiring 510(k) premarket notification with biocompatibility testing under ISO 10993 standards, while the EU MDR mandates notified body involvement and clinical evaluation reports for all permanent restorative materials. These frameworks elevate compliance costs for market entry but simultaneously filter out uncertified competitors and reinforce demand for documented clinical performance data. Stakeholders must monitor evolving FDA guidance on bioactive material classifications and MDR transition timelines to calibrate product development pipelines against shifting evidentiary requirements.
Market Dynamics
The EU MDR's biocompatibility certification requirements are compressing market entry timelines and elevating compliance investment thresholds for permanent implantable materials, restructuring competitive positioning around documented clinical performance data.
Growth Catalysts
- Glass ionomer chemistry:Sustained fluoride release properties align with preventive care reimbursement incentives in European dental systems, anchoring demand in Germany's dense network of private dental practices.
- Patient-funded aesthetic procedures:Cosmetic dentistry applications are expanding faster than reimbursement-dependent restorative work, restructuring the end-use vertical mix across dental clinics worldwide.
- MDR transition timelines:The EU Medical Device Regulation's clinical evaluation requirements filter out uncertified competitors, reinforcing demand for validated multivendor cementation workflows.
Market Restraints
- Biocompatibility testing costs:ISO 10993 compliance under FDA 510(k) pathways elevates capital requirements for market entry, disproportionately burdening smaller formulation specialists.
- Resin raw material concentration:Photoinitiator and monomer supply chains concentrate in East Asian chemical manufacturing clusters, exposing formulators to input cost volatility and logistics friction.
- Calcium hydroxide displacement:Bioactive alternatives are displacing traditional pulp capping formulations, compressing defensive utility segments and forcing portfolio reconfiguration.
Strategic Opportunities
- Digital workflow integration:Chairside liner and base placement within CAD/CAM restoration protocols creates white space for adhesive system compatibility testing across integrated platforms.
- Captive mineral sourcing:Proprietary fluoroaluminosilicate supply control enables glass ionomer margin defense against commodity formulation competitors.
- Bioactive material classifications:Evolving FDA guidance on therapeutic ion release mechanisms opens regulatory pathways for differentiated product positioning in deep cavity preparations.
Industry Challenges
- Notified body capacity constraints:EU MDR implementation bottlenecks extend certification timelines for permanent restorative materials, delaying revenue recognition and compressing development pipeline efficiency.
- Multivendor validation complexity:Adhesive system compatibility testing across disparate cementation workflows demands specialized technical personnel, creating talent scarcity in formulation chemistry functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Liners and Bases Market |
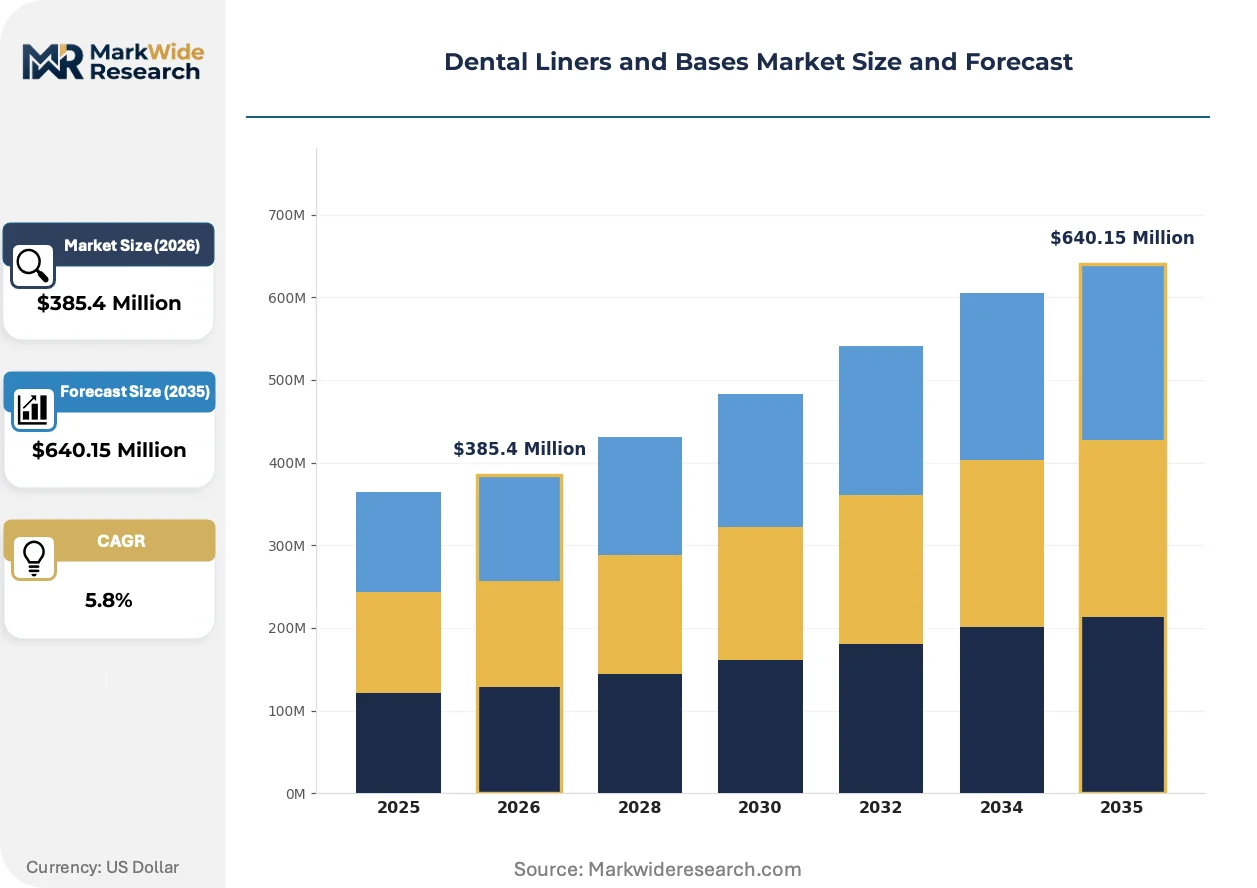
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cements, Resin-based, Glass Ionomer, Calcium Hydroxide End User: Dental Clinics, Hospitals, Dental Laboratories, Academic Institutions Application: Restorative Dentistry, Preventive Care, Cosmetic Dentistry, Pulp Capping Delivery Mode: Syringe, Bulk Package, Packets, Capsules |
| Companies Covered | 3M Company, Dentsply Sirona, GC Corporation, Ivoclar Vivadent AG, VOCO GmbH, Coltene Holding AG, Shofu Inc., Bisco Industries, Den-Mat Holdings LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Liners and Bases Market Strategic Shifts & Innovations
Material science convergence with digital dentistry protocols is actively restructuring how protective and insulating materials integrate into restorative workflows, compressing traditional placement sequences and elevating performance validation requirements.
Resin-modified glass ionomer formulations are rewriting thermal protection standards in time-pressed clinical environments. Private dental practices in Germany and specialized training centers are adopting immediate light-cure handling capabilities at accelerated replacement cycles. This technology is compressing chairside procedure duration thresholds and enabling same-visit restoration completion protocols that previously required multi-appointment sequencing.
The EU MDR's clinical evaluation report mandates are elevating evidentiary burdens for permanent restorative materials. Notified body involvement now extends to liner and base categories previously exempt from comprehensive biocompatibility documentation. German dental manufacturers are responding by consolidating validation data across multigenerational product lines to preempt regulatory scrutiny during transition timelines.
Patient-funded procurement models are displacing traditional reimbursement-dependent channel structures in aesthetic dentistry applications. Dental clinics in high-income European markets are unbundling liner and base placement from comprehensive restoration packages, creating direct-to-practice purchasing autonomy. This pattern concentrates most visibly in Germany's dense private practice networks where specialized training centers influence peer adoption of premium material tiers.
Dental Liners and Bases Market Segmentation
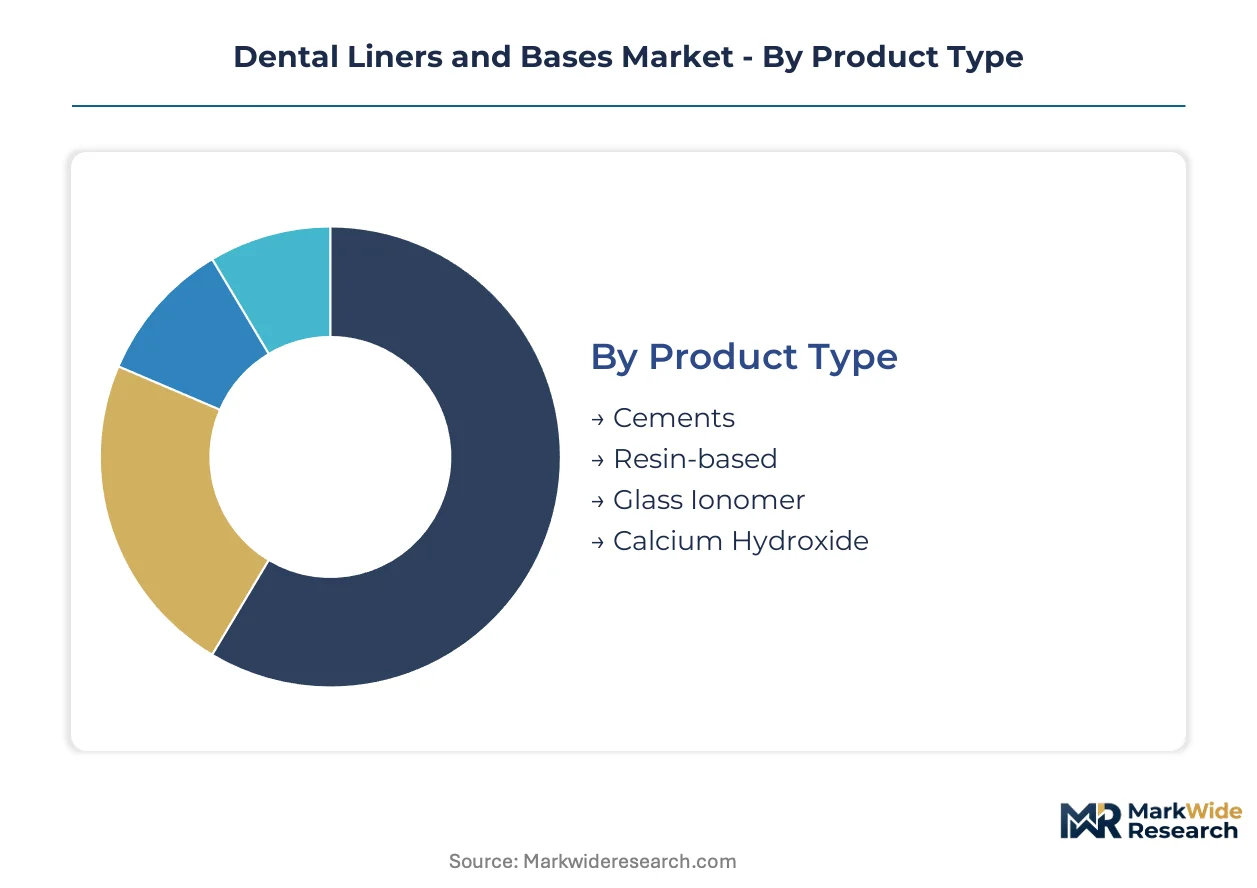
Material composition and clinical workflow integration define how dental liners and bases compete across distinct procurement channels. Each segmentation axis reveals divergent margin structures and regulatory exposure profiles that shape manufacturer resource allocation.
Product Type:
Formulation chemistry determines thermal protection performance, ion release kinetics, and light-cure handling characteristics that differentiate clinical utility across cavity preparation depths.
- Glass Ionomer:Fluoroaluminosilicate chemistry enables sustained fluoride release that aligns with preventive care reimbursement incentives in European dental systems. German private practices anchor demand through accelerated replacement cycles driven by same-visit restoration protocols.
- Resin-based:Photoinitiator-activated monomer systems deliver immediate light-cure handling and superior compressive strength that command price premiums in time-pressed clinical environments. Supply chain concentration in East Asian chemical clusters exposes formulators to input cost volatility.
- Cements:Zinc oxide-eugenol and zinc phosphate formulations retain defensive utility in provisional restoration applications despite displacement trends toward adhesive-compatible alternatives.
- Calcium Hydroxide:Traditional pulp capping formulations face compression from bioactive alternatives that offer superior dentin bridge formation and reduced postoperative sensitivity.
Glass ionomer leads on scale; resin-based leads on momentum.
End User:
Procurement autonomy varies sharply across institutional settings, with patient-funded models displacing traditional reimbursement-dependent channel structures in aesthetic dentistry applications.
- Dental Clinics:Dense private practice networks in Germany concentrate demand for premium material tiers, with specialized training centers influencing peer adoption through direct-to-practice purchasing autonomy.
- Hospitals:Centralized procurement functions in integrated health systems prioritize documented biocompatibility certification under EU MDR clinical evaluation requirements.
- Dental Laboratories:Outsourced restoration fabrication creates indirect demand for liner and base compatibility testing across multivendor cementation workflows.
- Academic Institutions:Training program standardization drives volume concentration in foundational calcium hydroxide and glass ionomer applications.
Dental clinics dominate volume throughput; academic institutions anchor technology transfer pipelines.
Application:
Clinical indication determines material thickness requirements, therapeutic ion release specifications, and integration sequencing within digital restoration workflows.
- Restorative Dentistry:Deep cavity preparations in permanent dentition drive thermal protection demand at 0.5 to 2.0 millimeter thickness specifications.
- Cosmetic Dentistry:Patient-funded aesthetic procedures expand faster than reimbursement-dependent restorative work, restructuring end-use vertical mix across high-income European markets.
- Preventive Care:Fluoride release properties align with reimbursement incentives that sustain above-average growth in glass ionomer segments.
- Pulp Capping:Bioactive alternatives displace traditional calcium hydroxide formulations, compressing defensive utility and forcing portfolio reconfiguration.
Restorative dentistry anchors installed base; cosmetic dentistry climbs fastest on patient-funded expansion.
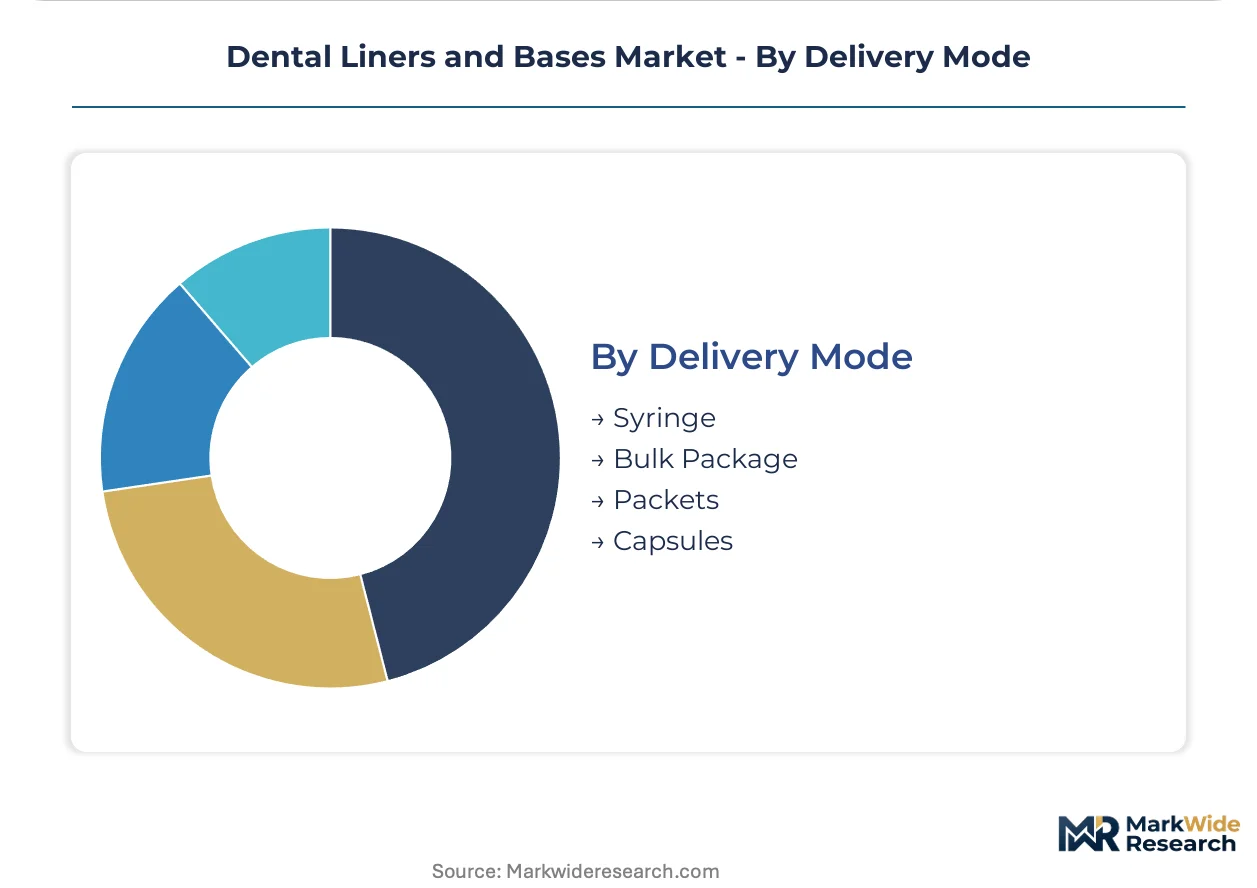
Delivery Mode:
Packaging format determines chairside handling efficiency, waste minimization, and inventory management burden across diverse practice scales.
- Syringe:Pre-dispensed unit-dose formats enable precise placement control in deep cavity preparations while minimizing material waste.
- Capsules:Mechanical mixing systems ensure consistent powder-liquid ratios for glass ionomer chemistry in high-volume clinical environments.
- Packets:Hand-mix formats retain cost advantage in price-sensitive procurement segments and emerging market penetration strategies.
- Bulk Package:Large-volume containers serve dental laboratory and institutional customers with predictable throughput requirements.
Syringe formats lead on clinical precision; capsules gain share fastest through workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense network of private dental practices anchors European demand for premium liner and base materials, with specialized training centers in Munich and Cologne driving peer adoption of advanced glass ionomer formulations.
Germany
Private dental practices in Bavaria and North Rhine-Westphalia concentrate procurement of resin-modified glass ionomer systems. The EU MDR's clinical evaluation requirements filter uncertified competitors from permanent restorative material categories. Frankfurt-based manufacturers consolidate validation data across multigenerational product lines to preempt regulatory scrutiny.
United States
Cosmetic dentistry expansion in California and Texas accelerates patient-funded procurement of premium liner materials. FDA 510(k) premarket notification pathways under ISO 10993 standards elevate compliance costs for market entrants. Minneapolis and Boston dental technology clusters anchor digital workflow integration for chairside placement protocols.
Japan
Academic institutions in Tokyo and Osaka standardize training programs for foundational calcium hydroxide and glass ionomer applications. METI guidelines on medical device quality management reinforce documentation requirements for therapeutic ion release mechanisms. Nagoya manufacturers specialize in adhesive system compatibility testing across multivendor cementation workflows.
China
Photoinitiator and monomer supply chains concentrate in Shanghai and Guangdong chemical manufacturing clusters. NMPA medical device registration rules tighten biocompatibility certification timelines for imported permanent restorative materials. Beijing dental hospitals pilot bioactive alternative formulations in pulp capping applications.
United Kingdom
London and Southeast England dental clinics unbundle liner placement from comprehensive restoration packages under direct-to-practice purchasing models. MHRA post-market surveillance requirements align with EU MDR transition timelines for clinical evaluation reports. Manchester training centers influence regional adoption of immediate light-cure handling systems.
Dental Liners and Bases Market Key Industry Players
Portfolio diversification dominates the current landscape as manufacturers reconfigure around bioactive material displacement and digital workflow integration. The vendor base stratifies across three tiers: integrated dental conglomerates with captive mineral sourcing, mid-scale formulation specialists with regional certification depth, and niche suppliers focused on single-technology segments. Two strategic archetypes define competitive positioning: chemistry-led players controlling proprietary fluoroaluminosilicate supply chains, and systems-led players anchoring multivendor adhesive compatibility. M&A activity concentrates on glass ionomer mineral reserves and CAD/CAM protocol integration capabilities.
Within the integrated systems tier, Dentsply Sirona and Ivoclar Vivadent AG exemplify divergent positioning archetypes. Dentsply Sirona leverages its chairside digital workflow platforms to anchor liner placement within CAD/CAM restoration protocols. Ivoclar Vivadent AG occupies a validation-focused position through adhesive system compatibility testing across disparate cementation workflows. GC Corporation represents the chemistry-controlled archetype with proprietary mineral sourcing strategies.
| Leading Market Players |
|---|
| 3M Company |
| Dentsply Sirona |
| GC Corporation |
| Ivoclar Vivadent AG |
| VOCO GmbH |
| Coltene Holding AG |
| Shofu Inc. |
| Bisco Industries |
| Den-Mat Holdings LLC |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility certification requirements gate qualified supply access and premium-tier pricing power, compressing market entry timelines while elevating compliance investment thresholds that filter uncertified competitors from permanent restorative material categories.
Pricing Analysis
Distributor margins on glass ionomer formulations absorb ISO 10993 testing cost pass-throughs while resin-based tiers command price premiums through immediate light-cure handling capabilities. Price differentiation rests on certification grade under FDA 510(k) pathways and volume scale through direct-to-practice procurement models. Pricing pressure stems from photoinitiator supply cost volatility concentrated in East Asian chemical clusters. Academic institutions exhibit highest price sensitivity; German private dental practices show lowest.
Supply Chain Analysis
Direct-to-practice channels handle hyperscale demand from Germany's dense private dental practice networks while dental laboratory outsourcing creates indirect compatibility testing requirements. Raw material dependencies draw from fluoroaluminosilicate mineral reserves, photoinitiator monomer systems, and calcium hydroxide chemical feedstocks. Supply concentrates in Japanese adhesive chemistry specialists, German validation service providers, and Chinese photoinitiator manufacturing clusters. Single-source vulnerability in East Asian photoinitiator supply exposes formulators to input cost volatility and logistics friction. Distribution runs through specialized dental distributors and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental liners and bases market functions as a stable compounder anchored by restorative dentistry's non-discretionary procedure volume and preventive care reimbursement incentives that sustain replacement cycle demand.
For Market Incumbents: Hedge bioactive material displacement risk by consolidating proprietary fluoroaluminosilicate mineral sourcing and accelerating adhesive system compatibility validation across multivendor cementation workflows. Prioritize notified body relationship investment to preempt EU MDR transition bottlenecks compressing certification timelines. For New Entrants and Emerging Players: Mid-tier dental clinics in UK direct-to-practice purchasing models represent underserved buyer archetypes with unbundled procurement autonomy creating white space outside German market concentration. Target capsule-format glass ionomer workflows with mechanical mixing efficiency as entry wedge, leveraging price sensitivity in academic training program standardization. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale formulation specialists with regional certification depth but lacking digital workflow integration capabilities. Five-to-ten year viability hinges on CAD/CAM protocol anchoring; acquisition targets should demonstrate multigenerational product line validation data. Watch FDA bioactive material classification guidance evolution as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Investment | EU MDR clinical evaluation requirements compress certification timelines for permanent restorative materials. |
| Captive Mineral Sourcing Acquisition | Proprietary fluoroaluminosilicate supply control defends glass ionomer margin position against commodity competitors. |
| CAD/CAM Protocol Integration | Chairside liner placement within digital workflows anchors demand through adhesive system compatibility testing. |
| Bioactive Material R&D Expansion | FDA therapeutic ion release guidance opens regulatory pathways for differentiated deep cavity preparation positioning. |
| Direct-to-Practice Channel Development | Patient-funded aesthetic procurement models unbundle liner placement from comprehensive restoration packages. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental materials procurement managers, biomedical engineers at hospital purchasing committees, GPO contracts specialists, and formulation chemistry R&D directors with secondary validation against FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and customs trade data. Bottom-up volume modeling and top-down market sizing triangulated segment-level outputs.
Comparable historical reference periods anchored the projection horizon across material composition, end-user procurement channel, clinical application indication, and delivery mode packaging format dimensions. CAGRs derived from segment-level growth rate convergence analysis incorporating restorative procedure volume trends, reimbursement incentive structures, and regulatory transition timeline assumptions.
Inputs from notified body guidance documents and hospital procurement databases were available through the study window; gaps in real-time pricing transaction data introduce uncertainty bands around premium-tier resin-based segment assumptions. Forecasts reflect documented assumptions regarding EU MDR implementation pacing and bioactive material classification evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Fittings Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Aligners Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Gingivitis Treatment Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Dental Forceps Market
Dental Devices
Dental Articulators Market
Dental Devices
Intraoral Dental Scanner Market
Dental Devices
Europe Dental Lab Market
Dental Devices
Global Dentures Market
Dental Devices
Global Periodontal Market