
 Hygiene Stations Market | 2026-2036
Hygiene Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Hygiene Stations Market Insights
Subscription-based compliance monitoring software is broadening the value proposition beyond hardware sales for hygiene station vendors. Ecolab leverages its institutional cleaning portfolio to bundle digital hygiene tracking with equipment leases. NIEROS sustains engineering leadership through stainless-steel fabrication specialization for food-grade environments. Meritech anchors North American market presence with automated hand-washing systems designed for USDA-inspected facilities.
Hygiene stations encompass integrated personnel decontamination systems combining hand washing, boot scrubbing, and sanitization dispensing, typically constructed from AISI 304 or 316 stainless steel with sensor-activated water and chemical delivery to prevent cross-contamination in controlled-access environments. The touchless systems segment within delivery mode is capturing premium positioning as facilities prioritize pathogen transmission reduction, while portable solutions serve temporary construction and event infrastructure where fixed installation proves impractical. Application demand in healthcare facilities retains mature volume leadership, though educational institutions represent an emerging structural growth pocket driven by state-level school health mandates.
OSHA workplace sanitation guidelines, FDA Food Code provisions, and EU hygiene package regulations (EC 852/2004) collectively mandate documented hand-washing protocols that institutional buyers must satisfy through certified station deployments. These frameworks elevate product specification thresholds and create compliance-driven replacement cycles independent of discretionary capital budgets. Stakeholders should monitor evolving EFSA guidance on automated versus manual sanitization efficacy, as forthcoming technical opinions could recalibrate equipment certification requirements across European foodservice procurement.
Market Dynamics
Touchless sensor technology and IoT-enabled compliance monitoring are compressing replacement cycles and elevating specification thresholds across institutional procurement, forcing vendors to bundle hardware with recurring software revenue streams.
Growth Catalysts
- HACCP compliance mandates:Food processing plants in Germany and the United States face intensified USDA and EU hygiene package inspections, driving automated hand-washing station deployments in meatpacking corridors.
- Stainless-steel fabrication specialization:AISI 316 grade enclosures with sensor-activated chemical delivery are displacing manual sanitization in pharmaceutical cleanrooms where cross-contamination protocols have tightened.
- School health mandates:State-level educational infrastructure spending in the United States is creating dedicated procurement channels for portable hygiene stations in K-12 facilities.
Market Restraints
- Stainless-steel input volatility:Nickel price swings directly compress margin structures for fabricators specializing in AISI 304 and 316 enclosures, forcing inventory hedging costs onto mid-tier vendors.
- German engineering concentration:Premium sensor module supply clusters in Bavaria and Baden-Württemberg, creating single-source vulnerability for North American assemblers during trade friction periods.
- Manual sanitization persistence:Low-complexity foodservice operations continue deploying conventional sinks where labor arbitrage outweighs automation capital expenditure, capping addressable market expansion.
Strategic Opportunities
- India food processing infrastructure:FSSAI modernization programs and cold chain expansion are creating first-mover advantage for vendors establishing localized stainless-steel fabrication partnerships.
- Subscription compliance software:IoT sensor data monetization through recurring hygiene tracking licenses is expanding vendor lifetime value beyond one-time equipment sales.
- Healthcare construction in Saudi Arabia:MOHAP facility accreditation standards are mandating dedicated personnel decontamination corridors in new hospital builds, opening premium specification channels.
Industry Challenges
- Cleanroom certification timelines:ISO 14644 validation for pharmaceutical-grade installations extends deployment cycles by 8-14 months, straining vendor working capital and project pipeline visibility.
- Legacy PLC integration:Food plants with 1990s-era automation infrastructure require costly middleware development to connect IoT-enabled stations to existing SCADA networks, delaying adoption decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygiene Stations Market |
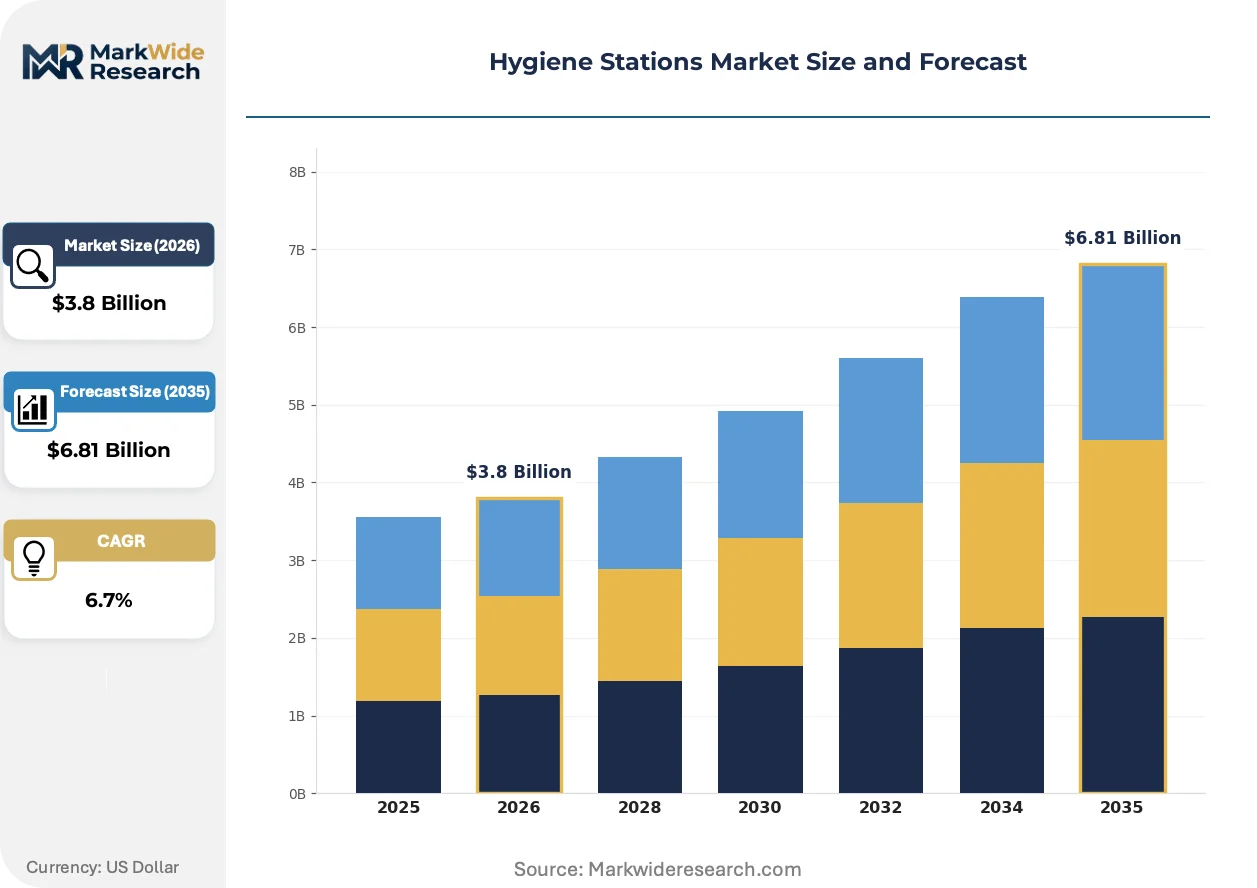
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Sanitizers, Soap Dispensers, Disposable Gloves, Wipes Application: Healthcare Facilities, Educational Institutions, Public Places, Corporates Delivery Mode: Automated Dispensers, Manual Dispensers, Touchless Systems, Portable Solutions End User: Hospitals, Schools, Offices, Retail Stores |
| Companies Covered | Ecolab, NIEROS, ROSER GROUP, Heim-EDT GmbH, SYSPAL Ltd, MOHN, Diversey, GOJO Industries, Meritech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygiene Stations Market Trends and Innovations
UV-C LED integration and predictive maintenance algorithms are redefining equipment value propositions, shifting competitive differentiation from physical durability to data-driven compliance assurance and uptime guarantees.
UV-C LED surface sanitization modules are expanding into high-throughput food processing environments where 275 nanometer wavelength exposure provides residual pathogen suppression between hand-washing cycles. Poultry and ready-to-eat meat facilities in the United States are piloting these systems under FDA Food Code guidance, compressing the acceptable microbial load window and enabling longer production runs without full line shutdowns.
REACH and RoHS amendments restricting mercury vapor lamp imports are accelerating UV-C LED adoption across European foodservice procurement, particularly in Netherlands and Denmark where municipal health inspectors enforce documented sanitization protocols. Equipment vendors are redesigning enclosure geometries to accommodate solid-state emitter arrays, triggering component supply chain reconfiguration toward semiconductor-grade substrate suppliers.
Buyers are consolidating vendor relationships around integrated hygiene corridor providers who bundle boot scrubbing, hand washing, and garment dispensing under single-source maintenance contracts. This pattern is most visible in German meatpacking where Betriebsrat works councils negotiate standardized equipment specifications across multi-facility operators, displacing fragmented point-solution procurement that dominated prior replacement cycles.
Hygiene Stations Market Segmentation
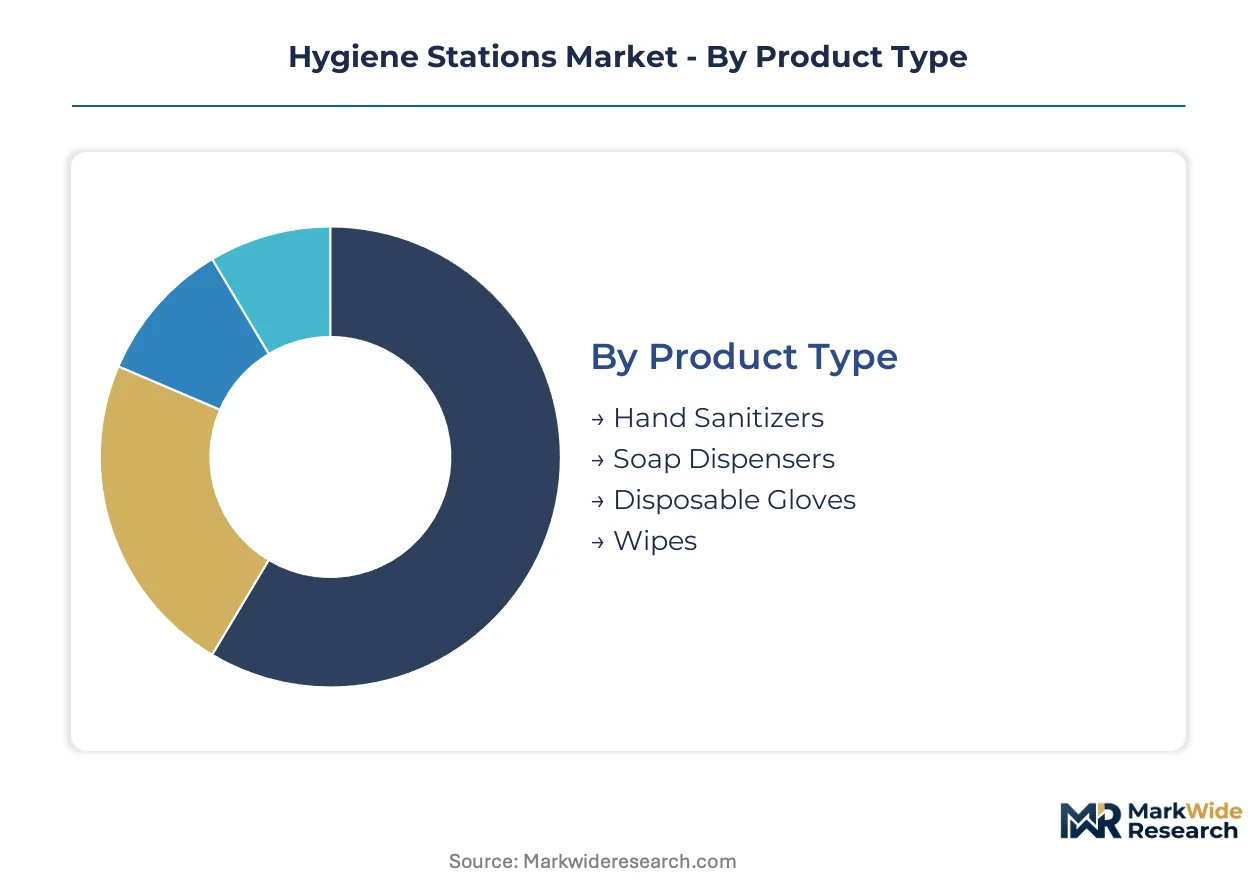
Segmentation in hygiene stations reveals how specification requirements diverge across regulatory environments and operational contexts. Buyers prioritize different performance attributes depending on whether compliance, throughput, or mobility drives procurement decisions.
Product Type:
Material composition and dispensing mechanism define competitive positioning across product categories.
- Hand Sanitizers:Alcohol-based formulations with 60-95% ethanol or isopropanol dominate hospital procurement under FDA antiseptic guidelines. Demand concentrates in US healthcare systems where Joint Commission audits mandate bedside accessibility.
- Soap Dispensers:Sensor-activated foam and liquid delivery systems with sealed cartridge designs prevent bacterial colonization in the reservoir. Food processing plants in Germany specify stainless-steel housings with HACCP-compliant documentation trails.
- Disposable Gloves:Nitrile and latex barrier protection for single-use contamination control in clinical and food-handling environments.
- Wipes:Pre-saturated towelettes with quaternary ammonium or alcohol chemistry for surface and hand hygiene in mobile field deployments.
Mature deployment sits with soap dispensers in institutional foodservice. Newer deployment is concentrated in automated sanitizer systems with compliance logging.
Application:
Facility type dictates traffic volume tolerance and regulatory scrutiny intensity.
- Healthcare Facilities:Operating rooms, patient wards, and emergency departments require 24/7 availability with CDC hand hygiene compliance monitoring. US hospitals under CMS reimbursement pressure deploy integrated dispenser networks with usage analytics.
- Educational Institutions:K-12 schools and universities face state-level health department mandates for respiratory illness mitigation. California and New York district procurement is climbing the fastest following pandemic-era infrastructure funding releases.
- Public Places:Airports, transit terminals, and municipal buildings with high transient traffic and vandalism exposure.
- Corporates:Office campuses and manufacturing facilities balancing employee wellness programming with occupational health obligations.
Mature deployment sits with healthcare facilities under Joint Commission protocols. Newer deployment is concentrated in educational institutions responding to state health mandate expansions.
Delivery Mode:
Automation level determines capital intensity and operating labor substitution.
- Automated Dispensers:Motorized delivery with programmable dose volumes and low-level alert telemetry. Pharmaceutical cleanrooms in Switzerland specify ISO 14644-compatible enclosures with HEPA-filtered air supply integration.
- Touchless Systems:Infrared or capacitive proximity sensors eliminate surface contact, reducing fomite transmission risk in high-pathogen environments. German meatpacking corridors mandate these under EU hygiene package enforcement.
- Manual Dispensers:Pump or lever-actuated mechanisms for cost-constrained deployments with lower throughput requirements.
- Portable Solutions:Battery-powered or mechanical units for construction sites, outdoor events, and temporary clinical facilities.
Mature deployment sits with manual dispensers in budget-limited foodservice. Newer deployment is concentrated in touchless systems capturing premium specification in infection-sensitive environments.
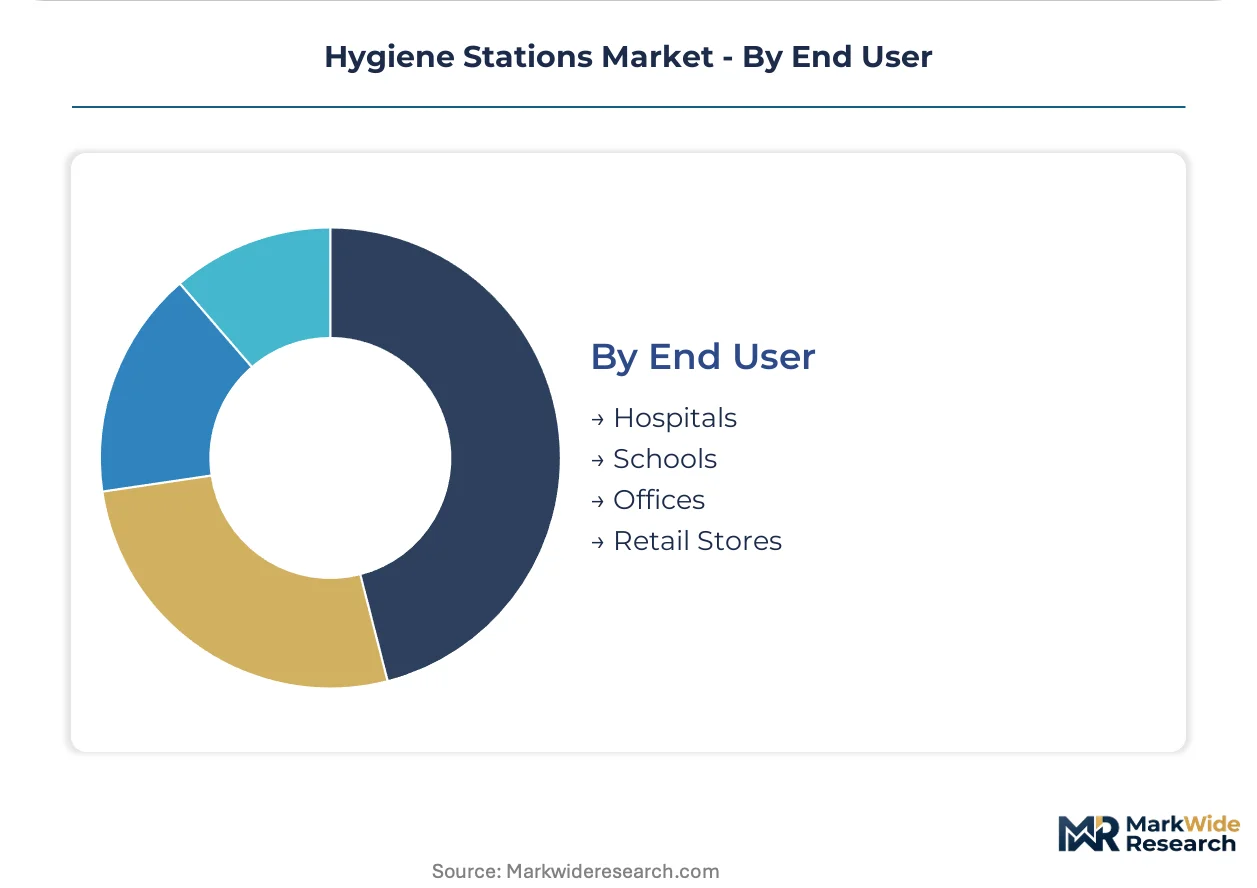
End User:
Purchasing authority and maintenance capability shape vendor relationship structures.
- Hospitals:Central sterile supply departments negotiate enterprise contracts with biomedical engineering support requirements. Saudi Arabia MOHAP accreditation standards are mandating dedicated hygiene corridors in new hospital construction.
- Schools:District-level procurement with parent association influence and state funding eligibility constraints. US K-12 facilities represent the steepest expansion trajectory as ESSER fund utilization extends to health infrastructure.
- Offices:Facility management outsourcing with integrated pest control and janitorial service bundling.
- Retail Stores:Loss prevention and customer experience teams balancing shrinkage control with shopper convenience.
Mature deployment sits with hospitals under biomedical engineering protocols. Newer deployment is concentrated in schools accessing dedicated state health infrastructure appropriations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria and Baden-Württemberg anchor European sensor module production for touchless hygiene equipment, while meatpacking corridors in Lower Saxony drive integrated station deployments under strict EU hygiene enforcement.
Germany
Meatpacking facilities in Lower Saxony and Bavaria mandate dedicated personnel hygiene corridors under EU hygiene package regulations. Betriebsrat works councils negotiate standardized equipment specifications across multi-facility operators, consolidating procurement around integrated boot scrubbing and hand-washing systems. Stuttgart engineering clusters supply premium infrared sensor modules to domestic fabricators.
United States
USDA-inspected poultry and ready-to-eat meat facilities deploy automated hand-washing stations to satisfy intensified HACCP compliance inspections. California and New York K-12 districts access ESSER infrastructure funding for portable hygiene station procurement. Chicago-based institutional cleaning vendors bundle digital compliance tracking with equipment leases.
India
FSSAI modernization programs and cold chain expansion create first-mover opportunities for localized stainless-steel fabrication partnerships. Maharashtra and Gujarat food processing zones adopt sensor-activated chemical delivery systems as export-oriented facilities seek HACCP certification. Mumbai commercial kitchen equipment distributors report rising inquiries for touchless dispensers.
Saudi Arabia
MOHAP facility accreditation standards mandate dedicated personnel decontamination corridors in new hospital construction across Riyadh and the Eastern Province. Healthcare construction booms in Jeddah and Dammam open premium specification channels for ISO 14644-compatible enclosures. King Faisal Specialist Hospital procurement frameworks favor single-source maintenance contracts.
Switzerland
Pharmaceutical cleanrooms in Basel and Zurich specify AISI 316 grade enclosures with HEPA-filtered air supply integration under Swissmedic manufacturing guidelines. Geneva-based contract manufacturers demand documented sanitization protocols for biologics production. Swiss engineering firms supply precision sensor modules to European hygiene station assemblers.
Hygiene Stations Market Competitive Landscape
Capital-heavy stainless-steel fabricators compete with asset-light compliance software developers for institutional procurement relationships. The vendor base stratifies across three tiers: integrated hygiene corridor providers bundling multi-function equipment, specialized sensor-technology licensors, and regional fabrication shops serving cost-constrained foodservice operators. Dominant competitive moves include backward integration into semiconductor-grade substrate supply and geographic expansion through localized stainless-steel partnerships in emerging food processing markets.
Within the integrated systems tier, Ecolab and NIEROS exemplify divergent strategic positions. Ecolab leverages its institutional cleaning portfolio to anchor recurring revenue through bundled digital hygiene tracking. NIEROS occupies a fabrication-specialist position rooted in Slovenian stainless-steel engineering for food-grade environments. Meritech represents the North American automated hand-washing segment designed for USDA-inspected facilities.
| Leading Market Players |
|---|
| Ecolab |
| NIEROS |
| ROSER GROUP |
| Heim-EDT GmbH |
| SYSPAL Ltd |
| MOHN |
| Diversey |
| GOJO Industries |
| Meritech |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between HACCP-compliant integrated corridors and commodity manual stations splits pricing power along stainless-steel fabrication depth and sensor module provenance. Premium AISI 316 enclosures with Bavarian-engineered infrared sensors command maintenance-contract multiples, while budget foodservice buyers source AISI 304 variants through regional metalworking clusters in Poland and Turkey.
Pricing Analysis
Margin tightening in mid-tier sensor-activated systems reflects nickel price volatility and German engineering premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by enclosure grade, with pharmaceutical cleanrooms absorbing Swiss-fabricated ISO 14644-certified units at the top. Cost-down pressure on portable solutions accelerates because Indian cold-chain operators prioritize upfront capital containment over compliance telemetry. School districts accessing ESSER funding exhibit lowest price sensitivity; conventional foodservice sinks face highest substitution risk.
Supply Chain Analysis
Single-source vulnerability sits with Bavarian infrared sensor module production, where Baden-Württemberg engineering clusters feed European and North American assembly lines. Stainless-steel enclosure fabrication draws from Slovenia, Germany, and emerging partnerships in Maharashtra. Nickel and semiconductor-grade substrate dependencies tether margin structures to commodity and chip foundry cycles. Tariff exposure on EU-origin sensor components threatens North American vendor cost positions. Distribution runs through institutional cleaning service providers bundling equipment leases with digital compliance tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum concentrates in backward control over semiconductor-grade substrate supply and captive stainless-steel fabrication capacity, as vendors seek insulation from nickel volatility and sensor module bottlenecks.
For Market Incumbents: Anchor recurring revenue through subscription-based compliance software bundling, while securing long-term AISI 316 supply agreements with Slovenian and German foundries. Sensor module single-source concentration in Bavaria presents vulnerability; qualification of secondary Swiss engineering suppliers mitigates trade friction exposure. Certification investment in ISO 14644 validation capabilities extends pharmaceutical cleanroom addressability. For New Entrants and Emerging Players: Enter via FSSAI-mandated food processing corridors in Maharashtra and Gujarat, where localized stainless-steel partnerships unlock first-mover positioning ahead of HACCP certification waves. India's export-oriented meat and dairy infrastructure represents the most penetrable geography. Go-to-market leverage through Mumbai commercial kitchen equipment distributors bypasses entrenched European vendor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with asset-light compliance software developers given IoT sensor data monetization trajectories. Five-to-ten-year viability favors vendors with installed hardware bases capable of converting to recurring hygiene tracking licenses. Acquisition target archetype: regional fabricators with FDA or EU hygiene package certification credentials lacking digital platform capabilities. Signal to watch: EFSA technical opinions on automated versus manual sanitization efficacy, which could recalibrate equipment certification requirements and trigger replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Module Supply | Captive Bavarian engineering partnerships reduce trade friction exposure for North American assemblers. |
| Subscription Compliance Software Launch | IoT telemetry monetization expands lifetime value beyond one-time equipment sales to institutional buyers. |
| Localized Stainless-Steel Fabrication Partnership | Maharashtra and Gujarat production hubs position vendors for FSSAI modernization program capture. |
| ISO 14644 Certification Investment | Swissmedic-aligned validation capabilities open pharmaceutical cleanroom procurement in Basel and Zurich. |
| Single-Source Maintenance Contract Consolidation | German Betriebsrat-negotiated specifications favor integrated corridor providers over point-solution vendors. |
Research Methodology
Document review covered FDA Food Code provisions, EU hygiene package regulations, FSSAI modernization directives, and SEC filings from institutional cleaning service providers, complemented by interviews with food processing plant engineers, pharmaceutical cleanroom managers, hospital biomedical engineering directors, and K-12 facilities procurement officers. Secondary validation drew from customs trade data, stainless-steel price indices, and healthcare construction project databases. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Segment-level projections across product type, application, delivery mode, and end user were generated through penetration modeling against regulatory mandate timelines and infrastructure spending appropriations. CAGRs were derived from replacement cycle compression analysis, IoT adoption curves, and regional food processing investment pipelines. Inputs included HACCP inspection intensity data, ESSER fund utilization rates, and MOHAP hospital construction permits.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price spike scenarios, trade policy friction affecting German sensor module exports, or EFSA technical opinion revisions altering equipment certification thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Antiseptic Bathing Market
Infection Control
Antimicrobial Suture Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Alcohol Wipes Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Disinfection Equipment Market
Infection Control
Sterility Indicators Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Botulism Market
Infection Control
Hand Hygiene Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Salivary Gland Infection Treatment Market
Infection Control
Sterilization Market