
 Hand and Wrist Devices Market | 2026-2036
Hand and Wrist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hand and Wrist Devices Market Analysis
Recurring software subscriptions for motion-tracking analytics is hardening into a standard revenue layer alongside hardware sales. Stryker leverages its hospital system partnerships to bundle sensor-enabled splints with cloud-based recovery dashboards. Zimmer Biomet sustains R&D intensity across traditional orthotics while building digital therapy platforms. Acumed specializes in anatomically contoured fixation plates that occupy the trauma surgery channel.
Hand and wrist devices encompass mechanically supportive and sensor-integrated apparatus designed to immobilize, stabilize, or monitor the distal upper extremity, typically constructed from thermoformable polymers, breathable textiles, or titanium alloys with load ratings calibrated to specific injury grades. These devices serve orthopedic trauma management, chronic condition mitigation, and athletic performance optimization through controlled range-of-motion enforcement or real-time kinematic feedback. The braces and splints category dominates unit volume due to post-operative protocol standardization across hospital systems, while smart wearables represent the fastest-expanding margin pool as biofeedback systems command premium pricing from sports medicine practices. Traditional devices still anchor revenue in emerging markets where reimbursement for connected technologies remains limited.
FDA 510(k) premarket notification requirements shape product development cycles for biofeedback systems entering the US market, while ISO 13485 quality management standards govern contract manufacturing relationships across the supply base. The EU Medical Device Regulation imposes clinical evidence thresholds on Class IIa orthotics that delay market access for smaller innovators. Stakeholders must monitor evolving CMS reimbursement codes for remote therapeutic monitoring to determine whether digital feature investments convert to sustainable pricing power.
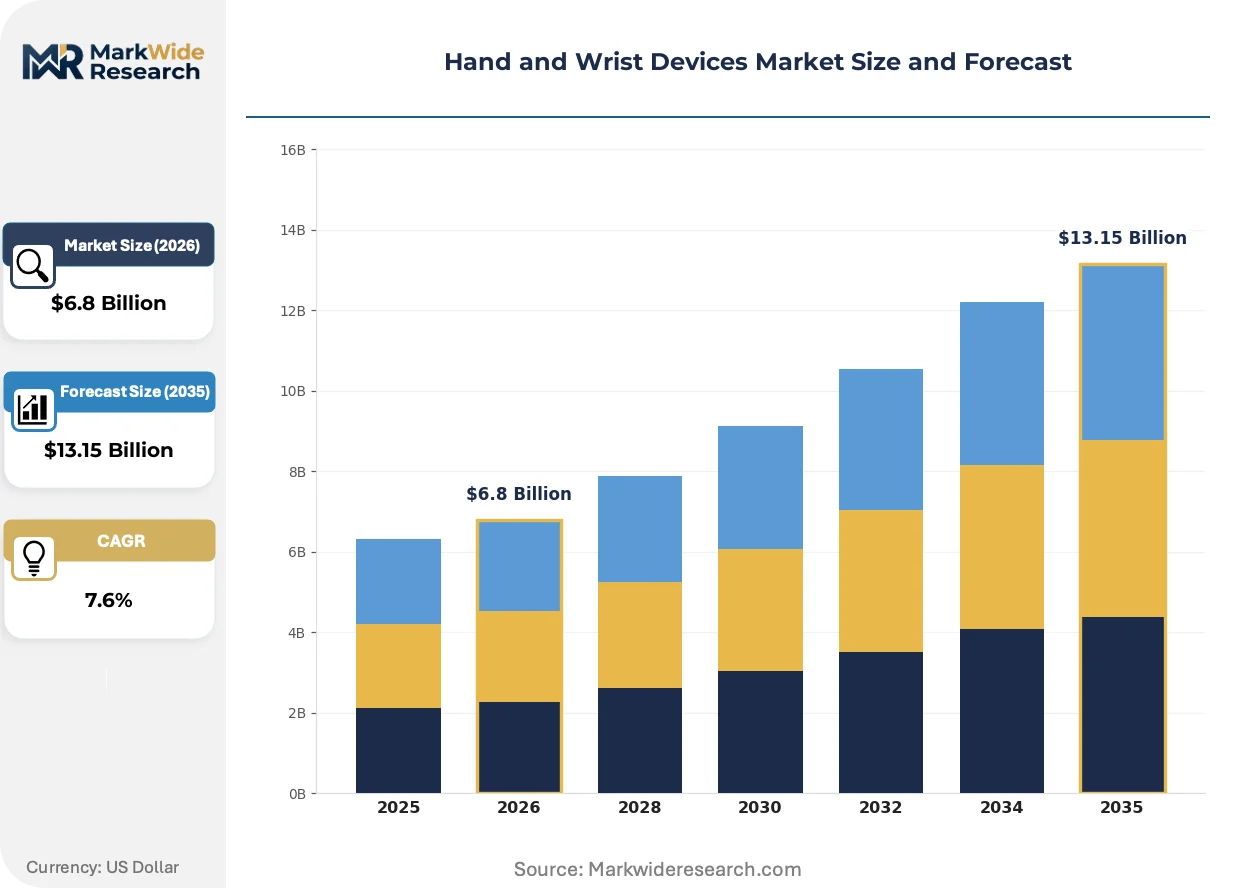
Market Dynamics
Biofeedback-enabled orthotics are compressing traditional device margins while creating subscription revenue architectures that orthopedic clinics now demand from suppliers. Hardware commoditization pressures manufacturers to differentiate through embedded sensors and cloud analytics platforms.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined premarket notification for biofeedback systems accelerates commercialization timelines for sensor-integrated splints targeting post-surgical rehabilitation protocols.
- Aging Demographics in United States:Medicare-eligible population expansion drives replacement volumes for osteoarthritis braces and fracture fixation hardware through established sports medicine infrastructure.
- Thermoformable Polymer Advances:Custom-fit fabrication technologies reduce orthopedic clinic inventory burdens while improving patient compliance through anatomically contoured immobilization.
Market Restraints
- Titanium Alloy Input Volatility:Surgical-grade metal price fluctuations squeeze margin structures for trauma fixation plate manufacturers dependent on aerospace-grade material specifications.
- EU MDR Clinical Evidence Thresholds:Class IIa orthotics face extended approval timelines that disadvantage smaller innovators against established quality management system holders.
- Traditional Brace Substitution:Low-cost textile splints from contract manufacturers displace premium positioning in price-sensitive emerging market procurement.
Strategic Opportunities
- Remote Therapeutic Monitoring Reimbursement:CMS code expansion creates sustainable pricing power for digital therapy platforms bundled with sensor-enabled hardware.
- India PLI Scheme Alignment:Medical device manufacturing incentives attract contract production investment for export-grade orthopedic apparatus serving Asian trauma surgery channels.
- Athletic Performance Optimization:Kinematic feedback convergence with professional sports training facilities opens premium pricing tiers outside traditional medical reimbursement.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering capability gaps constrain traditional orthotics manufacturers pursuing biofeedback integration without external development partnerships.
- ISO 13485 Certification Burden:Quality management system maintenance costs disproportionately impact mid-tier suppliers attempting multi-market regulatory compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand and Wrist Devices Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Splints, Supports, Orthotics Application: Rehabilitation, Injury Prevention, Pain Management, Performance Enhancement End User: Athletes, Occupational Therapists, Healthcare Providers, Home Users Technology: Smart Wearables, Traditional Devices, Biofeedback Systems, Motion Sensors |
| Companies Covered | DePuy Synthes, Zimmer Biomet, Stryker, Smith and Nephew, Acumed, Wright Medical, In2Bones, Double Medical, Evolutis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand and Wrist Devices Market Emerging Trajectories
Sensor miniaturization and wireless connectivity standards are dissolving the boundary between passive support devices and active therapeutic platforms. Manufacturers now compete on data architecture rather than mechanical design alone.
Stretchable electronics incorporating graphene-enhanced conductive polymers is modularizing the architecture of smart wrist braces. Professional sports medicine practices in Germany and Australia are piloting these systems for real-time load monitoring during athlete rehabilitation. Component standardization is modularizing supply chains, allowing orthopedic clinics to upgrade sensor capabilities without replacing entire splint structures.
EU Medical Device Regulation post-market surveillance requirements are forcing systematic clinical evidence collection for Class IIa orthotics. Manufacturers must now maintain active implant registries and periodic safety update reports that extend regulatory affairs headcount. Trauma fixation plate suppliers with existing notified body relationships are absorbing compliance costs faster than emerging competitors.
Hospital system procurement consolidation is compressing vendor rosters and demanding bundled hardware-software-service contracts. Integrated delivery networks in Texas and Florida now specify cloud-based recovery dashboards as mandatory bid components. This specification shift favors suppliers with established health information technology partnerships over pure-play device manufacturers.
Hand and Wrist Devices Market Segmentation
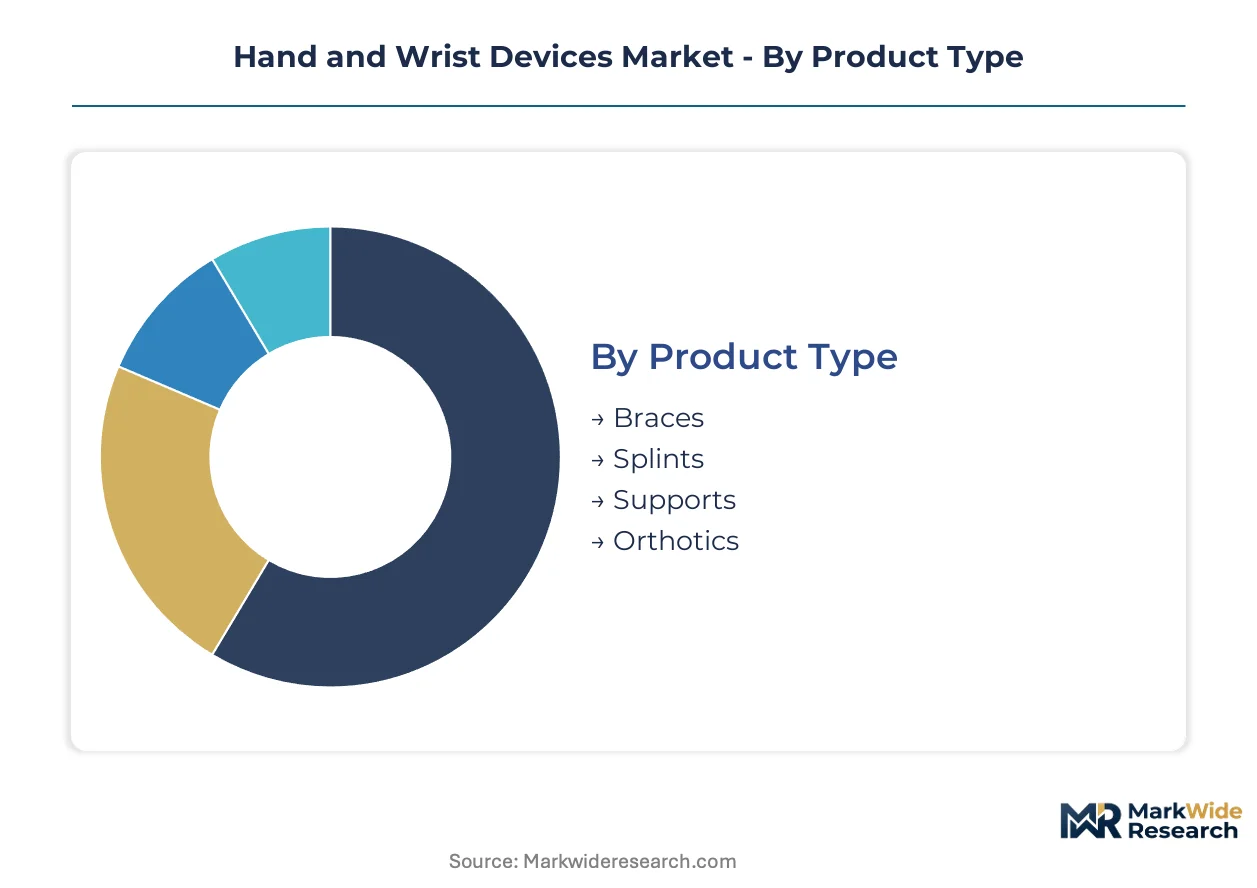
Segmentation in the hand and wrist devices market reveals divergent buyer priorities across clinical, athletic, and consumer channels. Manufacturers must align product specifications with distinct reimbursement pathways, performance requirements, and price sensitivity thresholds.
Product Type:
Buyers in this category differentiate by immobilization rigidity versus mobility preservation needs.
- Braces:Constructed from rigid thermoformable polymers with adjustable hinge mechanisms calibrated to specific range-of-motion restrictions. Hospital systems in the United States standardize on post-operative braces for fracture management, with procurement teams demanding inventory consolidation across multiple anatomical configurations.
- Splints:Fabricated from breathable textiles and aluminum stays offering semi-rigid support for soft tissue injuries. Occupational therapy clinics in Germany and Australia are expanding adoption of modular splint systems that permit component upgrades without full device replacement.
- Supports:Elastic compression garments with integrated gel padding for chronic condition management. Home users in price-sensitive markets drive volume through direct-to-consumer channels.
- Orthotics:Custom-molded apparatus fabricated from medical-grade silicone or carbon fiber composites. Specialized orthopedic clinics command premium pricing for anatomically contoured solutions.
Volume sits with Braces; growth tilts toward Orthotics.
Application:
End-use concentration varies by reimbursement eligibility and out-of-pocket willingness.
- Rehabilitation:Protocol-driven deployment following surgical intervention or trauma, with duration dictated by clinical guidelines. Medicare reimbursement codes in the United States determine supplier selection for post-operative protocols.
- Injury Prevention:Prophylactic use in occupational settings and contact sports. Manufacturing facilities in the Midwest United States specify wrist supports for repetitive strain mitigation.
- Pain Management:Chronic osteoarthritis and carpal tunnel syndrome mitigation through off-the-shelf or prescription devices. Retail pharmacy chains capture volume through simplified fitting processes.
- Performance Enhancement:Kinematic optimization for professional athletes and esports competitors. Sports medicine practices in Texas and Florida pilot subscription-based analytics platforms.
Rehabilitation commands installed base; Performance Enhancement climbs the fastest.
End User:
Procurement authority and technical sophistication separate institutional buyers from individual purchasers.
- Athletes:Professional and amateur competitors prioritizing motion capture data and rapid return-to-play protocols. NBA and MLB training facilities specify sensor-integrated braces with cloud dashboard compatibility.
- Occupational Therapists:Licensed practitioners prescribing custom-fabricated orthotics through clinical assessment workflows. Hand therapy certification requirements in the United States constrain supplier qualification.
- Healthcare Providers:Hospital systems and orthopedic clinics with consolidated vendor rosters and bundled contracting demands. Integrated delivery networks in Florida mandate health information technology integration.
- Home Users:Self-directed purchasers relying on retail availability and online configurators. E-commerce penetration concentrates volume in urban United States markets.
Healthcare Providers anchor revenue concentration; Athletes gain share fastest.
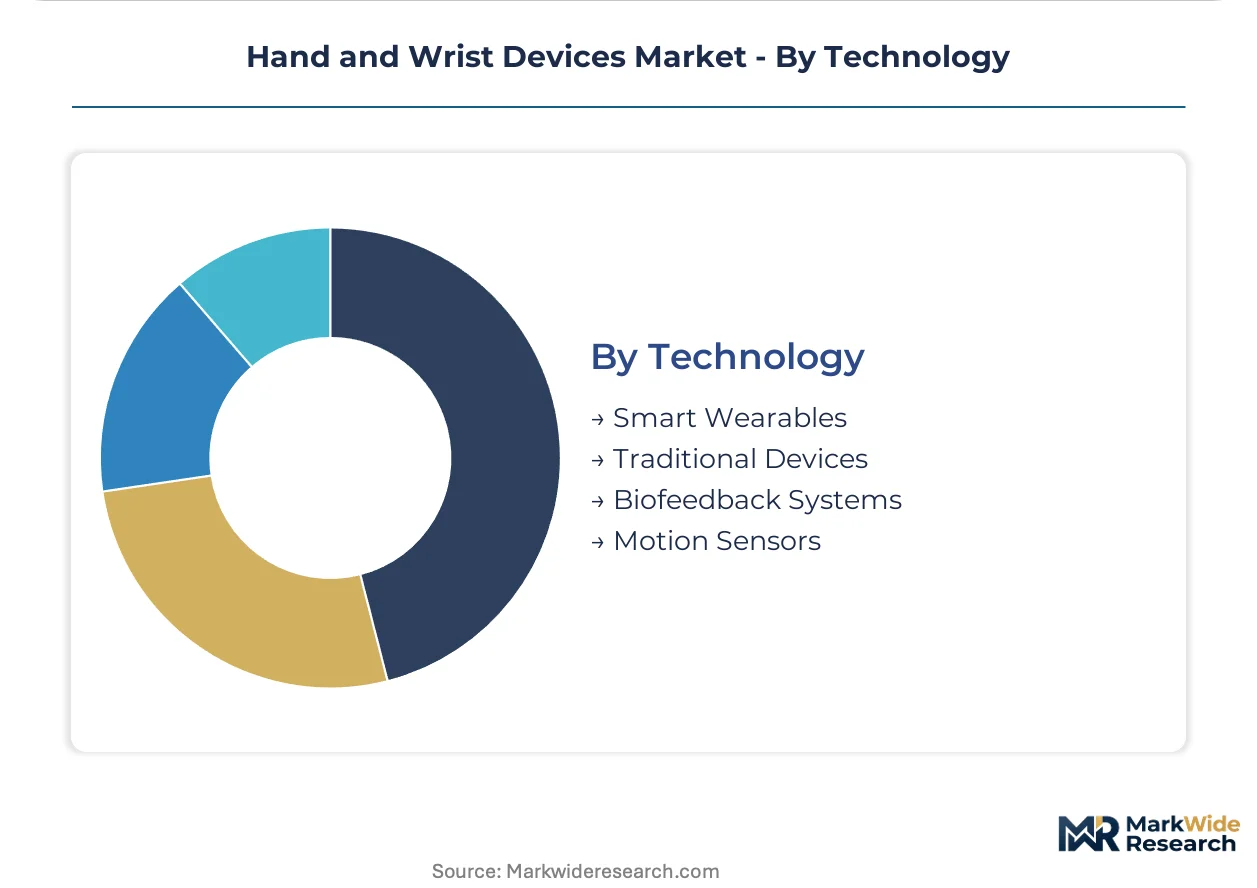
Technology:
Margin architecture separates connected platforms from commodity hardware.
- Smart Wearables:Stretchable electronics incorporating graphene-enhanced conductive polymers for real-time kinematic monitoring. FDA 510(k) clearance pathways accelerate commercialization for biofeedback-enabled systems.
- Traditional Devices:Passive mechanical support without embedded sensors or data transmission capabilities. Emerging market procurement favors low-cost textile construction from contract manufacturers.
- Biofeedback Systems:Closed-loop therapeutic platforms adjusting immobilization parameters based on physiological response. ISO 13485 certification requirements disadvantage smaller innovators.
- Motion Sensors:Accelerometer and gyroscope arrays capturing range-of-motion metrics for remote therapeutic monitoring. CMS reimbursement code expansion determines sustainable pricing power.
Traditional Devices hold volume dominance; Smart Wearables show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of hand and wrist devices concentrates in industrial clusters with precision polymer and metalworking capabilities, while consumption patterns diverge between aging populations seeking osteoarthritis management and athletic programs investing in motion-tracking rehabilitation systems.
United States
Medicare-eligible population expansion drives replacement volumes for fracture fixation hardware and post-operative braces through established sports medicine infrastructure in Texas and Florida. FDA 510(k) clearance pathways compress commercialization timelines for biofeedback-enabled orthotics entering rehabilitation protocols. Integrated delivery networks in the Southeast now mandate cloud-based recovery dashboards as mandatory procurement specifications.
Germany
Occupational therapy clinics in Bavaria and North Rhine-Westphalia are expanding adoption of modular splint systems that permit component upgrades without full device replacement. EU Medical Device Regulation post-market surveillance requirements impose systematic clinical evidence collection obligations on Class IIa orthotic manufacturers. The Stuttgart industrial corridor hosts precision polymer fabrication facilities serving export-grade orthopedic apparatus.
China
Domestic trauma surgery channels absorb volume from thermoformable polymer braces as hospital system procurement standardizes post-operative protocols. NMPA medical device registration requirements shape product development cycles for manufacturers targeting Class II orthopedic implants. The Yangtze River Delta manufacturing belt supplies contract production of titanium alloy fixation plates for Asian export markets.
India
Price-sensitive emerging market procurement favors low-cost textile splints from domestic contract manufacturers serving home user channels. PLI scheme medical device manufacturing incentives attract export-grade orthopedic production investment for trauma surgery apparatus. Gujarat and Maharashtra industrial zones are developing polymer fabrication capabilities for anatomically contoured immobilization devices.
Australia
Sports medicine practices in New South Wales and Victoria pilot graphene-enhanced conductive polymer wrist braces for real-time load monitoring during athlete rehabilitation. TGA medical device conformity assessment requirements govern market access for sensor-integrated therapeutic platforms. Melbourne's medical technology cluster supports firmware engineering partnerships for traditional orthotics manufacturers pursuing biofeedback integration.
Hand and Wrist Devices Market Vendor Landscape
Top-tier vendors anchor hospital system procurement through bundled hardware-software-service contracts, while mid-tier specialists compete on anatomical customization and trauma surgery channel relationships. The vendor base stratifies across three tiers: multinational conglomerates with health information technology partnerships, regional orthotic specialists with notified body relationships, and contract manufacturers serving emerging market price points. Dominant competitive moves include sensor integration partnerships with cloud analytics platforms and ISO 13485 certification investments to accelerate multi-market regulatory compliance.
Within the multinational tier, Stryker and Zimmer Biomet exemplify the shift toward subscription-based revenue architectures, while Acumed occupies a position among trauma fixation specialists. DePuy Synthes and Smith and Nephew represent diversified orthopedic portfolios spanning traditional mechanical support and emerging biofeedback systems. These companies sit within a competitive structure where hospital system consolidation compresses vendor rosters and demands integrated delivery network compatibility.
| Leading Market Players |
|---|
| DePuy Synthes |
| Zimmer Biomet |
| Stryker |
| Smith and Nephew |
| Acumed |
| Wright Medical |
| In2Bones |
| Double Medical |
| Evolutis |
| Others |
Supply Flow & Price Mechanics
Backward integration into sensor module fabrication anchors supply position for manufacturers seeking pricing power in biofeedback-enabled orthotics. Orthopedic clinics in Texas and Florida now mandate bundled hardware-software contracts that compress margins for pure-play device suppliers lacking captive cloud analytics capabilities.
Pricing Analysis
Margin tightening in traditional brace tiers reflects titanium alloy input volatility and low-cost textile substitution from Indian contract manufacturers. Pricing stratifies across premium sensor-integrated systems, standard thermoformable polymer braces, and economy textile splints. Cost-down pressure accelerates in the standard tier as hospital procurement consolidation demands volume discounts. Home users in price-sensitive markets exhibit highest price sensitivity; sports medicine practices show lowest sensitivity for biofeedback subscriptions.
Supply Chain Analysis
Dual-sourcing requirements from FDA-registered manufacturers mandate qualified suppliers in both the United States and China for titanium alloy fixation plates. Thermoformable polymer feedstock draws from Germany and the Yangtze River Delta, while graphene-enhanced conductive polymers source from Australian materials specialists. Single-source vulnerability concentrates in aerospace-grade titanium specifications. Distribution runs through orthopedic clinic networks, hospital GPO contracts, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
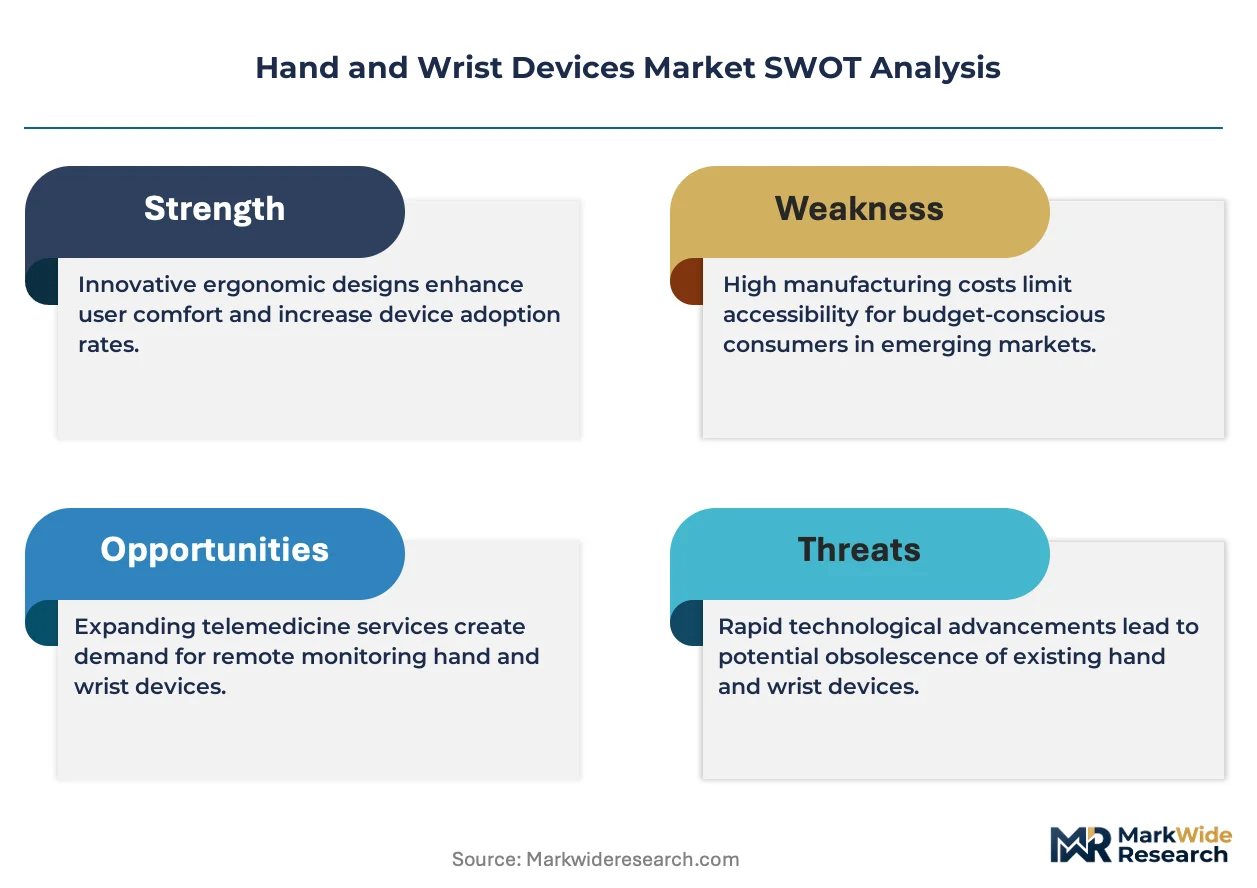
The hand and wrist devices market functions as a vertical-integration race where sensor firmware capabilities and cloud platform ownership determine sustainable margin capture.
For Market Incumbents: Lock in hospital system partnerships through ISO 13485 certification investments that accelerate multi-market regulatory compliance against EU MDR clinical evidence thresholds. Consolidate trauma surgery channel relationships with anatomically contoured fixation plate portfolios. Defend against embedded systems talent scarcity by acquiring firmware engineering capabilities in Melbourne and Stuttgart clusters. For New Entrants and Emerging Players: Enter via modular splint component upgrades in German and Australian occupational therapy clinics where reimbursement pathways favor component refresh cycles over full device replacement. Target price-sensitive home user channels in Indian urban markets through direct-to-consumer configurators. Pursue PLI scheme alignment for export-grade contract manufacturing in Gujarat industrial zones. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational conglomerates seeking health information technology integration capabilities. Long-term viability hinges on recurring software subscription revenue architectures rather than transactional hardware margins. Watch CMS remote therapeutic monitoring reimbursement code expansion as the inflection signal for digital therapy platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined premarket notification accelerates biofeedback system commercialization timelines. |
| CE Marking Pathway | EU MDR compliance investments open Class IIa orthotic access across German rehabilitation channels. |
| Hospital System Partnership | Integrated delivery networks in Florida mandate cloud dashboard compatibility in procurement bids. |
| Software Companion Development | Motion-tracking analytics platforms harden recurring revenue alongside hardware sales. |
| Reimbursement Strategy | CMS code alignment determines sustainable pricing power for remote therapeutic monitoring. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, CMS reimbursement code expansions, and ISO 13485 certification patterns anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA premarket notification databases, CMS Medicare fee schedules, hospital procurement registries, and EU MDR notified body filings. Bottom-up unit demand modeling triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Input-output matrices mapped thermoformable polymer consumption to brace fabrication capacity, titanium alloy supply to trauma plate production, and sensor module availability to smart wearable assembly across the projection horizon. Segmentation modeling incorporated product type rigidity specifications, application reimbursement eligibility, end user procurement authority, and technology connectivity tiers. CAGRs derived from regression analysis of historical replacement volumes correlated with Medicare-eligible population expansion and sports medicine infrastructure investment patterns.
Revisions become necessary when FDA regulatory pathway delays, EU MDR clinical evidence threshold escalations, or CMS reimbursement code contractions materialize. Deviation in titanium alloy price volatility or embedded systems engineering labor availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
Brazil Aesthetic Devices Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Global IVF Devices Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Home-Use Water Flosser Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
3D Printed Hip and Knee Implants Market